
 Vital Sign Simulators Market | 2026-2036
Vital Sign Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
Vital Sign Simulators Market Insights
Software-defined feature licensing is consolidating recurring revenue streams alongside hardware placements. Laerdal Medical leverages its installed base across Nordic training networks to sustain premium service attach rates. CAE Healthcare anchors its position through defense and civilian aviation-medical crossover contracts. Fluke Biomedical competes on calibration traceability and metrology-grade accuracy for regulatory compliance workflows.
Vital sign simulators are electromechanical or software-driven devices that replicate physiological parameters including ECG waveforms, blood pressure, oxygen saturation, and respiratory rate within programmable tolerance bands; they serve primarily to validate patient monitoring equipment and train clinical personnel without live-subject risk. Adult simulators dominate procurement budgets due to their versatility across general ward and ICU training scenarios, while wireless simulators represent the fastest-expanding technology segment as tether-free designs enable mass-casualty and in-situ emergency response drills. Software-based platforms capture disproportionate margin pools through subscription renewals and scenario library expansions that extend product lifecycles beyond physical refresh cycles.
FDA 510(k) clearance requirements and ISO 13485 quality management standards shape product development timelines and international market access for manufacturers targeting North American and European buyers. The EU Medical Device Regulation mandates clinical evidence and post-market surveillance protocols that elevate compliance costs but also screen out lower-tier competitors. Stakeholders must monitor how FDA guidance on artificial intelligence-enabled diagnostic devices redefines validation requirements for simulators that train or test algorithm-dependent monitoring systems.
Market Dynamics
The FDA's evolving guidance on medical device validation is compressing product development timelines while simultaneously elevating fidelity requirements for testing protocols used in regulatory submissions.
Growth Catalysts
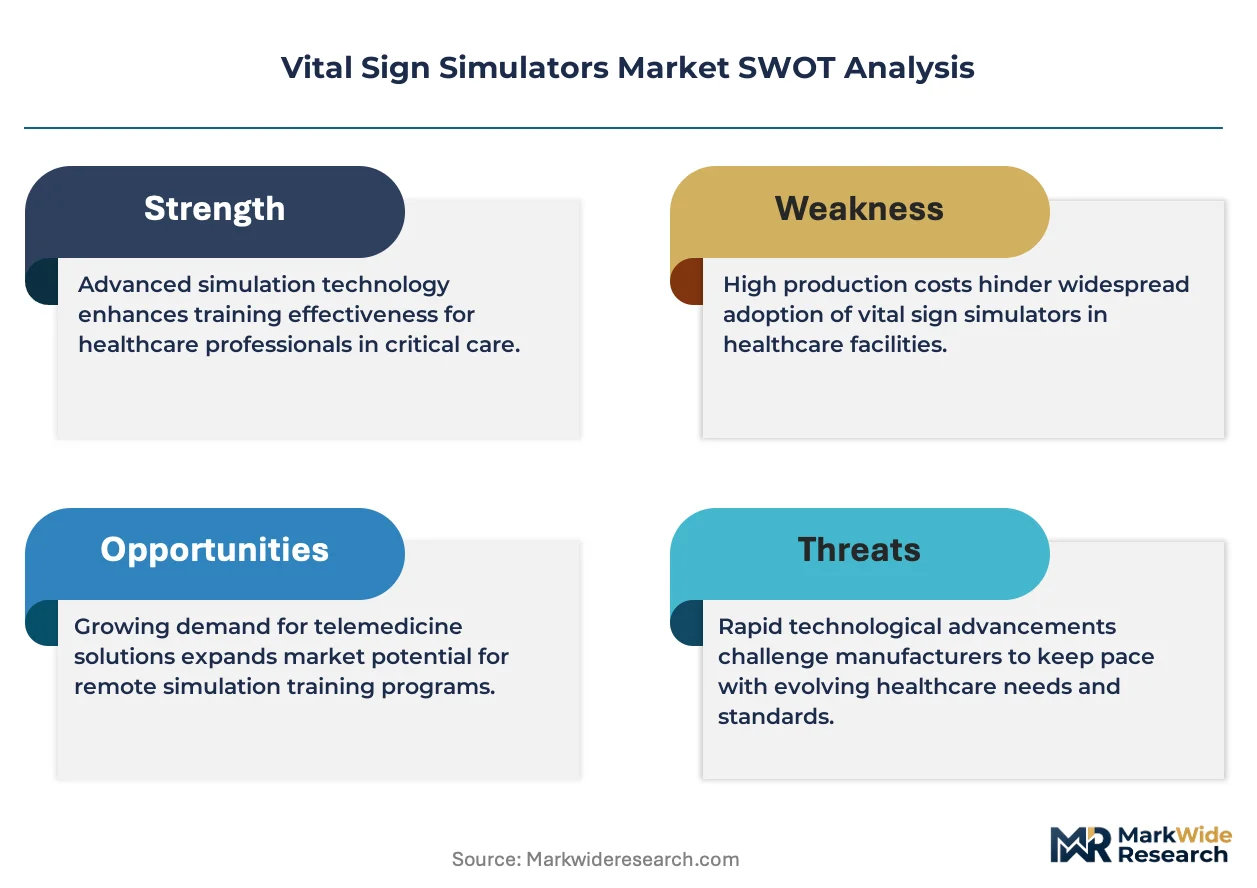
- EU Medical Device Regulation:MDR-mandated clinical evidence and post-market surveillance protocols screen out lower-tier competitors, consolidating procurement toward ISO 13485-certified manufacturers.
- Wireless telemetry:Tether-free simulator designs enable mass-casualty drills and in-situ emergency response training across military and civilian healthcare networks.
- German university hospital investment:Technical institutes in Baden-Württemberg and Bavaria anchor European demand for advanced patient monitoring simulation infrastructure.
Market Restraints
- Metrology-grade component costs:Calibration traceability requirements for regulatory compliance workflows inflate bill-of-materials for ECG waveform and SpO2 replication modules.
- ISO 13485 certification timelines:Quality management system audits and technical documentation reviews extend market access delays for new entrants targeting North American buyers.
- Software validation overhead:FDA 510(k) clearance requirements for algorithm-dependent monitoring systems create fixed-cost barriers for scenario library developers.
Strategic Opportunities
- Subscription-based scenario libraries:Software platforms capture recurring revenue through cloud-hosted physiology modeling that extends product lifecycles beyond hardware refresh cycles.
- Defense-civilian crossover contracts:Aviation-medical training convergence creates dual-use procurement channels for tactical casualty care simulation.
- India's CDSCO harmonization:Medical device rules alignment with IMDRF standards opens import pathways for CE-marked simulators into technical nursing institutes.
Industry Challenges
- Biomedical engineering talent scarcity:Electromechanical systems integration and physiological modeling expertise concentrates in Nordic and German training networks.
- Legacy patient monitor interoperability:Proprietary communication protocols from installed base manufacturers complicate seamless simulator integration during validation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vital Sign Simulators Market |
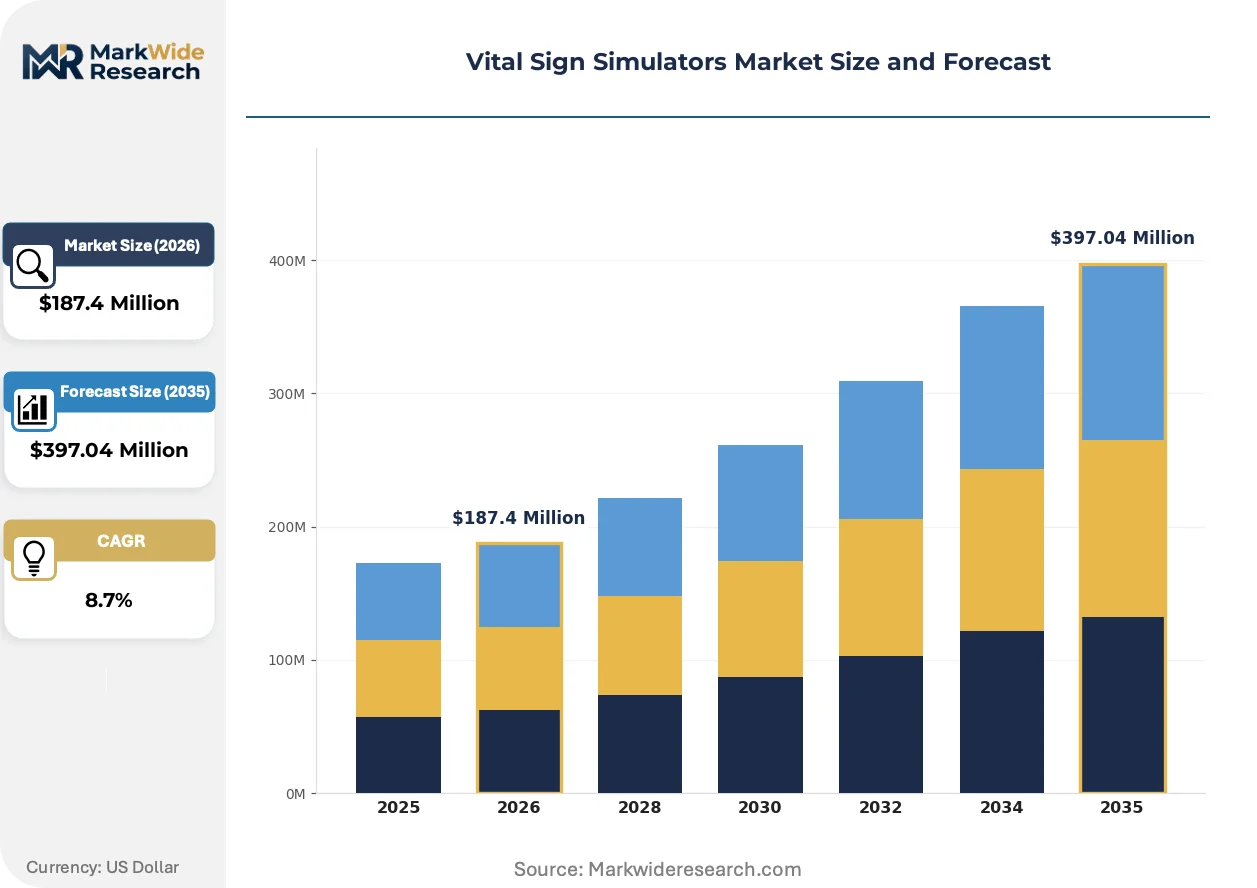
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Simulator, Pediatric Simulator, Neonatal Simulator, Wireless Simulator Technology: Electronic, Software-based, Hybrid, Mechanical End User: Hospitals, Training Centers, Medical Schools, Clinics Application: Patient Monitoring, Training, Research, Emergency Response |
| Companies Covered | Laerdal Medical, Gaumard Scientific, CAE Healthcare, Fluke Biomedical, Rigel Medical, 3B Scientific, Pronk Technologies, Nasco Healthcare, Datrend Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vital Sign Simulators Market Trends and Innovations
Artificial intelligence-enabled diagnostic validation is redefining simulator architecture, while software-defined licensing models separate hardware from recurring feature access.
Digital twin physiology engines are absorbing real-time biomarker variability into programmable tolerance bands. University hospitals in the United States are adopting these platforms for algorithm stress-testing at accelerated paces. This absorption is compressing validation cycles for AI-dependent monitoring systems seeking FDA clearance.
The EU AI Act's risk classification framework for medical device software is reshaping documentation burdens for simulator manufacturers. High-risk system providers must demonstrate conformity with post-market monitoring and bias mitigation protocols. German notified bodies are experiencing audit queue lengthening as CE-marking applications surge ahead of enforcement deadlines.
Service unbundling from hardware placements is restructuring vendor-buyer relationships across Nordic training networks. Laerdal Medical and CAE Healthcare are disaggregating scenario content from device sales, replacing capital-only transactions with annual licensing arrangements. This shift is most visible in Denmark and Sweden, where regional health authorities consolidate procurement through framework agreements.
Vital Sign Simulators Market Segmentation
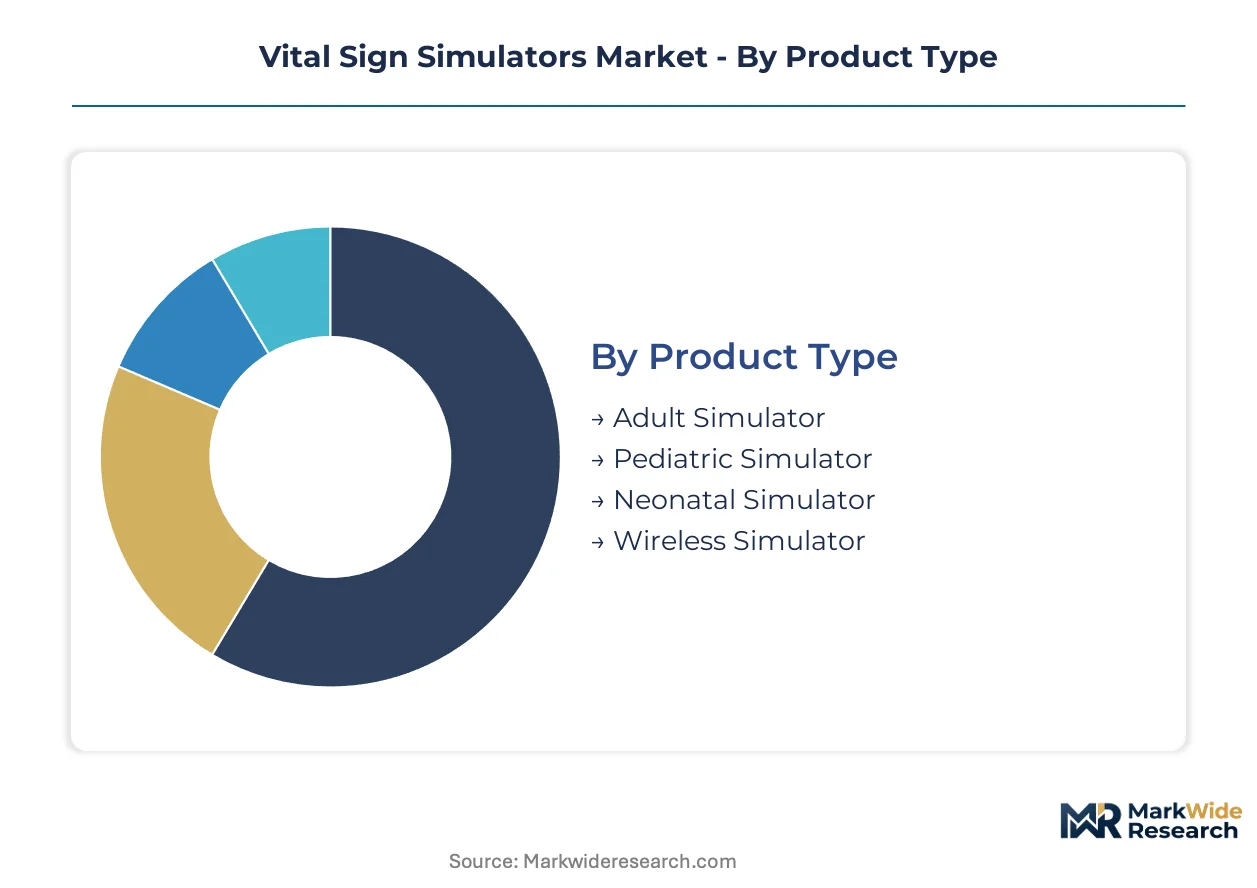
Vital sign simulators fragment across four intersecting dimensions that determine procurement workflows, certification pathways, and lifecycle economics. Product type and technology choices cascade into divergent regulatory burdens, while end-user and application segments dictate scenario fidelity requirements and software subscription attach rates.
Product Type:
FDA 510(k) clearance and EU MDR technical documentation requirements vary sharply by patient age band and connectivity architecture, with wireless platforms triggering additional electromagnetic compatibility validation.
- Adult Simulator:Full-body electromechanical systems replicate ECG, SpO2, NIBP, and respiratory waveforms across programmable vital sign ranges. Demand concentrates in US academic medical centers expanding simulation-based curricula for internal medicine and critical care training, driven by ACGME competency requirements for procedural skills assessment.
- Wireless Simulator:Battery-powered, tether-free designs transmit physiological data via Bluetooth or proprietary protocols to patient monitors during mobile scenarios. German university hospitals in Baden-Württemberg anchor European procurement for mass-casualty and in-situ emergency response drills, where untethered movement replicates field conditions.
- Pediatric Simulator:Anatomically scaled systems with age-adjusted vital sign ranges and medication dosing protocols.
- Neonatal Simulator:Low-birth-weight form factors with micro-preemie physiological parameters for NICU training scenarios.
Leading the category by volume: Adult Simulator. Growing fastest: Wireless Simulator.
Technology:
Cost tier separation runs from capital-intensive electromechanical platforms to lightweight software licenses, with hybrid architectures commanding premium positioning through hardware-software integration.
- Software-based:Cloud-hosted physiology engines deliver programmable vital sign modeling through API connections to existing monitors, eliminating physical hardware procurement. Subscription renewal revenue concentrates in Nordic training networks consolidating regional procurement through framework agreements, with annual licensing replacing capital transactions.
- Electronic:Solid-state waveform generators with calibrated signal outputs for metrology-grade device validation. Demand clusters in US medical device manufacturers facing FDA premarket submission requirements for patient monitoring algorithm verification.
- Hybrid:Combines physical patient interfaces with software-defined physiology modeling for flexible scenario deployment.
- Mechanical:Pneumatic and fluidic systems for blood pressure and respiratory simulation in resource-constrained settings.
Highest margin capture: Software-based. Steepest expansion trajectory: Hybrid.
End User:
Customer type determines scenario library complexity, with medical schools prioritizing curriculum integration and hospitals emphasizing interoperability with installed monitor fleets.
- Medical Schools:Comprehensive simulation centers requiring integrated debriefing systems and competency tracking aligned with accreditation standards. US allopathic and osteopathic programs drive procurement for standardized patient encounters and Objective Structured Clinical Examinations.
- Hospitals:Biomedical engineering departments seeking ISO 17025-traceable calibration sources for preventive maintenance workflows. German university hospitals anchor European demand for high-fidelity ICU training environments.
- Training Centers:Independent simulation facilities serving multiple institutional clients with portable scenario libraries.
- Clinics:Limited deployments focused on basic vital sign verification for point-of-care device validation.
Deepest scenario libraries: Medical Schools. Fastest procurement cycle acceleration: Hospitals.
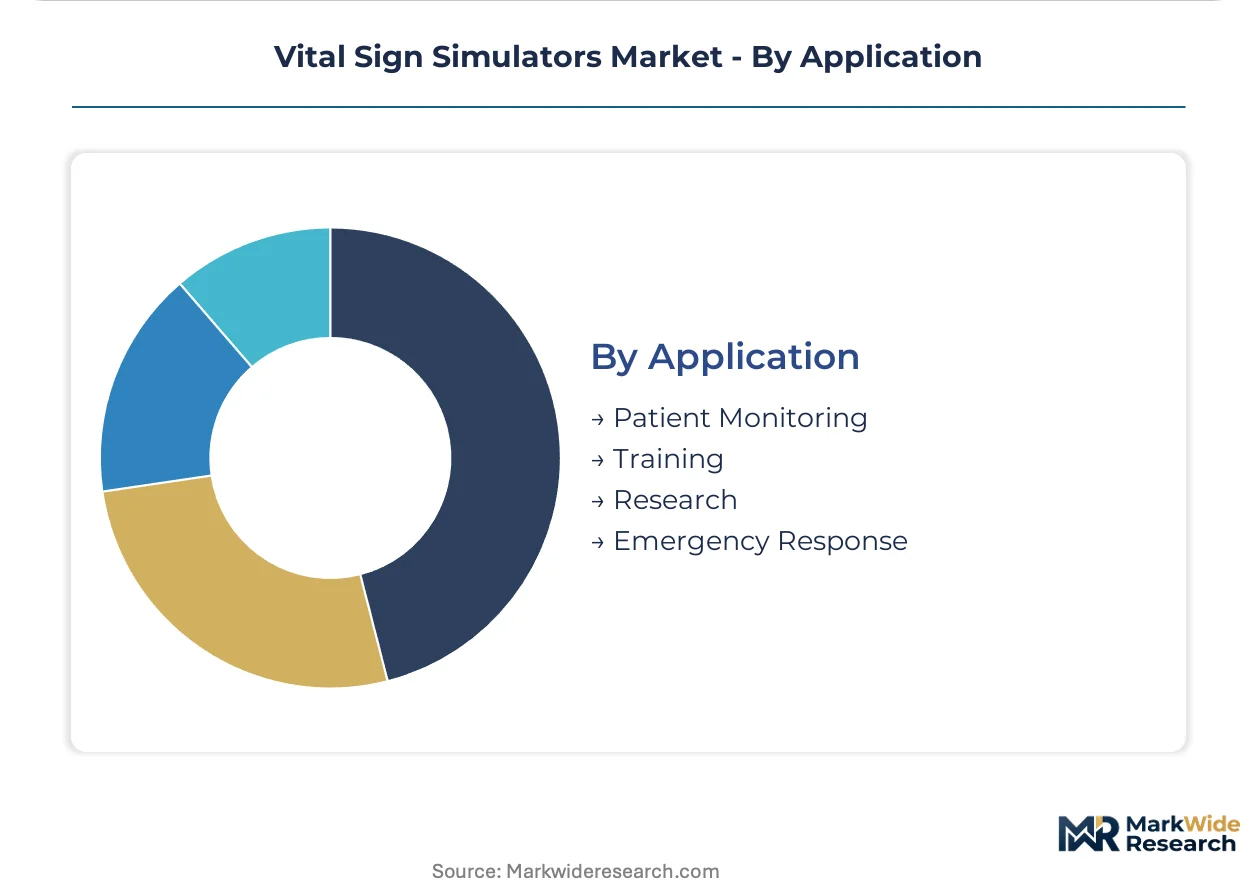
Application:
Application scope dictates fidelity thresholds, with research and emergency response segments pushing beyond standard training specifications into algorithm stress-testing and field-deployment validation.
- Training:Scenario-based education for nursing, physician, and paramedic competency development across ACLS, PALS, and trauma protocols. US military medical commands and civilian aviation-medical crossover programs sustain dual-use procurement channels.
- Patient Monitoring:Device validation for regulatory submission and post-market surveillance, requiring metrology-grade waveform accuracy. FDA 510(k) clearance timelines compress development cycles for manufacturers seeking predicate device equivalence.
- Research:Physiological model validation for AI-enabled diagnostic algorithm development and digital twin stress-testing.
- Emergency Response:Tactical casualty care simulation for mass-casualty and disaster preparedness drills.
Widest deployment base: Training. Tightest regulatory coupling: Patient Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Nordic and German precision engineering clusters contrasts with consumption gravity in US academic medical centers and German university hospital networks. Component sourcing for electromechanical systems flows through Baden-Württemberg and Bavaria, while end-user procurement concentrates where ACGME competency requirements and ISO 17025 calibration mandates drive replacement cycles.
United States
ACGME-mandated simulation-based curricula power procurement across allopathic and osteopathic medical schools, with Objective Structured Clinical Examination requirements expanding standardized patient encounter infrastructure. FDA 510(k) clearance timelines for patient monitoring algorithm validation compress development cycles for manufacturers seeking predicate device equivalence. Greater Boston and Pacific Northwest biomedical engineering clusters anchor metrology-grade calibration source production for regulatory compliance workflows.
Germany
University hospitals in Baden-Württemberg and Bavaria anchor European demand for high-fidelity ICU training environments and mass-casualty drill infrastructure. EU MDR-mandated clinical evidence and post-market surveillance protocols screen out lower-tier competitors, consolidating procurement toward ISO 13485-certified manufacturers. Stuttgart and Munich technical institutes invest heavily in wireless telemetry platforms for in-situ emergency response simulation.
United Kingdom
NHS simulation center consolidation drives framework agreements for regional health authority procurement of debriefing-integrated competency tracking systems. MHRA alignment with EU MDR technical documentation requirements elevates compliance costs but opens export pathways for CE-marked manufacturers. London and Southeast England academic medical centers prioritize software-defined physiology engines for AI-enabled diagnostic algorithm stress-testing.
India
Technical nursing institutes in Maharashtra and Karnataka expand simulation-based training capacity under National Skill Development Corporation healthcare sector targets. CDSCO harmonization with IMDRF standards opens import pathways for CE-marked simulators, reducing regulatory friction for Nordic and German manufacturers. Delhi-NCR biomedical device distributors build calibration service capabilities to support post-market surveillance requirements.
Sweden
Regional health authority framework agreements consolidate procurement through annual licensing arrangements replacing capital-only transactions. Swedish Institute for Standards (SIS) participation in ISO/IEC JTC 1/SC 42 artificial intelligence standardization shapes scenario library documentation requirements for algorithm-dependent monitoring systems. Stockholm and Gothenburg training networks sustain premium service attach rates across installed simulation infrastructure.
Vital Sign Simulators Market Competitive Landscape
Capital-heavy electromechanical producers compete with asset-light software platform designers for margin pools across the value chain. The vendor base stratifies into three tiers: integrated full-body simulator manufacturers, calibration-specialized metrology providers, and cloud-hosted physiology engine licensors. Consolidation pressure concentrates among ISO 13485-certified manufacturers as EU MDR and FDA 510(k) compliance costs escalate. Dominant competitive moves include service unbundling from hardware placements and defense-civilian crossover contract anchoring.
Within the integrated simulator tier, Laerdal Medical and CAE Healthcare occupy positions sustained by installed base leverage across Nordic training networks and aviation-medical procurement channels. Fluke Biomedical anchors the metrology-grade calibration segment, with traceability requirements for regulatory compliance workflows defining its competitive perimeter. These three exemplify divergent archetypes: premium service attach rate maximization, dual-use contract diversification, and precision measurement standardization.
| Leading Market Players |
|---|
| Laerdal Medical |
| Gaumard Scientific |
| CAE Healthcare |
| Fluke Biomedical |
| Rigel Medical |
| 3B Scientific |
| Pronk Technologies |
| Nasco Healthcare |
| Datrend Systems |
| Others |
Pricing and Supply Chain Analysis
Captive integration of electromechanical assembly and software-defined physiology modeling anchors premium positioning for ISO 13485-certified manufacturers while compressing margin capture for component-dependent assemblers. Nordic and German producers leverage backward integration into calibration-grade waveform generators to defend pricing power against Asian module suppliers.
Pricing Analysis
Margin tightening in standard-tier hardware reflects metrology-grade component inflation and extended FDA 510(k) validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates subscription-anchored software platforms from capital-intensive electromechanical systems. Cost-down pressure on economy-tier mechanical simulators accelerates because Indian technical institutes prioritize procurement volume over fidelity specifications. Medical schools exhibit lowest price sensitivity due to ACGME-mandated curriculum investments, while independent training centers face acute budget constraints.
Supply Chain Analysis
Precision sensor supply rests on German and Swiss electromechanical component specialists, with solid-state waveform generators drawing from Nordic semiconductor fabrication networks. ECG replication modules, SpO2 calibration sources, and pneumatic pressure transducers constitute critical input dependencies. Single-source vulnerability concentrates in Bluetooth telemetry chipsets for wireless simulator platforms. Distribution runs through authorized medical device distributors with ISO 13485-certified service capabilities, bypassing generalist procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance cost escalation and FDA 510(k) timeline compression are forcing sub-scale assemblers toward exit or acquisition, consolidating procurement influence among vertically integrated full-system producers.
For Market Incumbents: Extend scenario library subscription attach rates through framework agreements with regional health authorities in Sweden and Denmark. Deepen backward integration into electromechanical component production to offset metrology-grade sensor cost inflation. Anchor defense-civilian crossover contracts against emerging software-only entrants lacking hardware validation capabilities.
For New Entrants and Emerging Players: Technical nursing institutes in Maharashtra and Karnataka represent underserved buyer archetypes seeking CE-marked simulators under CDSCO harmonization pathways. Target cloud-hosted physiology engines for Indian market entry, bypassing capital-intensive hardware production. Pursue distributor partnerships with Delhi-NCR biomedical device service networks to establish post-market surveillance capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier hardware assemblers facing ISO 13485 certification backlog and MDR technical documentation burden. Long-term viability favors software-defined platform developers with recurring revenue infrastructure and algorithm-dependent monitoring system validation expertise. Monitor FDA guidance publication on AI-enabled diagnostic devices as inflection signal for simulator architecture investment priority.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation unlocks German university hospital procurement consolidation. |
| Software Companion Development | Cloud-hosted physiology engines extend product lifecycles beyond hardware refresh cycles. |
| Hospital System Partnership | Framework agreements with Baden-Württemberg technical institutes anchor recurring revenue. |
| FDA Submission | 510(k) clearance for algorithm-dependent monitoring systems compresses competitor development timelines. |
| Reimbursement Strategy | ACGME competency alignment positions simulators for US academic medical center capital allocation. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR CE-marking application queues, and German university hospital procurement awards anchored the trend analysis, supplemented by interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and simulation center operations leads. Secondary validation drew from FDA premarket notification databases, EUDAMED device registrations, CMS hospital cost report filings, and ISO 13485 certification body audit disclosures. Bottom-up segment sizing triangulated against top-down market envelope constraints.
Segment-weighting across product type, technology architecture, end-user category, and application scope drove volume and value allocation throughout the forecast period. CAGRs derived from fitted growth curves applied to replacement cycle analysis and expansion investment tracking. Algorithm-dependent monitoring system validation demand and wireless telemetry adoption curves served as industry-specific forecast inputs.
Revisions become necessary when FDA artificial intelligence guidance materializes, EU AI Act enforcement deadlines shift, or CDSCO harmonization pathways stall. Forecasts reflect documented assumptions regarding regulatory timeline stability and procurement budget continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market