
 Cardiac Surgery Devices Market | 2026-2036
Cardiac Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Surgery Devices Market Analysis
Market Context
Transcatheter valve delivery systems are fragmenting the traditional open-heart surgery device landscape as minimally invasive platforms capture complex cases once reserved for sternotomy. Edwards Lifesciences anchors transcatheter aortic valve replacement technology through sustained R&D investment in next-generation delivery catheters. Medtronic competes across mechanical and tissue valve portfolios while leveraging its structural heart franchise to extend geographic reach into Asia-Pacific tertiary centers. Abbott Laboratories differentiates through its MitraClip platform and hybrid device pipeline, positioning the company at the intersection of surgical and interventional cardiac care.
Technical Definition and Segment Structure
Cardiac surgery devices comprise sterile instruments, implantable prostheses, perfusion apparatus, and access cannulae engineered from biocompatible alloys, biological tissues, and medical-grade polymers to enable direct cardiac intervention under cardiopulmonary bypass or beating-heart conditions. These devices function to restore hemodynamic competence, replace diseased valvular structures, and establish coronary revascularization conduits with tolerances measured in millimeters for suture placement and leaflet coaptation. Heart valves generate concentrated margin pools as biological and mechanical platforms command premium pricing tied to durability benchmarks and anticoagulation burden trade-offs. Minimally invasive systems represent the fastest-expanding device technology segment as port-access and robotic-assisted platforms reduce ICU length of stay and accelerate discharge protocols. Coronary artery bypass grafting applications retain dominant procedural volume globally despite percutaneous coronary intervention encroachment in select lesion subsets.
Regulatory Environment and Outlook
The FDA's premarket approval pathway and breakthrough device program govern US market entry for novel cardiac implants, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for CE marking across European Union member states. Japan's PMDA maintains distinct pharmacovigilance reporting standards for biological valve implants that shape post-market surveillance obligations for manufacturers. Stakeholders must monitor evolving equivalence determinations between transcatheter and surgical valve indications as regulatory bodies reassess labeling boundaries and reimbursement categories.
Market Dynamics
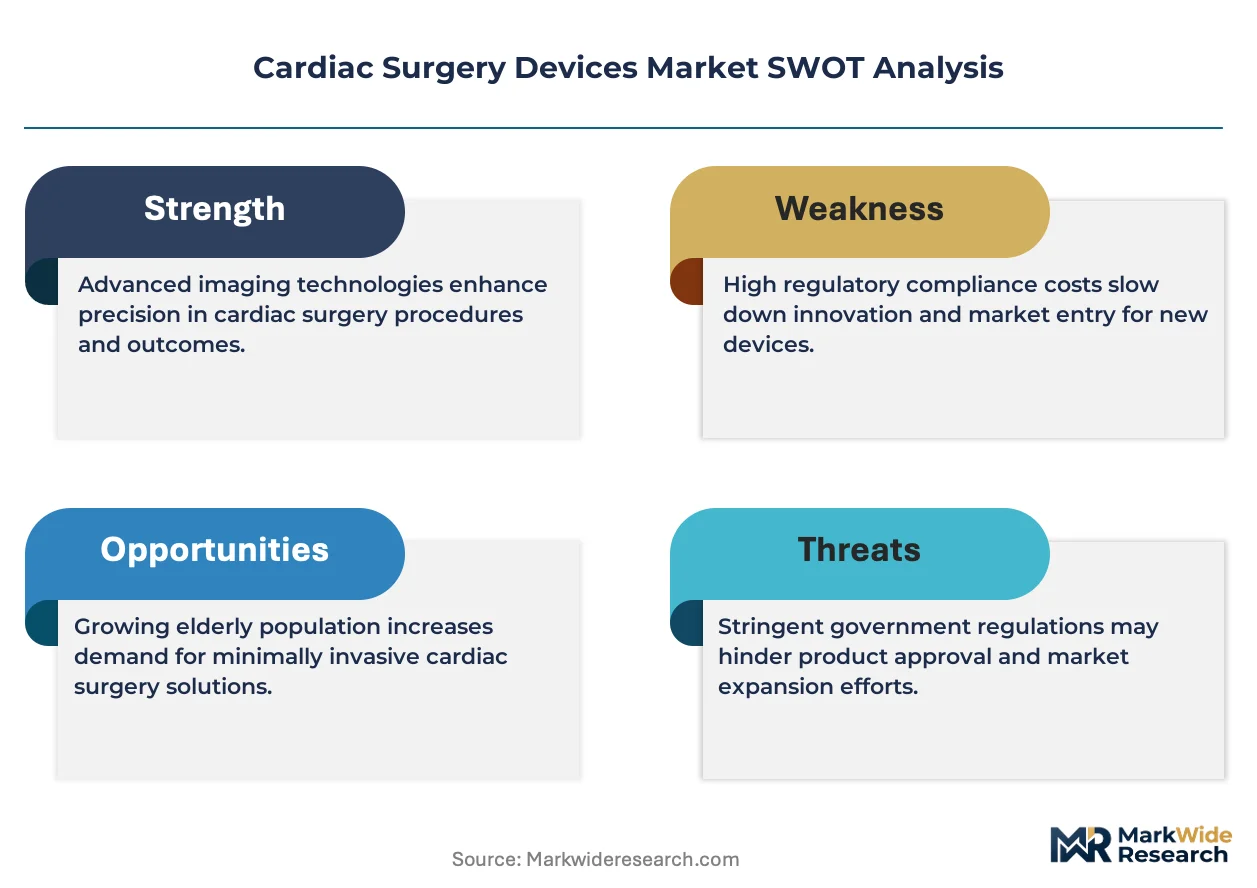
Transcatheter platforms are fragmenting the cardiac surgery device landscape by capturing complex valve cases previously reserved for sternotomy, forcing manufacturers to reconfigure R&D allocation between open-surgical and minimally invasive portfolios.
Growth Catalysts
- FDA Breakthrough Device Pathway:The accelerated approval timeline for novel cardiac implants compresses time-to-market for transcatheter valve innovations, enabling faster clinical adoption in US tertiary centers.
- German University Hospital Networks:These institutions anchor European valve replacement volumes and drive demand for next-generation biological prostheses through structured procurement frameworks.
- Catheterization Lab Expansion:US hospitals are adding dedicated structural heart suites to handle rising transcatheter procedure volumes, creating pull-through demand for compatible delivery systems and imaging integration.
Market Restraints
- Biological Tissue Supply Concentration:Bovine and porcine pericardial sourcing depends on concentrated agricultural processing regions, exposing manufacturers to zoonotic disease outbreaks and supply interruption.
- EMA MDR Clinical Evidence Burden:The Medical Device Regulation imposes extended trial requirements for CE marking renewal, lengthening approval timelines and increasing compliance costs for European market access.
- Percutaneous Coronary Intervention Substitution:Drug-eluting stent technology continues to capture select coronary artery bypass grafting indications in multi-vessel disease, constraining surgical revascularization device volumes.
Strategic Opportunities
- Japan PMDA Biological Valve Vigilance:Distinct post-market surveillance standards for tissue implants create first-mover advantage for manufacturers establishing pharmacovigilance infrastructure ahead of competitors.
- Hybrid Operating Suite Convergence:Integration of surgical bypass capability with interventional catheter platforms enables single-setting revascularization and valve procedures, opening new procedure categories.
- Direct-to-Hospital Distribution:Bypassing traditional distributor networks for high-value implantables reduces margin leakage and strengthens manufacturer control over inventory and consignment models.
Industry Challenges
- Structural Heart Imaging Specialist Shortage:Transcatheter procedures require advanced echocardiography and CT interpretation skills that outpace current fellowship training pipeline output.
- Legacy Electronic Health Record Integration:New device data capture requirements for implant registries conflict with outdated hospital IT infrastructure, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Surgery Devices Market |
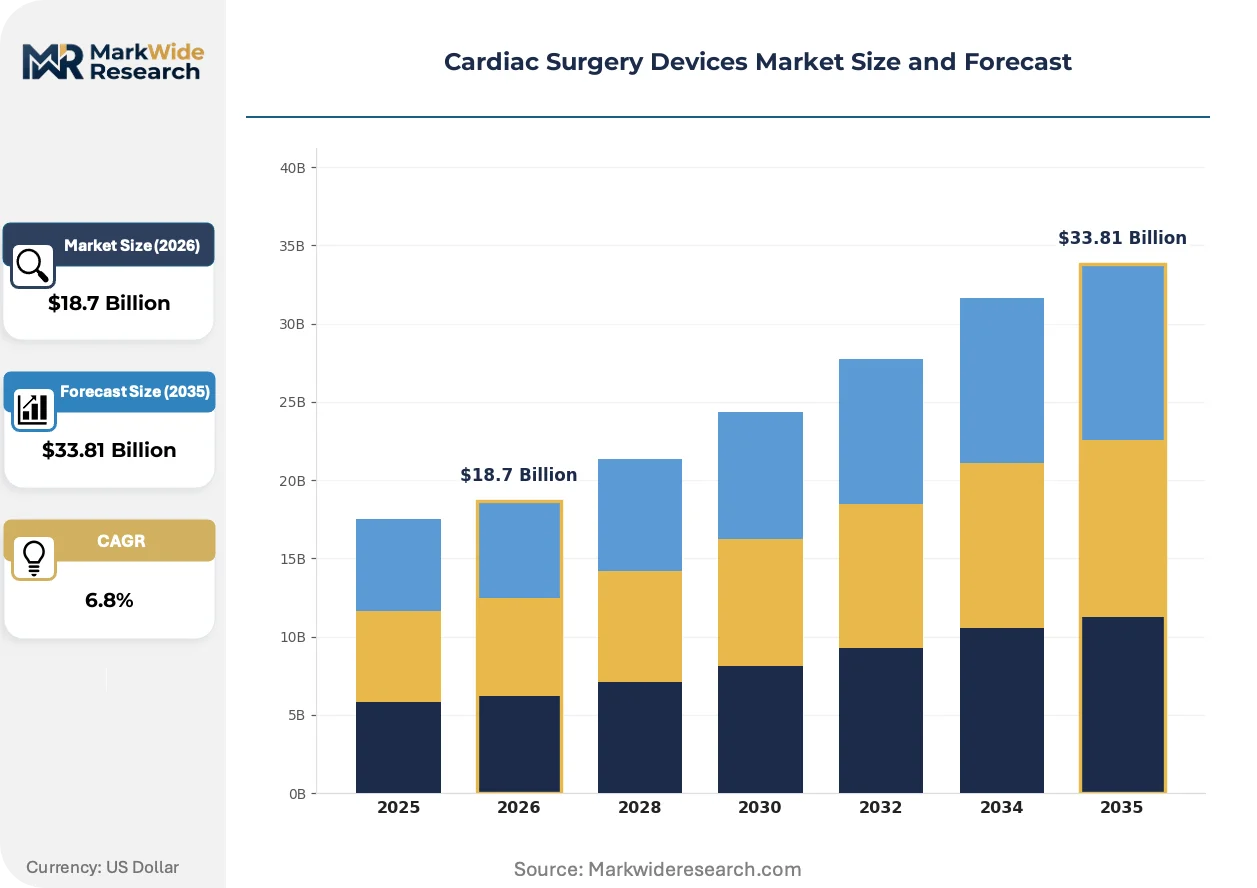
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valves, Surgical Instruments, Cardiopulmonary Bypass Equipment, Cannulae Application: Coronary Artery Bypass Grafting, Valve Replacement, Aneurysm Repair, Cardiac Resynchronization Therapy End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Cardiac Research Institutes Device Technology: Mechanical Valves, Tissue Valves, Hybrid Devices, Minimally Invasive Systems |
| Companies Covered | Edwards Lifesciences, Abbott Laboratories, Medtronic, Boston Scientific Corporation, Terumo Corporation, GE Healthcare, LivaNova, Cardinal Health, B. Braun Melsungen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Surgery Devices Market Emerging Trajectories
Device architecture is converging around modular platforms that bridge surgical and interventional workflows, while regulatory bodies recalibrate evidence standards to match hybrid procedure complexity.
Next-generation sutureless aortic valve prostheses are hybridizing surgical implantation techniques with transcatheter delivery mechanics, enabling beating-heart deployment through limited thoracotomy incisions. Cardiac surgeons in high-volume European centers are adopting these platforms to reduce cross-clamp time and ICU dependency. The technology is compressing the traditional boundary between sternotomy-based and percutaneous valve replacement by serving intermediate-risk patients previously excluded from both categories.
The EU Medical Device Regulation now mandates annual safety update reports and proactive post-market clinical follow-up for Class III implantable cardiac devices, extending manufacturer surveillance obligations beyond prior directive requirements. This regulatory tightening is elevating documentation costs and forcing portfolio rationalization among smaller device firms. Biological valve manufacturers with established European notified body relationships are consolidating market position while competitors delay CE marking submissions.
Hospital value analysis committees have displaced individual surgeon preference as the dominant purchasing authority for cardiac implants, centralizing procurement decisions under supply chain and finance leadership. This committee structure prioritizes standardized vendor contracts and outcome data transparency over traditional device loyalty. The shift is most pronounced in US integrated delivery networks where catheterization lab standardization across multiple hospital sites creates volume leverage for price negotiation.
Cardiac Surgery Devices Market Segmentation
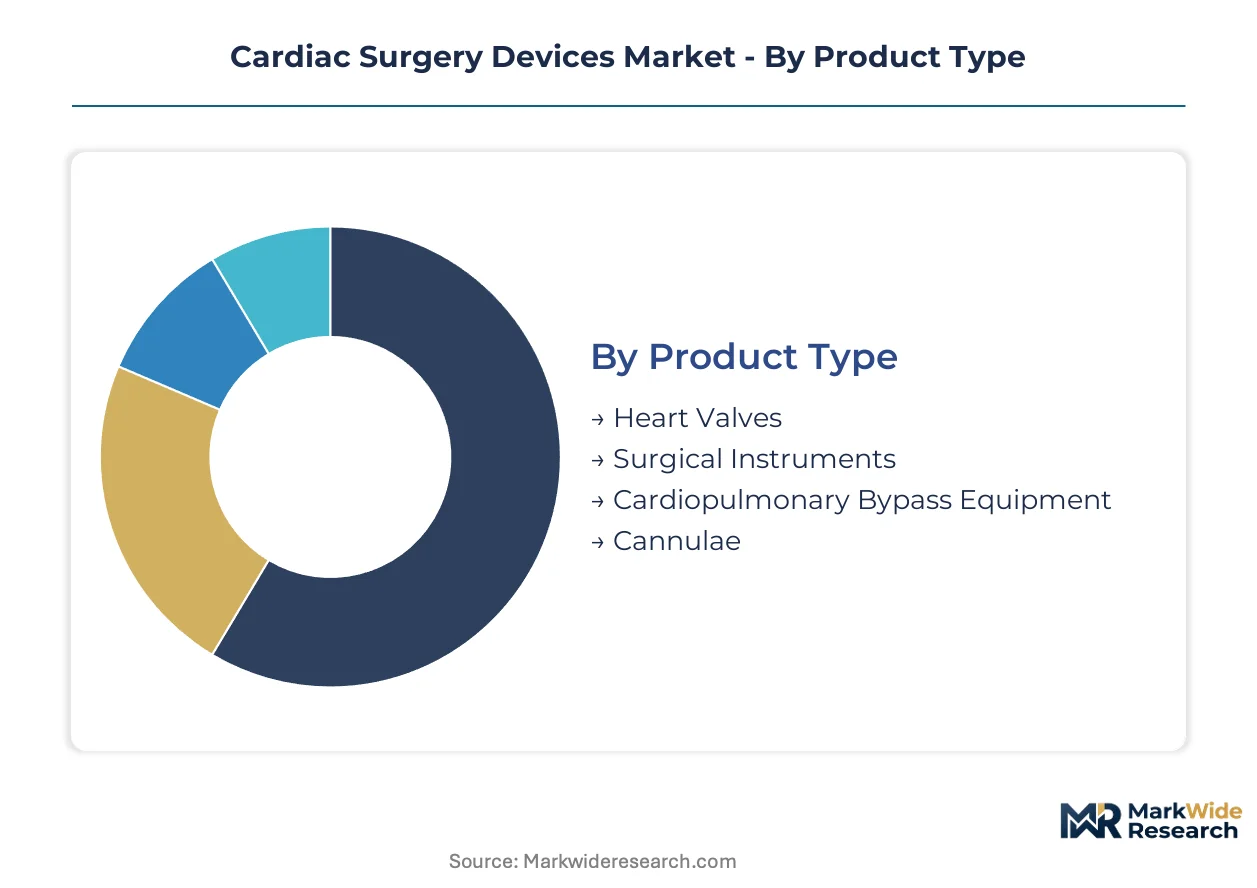
Segmentation in cardiac surgery devices reveals how procedure complexity, patient risk profiles, and facility capabilities fragment purchasing decisions across distinct technology tiers and clinical settings. Manufacturers must align product portfolios with specific hemodynamic restoration pathways rather than treating cardiac intervention as a uniform market.
Product Type:
The use-case spectrum spans implantable prostheses through disposable access tools, each commanding different margin structures and replacement cycles.
- Heart Valves:Biological and mechanical prostheses engineered from bovine pericardium, porcine tissue, or pyrolytic carbon deliver hemodynamic restoration with durability measured in decades. Demand concentrates in German university hospitals and US tertiary centers where transcatheter platforms are displacing traditional surgical volumes.
- Surgical Instruments:Precision-machined sternal saws, retractors, and needle holders fabricated from surgical-grade stainless steel enable direct cardiac access. Adoption tracks open-procedure volumes in India and Brazil where cost constraints delay minimally invasive platform penetration.
- Cardiopulmonary Bypass Equipment:Oxygenators, pumps, and heat exchangers maintain systemic perfusion during arrested-heart procedures. These systems anchor procurement decisions in high-volume surgical centers performing complex multi-valve operations.
- Cannulae:Biocompatible polymer and metal vascular access devices establish extracorporeal circulation circuits. Demand follows bypass procedure frequency with particular concentration in European centers maintaining robust surgical valve programs.
The dominant share belongs to Heart Valves, while Minimally Invasive Systems within the broader technology landscape are closing the gap fastest.
Application:
Cost tier stratification separates high-complexity revascularization from standardized valve replacement workflows.
- Coronary Artery Bypass Grafting:Surgical revascularization using arterial and venous conduits restores myocardial perfusion in multi-vessel disease. Volumes concentrate in US integrated delivery networks where hybrid operating suites enable combined interventional-surgical approaches.
- Valve Replacement:Prosthetic implantation addresses stenotic or regurgitant native valves across aortic, mitral, tricuspid, and pulmonary positions. German and Japanese centers drive biological valve demand through structured referral networks and aging demographics.
- Aneurysm Repair:Aortic root reconstruction and arch replacement procedures require specialized perfusion strategies and cerebral protection devices. These cases cluster in quaternary referral centers with established aortic surgery programs.
- Cardiac Resynchronization Therapy:Device-based coordination of ventricular contraction complements surgical intervention in heart failure populations. Application growth tracks expanding indications for combined electrophysiology-cardiac surgery collaboration.
Coronary Artery Bypass Grafting retains the largest procedure base, though Valve Replacement is expanding most quickly as transcatheter eligibility broadens.
End User:
Customer type determines capital intensity requirements and purchasing committee composition.
- Hospitals:Acute care facilities with dedicated cardiothoracic surgery departments perform the majority of complex procedures. These institutions anchor demand for integrated perfusion systems and high-value implantables through value analysis committee procurement.
- Specialty Clinics:Focused cardiac centers concentrate elective procedures with streamlined preoperative pathways. Such facilities prioritize disposable instrument standardization and rapid turnover protocols.
- Ambulatory Surgical Centers:Limited-service settings capture select low-acuity cardiac interventions where overnight stay requirements diminish. Regulatory scope constraints limit these centers to diagnostic and minor therapeutic procedures in most jurisdictions.
- Cardiac Research Institutes:Academic and clinical trial facilities drive early adoption of investigational devices. These users generate disproportionate influence on subsequent mainstream procurement through publication and training network effects.
Hospitals command the dominant institutional share, while Ambulatory Surgical Centers are gaining traction fastest where regulatory frameworks permit expanded procedure lists.
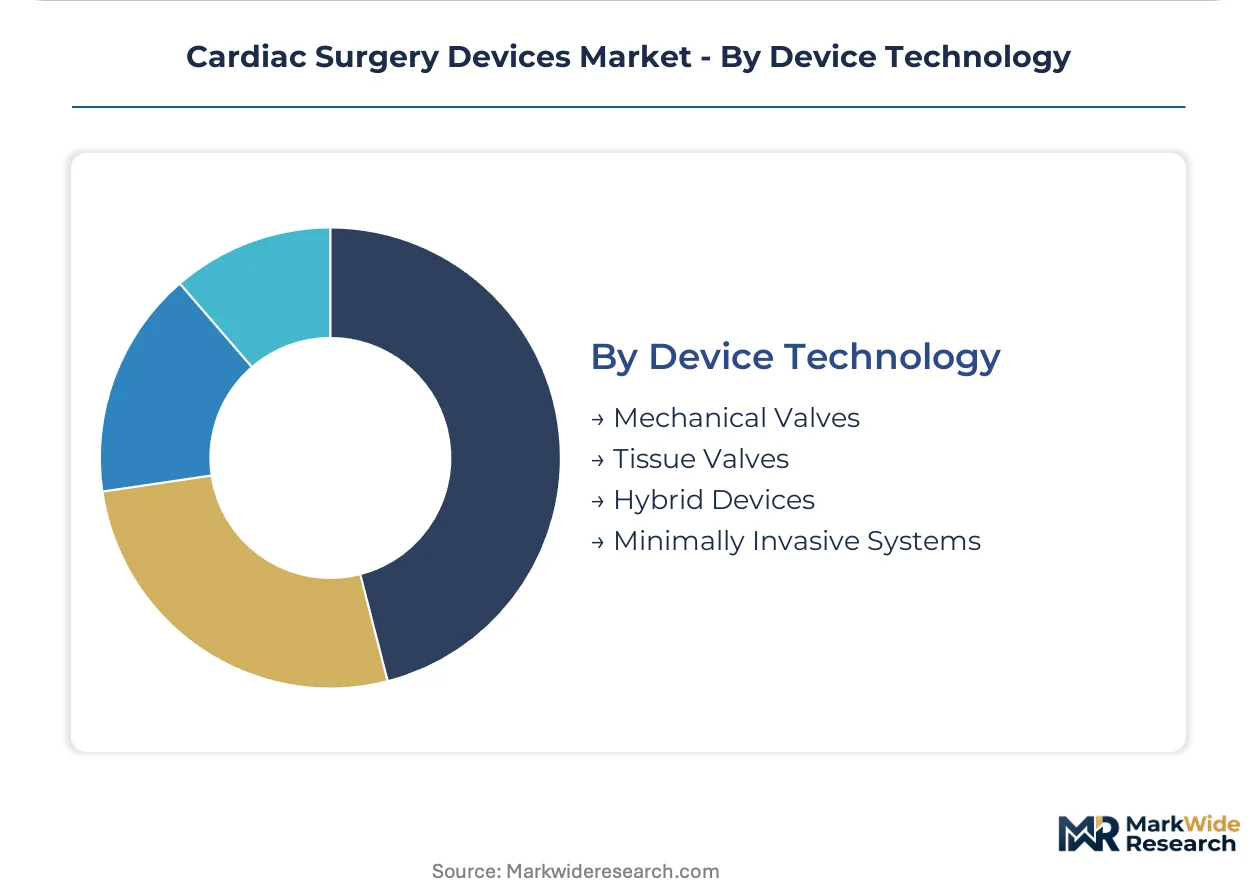
Device Technology:
Volume concentration varies sharply between established mechanical platforms and emerging hybrid architectures.
- Mechanical Valves:Pyrolytic carbon occluders housed in titanium or cobalt-chromium frames deliver indefinite durability with anticoagulation burden. Demand persists in younger patients and developing markets where lifelong medication access is reliable.
- Tissue Valves:Biological prostheses from bovine pericardium or porcine aortic roots eliminate anticoagulation but carry structural deterioration risk. Japanese PMDA vigilance requirements and European MDR surveillance obligations shape manufacturer competitive positioning.
- Hybrid Devices:Sutureless and rapid-deployment valves combine surgical implantation with transcatheter delivery mechanics. European high-volume centers are adopting these platforms for intermediate-risk patients excluded from pure percutaneous approaches.
- Minimally Invasive Systems:Port-access and robotic-assisted platforms reduce sternal trauma and accelerate recovery. US hospital catheterization lab expansion is pulling these systems into structural heart suites alongside traditional surgical equipment.
Tissue Valves hold the leading position by implant volume, though Hybrid Devices are climbing the fastest as procedural boundaries blur.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export transcatheter valve systems to tertiary centers across the United States and Japan, establishing the dominant trade corridor in high-value cardiac implants. This flow pattern concentrates procurement influence in university hospital networks while shaping regulatory alignment demands across three continents.
United States
The FDA's breakthrough device designation accelerates approval timelines for novel transcatheter valves, compressing commercialization cycles. Hospital systems in Cleveland and Houston are expanding dedicated structural heart suites to capture rising procedure volumes. The Centers for Medicare & Medicaid Services reimbursement frameworks determine site-of-service economics for hybrid operating room investments.
Germany
University hospital networks in Munich and Heidelberg anchor European valve replacement volumes through structured referral pathways. The EMA's Medical Device Regulation imposes extended clinical evidence requirements for CE marking renewal, elevating compliance costs. Baden-Württemberg manufacturing clusters supply sutureless valve platforms to high-volume cardiac centers.
Japan
PMDA pharmacovigilance standards for biological tissue implants create distinct post-market surveillance obligations. Tokyo and Osaka medical centers drive demand for next-generation tissue valves through aging demographics and expanded transcatheter indications. The Ministry of Health, Labour and Welfare reimbursement revisions determine procedural access thresholds.
China
NMPA regulatory harmonization efforts accelerate domestic valve platform approvals while maintaining import requirements for foreign manufacturers. Shanghai and Beijing tertiary hospitals are adopting hybrid surgical-interventional workflows. Provincial centralized procurement programs compress pricing for mechanical and tissue prostheses.
India
CDSCO medical device rules impose quality standards on imported cardiac implants while streamlining domestic manufacturing approvals. Chennai and Mumbai cardiac centers concentrate surgical valve volumes amid cost constraints delaying transcatheter platform penetration. Government hospital procurement tenders dominate mechanical valve demand.
Cardiac Surgery Devices Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments where hospital value analysis committees displace individual surgeon preference. The market structure concentrates around integrated cardiovascular franchises with structural heart portfolios spanning surgical and interventional modalities. Three archetypes dominate: diversified medical technology conglomerates with perfusion-to-implant vertical scope; pure-play structural heart specialists with concentrated transcatheter R&D and regional equipment manufacturers serving cost-sensitive bypass markets. Competitive moves center on portfolio hybridization between open-surgical and catheter-based platforms, plus direct-to-hospital distribution bypassing traditional distributor networks.
Among diversified technology conglomerates, Edwards Lifesciences and Medtronic occupy positions spanning tissue valve manufacturing through transcatheter delivery system development. Abbott Laboratories exemplifies the structural heart specialist archetype with concentrated investment in mitral repair platforms. These three anchors illustrate how competitive positioning fragments across surgical-to-interventional modality boundaries rather than consolidating around single procedure categories.
| Leading Market Players |
|---|
| Edwards Lifesciences |
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| Terumo Corporation |
| GE Healthcare |
| LivaNova |
| Cardinal Health |
| B. Braun Melsungen |
| Others |
Supply Flow & Price Mechanics
Frankfurt-to-Chicago air freight corridors carry biological valve tissues and precision-machined delivery catheters at premium rates, compressing margins for manufacturers while enabling three-tier pricing stratification across German-engineered premium prostheses, Asian-manufactured mechanical valves, and regional standard-tier instruments.
Pricing Analysis
Next-generation transcatheter delivery systems command 40-60% premiums over prior-generation surgical platforms, while legacy mechanical valves face commoditization in Indian government tenders. Three-tier pricing structure across premium, standard, and economy levels separates FDA-designated breakthrough devices from CE-marked equivalents and unregulated regional alternatives. Price erosion runs through mechanical valve tiers as Chinese provincial procurement programs enforce volume-based discounting. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while German university hospitals prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for cardiac surgery device manufacturers sourcing nitinol tubing and biological tissue processing equipment. Manufacturing concentrates in Germany for sutureless valve platforms, Ireland for perfusion system assembly, and Malaysia for disposable instrument production. Raw material procurement draws from Australian bovine pericardium farms, Japanese pyrolytic carbon suppliers, and Swiss precision-machining operations. Single-source vulnerability persists in biological tissue sterilization services. Distribution runs through direct-to-hospital consignment models for implantables and distributor networks for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac surgery device markets increasingly monetize through service-attach revenue streams, with remote monitoring subscriptions for transcatheter valve patients expanding faster than hardware replacement cycles.
For Market Incumbents: Build regulatory data moats through proactive post-market surveillance infrastructure that satisfies Japan PMDA and EU MDR requirements ahead of competitor submissions. Deepen backward integration into biological tissue processing to secure supply continuity against zoonotic disease outbreaks. Expand catheterization lab partnership programs to lock in delivery system standardization before rival platforms achieve critical mass. For New Entrants and Emerging Players: Build out hybrid device portfolios targeting intermediate-risk patients excluded from pure transcatheter and pure surgical categories in European high-volume centers. Focus initial penetration on Indian mechanical valve tenders where cost constraints delay premium platform adoption. Pursue direct-to-hospital distribution bypassing established distributor markups to capture margin advantage in price-sensitive procurement environments. For Investors and Strategic Acquirers: Specialized structural heart software firms with FDA-cleared imaging analytics represent priority acquisition targets as procedural complexity drives algorithmic dependency. Long-term viability hinges on portfolio breadth spanning surgical-to-interventional modality boundaries rather than single-procedure concentration. Watch for reimbursement parity decisions between transcatheter and surgical valve indications as inflection signals for platform shift velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR clinical evidence requirements extend approval timelines for European market access. |
| Hospital System Partnership | Value analysis committee standardization creates volume leverage for pricing negotiation. |
| Software Companion Development | Imaging integration platforms address structural heart specialist shortage constraints. |
| Reimbursement Strategy | CMS site-of-service economics determine hybrid operating room investment returns. |
| Backward Integration | In-house biological tissue processing reduces zoonotic supply interruption exposure. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EMA CE marking databases, CMS Medicare procedure data, and hospital procurement contract repositories. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporated procedure volume trajectories by valve position and access route, technology substitution curves between surgical and transcatheter platforms, and reimbursement elasticity parameters across US, German, and Japanese payment systems. CAGRs derived from logistic diffusion modeling of platform adoption curves, with cross-segment consistency checks against perfusion equipment replacement cycles and biological valve structural deterioration rates.
Sensitivities concentrate around regulatory equivalence determinations between transcatheter and surgical indications, biological tissue supply disruptions, and catheterization lab capacity expansion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Interventional Cardiology Market