
 Consumer Grade EEG Device Market | 2026-2036
Consumer Grade EEG Device Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Grade EEG Device Market Insights
The EU AI Act is shifting liability frameworks for algorithmic health recommendations embedded in consumer EEG software. Emotiv leverages its dry electrode patent portfolio to sustain hardware margins across direct-to-consumer channels. NeuroSky competes on cost-optimized semiconductor design for Asian OEM partnerships. Interaxon anchors its position through meditation-app ecosystem integration that deepens user retention cycles.
Consumer grade EEG devices measure electrical brain activity via non-invasive scalp electrodes, typically sampling at 256 Hz to 1024 Hz with 8 to 32 channels for real-time neurophysiological monitoring in home or ambulatory settings. Dry electrode configurations dominate the product type landscape due to elimination of conductive gel and simplified onboarding workflows. The end user base bifurcates sharply: individuals purchase through retail for wellness tracking while researchers demand calibrated signal fidelity that commands premium pricing tiers. Application-level momentum clusters around mental health monitoring and neurofeedback protocols as reimbursement codes gradually expand for remote therapeutic interventions.
FDA software-as-medical-device guidance, EU MDR Class IIa device classification, and China's NMPA innovation pathway collectively determine market access timelines and clinical claim permissibility for consumer-oriented manufacturers. ISO 13485 quality management certification and IEC 60601 electrical safety standards function as baseline procurement filters for institutional buyers across North American and European health systems. Stakeholders must monitor evolving regulatory divergence between wellness-exempt and medical-grade classification thresholds to calibrate product positioning and geographic launch sequencing.
Market Dynamics
The Consumer Grade EEG Device Market pivots on regulatory bifurcation between wellness-exempt and medical-grade classification thresholds, forcing manufacturers to architect dual-track compliance frameworks while dry electrode advances compress hardware differentiation windows.
Growth Catalysts
- FDA SaMD Pathway:The FDA's software-as-medical-device guidance accelerates algorithmic health claim approvals for EEG analytics platforms, reducing time-to-market for neurofeedback therapeutic applications.
- Dry Electrode Innovation:Elimination of conductive gel through polymer-composite sensor arrays removes onboarding friction for home users and expands addressable wellness segments.
- Germany's Digital Care Act:Reimbursement code expansion for remote therapeutic monitoring creates institutional procurement pull for calibrated consumer-grade hardware in ambulatory mental health protocols.
Market Restraints
- Signal Fidelity Trade-offs:Dry electrode configurations sacrifice spatial resolution versus wet-gold-standard clinical systems, constraining researcher willingness to pay premium tiers for uncalibrated consumer hardware.
- Semiconductor Supply Concentration:ASIC fabrication for low-noise analog front-ends clusters in Taiwan and South Korea foundries, exposing OEMs to geopolitical supply disruption risk.
- EU MDR Class IIa Burden:Clinical claim permissibility requires notified body intervention and post-market surveillance systems that inflate fixed compliance costs for sub-scale entrants.
Strategic Opportunities
- China's NMPA Innovation Track:Priority review pathways for AI-enabled diagnostic software compress regulatory timelines for algorithmic EEG biomarker platforms targeting cognitive decline screening.
- EEG-fNIRS Convergence:Hybrid optical-electrical neuroimaging architectures enable hemodynamic validation of electrical signals, opening premium positioning for dual-modality home monitoring systems.
- Employer Wellness Channels:Corporate mental health benefit administrators represent underpenetrated procurement nodes seeking validated stress-monitoring endpoints for workforce productivity programs.
Industry Challenges
- Biomedical Signal Processing Talent Scarcity:Cross-functional engineering teams combining neuroscience domain knowledge with embedded systems optimization command compensation premiums that strain R&D budgets.
- IEC 60601-1-2 EMC Certification Delays:Electromagnetic compatibility testing for home-use RF environments extends hardware validation cycles and defers revenue recognition.
- Interoperability Fragmentation:Proprietary data formats across meditation-app ecosystems and clinical research platforms force redundant API development and dilute platform network effects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Grade EEG Device Market |
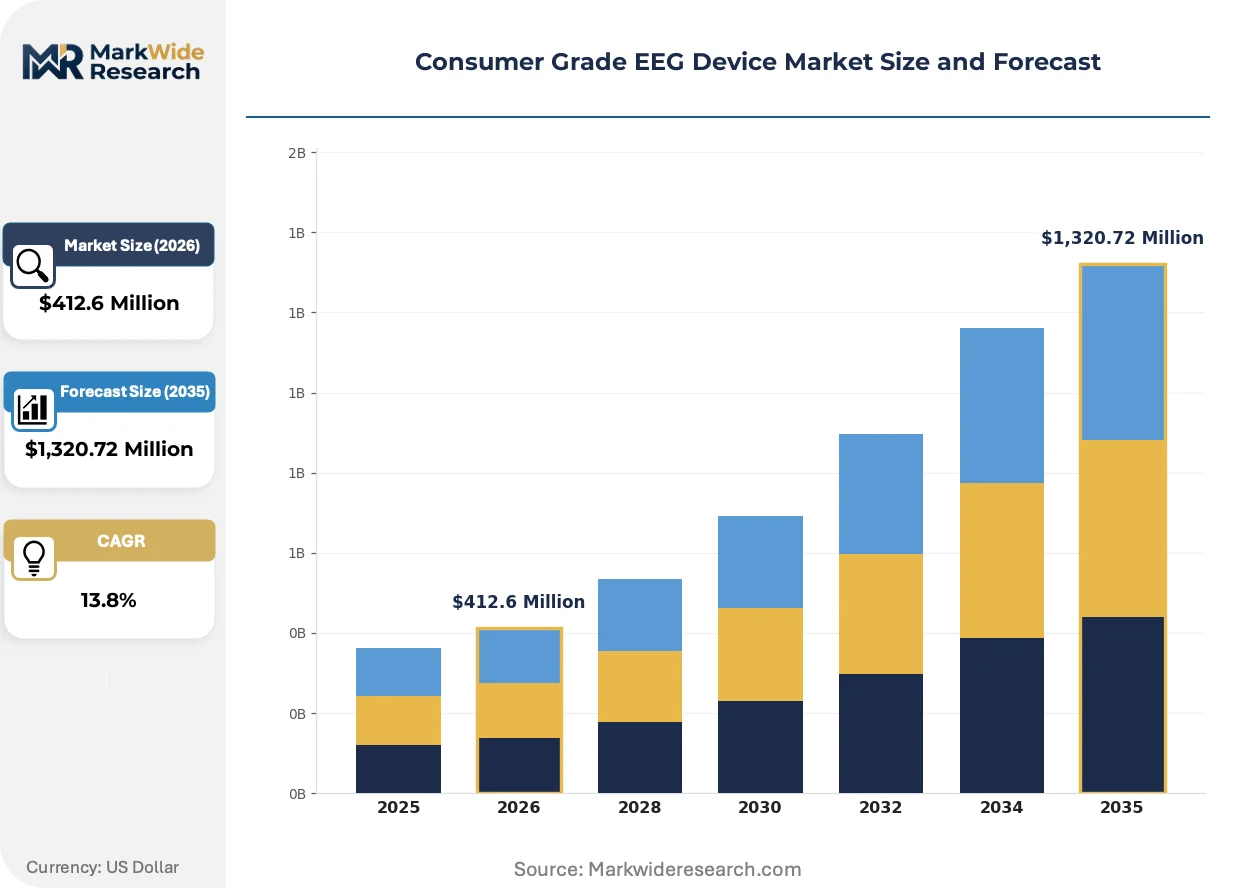
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,320.72 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Headsets, Mobile Devices, Portable Units, Smartphone Accessories End User: Individuals, Healthcare Professionals, Researchers, Educational Institutions Technology: Dry Electrode, Wet Electrode, Wireless Communication, Signal Processing Application: Mental Health Monitoring, Sleep Analysis, Cognitive Enhancement, Neurofeedback |
| Companies Covered | Emotiv, NeuroSky, Interaxon, Wearable Sensing, Neuroelectrics, Cognionics, Bitbrain, BrainBit, Neeuro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Grade EEG Device Market Trends and Innovations
Wearable neurotechnology architectures are fragmenting into specialized component layers as regulatory clarity and demand segmentation mature, creating openings for modular suppliers to capture value previously monopolized by integrated device manufacturers.
Flexible printed circuit board substrates with micro-needle electrode arrays are modularizing the physical interface between scalp and signal acquisition electronics. Academic research groups and boutique OEMs are adopting these substrates at accelerating cadence to bypass legacy wet-electrode supply chains. This modularization is compressing hardware development cycles and enabling rapid form-factor experimentation for sleep, athletic, and pediatric use cases.
The EU AI Act's risk-based classification for biometric inference systems is imposing documentation and human-oversight obligations on algorithmic mental health recommendations embedded in consumer EEG software. Industrial consequence includes mandatory conformity assessments for affective state classification models that previously operated under wellness exemptions. Meditation-app integrators and neurofeedback platform developers face the steepest compliance ramps as they recategorize algorithmic outputs from wellness insights to health-relevant biomarkers.
Institutional procurement for remote therapeutic monitoring is displacing direct-to-consumer retail as the dominant revenue channel for calibrated hardware. Hospital-at-home programs and telepsychiatry platforms are consolidating demand through group purchasing organizations that mandate ISO 13485 certification and signal fidelity documentation. The United States exhibits the most pronounced channel rotation as CMS reimbursement expansion for remote patient monitoring creates volume commitments that override retail margin structures.
Consumer Grade EEG Device Market Segmentation
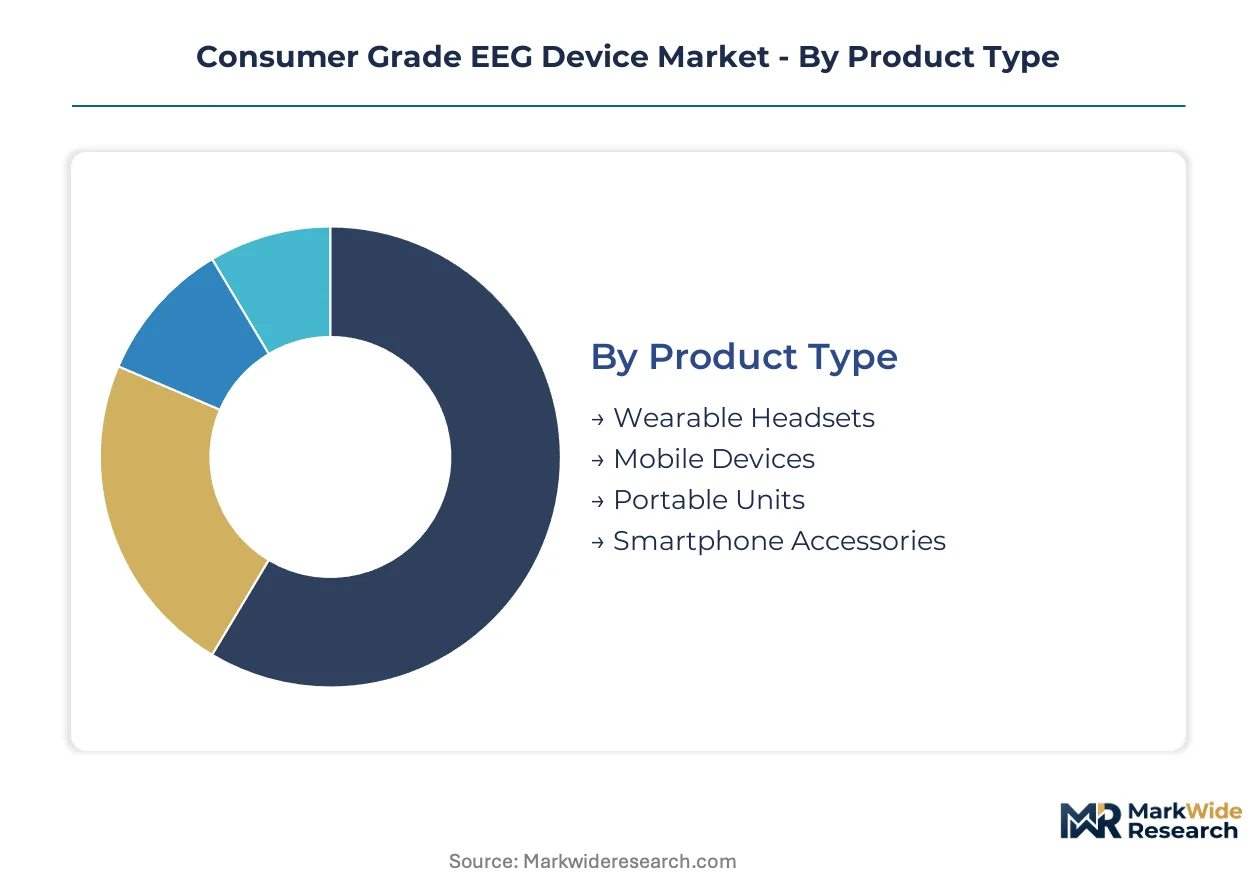
Segmentation in the consumer EEG device market determines which regulatory pathways manufacturers must navigate. FDA SaMD classifications, EU MDR thresholds, and China's NMPA innovation tracks apply differently across product configurations and end-use contexts, directly shaping commercialization timelines and geographic prioritization.
Product Type:
Wearable headsets require FDA 510(k) clearance for neurofeedback claims while smartphone accessories fall under wellness exemptions. Mobile devices and portable units occupy intermediate regulatory territory depending on embedded algorithm outputs.
- Wearable Headsets:Over-ear and headband form factors integrate 8-32 channel dry electrode arrays with onboard signal processing. Demand concentrates in the United States among telepsychiatry platforms and employer wellness programs seeking validated stress-monitoring endpoints. FDA SaMD pathway acceleration favors manufacturers embedding therapeutic neurofeedback algorithms.
- Portable Units:Briefcase-sized systems with calibrated signal fidelity serve ambulatory mental health protocols in Germany under Digital Care Act reimbursement expansion. Clinical claim permissibility requires notified body intervention for EU MDR Class IIa compliance, inflating fixed costs that favor scaled manufacturers.
- Mobile Devices:Tablet-integrated systems with detachable electrode caps target educational institutions and research settings.
- Smartphone Accessories:Single-channel earbud or clip-on sensors bypass gel application through polymer-composite interfaces.
Leading the category by volume: Wearable Headsets. Growing fastest: Smartphone Accessories.
End User:
Procurement authority bifurcates sharply between institutional buyers mandating ISO 13485 certification and direct-to-consumer retail channels prioritizing onboarding simplicity.
- Individuals:Wellness-focused consumers purchase through retail for meditation-app integration and sleep tracking. Onboarding friction elimination through dry electrode configurations expands addressable segments beyond early adopters.
- Healthcare Professionals:Telepsychiatry platforms and hospital-at-home programs in the United States consolidate demand through group purchasing organizations. CMS reimbursement expansion for remote patient monitoring creates volume commitments that override retail margin structures.
- Researchers:Academic laboratories demand calibrated signal fidelity with documented electrode impedance specifications.
- Educational Institutions:University neuroscience departments and K-12 STEM programs procure entry-level systems for pedagogical demonstration.
Volume concentrates with: Individuals. Steepest expansion trajectory: Healthcare Professionals.
Technology:
Electrode chemistry and data transmission architectures determine hardware differentiation windows and semiconductor supply exposure.
- Dry Electrode:Polymer-composite and micro-needle arrays eliminate conductive gel, compressing onboarding workflows for home users. Foundry concentration for low-noise analog front-end ASICs in Taiwan and South Korea exposes OEMs to geopolitical supply disruption risk.
- Wireless Communication:Bluetooth Low Energy and proprietary RF protocols enable real-time data streaming to meditation-app ecosystems. EU AI Act documentation obligations for biometric inference systems impose conformity assessment burdens on affective state classification models.
- Wet Electrode:Silver-silver chloride gel-based configurations retain spatial resolution superiority for research applications.
- Signal Processing:Embedded edge computing and cloud-based analytics platforms differentiate through algorithmic biomarker validation.
Widest installed base: Dry Electrode. Climbing the fastest: Wireless Communication.
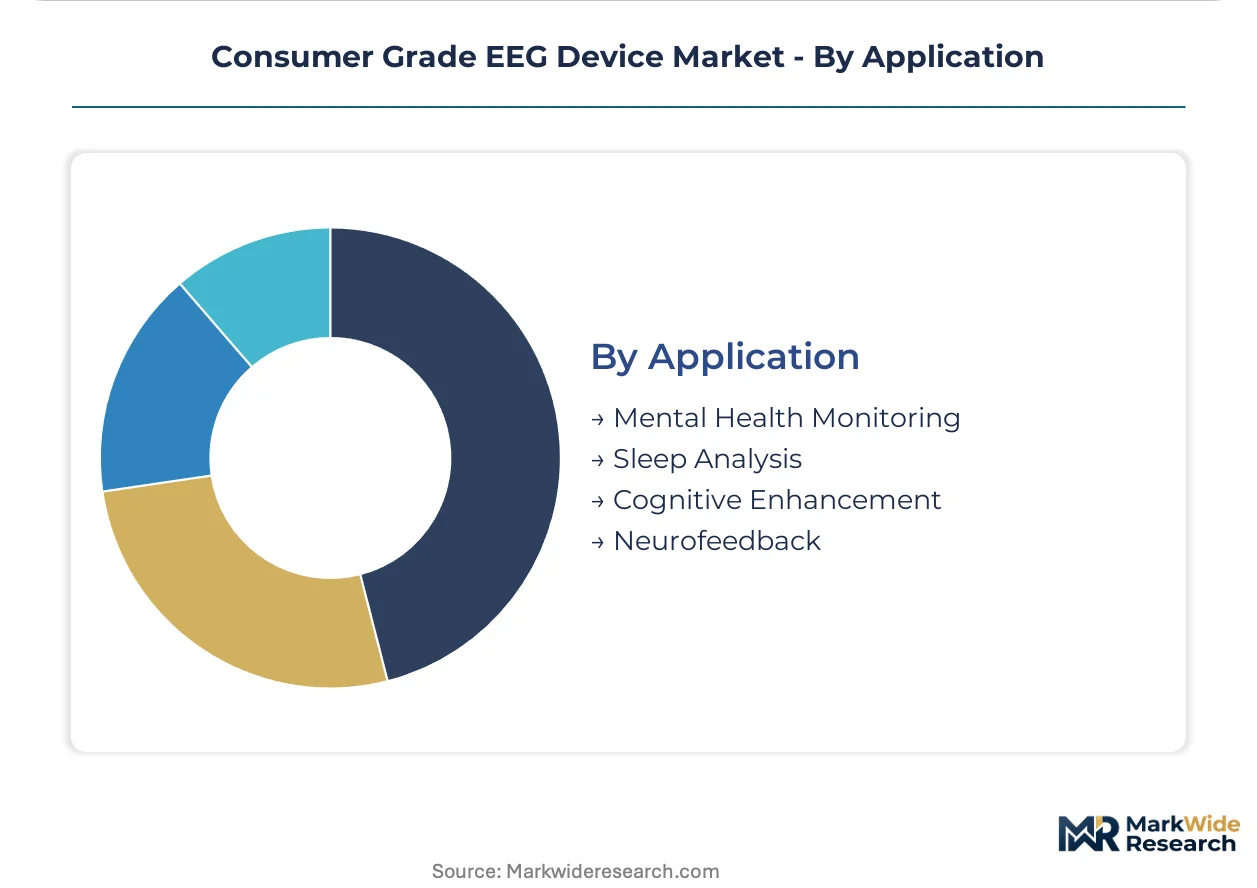
Application:
Reimbursement code availability and clinical evidence thresholds segment addressable markets between wellness-exempt and medical-grade positioning.
- Mental Health Monitoring:Anxiety, depression, and PTSD biomarker detection drives institutional procurement in the United States and Germany. Remote therapeutic monitoring reimbursement expansion creates procurement pull for calibrated hardware in ambulatory protocols.
- Neurofeedback:Real-time brainwave visualization for attention training and peak performance commands premium pricing tiers. China's NMPA innovation pathway compresses regulatory timelines for AI-enabled diagnostic software targeting cognitive decline screening.
- Sleep Analysis:Overnight EEG staging competes with polysomnography alternatives in home diagnostic markets.
- Cognitive Enhancement:Working memory and focus training applications target productivity-oriented consumers and corporate wellness channels.
Dominant revenue share: Mental Health Monitoring. Gaining share fastest: Neurofeedback.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Shanghai anchor Asia-Pacific manufacturing concentration for consumer neurotechnology components, while tax-advantaged research corridors in Massachusetts and North Carolina drive United States demand aggregation.
United States
Telepsychiatry platforms and employer wellness programs drive hardware procurement through group purchasing organizations. FDA software-as-medical-device guidance accelerates neurofeedback therapeutic claims for algorithmic platforms. The Research Triangle Park corridor in North Carolina hosts multiple digital health incubators refining remote patient monitoring integrations.
Germany
Ambulatory mental health protocols under the Digital Care Act create institutional pull for calibrated portable units. EU MDR Class IIa device classification mandates notified body intervention for clinical claim permissibility. The Munich-Frankfurt corridor concentrates medical device engineering talent and notified body presence for accelerated conformity assessments.
China
NMPA innovation pathway priority review compresses regulatory timelines for AI-enabled diagnostic software targeting cognitive decline screening. Dual carbon goals incentivize low-power edge computing architectures in neurotechnology hardware. Shenzhen's Qianhai special economic zone hosts ASIC foundry partnerships for low-noise analog front-end production.
Japan
METI funding for aging-in-place technologies accelerates home-use EEG adoption for dementia monitoring applications. PMDA streamlined review pathways for software-enabled medical devices reduce time-to-market for algorithmic biomarker platforms. The Kansai region's Osaka-Kobe medical device cluster specializes in miniaturized sensor integration for wearable form factors.
United Kingdom
NHS digital transformation programs pilot remote therapeutic monitoring for anxiety and depression management in primary care settings. MHRA recognition of FDA-approved software-as-medical-device platforms enables accelerated market entry for transatlantic manufacturers. London's King's Cross health technology cluster aggregates venture capital for neurotechnology startups targeting clinical validation pathways.
Consumer Grade EEG Device Market Competitive Landscape
United States producers anchor the premium-tier hardware segment; Chinese specialists hold cost-optimized component supply. The vendor base stratifies across three tiers: integrated device manufacturers with end-to-end software-hardware stacks, modular sensor substrate suppliers licensing to third-party OEMs, and algorithm-only platforms partnering with hardware incumbents. Dominant competitive moves include strategic patent portfolio licensing for dry electrode configurations and meditation-app ecosystem exclusivity arrangements that deepen user retention cycles.
Within the integrated device manufacturer tier, Emotiv exemplifies the patent-anchored premium positioning archetype through its dry electrode portfolio, while NeuroSky occupies the semiconductor-optimized cost leadership position serving Asian OEM partnerships. Interaxon represents the software-ecosystem integration archetype, anchoring its competitive position through meditation-app platform exclusivity that extends user lifetime value beyond hardware margins.
| Leading Market Players |
|---|
| Emotiv |
| NeuroSky |
| Interaxon |
| Wearable Sensing |
| Neuroelectrics |
| Cognionics |
| Bitbrain |
| BrainBit |
| Neeuro |
| Others |
Pricing and Supply Chain Analysis
Dry electrode polymer-composite manufacturing transitions from batch to roll-to-roll processing, compressing per-unit sensor costs while concentrating production in Taiwan and South Korea foundries. This simultaneous cost reduction and geographic clustering reshapes margin structures across wellness-exempt and medical-grade hardware tiers.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard procurement cycles for ISO 13485-certified hardware. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared neurofeedback systems from wellness-exempt consumer headsets and unbranded OEM components. Pricing pressure stems from foundry capacity constraints for low-noise analog front-end ASICs. Healthcare professionals exhibit lowest price sensitivity due to reimbursement code coverage, while individual wellness consumers drive volume through discount channels.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific to North American distribution centers has prompted regional buffer inventory strategies among GPO-serving manufacturers. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan; electrode substrate production clusters in Shenzhen and Dongguan. Raw material dependencies span polymer-composite sensor substrates, Bluetooth Low Energy modules, and medical-grade lithium-polymer cells. Single-source vulnerability in 7nm analog front-end foundry capacity exposes OEMs to allocation risk. Distribution runs through group purchasing organizations for institutional buyers and direct-to-consumer e-commerce for wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints for low-noise ASICs prop pricing premiums through the forecast horizon, constraining volume expansion for sub-scale entrants. Supply scarcity favors incumbents with allocated wafer starts.
For Market Incumbents: Hedge against semiconductor supply disruption through multi-foundry qualification programs spanning Taiwan and South Korea. Secure long-term capacity agreements before competitor allocation locks. Defensive patent licensing for dry electrode configurations blocks Asian OEM cost-optimized entrants from premium channel access.
For New Entrants and Emerging Players: FDA SaMD pathway acceleration in the United States opens a window for algorithm-only platforms to bypass hardware development entirely. White-space concentrates in employer wellness channels seeking validated stress-monitoring endpoints without clinical-grade certification burdens. Target corporate mental health benefit administrators through API-first integration with existing productivity software suites.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by telehealth platforms seeking vertical integration into remote patient monitoring hardware. Five-to-ten year viability hinges on reimbursement code expansion velocity. Acquisition target archetype: modular sensor substrate suppliers with ISO 13485 certification and existing GPO contracts. Signal to monitor: CMS remote therapeutic monitoring code updates for neurofeedback applications.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission | Accelerates neurofeedback therapeutic claims for algorithmic EEG analytics platforms. |
| CE Marking Pathway | Unlocks EU MDR Class IIa clinical claim permissibility for ambulatory mental health protocols. |
| Hospital System Partnership | Secures volume commitments through GPO contracts that override retail margin structures. |
| Software Companion Development | Deepens user retention through meditation-app ecosystem integration and biometric feedback loops. |
| Reimbursement Strategy | Aligns hardware positioning with Germany Digital Care Act and CMS remote monitoring expansion. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, NMPA innovation pathway decisions, and ISO 13485 certification registries, complemented by interviews with telepsychiatry platform procurement directors, biomedical engineering leads at academic medical centers, meditation-app product managers, and dry electrode substrate manufacturing executives. Secondary validation drew from SEC filings of neurotechnology hardware vendors, CMS reimbursement code updates, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up unit economics and top-down market sizing triangulated volume estimates.
Revenue and unit projections emerged from segmented modeling across product type, end user, technology, and application dimensions, with geographic regulatory clusters as an overlay variable. CAGRs derived from regression analysis of historical adoption curves adjusted for reimbursement policy inflection points. Industry-specific inputs included foundry capacity utilization rates for analog front-end ASICs and meditation-app subscriber conversion metrics for hardware attachment rates across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for hybrid EEG-fNIRS convergence would alter the outlook if hemodynamic validation achieves clinical guideline inclusion. Forecasts embed assumptions about FDA SaMD pathway throughput and EU AI Act enforcement timing that carry revision risk. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
France Respiratory Devices Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Ambulatory X-Ray Devices Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Smart Mask Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Pulmonary Function Testing System Market