
 Global Medical Dynamometer Market | 2026-2036
Global Medical Dynamometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Dynamometer Market Foresight
A capital-intensity divergence between precision sensor fabricators and assembly-only OEMs is redrawing vendor tiering in the medical dynamometer space. Biodex Medical Systems leverages in-house strain-gauge calibration to sustain premium positioning across North American rehabilitation networks. KERN & SOHN anchors European demand through ISO 17025-accredited force laboratories that validate clinical-grade repeatability. Charder Electronic competes aggressively in Asian physiotherapy markets with cost-optimized digital platforms certified to regional electromagnetic-compatibility standards.
A medical dynamometer is a calibrated force-measurement instrument that quantifies muscular strength output, typically resolving to 0.1-pound or 0.05-kilogram precision through load-cell or strain-gauge transduction, and serves primarily to document patient progress in orthopedic recovery and neuromuscular rehabilitation protocols. Digital dynamometer platforms are capturing share from mechanical predecessors as clinicians demand Bluetooth-enabled data logging and electronic health record integration. Muscle strength assessment applications generate the deepest margin pools due to recurring calibration-service contracts, while sports medicine represents the fastest-expanding application segment driven by professional athletic franchise investment in objective return-to-play metrics. Piezoelectric sensor technology occupies a niche in high-frequency grip-strength research but remains cost-prohibitive for routine clinical deployment.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations are elevating barrier costs for new entrants while accelerating consolidation among established manufacturers with dedicated regulatory affairs functions. The International Organization for Standardization publishes ISO 17025 and ISO 13485 frameworks that govern calibration traceability and quality-management systems respectively, and compliance with both has become a non-negotiable procurement criterion for hospital group purchasing organizations across Germany, Japan, and the United States. Stakeholders must monitor evolving cybersecurity guidance from FDA for connected diagnostic devices, as wireless-enabled dynamometers face emerging premarket scrutiny of data-integrity safeguards and encryption protocols.
Market Dynamics
Digital load-cell platforms are systematically displacing hydraulic grip-strength systems across hospital outpatient departments, driven by mandates for electronic health record interoperability and real-time telemetry in post-surgical rehabilitation protocols.
Growth Catalysts
- EU MDR Technical Documentation:Stricter conformity assessment requirements for Class I measuring devices are filtering out uncertified suppliers and consolidating procurement toward validated manufacturers with dedicated quality-management systems.
- Bluetooth-Enabled Data Logging:Wireless connectivity standards are enabling seamless integration with physiotherapy software suites, accelerating replacement cycles in German and Japanese rehabilitation networks.
- Professional Athletic Franchise Investment:Objective return-to-play metrics are driving demand for precision force-measurement instruments in sports medicine applications across North American and European markets.
Market Restraints
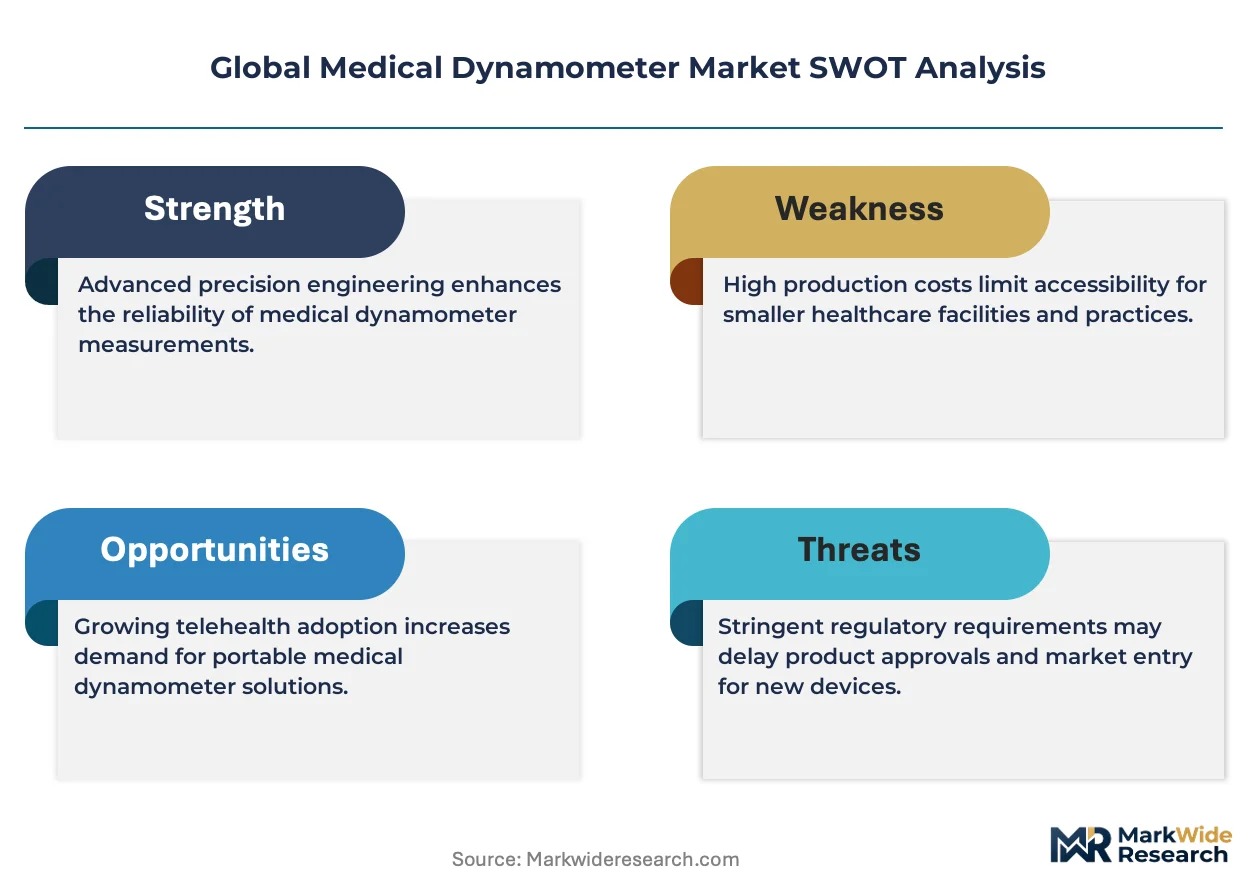
- Piezoelectric Sensor Cost Structure:High-frequency transduction materials remain economically prohibitive for routine clinical deployment, constraining adoption to specialized research laboratories.
- Strain-Gauge Supply Concentration:Precision sensor fabrication capacity clusters among ISO 17025-accredited force laboratories in Germany and Switzerland, creating vulnerability to regional production disruptions.
- FDA 510(k) Premarket Scrutiny:Elevated validation standards for wireless-enabled diagnostic devices are extending regulatory timelines and compressing margins for new market entrants.
Strategic Opportunities
- Underpenetrated Indian Physiotherapy Sector:CDSCO medical device registration pathways and expanding private rehabilitation chains present white-space expansion potential for cost-optimized digital platforms.
- Cybersecurity Guidance Convergence:FDA premarket requirements for data-integrity safeguards and encryption protocols are creating competitive differentiation for manufacturers with embedded security architectures.
- Telehealth Integration:Remote patient monitoring reimbursement codes in the United States are opening channel opportunities for cloud-connected dynamometer systems in home-based rehabilitation settings.
Industry Challenges
- Calibration Technician Scarcity:ISO 17025-accredited force metrology expertise concentrates among aging specialist workforces in European calibration laboratories, constraining service-network expansion.
- Legacy System Interoperability:Proprietary data formats from incumbent electronic health record vendors complicate API development for seamless device integration in hospital information technology environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Dynamometer Market |
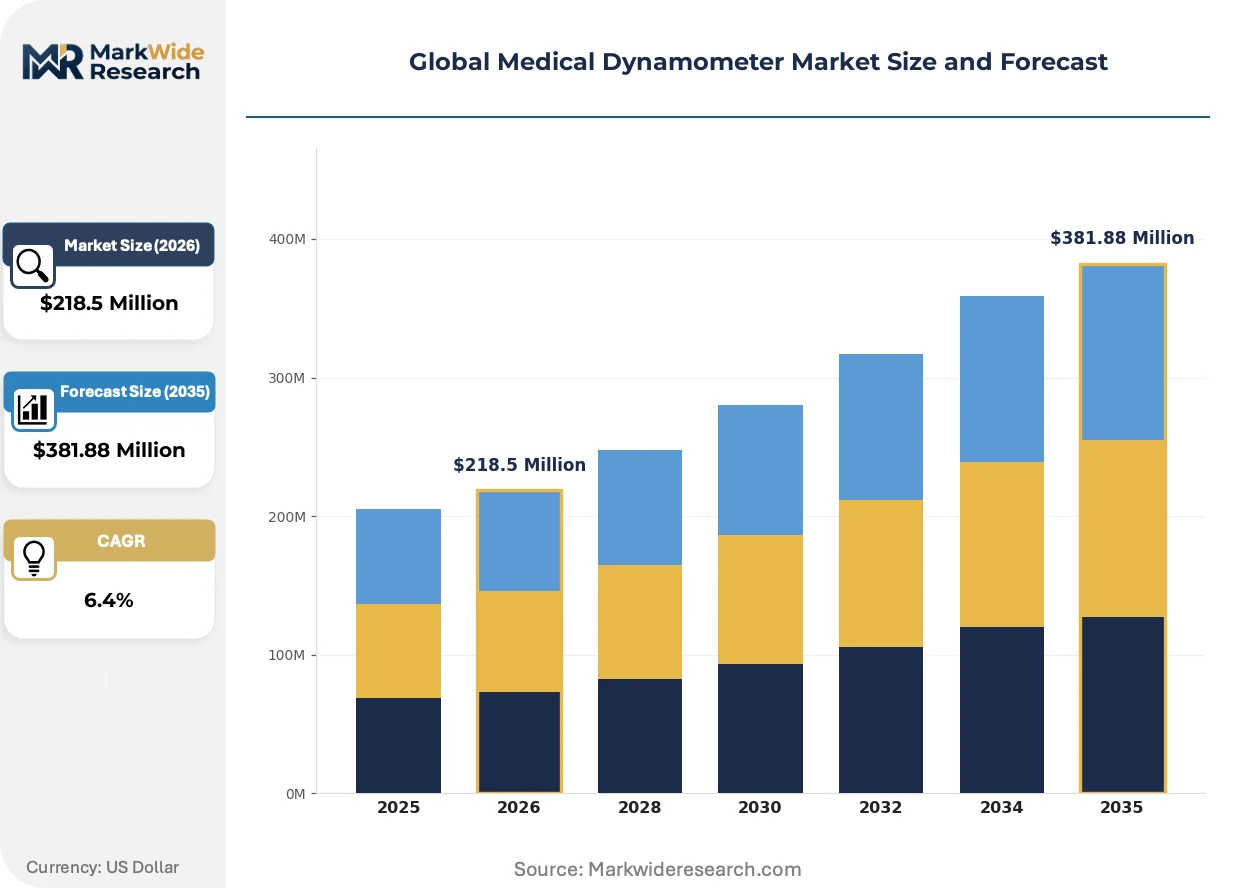
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $381.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Dynamometer, Digital Dynamometer, Mechanical Dynamometer, Pneumatic Dynamometer Application: Muscle Strength Assessment, Physical Therapy, Sports Medicine, Rehabilitation End User: Hospitals, Physiotherapy Centers, Sports Clinics, Research Institutions Technology: Load Cell, Strain Gauge, Piezoelectric Sensor, Optical Sensor |
| Companies Covered | JTECH Medical Industries, North Coast Medical, Hausmann Industries, Biodex Medical Systems, KERN & SOHN, Marsden Weighing Group, Charder Electronic, 3B Scientific, Lafayette Instrument Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Dynamometer Market Shifts & Advancements
Sensor miniaturization and wireless protocol standardization are compressing hardware differentiation and shifting competitive focus toward software analytics and calibration-service ecosystems.
MEMS-based force transducers are supplanting traditional strain-gauge assemblies in handheld grip-strength units, offering comparable precision at reduced unit cost. Outpatient rehabilitation clinics in the United States are adopting these platforms at accelerated replacement cycles. The technology is supplanting premium-tier pricing power and compressing margin pools toward software subscription and recalibration revenue streams.
FDA cybersecurity guidance for connected diagnostic devices is mandating encryption protocols and data-integrity safeguards in premarket submissions. Manufacturers must document threat-modeling and software-bill-of-materials disclosures, elevating development overhead. Wireless-enabled dynamometer platforms face the most acute compliance burden, with vendors restructuring quality-assurance functions to address emerging scrutiny.
Hospital group purchasing organizations are consolidating vendor panels and unbundling after-sales calibration contracts from hardware procurement. German and Japanese rehabilitation networks now source devices and metrology services through separate competitive tenders, fragmenting incumbent full-service relationships. This pattern is most visible in United States academic medical centers, where procurement functions have established distinct supplier qualification tracks for equipment and ongoing validation services.
Global Medical Dynamometer Market Segmentation
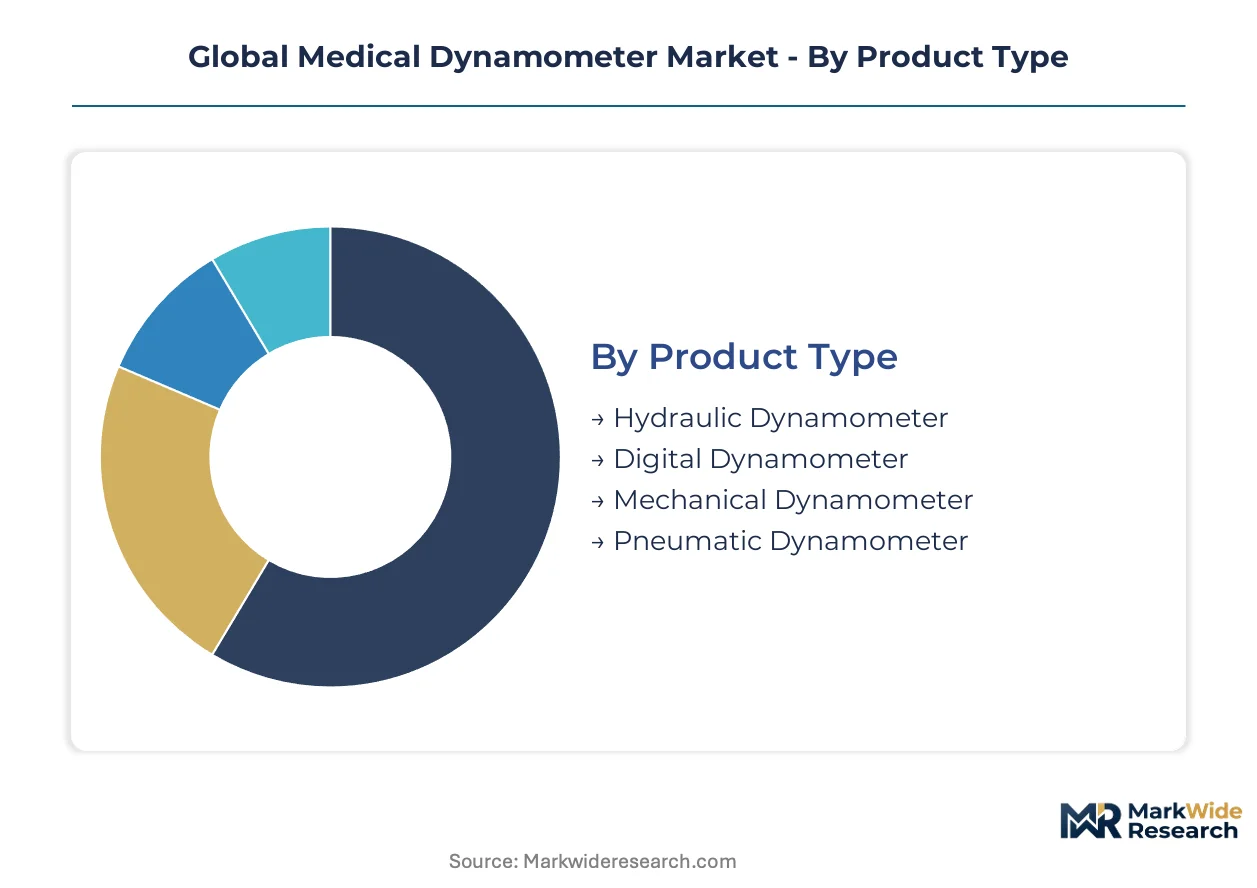
Medical dynamometer procurement patterns diverge sharply across clinical settings, with digital platforms displacing legacy systems in hospital outpatient departments while cost-sensitive physiotherapy networks retain mechanical alternatives. Understanding segment-level substitution pressures and technology migration trajectories enables vendors to align R&D investment with replacement-cycle timing.
Product Type:
Digital platforms face intensifying substitution pressure from MEMS-based alternatives in handheld grip-strength applications, while hydraulic systems confront regulatory obsolescence in markets enforcing electronic health record interoperability mandates.
- Digital Dynamometer:Bluetooth-enabled load-cell platforms resolve to 0.05-kilogram precision and transmit data directly to physiotherapy software suites. Hospital outpatient departments in the United States and rehabilitation networks across Germany and Japan are replacing legacy systems at accelerated procurement cycles driven by EHR integration requirements.
- Hydraulic Dynamometer:Fluid-pressure transduction mechanisms require no electrical calibration but generate analog output incompatible with modern telemetry protocols. These units persist in budget-constrained physiotherapy centers in India and Southeast Asia where CDSCO registration pathways for digital alternatives remain underdeveloped.
- Mechanical Dynamometer:Spring-based force measurement offers lowest unit cost but limited precision; dominant in rural clinic deployments across Latin America and Africa.
- Pneumatic Dynamometer:Compressed-air transduction enables isokinetic testing configurations; niche adoption in research laboratories studying repetitive strain injury mechanics.
Digital dynamometer platforms retain volume leadership across reimbursed healthcare systems; pneumatic configurations hold the steepest expansion curve in specialized research applications.
Application:
Margin concentration varies by clinical workflow integration depth, with muscle strength assessment commanding premium pricing through recurring calibration contracts while sports medicine applications expand through professional franchise procurement.
- Muscle Strength Assessment:Quantified grip, pinch, and lift testing protocols require ISO 17025-traceable calibration documentation for orthopedic surgical outcomes validation. German rehabilitation networks and United States academic medical centers source these systems through separate equipment and metrology service tenders, fragmenting vendor relationships.
- Sports Medicine:Objective return-to-play metrics drive demand for portable force-measurement platforms with cloud-connected analytics dashboards. North American professional athletic franchises and European football club medical departments are investing in standardized assessment protocols.
- Physical Therapy:Progress-tracking applications prioritize cost-optimized digital units with basic Bluetooth connectivity; volume concentrates in private clinic chains across Japan and South Korea.
- Rehabilitation:Post-surgical and neuromuscular recovery protocols favor connected platforms enabling remote patient monitoring reimbursement capture in United States home-based settings.
Muscle strength assessment commands the deepest margin pools through service-contract attachment; sports medicine is climbing the fastest as franchise investment professionalizes athletic medical departments.
End User:
Procurement sophistication tiers separate institutional buyers with dedicated clinical engineering functions from independent practitioners prioritizing capital efficiency.
- Hospitals:Group purchasing organizations consolidate vendor panels and unbundle calibration contracts from hardware procurement, favoring manufacturers with embedded cybersecurity architectures meeting FDA premarket scrutiny for wireless-enabled diagnostic devices.
- Physiotherapy Centers:Private rehabilitation chains in India and Brazil present white-space expansion potential for cost-optimized digital platforms certified to regional electromagnetic-compatibility standards.
- Sports Clinics:Franchise-affiliated medical departments demand API-ready platforms integrating with proprietary athlete management systems.
- Research Institutions:Piezoelectric sensor configurations for high-frequency grip-strength studies concentrate demand in biomechanics laboratories across Switzerland and the Netherlands.
Hospitals retain procurement volume leadership through replacement-cycle concentration; physiotherapy centers in emerging markets represent the steepest expansion trajectory as private rehabilitation infrastructure scales.
Technology:
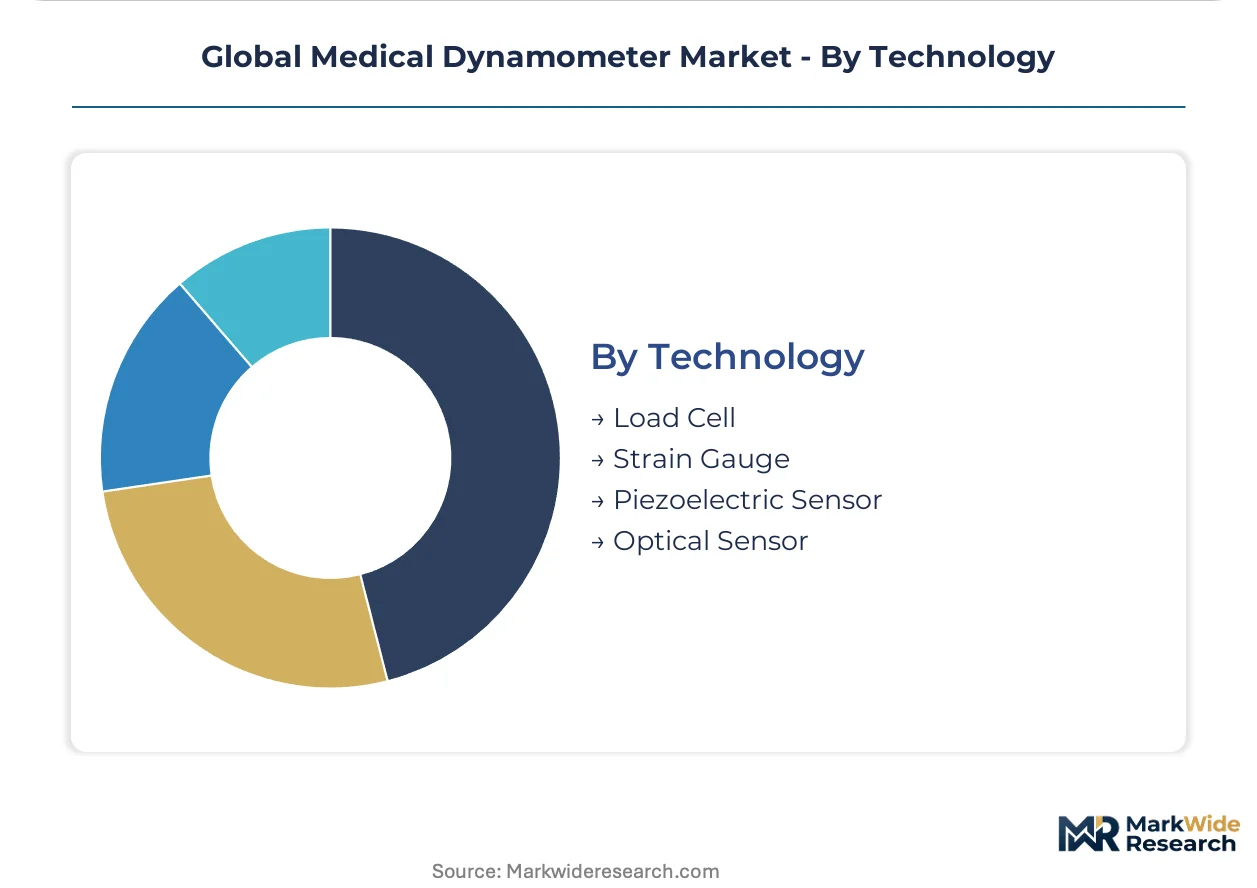
Sensor fabrication capability concentration among ISO 17025-accredited force laboratories in Germany and Switzerland creates supply vulnerability for precision-dependent segments.
- Load Cell:Resistive transduction elements deliver clinical-grade repeatability with 0.1-pound resolution standards. Biodex Medical Systems and KERN & SOHN leverage in-house calibration capabilities to sustain premium positioning across North American and European rehabilitation networks.
- Strain Gauge:Metallic foil deformation sensors enable compact handheld configurations; MEMS-based alternatives are compressing unit costs in outpatient clinic segments.
- Piezoelectric Sensor:Quartz-crystal transduction captures high-frequency force variations for research applications; cost structure constrains deployment beyond specialized laboratories.
- Optical Sensor:Fiber-Bragg-grating configurations offer electromagnetic immunity for MRI-suite deployment; nascent commercialization in academic medical center pilot programs.
Load cell technology retains volume leadership across reimbursed clinical settings; optical sensor platforms are gaining share fastest in specialized imaging-environment applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for medical dynamometers varies sharply across reimbursement environments, with German and United States hospital systems absorbing premium digital platforms while Indian physiotherapy chains prioritize cost-optimized configurations.
United States
Hospital outpatient departments are replacing legacy hydraulic systems with Bluetooth-enabled load-cell platforms to capture remote patient monitoring reimbursement codes. FDA 510(k) premarket notification requirements are elevating validation standards for wireless-enabled diagnostic devices. Academic medical centers in Massachusetts and California are unbundling equipment procurement from calibration service contracts.
Germany
Rehabilitation networks are expanding ISO 17025-accredited force laboratory partnerships to document orthopedic surgical outcomes. EU MDR technical documentation obligations for Class I measuring devices are filtering procurement toward validated manufacturers with dedicated quality-management systems. Medical technology clusters in Bavaria and Baden-Württemberg concentrate precision sensor fabrication capacity.
Japan
Private physiotherapy clinic chains are adopting MEMS-based handheld units with basic connectivity for progress-tracking workflows. METI standards harmonization with international electromagnetic-compatibility protocols is accelerating digital platform certification. Rehabilitation infrastructure investment in the Kanto and Kansai regions is driving replacement-cycle concentration.
India
CDSCO medical device registration pathways for digital alternatives remain underdeveloped, preserving mechanical dynamometer penetration in budget-constrained rural clinics. Expanding private rehabilitation chains in Maharashtra and Karnataka present white-space expansion potential for cost-optimized platforms certified to regional standards. National health mission procurement is prioritizing capital efficiency over connectivity features.
Switzerland
Biomechanics research laboratories are sustaining niche demand for piezoelectric sensor configurations in high-frequency grip-strength studies. Swissmedic conformity assessment requirements are reinforcing premium positioning for precision instrumentation. The Basel and Zurich metropolitan areas concentrate specialized force-metrology expertise for clinical-grade repeatability validation.
Global Medical Dynamometer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the medical dynamometer market, with in-house calibration capabilities separating premium-tier vendors from assembly-only OEMs. The vendor base clusters around three strategic archetypes: precision sensor fabricators with ISO 17025-accredited force laboratories, regional cost-optimized platform specialists, and diversified rehabilitation equipment conglomerates. Competitive moves center on unbundling calibration services from hardware procurement and restructuring quality-assurance functions to address FDA cybersecurity guidance for connected diagnostic devices.
Among North American rehabilitation equipment specialists, Biodex Medical Systems and Lafayette Instrument Company exemplify the premium-tier archetype through sustained positioning across hospital networks. KERN & SOHN anchors European demand through German force-metrology capabilities, while Charder Electronic occupies a position within the cost-optimized digital platform segment serving Asian physiotherapy markets.
| Leading Market Players |
|---|
| JTECH Medical Industries |
| North Coast Medical |
| Hausmann Industries |
| Biodex Medical Systems |
| KERN & SOHN |
| Marsden Weighing Group |
| Charder Electronic |
| 3B Scientific |
| Lafayette Instrument Company |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day strain-gauge procurement lead times from ISO 17025-accredited force laboratories in Germany and Switzerland concentrate upstream bargaining power among precision sensor fabricators, compressing assembly-only OEM margins while elevating premium-tier pricing for vendors with in-house calibration capabilities.
Pricing Analysis
Calibration-service revenue streams drive lifetime value across digital dynamometer platforms, with three-tier pricing structure across premium, standard, and economy levels separating vendors by ISO 17025 certification status and embedded cybersecurity architectures. Premium positioning commands sustained margins through recurring metrology contracts unbundled from hardware procurement in United States academic medical centers, while cost-optimized MEMS-based units face intensifying price erosion in Asian physiotherapy markets. Hospital group purchasing organizations exhibit lowest price sensitivity due to reimbursement capture requirements, whereas independent physiotherapy centers in India and Brazil prioritize capital efficiency over connectivity features.
Supply Chain Analysis
Rhine Valley logistics corridors and Swiss Alpine transit routes concentrate precision sensor fabrication capacity, creating single-source vulnerability for load-cell and strain-gauge transduction elements that draw from specialized metallurgy suppliers in Germany, Switzerland, and Japan. Raw material dependencies center on high-purity aluminum alloys for strain-gauge substrates, piezoelectric quartz crystals for research-grade configurations, and rare-earth elements for MEMS-based force transducers. Distribution runs through authorized metrology service networks rather than conventional medical device distributors, with hospital procurement functions increasingly sourcing hardware and validation services through separate competitive tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital platform migration in post-surgical rehabilitation protocols positions this market for early-cycle expansion, with remote patient monitoring reimbursement codes in the United States accelerating replacement cycles beyond traditional equipment depreciation schedules.
For Market Incumbents: Secure calibration-service contract retention through embedded cybersecurity architectures that preempt FDA premarket scrutiny for wireless-enabled diagnostic devices. Deepen in-house strain-gauge production to defend margin position against MEMS-based cost compression in outpatient clinic segments. Consolidate vendor panel relationships with German and Japanese rehabilitation networks before procurement functions complete unbundling of equipment and metrology tenders. For New Entrants and Emerging Players: Anchor in underpenetrated Indian physiotherapy chains where CDSCO medical device registration pathways for digital alternatives remain underdeveloped, exploiting white-space expansion potential for cost-optimized platforms certified to regional electromagnetic-compatibility standards. Target sports medicine applications through API-ready platform development that integrates with proprietary athlete management systems in North American professional franchises. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory barrier elevation through FDA 510(k) validation standards and EU MDR technical documentation obligations is filtering procurement toward established manufacturers with dedicated quality-management systems. Acquisition targets should exhibit ISO 17025-accredited force laboratory capabilities or embedded software analytics ecosystems. The signal to watch is hospital group purchasing organization vendor panel consolidation velocity in United States academic medical centers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | Validates clinical-grade repeatability for orthopedic surgical outcomes documentation in German rehabilitation networks. |
| FDA 510(k) Premarket Submission | Enables wireless-enabled diagnostic device commercialization with documented threat-modeling and encryption protocols. |
| Hospital System Partnership | Secures procurement volume through group purchasing organization vendor panel placement and unbundled service contracts. |
| Software Companion Development | Captures recurring revenue through cloud-connected analytics dashboards for sports medicine return-to-play protocols. |
| Reimbursement Strategy | Aligns platform connectivity features with remote patient monitoring codes in United States home-based rehabilitation settings. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and rehabilitation clinic directors anchored the qualitative base, cross-referenced with FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and ISO 17025 accreditation records. Secondary validation drew from customs trade data for precision sensor imports and CMS Medicare reimbursement code analyses. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure models.
Sensitivity analysis around MEMS adoption velocity, regulatory timeline compression, and calibration technician workforce demographics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application workflow depth, end-user procurement sophistication, and sensor technology tier. CAGRs derived from replacement-cycle timing analysis, reimbursement code expansion trajectories, and sports medicine franchise investment patterns.
Decision-makers should treat outputs as directional under assumptions of sustained FDA cybersecurity guidance enforcement and EU MDR conformity assessment continuity; material deviation in regulatory timeline acceleration or wireless protocol standardization fragmentation would warrant model refresh. Practitioners should keep alternative scenarios live as telehealth integration mandates and emerging market private rehabilitation infrastructure scale evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Global Pacemakers Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
US Nebulizer Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Oxygen Generator Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market