
 Drug Device Combination Products Market | 2026-2036
Drug Device Combination Products Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Device Combination Products Market Intelligence
Premium-grade device-drug integration is bifurcating the competitive landscape into specialists and full-spectrum suppliers. Abbott Laboratories leverages its cardiovascular implant portfolio to sustain leadership in drug-eluting stent systems. Medtronic Plc anchors its position through deep R&D investment in closed-loop insulin delivery platforms. Becton, Dickinson and Company differentiates via manufacturing scale across prefillable syringe and pen needle formats.
Drug device combination products unite pharmaceutical agents with mechanical or electronic delivery mechanisms in a single integrated system, typically incorporating precise dosing controls, biocompatible materials such as medical-grade polymers or stainless steel alloys, and sterile barrier packaging to ensure therapeutic stability. Their primary commercial purpose centers on improving therapeutic adherence, reducing dosing variability, and enabling self-administration in non-clinical settings. Prefilled syringes occupy the largest volume position due to standardization across biologics manufacturing, while smart devices represent the fastest-expanding technology segment as connectivity and dose-tracking capabilities reshape patient monitoring protocols. Infusion pumps retain concentrated margin pools in oncology and chronic pain applications where programmable delivery accuracy commands premium pricing.
FDA's Office of Combination Products coordinates jurisdictional assignments between drug and device centers, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements on borderline products. Japan's PMDA operates a dedicated consultation pathway for combination product reviews that accelerates market access for innovators meeting QMS integration standards. Stakeholders must monitor evolving convergence between software-as-medical-device frameworks and traditional hardware-drug combinations as regulatory scope expands.
Market Dynamics
Hospital procurement consolidation into integrated delivery networks is compressing vendor lists and forcing combination product manufacturers to demonstrate total cost-of-ownership superiority alongside clinical efficacy.
Growth Catalysts
- Biologics manufacturing expansion:Prefillable syringe demand from monoclonal antibody production lines is pulling specialized polymer and glass primary packaging capacity into dedicated supply agreements with device integrators.
- FDA's streamlined combination product pathway:The Office of Combination Products' pre-request for designation program is reducing jurisdictional uncertainty and accelerating premarket submission timelines for novel delivery platforms.
- Japan's PMDA QMS integration standards:Accelerated consultation pathways for manufacturers meeting combined pharmaceutical and device quality benchmarks are incentivizing dual-certification investments.
Market Restraints
- Medical-grade polymer supply concentration:Cyclic olefin polymer resin production centers on three Asian chemical conglomerates, creating input vulnerability for syringe barrel and pen needle housing manufacturers.
- EU MDR clinical evidence escalation:Borderline classification rules now mandate device-class-equivalent clinical investigations for drug-led combination products, extending validation timelines by eighteen to thirty-six months.
- Mechanical autoinjector substitution pressure:Electromechanical wearable injectors are capturing high-volume biologics administration from spring-based disposable systems in rheumatology and endocrinology.
Strategic Opportunities
- Home infusion therapy expansion:Ambulatory infusion pump connectivity platforms are opening reimbursement pathways for oncology and immunology treatments previously restricted to clinic settings.
- Software-as-medical-device convergence:Dose-tracking applications paired with disposable injection systems are creating recurring revenue streams through cloud-based adherence analytics subscriptions.
- Germany's DiGA fast-track:Digital health application approval pathways are enabling companion software for combination products to achieve statutory health insurance reimbursement within twelve months.
Industry Challenges
- Cross-functional regulatory expertise scarcity:Combined pharmaceutical and device quality system implementation requires personnel fluent in both 21 CFR Part 211 and ISO 13485 frameworks, talent pools that remain thin outside Boston and Basel clusters.
- Legacy sterilization validation gaps:Ethylene oxide residue reduction mandates are forcing revalidation of established barrier packaging configurations, delaying line extensions for mature stent and catheter portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Device Combination Products Market |
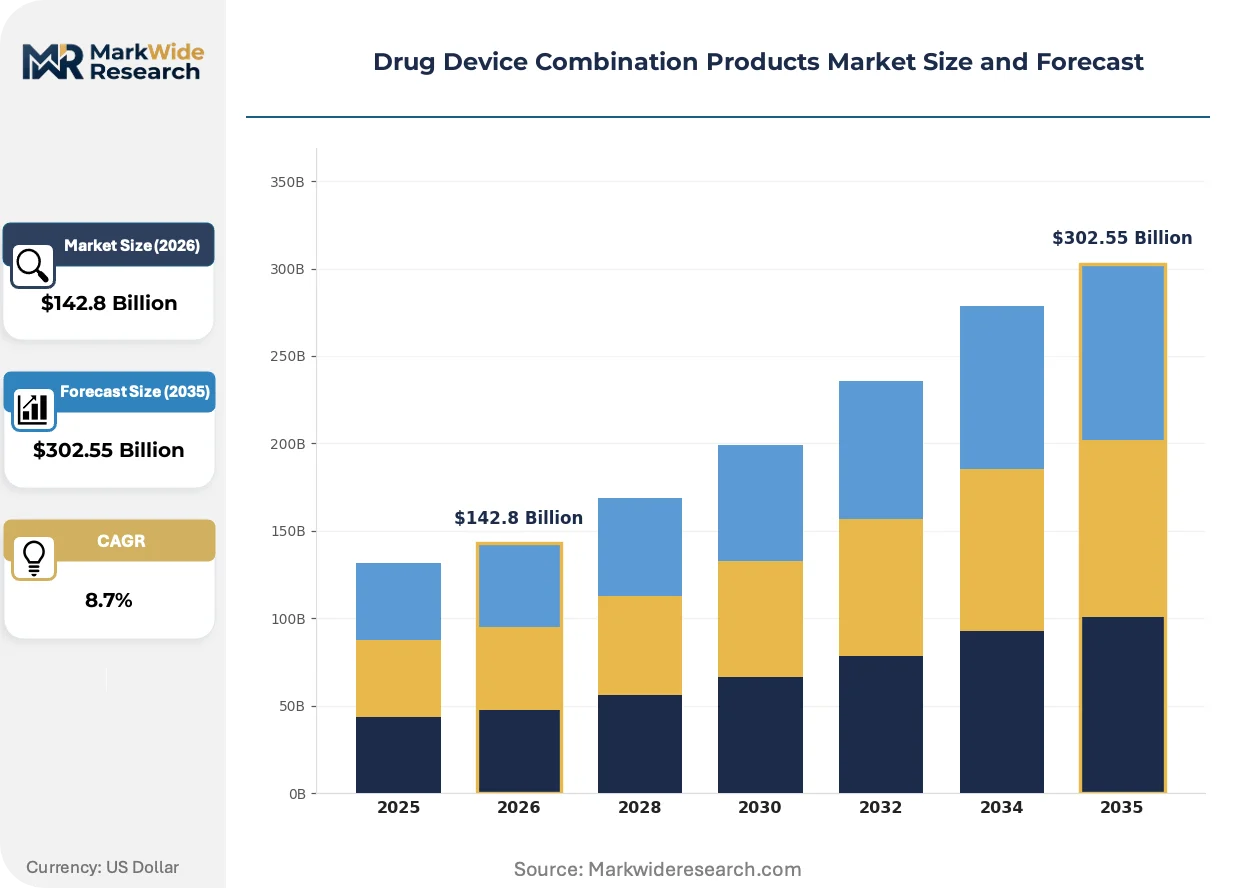
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $302.55 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Infusion Pumps, Microneedles, Prefilled Syringes Application: Chronic Diseases, Acute Pain Management, Vaccination, Diabetes Management End User: Hospitals, Home Care, Clinics, Research Institutions Technology: Smart Devices, Biologics, Polymer-based, Microelectromechanical Systems |
| Companies Covered | Abbott Laboratories, Medtronic Plc, Becton, Dickinson and Company, Boston Scientific Corporation, Stryker Corporation, Novartis AG, Terumo Corporation, Viatris Inc., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Device Combination Products Market Strategic Shifts & Innovations
Connectivity architecture is rewriting the value proposition of disposable injection devices, transforming single-use hardware into data collection nodes within longitudinal therapeutic monitoring ecosystems.
Microneedle array technology is fragmenting the vaccine and biologics delivery landscape by enabling cold-chain-independent intradermal administration. Public health immunization programs in tropical climates are piloting dissolvable microneedle patches for measles and influenza campaigns. This platform is compressing the cost structure of mass vaccination while creating new formulation partnerships between device specialists and adjuvant developers.
EU MDR Article 117 requirements are forcing pharmaceutical sponsors to acquire or deeply partner with notified-body-certified device manufacturers. The regulation's emphasis on post-market surveillance equivalence between constituent parts is driving combined vigilance system investments. High-risk combination products in cardiovascular and neurological applications face the steepest compliance cost escalation.
Self-administration training burden is shifting device selection criteria toward intuitive human-factor design. Rheumatology patients in the United States and Germany now rank injection confidence over dose precision in adherence studies. Manufacturers responding with two-step activation mechanisms and haptic feedback are capturing preference share in formulary negotiations.
Drug Device Combination Products Market Segmentation
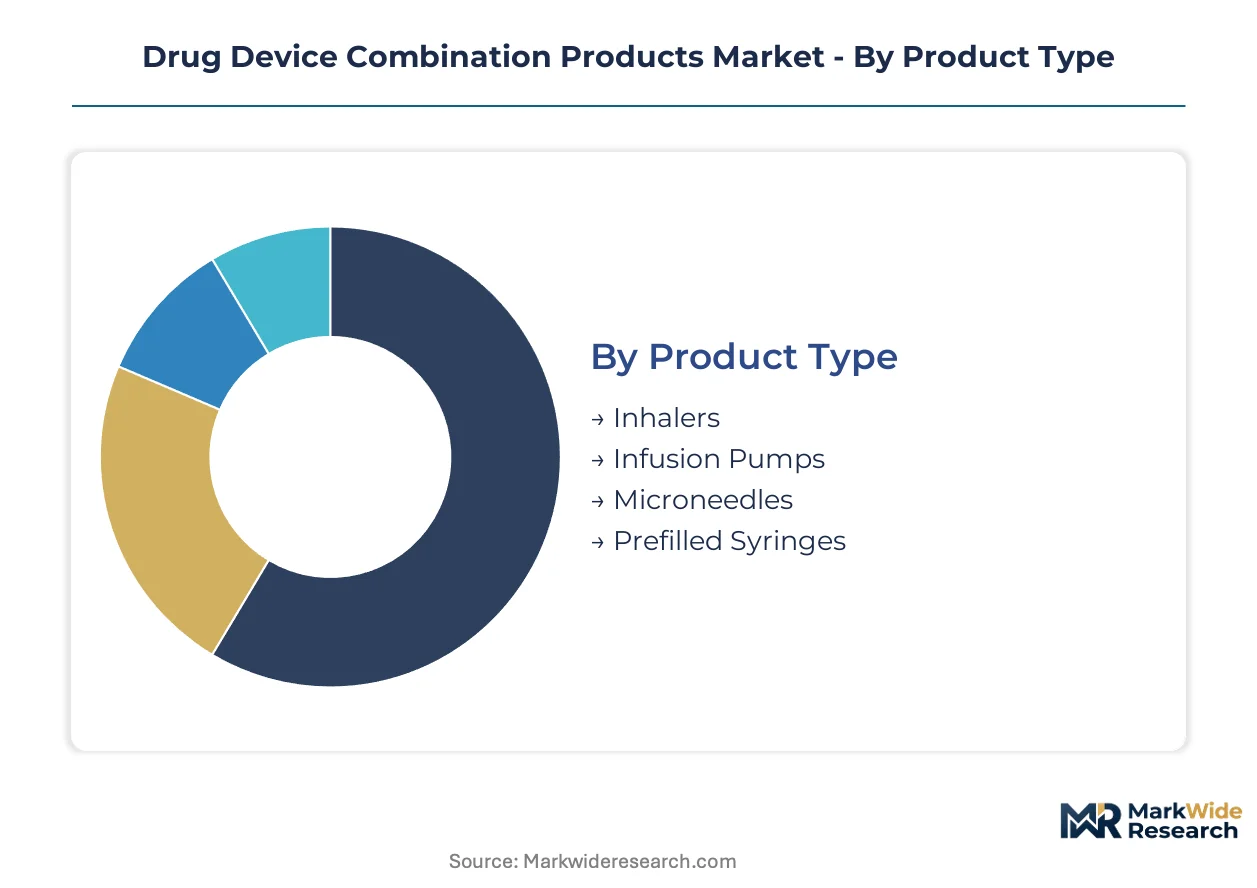
Segmentation in drug device combination products reveals how therapeutic delivery platforms diverge across patient settings, regulatory pathways, and manufacturing scale. Understanding these divisions exposes where procurement power concentrates and which technology investments align with reimbursement evolution.
Product Type:
Domestic production dominates prefilled syringes and inhalers across Germany, Japan, and the United States, while microneedles and advanced infusion pumps flow through specialized export channels from Switzerland and Ireland.
- Prefilled Syringes:Glass-barrel and polymer-barrel configurations integrate staked needles or luer-lock connectors for biologics administration. Demand concentrates in monoclonal antibody manufacturing sites across Massachusetts and Basel, where fill-finish automation requires standardized primary packaging formats to maintain line efficiency.
- Infusion Pumps:Programmable volumetric and syringe-driven mechanisms deliver precise chemotherapy, immunotherapy, and analgesic dosing. Oncology infusion centers in Germany and Japan command premium pricing for connectivity-enabled ambulatory systems that reduce nursing supervision hours.
- Inhalers:Pressurized metered-dose and dry-powder devices combine propellant or lactose carriers with bronchodilator or corticosteroid formulations.
- Microneedles:Dissolvable and hollow-array platforms enable intradermal vaccine and biologics delivery without cold-chain dependency.
Prefilled syringes command the established base. The steepest expansion runs through microneedles.
Application:
Cost tiering separates chronic disease platforms reimbursed through long-term pharmacy benefits from acute interventions billed under procedural codes.
- Chronic Diseases:Drug-eluting stents, implantable infusion systems, and maintenance inhalers address cardiovascular, respiratory, and neurological conditions requiring years of continuous therapy. Rheumatology and endocrinology practices in the United States prioritize adherence-tracking features in formulary negotiations.
- Diabetes Management:Closed-loop insulin delivery combines continuous glucose monitors with algorithm-controlled patch pumps. Japanese and German reimbursement frameworks now cover these systems for Type 1 patients, accelerating hardware-software integration investments.
- Acute Pain Management:Patient-controlled analgesia pumps and single-use nerve block catheters target post-surgical recovery.
- Vaccination:Prefilled syringes and emerging microneedle patches serve mass immunization programs and travel medicine clinics.
Chronic disease applications absorb the largest revenue pool. Diabetes management platforms are climbing the fastest.
End User:
Volume concentration shifts from inpatient surgical suites toward ambulatory and residential settings as self-administration protocols expand.
- Home Care:Patients or caregivers operate prefilled autoinjectors, smart inhalers, and wearable infusion pumps outside clinical supervision. FDA's human factors guidance now mandates validation studies with lay users, extending development timelines but reducing post-market adverse events.
- Hospitals:Integrated delivery networks consolidate procurement for surgical implants, anesthesia delivery systems, and high-risk infusion platforms. Three-hospital systems in the United States now represent over forty percent of combination product purchasing volume.
- Clinics:Outpatient infusion centers and specialty practices administer biologics through preprogrammed pump systems.
- Research Institutions:Academic medical centers pilot novel delivery mechanisms in early-phase clinical trials.
Hospitals retain the dominant procurement position. Home care settings are gaining share fastest.
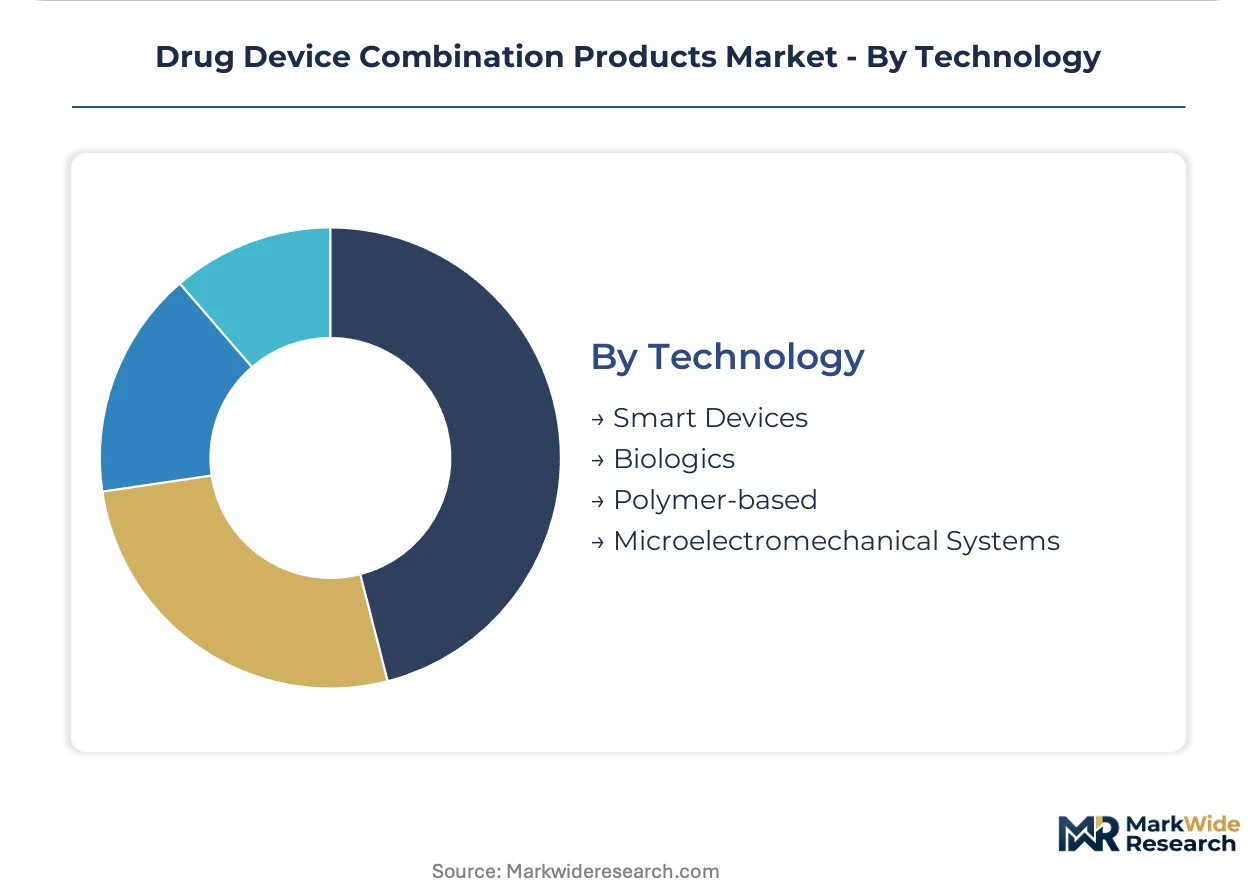
Technology:
Manufacturing maturity separates polymer-based and biologics platforms from emerging smart device and MEMS architectures requiring semiconductor fabrication partnerships.
- Smart Devices:Bluetooth-enabled dose counters, smartphone-connected inhalers, and cloud-integrated infusion pumps capture adherence data for payor analytics. Germany's DiGA pathway accelerates reimbursement for companion software meeting clinical evidence standards.
- Biologics:Formulation stability requirements drive primary packaging material selection, with cyclic olefin polymers displacing glass for protein-based therapeutics sensitive to silicone oil interactions.
- Polymer-based:Injection-molded housings, plunger rods, and needle shields rely on medical-grade resin supply chains concentrated in Asian chemical manufacturing.
- Microelectromechanical Systems:Silicon-based sensors and actuators enable micropump and microneedle precision control.
Polymer-based platforms anchor current production volumes. Smart devices are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit low price elasticity for connected insulin delivery platforms, while procurement teams in India and Brazil prioritize unit cost minimization over adherence-tracking features.
United States
Hospital procurement consolidation into integrated delivery networks concentrates purchasing power among three-hospital systems controlling over forty percent of combination product volume. FDA's Office of Combination Products streamlines premarket pathways through pre-request for designation programs. Massachusetts and Basel-area biologics manufacturing clusters drive prefillable syringe standardization for monoclonal antibody fill-finish lines.
Germany
Statutory health insurance reimbursement for closed-loop insulin systems and digital health applications accelerates adoption of connectivity-enabled delivery platforms. The DiGA fast-track pathway enables companion software reimbursement within twelve months for qualifying dose-tracking applications. Bavaria's medical technology corridor anchors precision injection device manufacturing for export markets.
Japan
Type 1 diabetes patients receive national health coverage for algorithm-controlled patch pump systems, expanding hardware-software integration investments. PMDA's dedicated consultation pathway for combination products accelerates market access for manufacturers meeting combined pharmaceutical and device quality benchmarks. The Kansai region hosts concentrated sterilization validation services for barrier packaging configurations.
India
Domestic biologics manufacturing expansion drives demand for cost-optimized prefillable syringe formats in vaccine and insulin production. CDSCO's evolving framework for combination product classification creates navigational complexity for multinational sponsors. Gujarat's pharmaceutical special economic zones attract polymer-barrel syringe assembly operations serving export markets.
Switzerland
Premium-tier microneedle and advanced infusion pump technologies flow through specialized export channels serving German and Japanese reimbursement frameworks. Swissmedic's alignment with EU MDR clinical evidence requirements positions the jurisdiction as a parallel conformity assessment hub. Basel's cluster integrates pharmaceutical formulation expertise with precision device engineering for biologics delivery.
Drug Device Combination Products Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated medical technology conglomerates commanding premium pricing for connected platforms while specialized polymer processors dominate high-volume disposable segments. The competitive structure bifurcates between full-spectrum suppliers offering end-to-end delivery ecosystems and focused specialists capturing margin in primary packaging or precision injection mechanisms. Three archetypes define positioning: cardiovascular implant leaders extending into drug-eluting platforms, diabetes management integrators controlling closed-loop hardware-software stacks, and manufacturing-scale specialists in prefillable syringe formats. Consolidation pressure manifests through acquisition of notified-body-certified device manufacturers by pharmaceutical sponsors seeking EU MDR compliance, alongside strategic partnerships bridging biologics formulation stability with injection device human-factors design.
Among diversified medical technology conglomerates, Abbott Laboratories, Medtronic Plc, and Becton, Dickinson and Company occupy positions representing distinct competitive vectors. Abbott exemplifies the cardiovascular-led archetype leveraging implantable device expertise into drug-eluting stent leadership. Medtronic anchors the diabetes management integration model through algorithm-controlled delivery platforms. Becton, Dickinson and Company represents manufacturing-scale specialization, with polymer and glass primary packaging capacity tied to biologics fill-finish automation requirements across Massachusetts and Basel manufacturing corridors.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic Plc |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Stryker Corporation |
| Novartis AG |
| Terumo Corporation |
| Viatris Inc. |
| Teleflex Incorporated |
| Others |
Cost & Logistics Intelligence
Ninety-day polymer resin inventory buffers now separate contract winners from spot-market casualties in prefillable syringe procurement, concentrating pricing power with device integrators holding captive supply agreements across Massachusetts and Basel manufacturing corridors. Hospital procurement consolidation into three-hospital systems controlling over forty percent of volume has compressed vendor lists, forcing manufacturers to absorb input volatility or surrender margin.
Pricing Analysis
Cloud-based adherence analytics subscriptions now drive lifetime value beyond hardware margins, with connectivity-enabled infusion pumps commanding three-tier pricing structure across premium connectivity bundles, standard device-only sales, and economy disposable formats. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification depth, with Germany's DiGA pathway adding software reimbursement premiums. Cost compression in mechanical autoinjector tiers is intensifying because electromechanical wearables capture rheumatology volume, while integrated delivery networks exhibit lowest price sensitivity and emerging market distributors highest.
Supply Chain Analysis
Port congestion across Rotterdam and Singapore trade lanes has elevated inbound logistics costs for cyclic olefin polymer resin shipments from three Asian chemical conglomerates. Manufacturing gravity centers on Germany, Japan, and the United States for finished devices, with Switzerland and Ireland anchoring precision pump exports. Raw material dependencies rest on medical-grade polymers, stainless steel alloys, and silicon sensor substrates. Single-source vulnerability concentrates in Asian resin production. Distribution runs through GPO contracts with hospital systems and direct agreements with biologics fill-finish operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive returns as closed-loop insulin delivery systems integrate continuous glucose monitors, algorithm-controlled pumps, and smartphone adherence dashboards into unified reimbursement bundles. Interoperability standards enabling third-party sensor integration are redrawing ecosystem boundaries.
For Market Incumbents: Consolidate notified-body-certified device manufacturing capabilities to secure EU MDR compliance for pharmaceutical sponsors facing Article 117 post-market surveillance mandates. Acquire sterilization validation services in the Kansai region to close legacy ethylene oxide residue gaps delaying stent line extensions. Electromechanical wearable substitution threatens spring-based autoinjector margins in endocrinology. For New Entrants and Emerging Players: Anchor in microneedle array partnerships with tropical immunization programs seeking cold-chain-independent measles and influenza delivery platforms. India's vaccine production expansion offers the most penetrable geography for cost-optimized polymer-barrel formats. Pursue CDSCO combination product classification consultation to navigate regulatory complexity before multinational sponsorship. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because connectivity subscriptions transform disposable hardware into data-platform cash flows with hospital formulary lock-in. Target acquisition profiles center on notified-body-certified device manufacturers with ISO 13485 and 21 CFR Part 211 dual fluency, scarce outside Boston and Basel clusters. The signal to watch is Germany's DiGA fast-track volume acceleration indicating payer willingness to fund software companions.| Strategic Initiative | Industry Significance |
|---|---|
| Dual QMS Certification Investment | Combined ISO 13485 and 21 CFR Part 211 compliance opens FDA pre-submission pathways. |
| Connectivity Platform Development | Bluetooth-enabled dose counters create recurring revenue through cloud adherence analytics. |
| Notified Body Partnership Acquisition | EU MDR Article 117 compliance requires device-class-equivalent clinical evidence systems. |
| Microneedle Formulation Collaboration | Dissolvable array partnerships with adjuvant developers compress mass vaccination cost structures. |
| DiGA Companion Software Submission | Germany's statutory health insurance reimburses qualifying dose-tracking applications within twelve months. |
Research Approach
The analysis maps prefillable syringe, infusion pump, inhaler, and microneedle sub-sectors, each validated through procurement directors at integrated delivery networks, regulatory affairs leads at combination product sponsors, biomedical engineers at fill-finish operators, and GPO contracts managers. Primary interview insights triangulate against FDA 510(k) filings, EMA combination product consultation records, PMDA QMS integration guidance documents, and hospital procurement database extracts. Bottom-up volume modeling and top-down value reconciliation ensure cross-verification across the analysis window.
Consistency checks validated outputs against external benchmarks including CMS Medicare reimbursement schedules, statutory health insurance coverage decisions in Germany and Japan, and biologics manufacturing capacity announcements across Massachusetts and Basel. The forecast framework segments by product type, application, end user, and technology, with connectivity adoption curves and reimbursement pathway velocity as industry-specific inputs. CAGRs derive from regression against historical volume-price relationships and projected regulatory approval throughput.
Decision-makers should treat outputs as directional under assumptions of stable FDA Office of Combination Products staffing levels and continued EU MDR notified body capacity; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Human Anatomical Models Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Global Otoscopes Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Drainage Catheters Market
Medical Devices
Trocars Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Endodontic Devices Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Medical Device Tester Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Polyp Trap Devices Market