
 Ventilator-Associated Pneumonia (VAP) Market | 2026-2036
Ventilator-Associated Pneumonia (VAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilator-Associated Pneumonia (VAP) Market Analytics
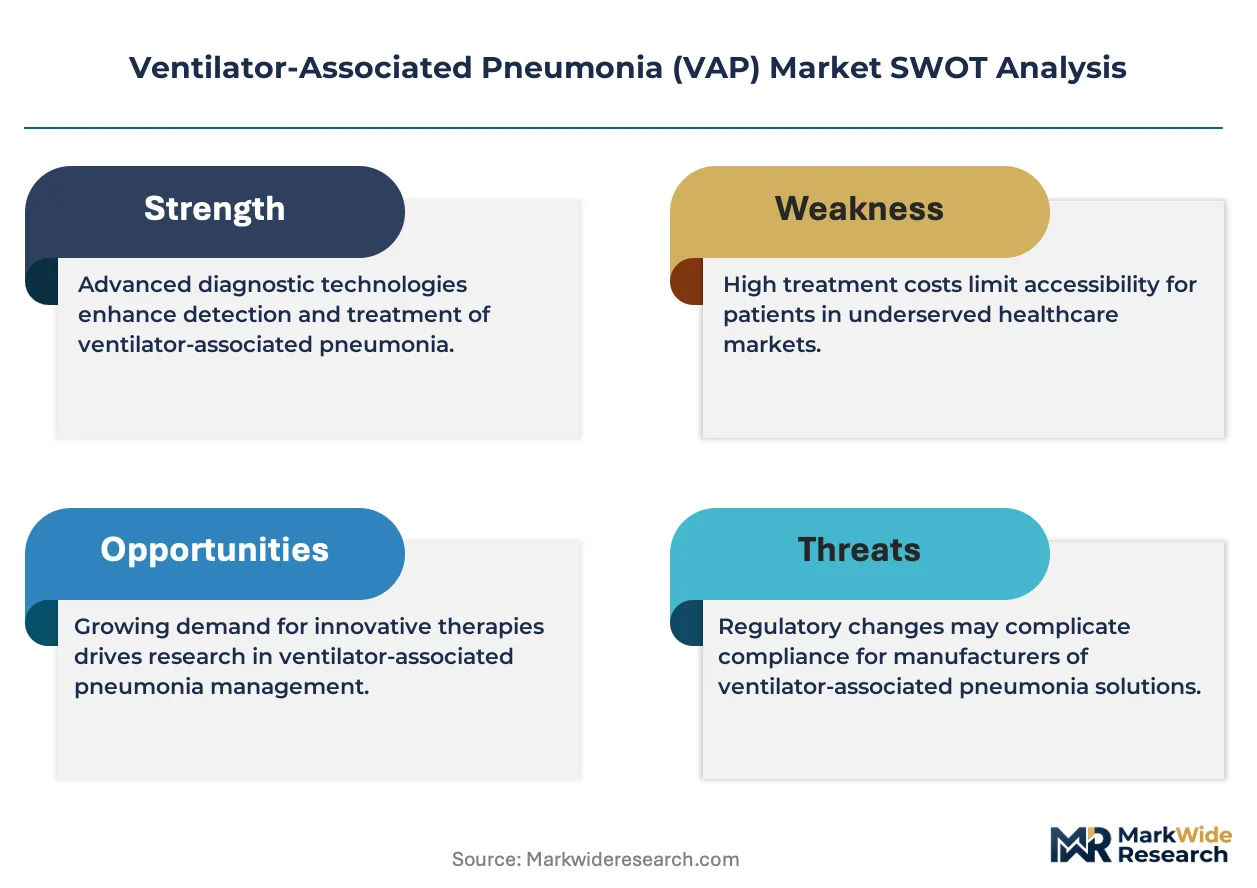
Critical care nursing shortages are reorganizing how hospitals deploy VAP prevention bundles, forcing device manufacturers to simplify training workflows. Merck & Co. leverages its antimicrobial portfolio to anchor hospital formulary relationships across North American health systems. AstraZeneca competes through sustained R&D investment in novel inhaled antibiotic formulations. GE HealthCare dominates imaging-integrated ventilator platforms that enable real-time lung monitoring.
Ventilator-Associated Pneumonia denotes lower respiratory tract infection developing after endotracheal intubation, typically diagnosed by quantitative culture thresholds exceeding 10⁴ colony-forming units per milliliter alongside radiographic infiltrates. Its primary clinical purpose is to guide antimicrobial stewardship and reduce mechanical ventilation duration, thereby lowering ICU mortality and length-of-stay costs. Endotracheal tubes with subglottic suction ports command premium positioning as the leading product category, while biofeedback systems represent the fastest-growing technology segment due to algorithm-driven weaning protocols. Intensive care units concentrate the bulk of procurement volume, though long-term care facilities are emerging as a structurally underpenetrated channel with distinct reimbursement constraints.
The FDA enforces 510(k) clearance pathways for modified endotracheal devices, while the EU MDR demands clinical performance studies for suction-enabled airway products, elevating compliance costs for market access. ISO 18562 biocompatibility evaluation for breathing gas pathways further constrains material selection and supplier qualification. Stakeholders must monitor how CMS hospital-acquired condition penalty adjustments and Joint Commission surveillance standards recalibrate the business case for preventive device investment against pharmacological prophylaxis.
Market Dynamics
ICU nursing shortages are compressing device training windows, forcing manufacturers to engineer single-setup workflows that eliminate multi-step calibration sequences previously handled by respiratory therapists.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter performance study requirements for suction-enabled airway products are accelerating hospital procurement of validated devices over unproven alternatives.
- Subglottic secretion drainage:Endotracheal tubes with integrated suction ports are displacing standard tubes in tertiary ICUs seeking measurable VAP rate reductions.
- Japan's aging ICU population:Metropolitan Tokyo hospitals are expanding ventilator capacity, creating concentrated demand for infection prevention infrastructure.
Market Restraints
- Silicone polymer supply concentration:Medical-grade elastomer production clusters in German and Japanese chemical corridors, exposing device makers to input bottlenecks.
- FDA 510(k) pathway friction:Modified endotracheal designs face extended review timelines when predicate device equivalence is contested.
- Pharmacological prophylaxis substitution:Inhaled antibiotic protocols compete for hospital formulary slots against mechanical prevention devices.
Strategic Opportunities
- Long-term acute care facilities:Post-ICU ventilator units in the United States remain structurally underpenetrated for bundled prevention protocols.
- Algorithm-driven weaning systems:Biofeedback platforms that integrate respiratory mechanics data with automated sedation adjustment represent emergent white space.
- ISO 18562 biocompatibility certification:Early compliance with breathing gas pathway standards creates differentiation against late-adopting competitors.
Industry Challenges
- Respiratory therapy certification gaps:Specialized training for subglottic suction device management outpaces accredited education program expansion.
- Legacy ventilator integration:New monitoring peripherals face interoperability friction with installed base platforms from dominant equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilator-Associated Pneumonia (VAP) Market |
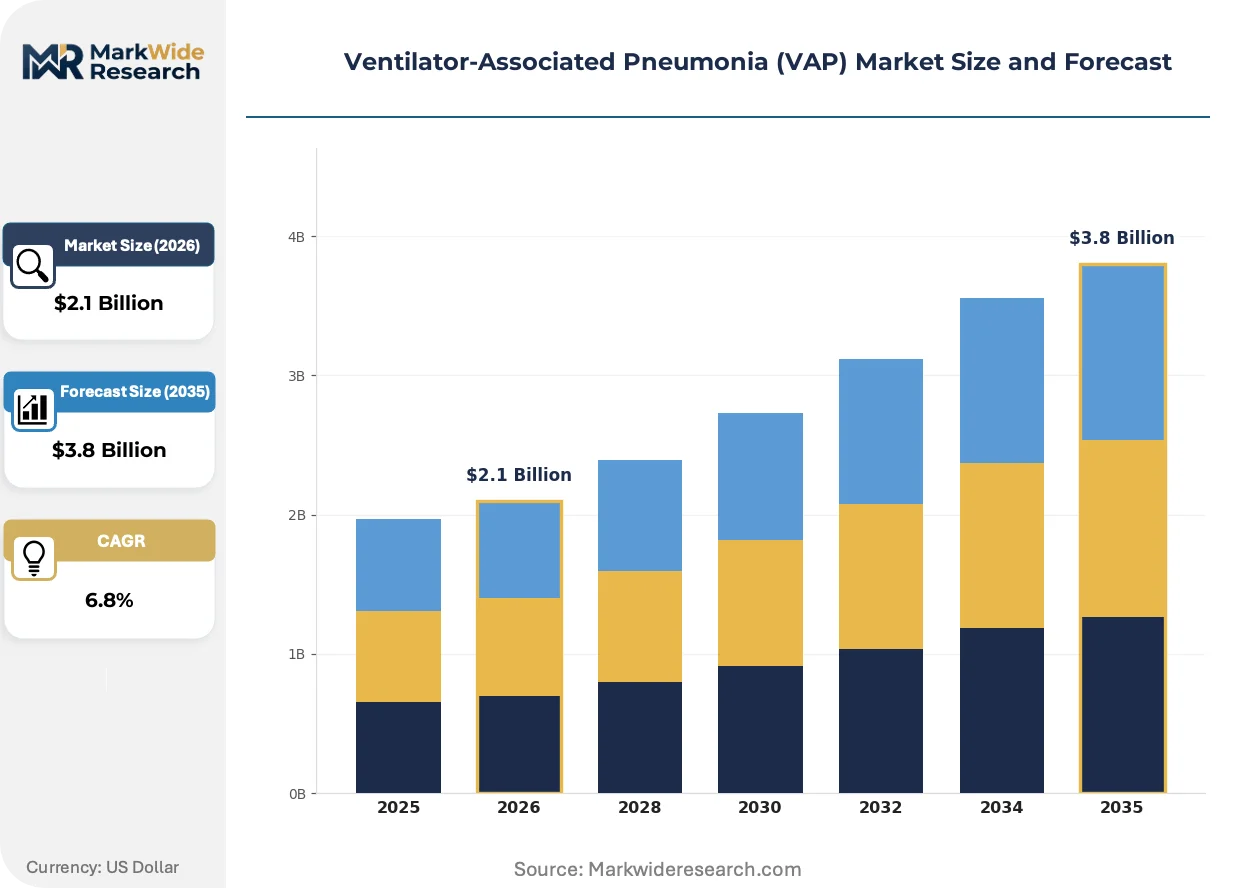
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Ventilator Systems, Monitoring Equipment, Suction Devices End User: Intensive Care Units, Emergency Departments, Home Care Settings, Long-Term Care Facilities Delivery Mode: Inhalation, Intravenous, Nebulization, Oral Technology: Mechanical Ventilation, Non-Invasive Ventilation, Biofeedback Systems, Automated Management |
| Companies Covered | Merck & Co., GE HealthCare, AstraZeneca, Shionogi & Co., Koninklijke Philips, Bayer AG, Medtronic, Wockhardt, Aridis Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilator-Associated Pneumonia (VAP) Market Evolving Landscape
Device architecture is converging around closed-loop automation, with sensor miniaturization and machine learning inference compressing the gap between physiological signal detection and clinical intervention.
Microelectromechanical pressure sensors embedded in endotracheal tube cuffs are miniaturizing real-time subglottic pressure monitoring, enabling automated secretion clearance without manual nursing intervention. Tertiary ICUs in Germany and the United States are piloting these systems to reduce aspiration events. The technology is miniaturizing the footprint of preventive care, collapsing multi-step protocols into continuous automated loops that require minimal staff attention.
EU MDR's post-market surveillance requirements for Class IIa respiratory devices are extending clinical follow-up obligations from two to five years, elevating registry maintenance costs for manufacturers. Device sponsors must now submit annual safety reports rather than periodic updates. Suction-enabled airway product categories face the steepest compliance burden, with notified bodies in Germany and the Netherlands imposing additional biocompatibility testing conditions.
Hospital purchasing committees are consolidating vendor relationships into single-source contracts spanning ventilators, consumables, and monitoring platforms. Integrated system procurement is displacing standalone device selection in United States health systems seeking standardized training protocols. This concentration is most visible in multi-hospital IDNs in Texas and Florida, where supply chain rationalization overrides product-level feature differentiation.
Ventilator-Associated Pneumonia (VAP) Market Segmentation
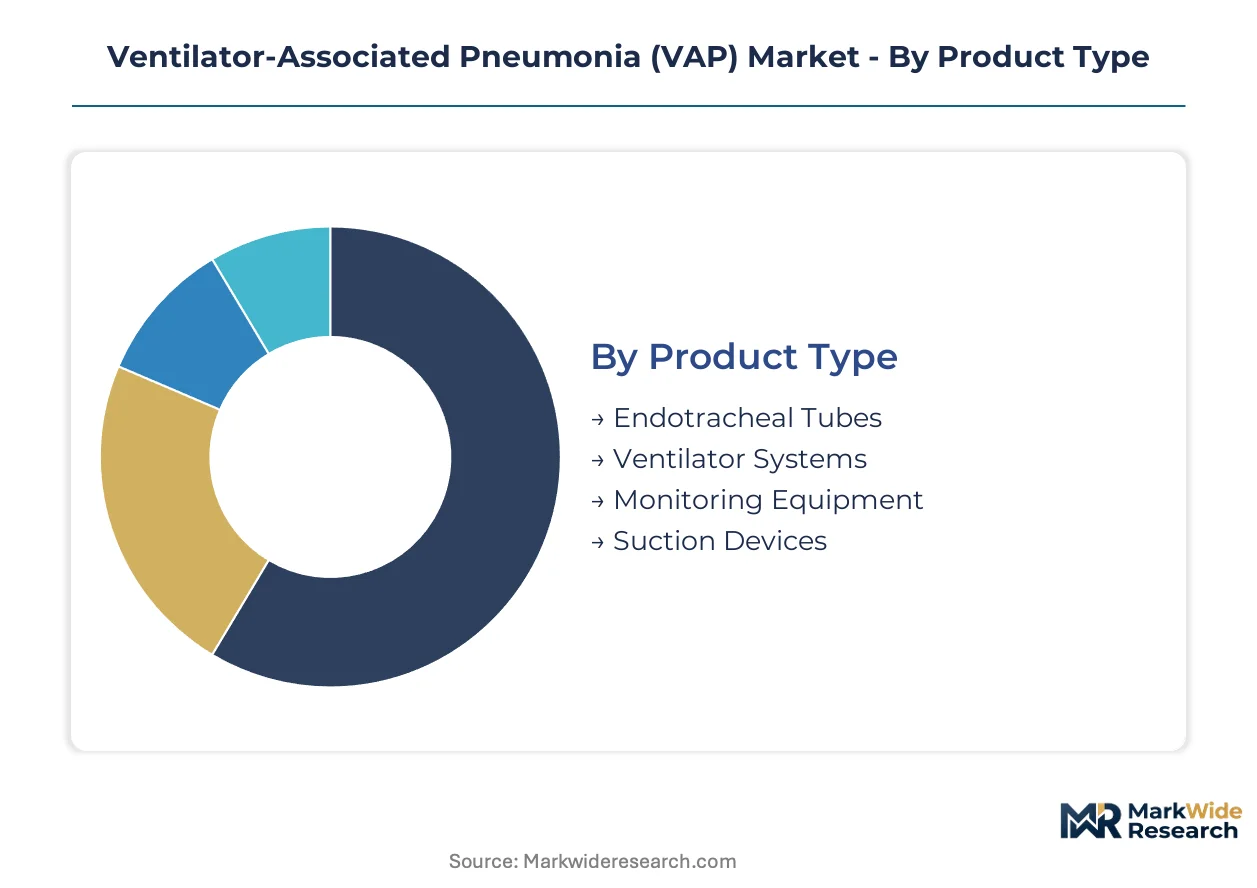
VAP prevention markets fragment across device physics, care settings, and automation intensity. Procurement committees weight bundled contracts against standalone performance, reshaping how manufacturers position across these axes.
Product Type:
Endotracheal tubes and suction devices concentrate production in German and Japanese chemical corridors, while ventilator systems and monitoring equipment draw more dispersed electronics supply chains from Taiwan and South Korea.
- Endotracheal Tubes:Polyvinyl chloride and silicone elastomer constructions with subglottic suction lumens dominate tertiary ICU specifications. Demand clusters in United States metropolitan hospital systems where CMS hospital-acquired condition penalties sharpen formulary scrutiny.
- Ventilator Systems:Microprocessor-controlled platforms with integrated graphics displays enable lung-protective ventilation protocols. Japanese and German manufacturers anchor export volume to Southeast Asian markets expanding ICU infrastructure.
- Monitoring Equipment:Capnography and respiratory mechanics sensors track ventilation adequacy and weaning readiness.
- Suction Devices:Closed-circuit aspirators reduce cross-contamination during secretion clearance.
Endotracheal tubes hold the largest share; momentum sits with suction-integrated variants.
End User:
Cost tiers separate capital-intensive tertiary hospitals from reimbursement-constrained post-acute facilities, with emergency departments occupying a middle tier of episodic high-acuity investment.
- Intensive Care Units:Tertiary medical centers with 24-hour respiratory therapy coverage deploy full prevention bundles including subglottic drainage and automated weaning protocols. United States academic medical centers drive validation studies for novel device categories.
- Long-Term Care Facilities:Post-ICU ventilator units manage prolonged mechanical ventilation with thinner clinical staffing. Texas and Florida health systems experiment with bundled remote monitoring to extend prevention protocols into these settings.
- Emergency Departments:Rapid-sequence intubation workflows prioritize speed over prevention feature deployment.
- Home Care Settings:Portable ventilator populations remain underpenetrated for institutional-grade infection prevention.
Intensive Care Units command premium pricing; Long-Term Care Facilities represent the steepest expansion trajectory.
Delivery Mode:
Volume concentration favors inhalation and intravenous routes where pharmaceutical prophylaxis competes directly with mechanical prevention devices for hospital formulary slots.
- Inhalation:Aerosolized antibiotic deposition targets distal airways with limited systemic absorption. Cleveland Clinic and Mayo Clinic protocols influence United States adoption patterns for adjunctive prophylaxis.
- Intravenous:Systemic antimicrobial prophylaxis remains standard for high-risk surgical populations despite resistance selection concerns.
- Nebulization:Mesh and jet nebulizer technologies optimize particle size distribution for alveolar penetration.
- Oral:Selective digestive decontamination regimens persist in European ICU practice despite variable guideline endorsement.
Inhalation delivery holds the largest share; momentum sits with nebulization technology improvements.
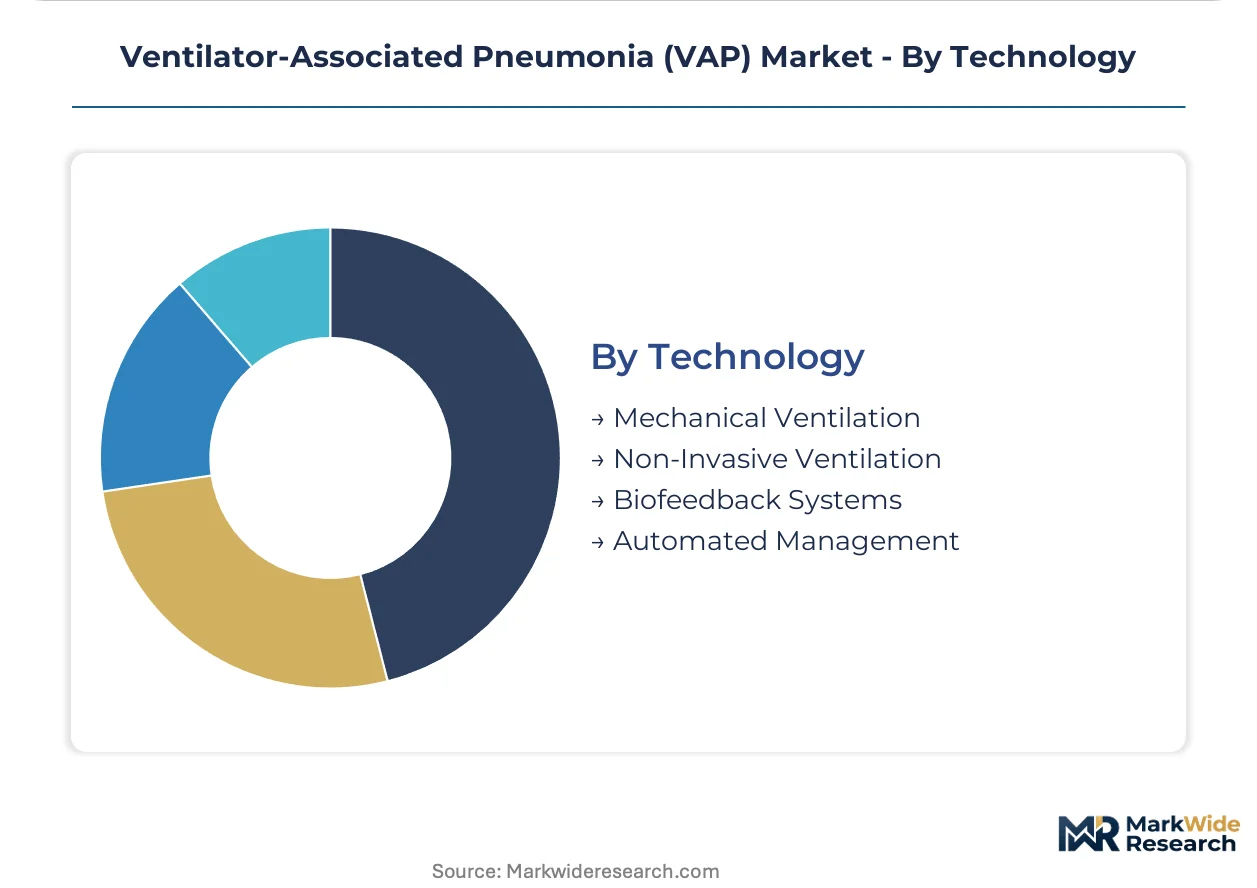
Technology:
Application intensity separates continuous-use mechanical platforms from intermittent monitoring and automation layers that retrofit existing installed bases.
- Mechanical Ventilation:Positive-pressure systems with adjustable inspiratory-to-expiratory ratios remain the foundational platform. German engineering clusters in Hamburg and Munich supply precision valve technology to global OEMs.
- Biofeedback Systems:Algorithm-driven weaning protocols integrate respiratory mechanics, gas exchange, and sedation depth data. Charité – Universitätsmedizin Berlin and Massachusetts General Hospital pilot closed-loop automation reducing nursing documentation burden.
- Non-Invasive Ventilation:Mask interfaces for acute hypoxemic failure reduce intubation rates but carry distinct aspiration risk profiles.
- Automated Management:Cuff pressure controllers and secretion clearance timers reduce protocol compliance variance.
Mechanical Ventilation holds the largest share; Biofeedback Systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospitals extract 40% pricing premiums for MDR-validated suction-enabled airway products compared to standard tubes in Indian procurement. This asymmetry reflects divergent regulatory enforcement and reimbursement depth across acute care systems.
United States
Academic medical centers in Boston and Houston drive validation studies for automated cuff pressure controllers. CMS hospital-acquired condition penalties sharpen formulary scrutiny for mechanical prevention devices. The Texas Medical Center cluster anchors multi-hospital IDN procurement standardization across ventilator platforms.
Germany
Charité – Universitätsmedizin Berlin pilots closed-loop biofeedback weaning systems reducing nursing documentation burden. EU MDR notified bodies in Hamburg impose additional biocompatibility testing conditions on Class IIa respiratory devices. Precision valve engineering clusters in Munich supply global OEMs with adjustable inspiratory-to-expiratory ratio components.
Japan
Metropolitan Tokyo hospitals expand ventilator capacity for aging ICU populations with prolonged ventilation needs. PMDA post-market surveillance requirements align with EU MDR five-year clinical follow-up obligations. Osaka-based manufacturers concentrate export volume for Southeast Asian markets building ICU infrastructure.
United Kingdom
NHS England integrated care systems consolidate vendor relationships into single-source contracts spanning consumables and monitoring platforms. MHRA recognition of EU MDR certificates streamlines market access for German-engineered suction devices. London teaching hospitals influence adoption patterns for nebulized antibiotic adjunctive prophylaxis.
India
Private tertiary hospitals in Mumbai and Delhi-NCR expand ICU bed capacity without proportional respiratory therapy staffing growth. CDSCO medical device rules create registration friction for imported suction-enabled endotracheal tubes. Domestic manufacturers in Gujarat and Karnataka target price-sensitive post-acute ventilator units with simplified prevention bundles.
Ventilator-Associated Pneumonia (VAP) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the VAP prevention ecosystem. The market structures around three tiers: diversified conglomerates with hospital system anchoring power, pharmaceutical specialists with antimicrobial formulary relationships, and device engineering houses with ICU workflow integration. Consolidation pressure concentrates procurement influence among integrated delivery networks seeking standardized training protocols. Dominant competitive moves include vertical integration of monitoring peripherals with ventilator platforms and strategic partnerships between device makers and hospital formulary committees.
Within the diversified conglomerate tier, GE HealthCare and Koninklijke Philips occupy positions anchoring imaging-integrated ventilator platforms with real-time lung monitoring capabilities. Among pharmaceutical specialists, Merck & Co. and AstraZeneca exemplify contrasting R&D strategies—one leveraging existing antimicrobial portfolios for hospital relationship depth, the other pursuing novel inhaled antibiotic formulations. Shionogi & Co. represents the mid-cap specialist archetype with concentrated geographic presence in Japanese and select Asian markets. Bayer AG and Medtronic sit within hybrid positioning, spanning pharmaceutical prophylaxis and device-based prevention modalities without full integration of either stack.
| Leading Market Players |
|---|
| Merck & Co. |
| GE HealthCare |
| AstraZeneca |
| Shionogi & Co. |
| Koninklijke Philips |
| Bayer AG |
| Medtronic |
| Wockhardt |
| Aridis Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German silicone polymer plants runs above 85%, concentrating medical-grade elastomer supply in Hamburg and Munich chemical corridors and establishing price floors that device makers cannot negotiate below without sourcing from unvalidated Asian suppliers. This scale concentration creates asymmetric pricing power where FDA-validated manufacturers absorb premium input costs while post-acute facilities in India and Southeast Asia face procurement exclusion.
Pricing Analysis
Configured-to-order pricing for subglottic suction endotracheal tubes commands 35-50% premiums over standard PVC tubes in United States academic medical centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU MDR certification status and ISO 18562 biocompatibility validation. Pricing pressure stems from CMS hospital-acquired condition penalty adjustments that compress capital equipment budgets. Post-acute long-term care facilities exhibit highest price sensitivity; tertiary ICUs with GPO-negotiated contracts show lowest.
Supply Chain Analysis
Inventory lead times for medical-grade silicone elastomers stretch 16-24 weeks, forcing device manufacturers to hold 90-day safety stock against German and Japanese chemical corridor disruptions. Raw material dependencies center on silicone polymers, precision-molded PVC compounds, and microelectromechanical pressure sensors. Single-source vulnerability concentrates in Hamburg-based specialty chemical suppliers serving Class IIa respiratory device categories. Distribution runs through hospital GPOs and integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among United States integrated delivery networks concentrates procurement influence among 15-20 multi-hospital systems, shifting bargaining power toward standardized bundled contracts and away from product-level feature differentiation.
For Market Incumbents: Compound hospital formulary anchoring by deepening backward integration into silicone polymer compounding and securing captive supply from German chemical corridors. Prioritize ISO 18562 certification investment ahead of EU MDR five-year surveillance mandates. Defend against pharmacological prophylaxis substitution by embedding biofeedback weaning algorithms into ventilator platform software stacks. For New Entrants and Emerging Players: Anchor in Texas and Florida post-acute long-term care facilities where bundled remote monitoring protocols remain underpenetrated and respiratory therapy staffing ratios lag tertiary ICU benchmarks. Target algorithm-driven weaning systems as the fastest-expanding technology segment with lowest incumbent lock-in. Pursue hospital-at-home partnerships as the go-to-market angle bypassing GPO procurement concentration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device engineering houses with software companion platforms and disposable consumable attachments. Five-to-ten year viability favors manufacturers with EU MDR notified body relationships in Germany and the Netherlands. Monitor FDA 510(k) review timeline extensions for modified endotracheal designs as the inflection signal for regulatory friction costs.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Performance Study Completion | Notified bodies in Hamburg impose additional biocompatibility testing that validates premium positioning. |
| ISO 18562 Breathing Gas Pathway Certification | Early compliance creates material differentiation against late-adopting competitors in United States GPO contracts. |
| Hospital System Partnership for Bundled Protocols | Texas Medical Center IDN standardization demonstrates procurement influence concentration. |
| Software Companion Development for Biofeedback Weaning | Charité – Universitätsmedizin Berlin pilots reduce nursing documentation burden and extend platform stickiness. |
| Reimbursement Strategy Alignment with CMS Penalty Structures | Hospital-acquired condition adjustments sharpen formulary scrutiny for mechanical prevention devices. |
Research Methodology
A spread of perspectives from ICU clinicians, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions driving device adoption curves. Primary interviews with respiratory therapy directors and formulary pharmacists combined with secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare cost report data, and hospital procurement database extracts. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from ventilator installed base estimates.
Segmentation dimensions modeled span product type, end-user facility tier, technology automation intensity, and regional regulatory cluster across the projection horizon. CAGRs derive from weighted average of historical procurement volume trends and forward-looking adoption assumptions for biofeedback systems. Industry-specific forecast inputs include ICU nursing shortage projections and EU MDR transition timeline compliance rates.
Material uncertainties — regulatory timeline slippage, silicone polymer supply disruptions, and pharmacological prophylaxis protocol adoption — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and clinical guideline endorsement evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Emphysema Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Acute Lung Injury Market