
 Global Medical Implants Market | 2026-2036
Global Medical Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Implants Market Outlook
Multi-source procurement for titanium feedstock is shifting toward captive supply arrangements among top manufacturers. Medtronic leverages its in-house forging capabilities to secure alloy consistency for spinal hardware. Stryker anchors its orthopedic portfolio through direct long-term contracts with Australian and South African rutile miners. Zimmer Biomet differentiates by controlling precision machining centers in Indiana and Switzerland.
Medical implants are artificial devices surgically placed inside or on the surface of the body to replace missing biological structures, typically manufactured from titanium alloys, cobalt-chrome, or bioresorbable polymers through CNC machining, additive manufacturing, or investment casting to restore physiological function. Orthopedic implants represent the most mature revenue pool, while neurostimulators command premium pricing due to firmware complexity and neuromodulation programming requirements. Cardiovascular implants are expanding fastest as transcatheter delivery systems displace open-chest procedures in hospital catheterization labs.
FDA premarket notification and EU MDR conformity assessment create dual compliance burdens that favor manufacturers with dedicated regulatory affairs teams in both jurisdictions. ISO 13485 quality management certification and Japan's PMDA foreign manufacturer registration further stratify market access, forcing mid-tier firms to outsource quality systems or exit premium segments. Stakeholders must monitor how CMS national coverage determinations and NICE technology appraisals redefine reimbursement for bioresorbable stents versus durable metal alternatives.
Market Dynamics
Transcatheter delivery systems are compressing hospital procurement cycles for cardiovascular implants while EU MDR conformity assessments extend regulatory timelines, creating a structural tension between speed-to-market and compliance burden that manufacturers must navigate through dedicated regulatory infrastructure.
Growth Catalysts
- Aging Demographics in Germany and Japan:Orthopedic implant volumes from patients over 65 are expanding as hip and knee replacement thresholds lower. Hospitals in Stuttgart and Osaka are prioritizing titanium-based spinal hardware.
- FDA Breakthrough Device Designation:Expedited premarket review pathways for neurostimulators and bioresorbable stents are compressing time-to-revenue for firmware-intensive devices with novel neuromodulation protocols.
- Value-Based Procurement Mandates:CMS national coverage determinations in the United States are rewarding durable cardiovascular implants with superior long-term outcomes data, shifting hospital purchasing criteria toward total cost of ownership metrics.
Market Restraints
- Rutile Supply Concentration:Titanium feedstock dependence on Australian and South African mining operations exposes forging operations to concentrate price volatility and geopolitical shipping disruptions.
- Dual Jurisdiction Compliance Burden:Simultaneous FDA premarket notification and EU MDR technical documentation requirements force mid-tier manufacturers to maintain parallel quality systems or abandon premium segments entirely.
- Bioresorbable Polymer Degradation Uncertainty:Variable resorption rates in magnesium and polylactic acid stents create clinical hesitation against proven cobalt-chrome alternatives, limiting addressable patient populations.
Strategic Opportunities
- Underpenetrated Indian Cardiac Centers:Tier-2 cities in Maharashtra and Tamil Nadu lack transcatheter aortic valve replacement capacity, creating first-mover advantage for manufacturers establishing training partnerships with CDSCO-registered distributors.
- Additive Manufacturing Convergence:Laser powder bed fusion combined with topology optimization software enables patient-specific orthopedic implants with porous structures that accelerate osseointegration.
- Japan PMDA Foreign Manufacturer Simplification:Streamlined registration pathways for ISO 13485-certified facilities are reducing market entry friction for spinal implant specialists targeting Tokyo and Nagoya hospital networks.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 18-24 month completion timelines, delaying product launches even when mechanical design is finalized.
- Legacy ERP Integration Friction:Hospital catheterization labs struggle to incorporate implant traceability data into existing supply chain management platforms, complicating lot-recall procedures and inventory reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Implants Market |
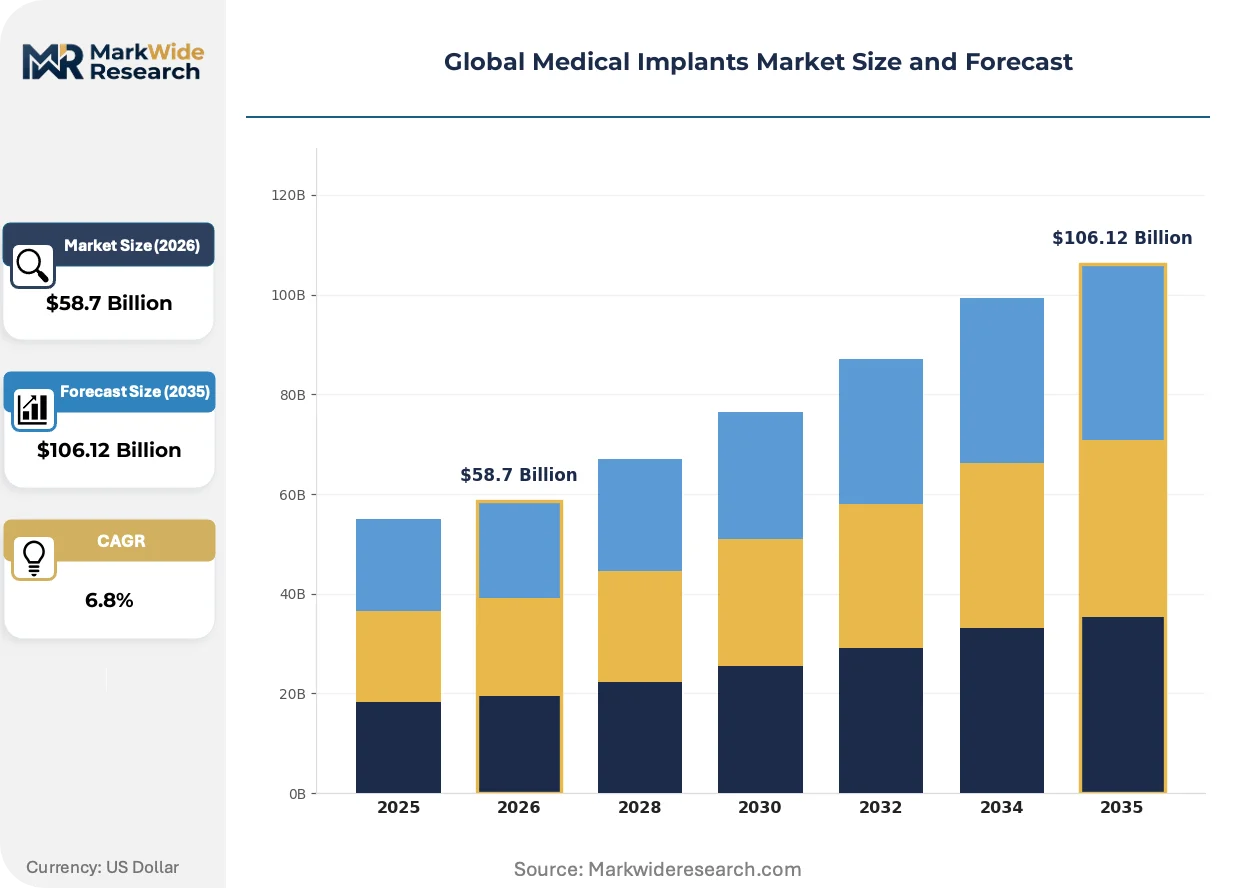
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Implants, Cardiovascular Implants, Dental Implants, Neurostimulators Material: Titanium, Stainless Steel, Biopolymers, Ceramics End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Technology: 3D Printing, Coatings, Bioresorbable Materials, Robotics |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker, Zimmer Biomet, Boston Scientific Corporation, Abbott Laboratories, Smith & Nephew, Globus Medical, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Implants Market Strategic Shifts
Additive manufacturing is rewriting titanium implant economics by eliminating forging waste and enabling lattice structures that mimic bone modulus. Three developments are compressing product development cycles and reshaping competitive positioning.
Porous titanium constructs produced through electron beam melting are absorbing load-bearing functions previously reserved for solid forged blanks. Academic medical centers in Switzerland and the United States are adopting these geometries for spinal fusion cages, with surgeons reporting reduced stress-shielding complications. The technology is absorbing market share from conventional subtractive machining as hospitals prioritize osseointegration performance over legacy manufacturing familiarity.
EU MDR Article 117 clinical evidence requirements are forcing cardiovascular implant manufacturers to commission prospective registries rather than rely on historical predicate equivalence. The regulation is extending conformity assessment durations by 12-18 months for Class III devices. High-risk stent and valve manufacturers are responding by pre-submission engagement with notified bodies in Germany and the Netherlands to de-risk technical documentation gaps.
Hospital value analysis committees are consolidating implant purchasing authority previously dispersed across individual surgeons. The concentration is displacing traditional distributor relationships with direct manufacturer contracts in the United States and Germany. Integrated delivery networks in Texas and Bavaria are negotiating multi-year spine and trauma implant agreements with price-volume tiers tied to exclusivity commitments.
Global Medical Implants Market Segmentation
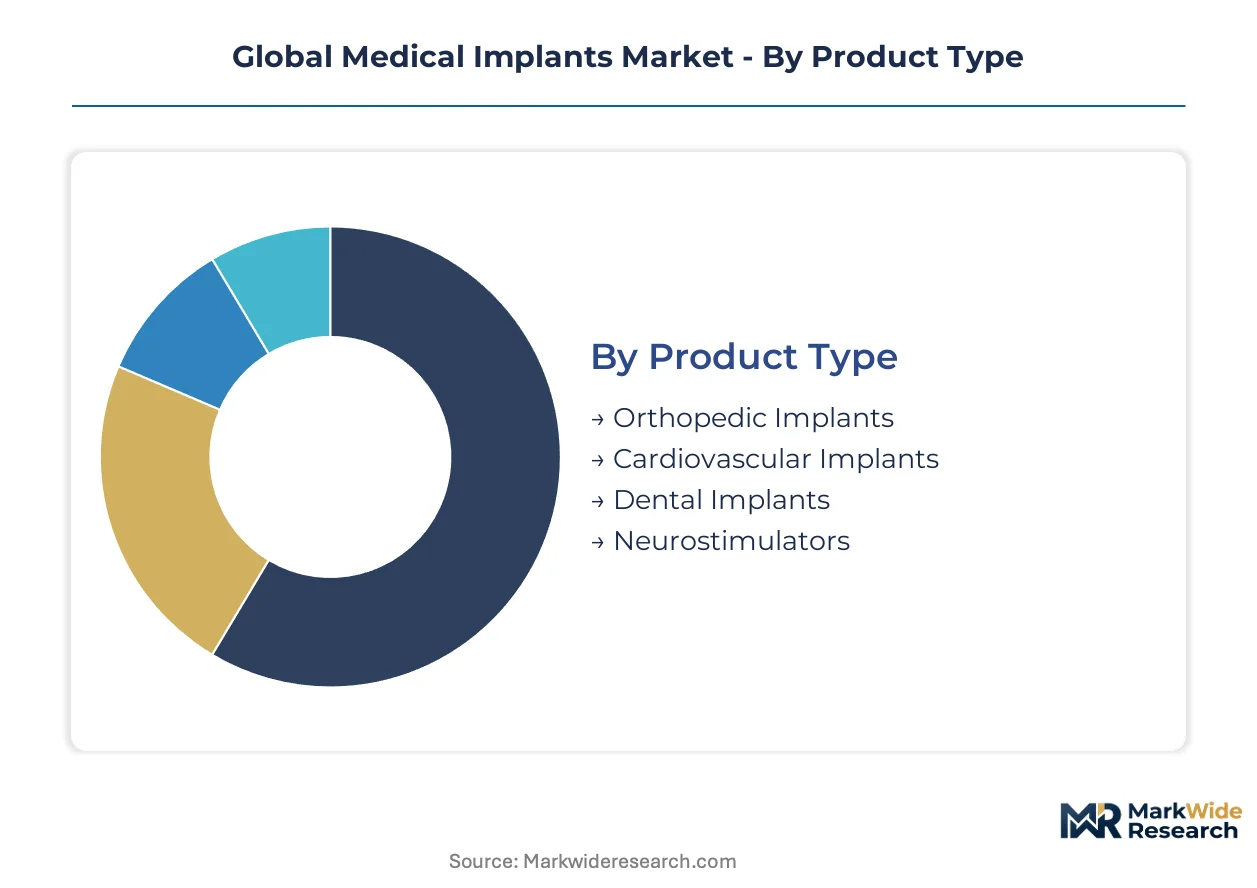
Implant replacement cycles vary dramatically by product type and material durability, creating distinct upgrade timelines that reshape manufacturer R&D priorities and hospital capital planning. Understanding these segment-specific renewal patterns reveals where procurement budgets concentrate and which technologies command premium positioning.
Product Type:
Upgrade urgency differs sharply across anatomical applications, with weight-bearing orthopedic hardware facing earlier revision pressure than neurostimulators with firmware-update pathways.
- Orthopedic Implants:Titanium and cobalt-chrome constructs for hip, knee, and spinal fusion carry 15-20 year functional lifespans, yet younger patient demographics in Germany and Japan are driving earlier revision surgeries as activity levels strain fixation hardware. Stuttgart hospitals report rising demand for titanium spinal cages with porous surfaces.
- Cardiovascular Implants:Transcatheter aortic valves and drug-eluting stents represent the steepest expansion trajectory as catheterization labs in the United States and China displace open-chest procedures. CMS reimbursement shifts favor durable metal platforms over bioresorbable alternatives with uncertain long-term patency.
- Dental Implants:Titanium screw fixtures and abutments serve edentulous populations with 95%+ ten-year survival rates, limiting replacement volume but sustaining steady primary placement demand.
- Neurostimulators:Firmware-upgradable spinal cord and deep brain stimulators extend device lifespans through remote programming, reducing explant frequency while capturing recurring revenue from neuromodulation protocol updates.
Orthopedic implants sit at the top of the volume ranking, with cardiovascular implants climbing the fastest.
Material:
Cost tier stratification separates premium titanium alloys from commodity stainless steel, with biopolymers occupying an emerging premium position despite clinical hesitation.
- Titanium:Ti-6Al-4V ELI alloys dominate load-bearing applications through superior strength-to-weight ratios and osseointegration performance. Australian and South African rutile supply concentration forces manufacturers toward captive mining contracts or long-term offtake agreements.
- Stainless Steel:316L grade serves cost-sensitive trauma plates and temporary fixation devices where explant timing reduces corrosion concerns. Indian and Chinese hospitals favor steel for high-volume fracture repair in price-constrained procurement environments.
- Biopolymers:Polylactic acid and polyglycolic acid scaffolds for craniofacial reconstruction and suture anchors face variable resorption rate challenges that limit adoption against proven metal alternatives.
- Ceramics:Alumina and zirconia femoral heads deliver exceptional wear resistance for hip arthroplasty, commanding premium pricing in Japanese and Swiss hospitals with established ceramic-on-ceramic bearing protocols.
Titanium commands the dominant revenue share, while biopolymers face the steepest adoption barriers despite theoretical advantages.
End User:
Customer type determines purchasing authority concentration, with integrated delivery networks consolidating implant selection power previously dispersed across individual surgeons.
- Hospitals:Academic medical centers and community hospitals in Texas and Bavaria negotiate multi-year spine and trauma agreements with price-volume tiers tied to exclusivity commitments, displacing traditional distributor relationships.
- Specialty Clinics:Orthopedic and dental implant-focused facilities concentrate high-margin elective procedures, with Swiss and South Korean clinics pioneering same-day discharge protocols for joint replacement.
- Ambulatory Surgical Centers:CMS site-of-service differentials are shifting low-acuity implant procedures to outpatient settings, compressing procurement timelines and favoring manufacturers with streamlined logistics.
- Research Institutions:Academic centers in Switzerland and the United States drive early adoption of electron beam melted titanium constructs and patient-specific additive manufacturing for complex spinal deformity correction.
Hospitals absorb the majority of implant volume, though ambulatory surgical centers are gaining share fastest as reimbursement shifts accelerate site migration.
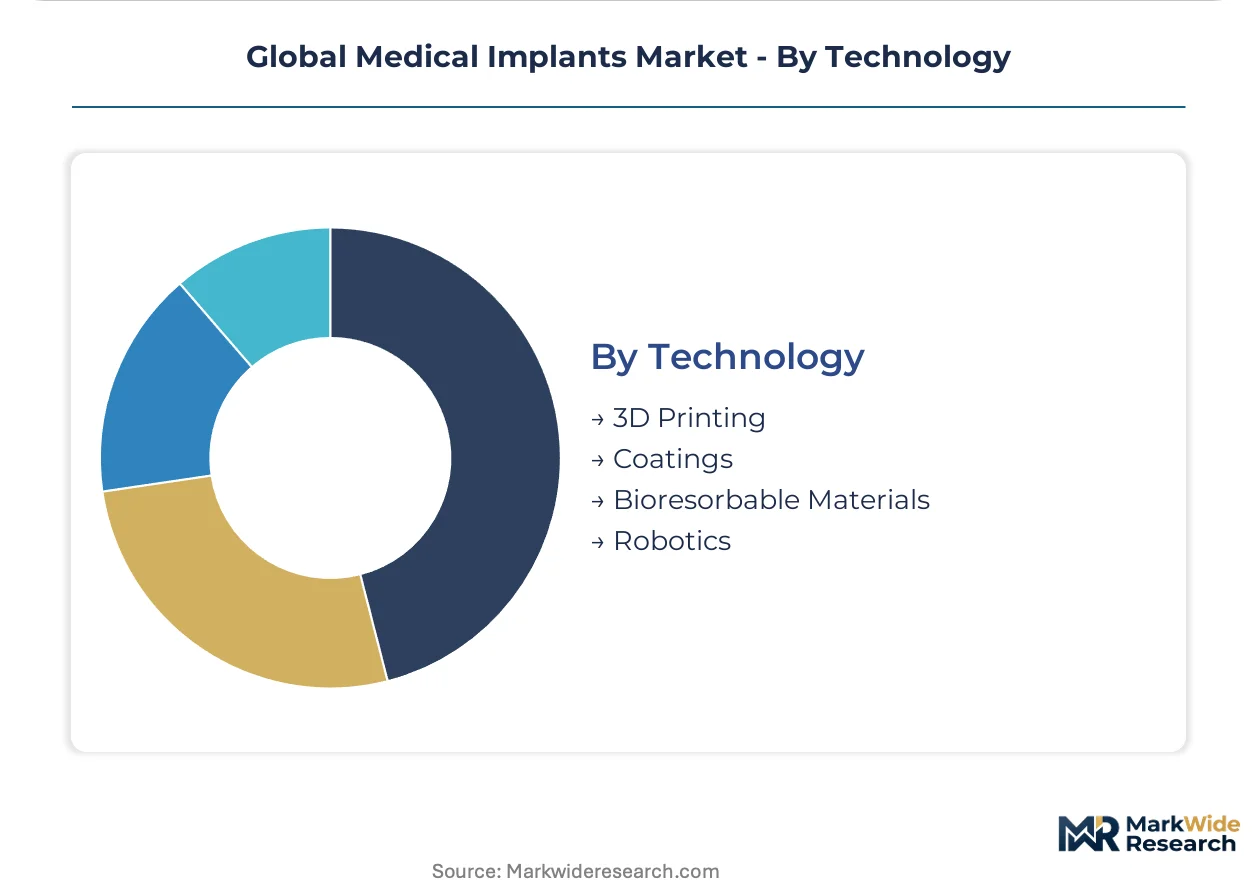
Technology:
Manufacturing maturity separates established coating platforms from emerging robotics integration, with 3D printing rewriting titanium economics through topology optimization.
- 3D Printing:Laser powder bed fusion enables patient-specific orthopedic implants with lattice structures that accelerate osseointegration. Academic medical centers in Switzerland and the United States report reduced stress-shielding complications with electron beam melted spinal fusion cages.
- Coatings:Hydroxyapatite and porous titanium plasma spray surfaces enhance bone-implant fixation, representing the most mature technology pathway with established FDA predicate equivalence.
- Bioresorbable Materials:Magnesium and polylactic acid scaffolds for pediatric and craniofacial applications face ISO 10993 testing bottlenecks that extend development timelines despite theoretical biodegradation benefits.
- Robotics:Surgical navigation and robotic-assisted placement systems for knee and spinal implants improve alignment accuracy, with Stryker and Zimmer Biomet integrating hardware with proprietary software ecosystems.
Coatings technology holds the broadest installed base, with 3D printing expanding most quickly as design software and powder supply chains mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's medical device manufacturing corridor anchors European orthopedic implant production, with precision machining clusters feeding supply chains across the continent. Demand concentrates in hospital systems with established value-based procurement frameworks and aging patient demographics requiring revision surgeries.
United States
Integrated delivery networks in Texas and California negotiate multi-year spine implant agreements tied to exclusivity commitments and volume thresholds. FDA premarket approval pathways for breakthrough cardiovascular devices compress regulatory timelines for transcatheter valve manufacturers. Academic medical centers in Boston and Minneapolis pioneer patient-specific additive manufacturing for complex spinal deformity correction.
Germany
Stuttgart hospitals report rising demand for titanium spinal cages with porous surfaces as hip and knee replacement thresholds lower for active aging populations. EU MDR conformity assessments extend technical documentation timelines for Class III cardiovascular devices by 12-18 months. The Bavarian industrial corridor concentrates precision forging operations serving orthopedic OEMs with captive rutile supply arrangements.
Japan
Osaka hospital networks prioritize titanium-based spinal hardware for patients over 65 with elevated activity levels straining fixation components. PMDA foreign manufacturer registration requirements stratify market access, favoring ISO 13485-certified facilities with dedicated regulatory infrastructure. Nagoya's medical device cluster specializes in ceramic-on-ceramic bearing protocols for hip arthroplasty with exceptional wear resistance.
China
Shanghai catheterization labs displace open-chest procedures with transcatheter delivery systems for aortic valve replacement. NMPA medical device registration pathways demand local clinical evidence generation, forcing multinational manufacturers to establish domestic trial infrastructure. Beijing-Tianjin-Hebei hospital networks consolidate implant purchasing authority under value analysis committees with price-volume tier structures.
India
Tier-2 cardiac centers in Maharashtra and Tamil Nadu lack transcatheter aortic valve replacement capacity, creating infrastructure gaps for CDSCO-registered distributors. Central government procurement schemes favor cost-sensitive stainless steel trauma plates for high-volume fracture repair. Mumbai's specialty clinics concentrate elective dental implant procedures with same-day discharge protocols.
Global Medical Implants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing specialization and bioresorbable material platforms. The market structure concentrates revenue among diversified conglomerates with captive forging capabilities and dedicated regulatory affairs teams spanning FDA and EU MDR jurisdictions. Three archetypes dominate: integrated device manufacturers with in-house alloy supply, precision machining specialists controlling regional production nodes, and firmware-intensive neuromodulation developers. Competitive dynamics center on M&A activity capturing additive manufacturing competencies and long-term offtake agreements securing titanium feedstock consistency.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson exemplify the integrated manufacturer archetype with multi-segment orthopedic and cardiovascular portfolios. These entities represent positions sustained through regulatory infrastructure spanning premarket notification pathways and MDR conformity assessment capabilities. Their geographic footprints concentrate manufacturing and quality systems across jurisdictions with stringent biocompatibility testing requirements.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker |
| Zimmer Biomet |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Smith & Nephew |
| Globus Medical |
| Integra LifeSciences |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in Texas and Bavaria concentrate implant purchasing authority through multi-year spine and trauma agreements, anchoring contract-based pricing with volume-tier discounts tied to exclusivity commitments. This buyer consolidation shifts pricing power toward manufacturers with captive titanium forging capabilities and dedicated regulatory infrastructure spanning FDA and EU MDR jurisdictions.
Pricing Analysis
Input-cost pass-through from Australian and South African rutile concentrate volatility feeds directly into titanium alloy pricing, with Ti-6Al-4V ELI premiums widening during shipping disruptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated neurostimulators from CE-marked orthopedic hardware and Indian government-procured stainless steel trauma plates. Pricing pressure stems from CMS site-of-service differentials compressing margins in ambulatory surgical centers. Ambulatory settings exhibit highest price sensitivity; academic medical centers with research partnerships tolerate premium positioning for patient-specific additive manufacturing.
Supply Chain Analysis
Regional distribution centers in Warsaw, Stuttgart, and Indianapolis operate hub-and-spoke patterns feeding hospital catheterization labs and orthopedic surgery suites with lot-traceable implant inventory. Geographic supply concentration centers on Australia and South Africa for rutile feedstock, Switzerland and the United States for precision machining, and China for bioresorbable polymer precursors. Raw material dependencies encompass titanium sponge, cobalt-chrome powder, and polylactic acid resin. Single-source vulnerability in South African mining operations exposes forging schedules to concentrate price spikes. Distribution runs through manufacturer-direct contracts displacing traditional distributor relationships in consolidated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing convergence and firmware-upgradable neuromodulation platforms are expanding premium-tier addressable markets while captive titanium supply arrangements compress input-cost volatility for integrated manufacturers.
For Market Incumbents: Lock in long-term rutile offtake agreements with Australian and South African miners to insulate forging operations from concentrate price spikes. Expand electron beam melting capacity in Switzerland and the United States to capture patient-specific orthopedic demand from academic medical centers. Bioresorbable polymer specialists with uncertain ISO 10993 timelines represent acquisition targets for neuromodulation firmware capabilities. For New Entrants and Emerging Players: Capture tier-2 cardiac centers in Maharashtra and Tamil Nadu through CDSCO-registered distributor partnerships for transcatheter valve training programs. Establish laser powder bed fusion service bureaus adjacent to Nagoya and Stuttgart hospital networks to bypass capital-intensive forging infrastructure. Direct-to-hospital logistics integration offers the most penetrable go-to-market angle against incumbent distributor relationships. For Investors and Strategic Acquirers: Diversified orthopedic conglomerates with captive alloy supply are the most active acquirer in this space, targeting additive manufacturing specialists and bioresorbable material platforms. The five-to-ten year viability window favors manufacturers with ISO 13485-certified facilities and dedicated EU MDR regulatory affairs teams. Acquisition target archetype: precision machining specialists controlling regional production nodes with PMDA registration pathways. Hospital value analysis committee consolidation rate serves as the critical inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Pre-Submission | Notified body engagement in Germany and Netherlands de-risks Class III device technical documentation gaps. |
| Captive Rutile Supply Arrangement | Direct long-term contracts with Australian and South African miners secure Ti-6Al-4V ELI alloy consistency. |
| Hospital System Partnership | Multi-year spine and trauma agreements with Texas integrated delivery networks displace distributor intermediaries. |
| Additive Manufacturing Competency Acquisition | Electron beam melting capabilities capture patient-specific orthopedic demand from Swiss academic centers. |
| Reimbursement Strategy Alignment | CMS national coverage determination positioning favors durable cardiovascular implants with long-term outcomes data. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down titanium feedstock tracking forms the analytical core of this study. Primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body registers, CMS Medicare reimbursement databases, and hospital procurement records. Triangulation between implant volume data and raw material trade flows ensures consistency across manufacturer-reported shipments and end-use consumption patterns.
Historical trendline analysis of orthopedic revision surgery rates, cardiovascular catheterization lab procedure volumes, and neurostimulator firmware update frequencies informs the projection framework. Segmentation dimensions span product type, material grade, end-user facility category, and manufacturing technology across the modeling period. CAGRs derive from fitted trend extrapolation adjusted for regulatory timeline impacts and reimbursement policy shifts. Forecast inputs incorporate EU MDR conformity assessment duration extensions and PMDA foreign manufacturer registration simplification trajectories.
Underlying measurement precision varies by segment; cardiovascular implant volumes carry tighter precision than bioresorbable polymer adoption curves given clinical hesitation uncertainties. Forecasts reflect documented assumptions regarding CMS reimbursement stability and rutile supply concentration persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
US Clear Aligners Market