
 Vehicle Transfer Case Market | 2026-2036
Vehicle Transfer Case Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Transfer Case Market Outlook
Aftermarket service revenue is tilting toward OEM-authorized network providers as vehicle complexity rises. BorgWarner Inc. leverages its integrated powertrain portfolio to capture recurring service contracts across North American light-truck platforms. Magna International Inc. anchors its position through captive manufacturing scale across multiple OEM assembly footprints. ZF Friedrichshafen AG differentiates via mechatronic integration expertise that extends from transfer case hardware into adjacent driveline controls.
A vehicle transfer case is a specialized gearbox that distributes torque between the front and rear axles, typically incorporating a chain-driven or gear-driven architecture with selectable or full-time engagement modes rated for specific torque capacities exceeding 5,000 Nm in heavy-duty applications. Its primary purpose is to enable multi-axle traction in passenger vehicles, commercial trucks, and off-highway equipment operating across variable terrain or adverse weather conditions. Electronic transfer cases now command the fastest expansion within product type segmentation as torque-on-demand architectures displace mechanical selector systems in premium SUV and crossover platforms. Within transmission type categories, torque-vectoring configurations represent the concentrated margin pool where electromechanical clutch packs enable dynamic left-right torque apportionment beyond conventional front-rear splits.
The EPA enforces Corporate Average Fuel Economy thresholds that compel transfer case manufacturers to reduce rotational mass and friction losses, while NHTSA Federal Motor Vehicle Safety Standards govern structural integrity under crash loading and rollover scenarios. ISO 26262 functional safety requirements for automotive electrical systems further constrain design freedom for electronic transfer case control modules, elevating validation costs for new program entries. Stakeholders must weigh the capital intensity of torque-vectoring electrification against the volume concentration in conventional all-wheel-drive architectures serving mainstream crossover segments.
Market Dynamics
Torque-on-demand architectures are compressing development cycles across the transfer case supply base as electronic clutch packs displace mechanical selector systems in volume SUV platforms. Tier 1 suppliers now face capital allocation decisions between electrified torque-vectoring R&D and sustaining production of conventional all-wheel-drive hardware.
Growth Catalysts
- EPA Corporate Average Fuel Economy thresholds:NHTSA-aligned mandates in the United States compel rotational mass reduction and friction-loss minimization in transfer case housings. Lightweight aluminum-magnesium alloys now penetrate heavy-duty pickup architectures previously dominated by cast iron.
- Last-mile delivery fleet electrification:Commercial operators in the United States are specifying all-wheel-drive configurations for electric van platforms operating across snow-belt states. Torque management hardware enables consistent traction without range-compromising tire chains.
- ISO 26262 functional safety requirements:Automotive electrical system standards elevate validation rigor for electronic transfer case control modules. Compliance investments create barrier-to-entry effects that consolidate supplier relationships around proven firmware developers.
Market Restraints
- Aluminum alloy price volatility:Housing material substitution toward lightweight grades exposes manufacturers to London Metal Exchange commodity swings. Margin compression intensifies when automotive OEMs resist raw-material pass-through clauses in multi-year supply agreements.
- Supply concentration in Michigan-Ohio corridor:Foundry capacity and machining expertise cluster within a 200-mile radius of Detroit. Weather disruptions or labor actions at key Tier 2 suppliers cascade through just-in-sequence assembly schedules.
- Electrified powertrain substitution:Dedicated electric axle architectures eliminate mechanical torque distribution hardware entirely. Battery-electric platforms from Rivian and legacy OEMs bypass transfer case integration through independent front-rear motor control.
Strategic Opportunities
- Texas-Oklahoma shale field equipment:Off-highway applications in oil patch service trucks remain underpenetrated by electronic torque-vectoring systems. Harsh-cycle durability requirements favor suppliers with validated sealing and thermal management IP.
- California Air Resources Board zero-emission mandates:Hybrid commercial truck incentives create demand for electrified transfer cases managing torque splits between combustion and electric axles. CARB credit economics improve total-cost-of-ownership calculations for fleet operators.
- Mechatronics-convergence with brake-by-wire:Integration of torque-vectoring clutch packs with electronic stability control systems enables predictive traction management. Tier 1 suppliers with adjacent brake actuator expertise capture system-level specification authority.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineers with ISO 26262 ASIL-D project experience command premium compensation in Detroit and Stuttgart labor markets. Recruitment competition from autonomous vehicle programs strains transfer case control module development timelines.
- Legacy platform coexistence complexity:Simultaneous engineering of mechanical selector systems for aging truck architectures and electronic units for next-generation crossovers duplicates validation infrastructure. Capital intensity rises without corresponding volume consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Transfer Case Market |
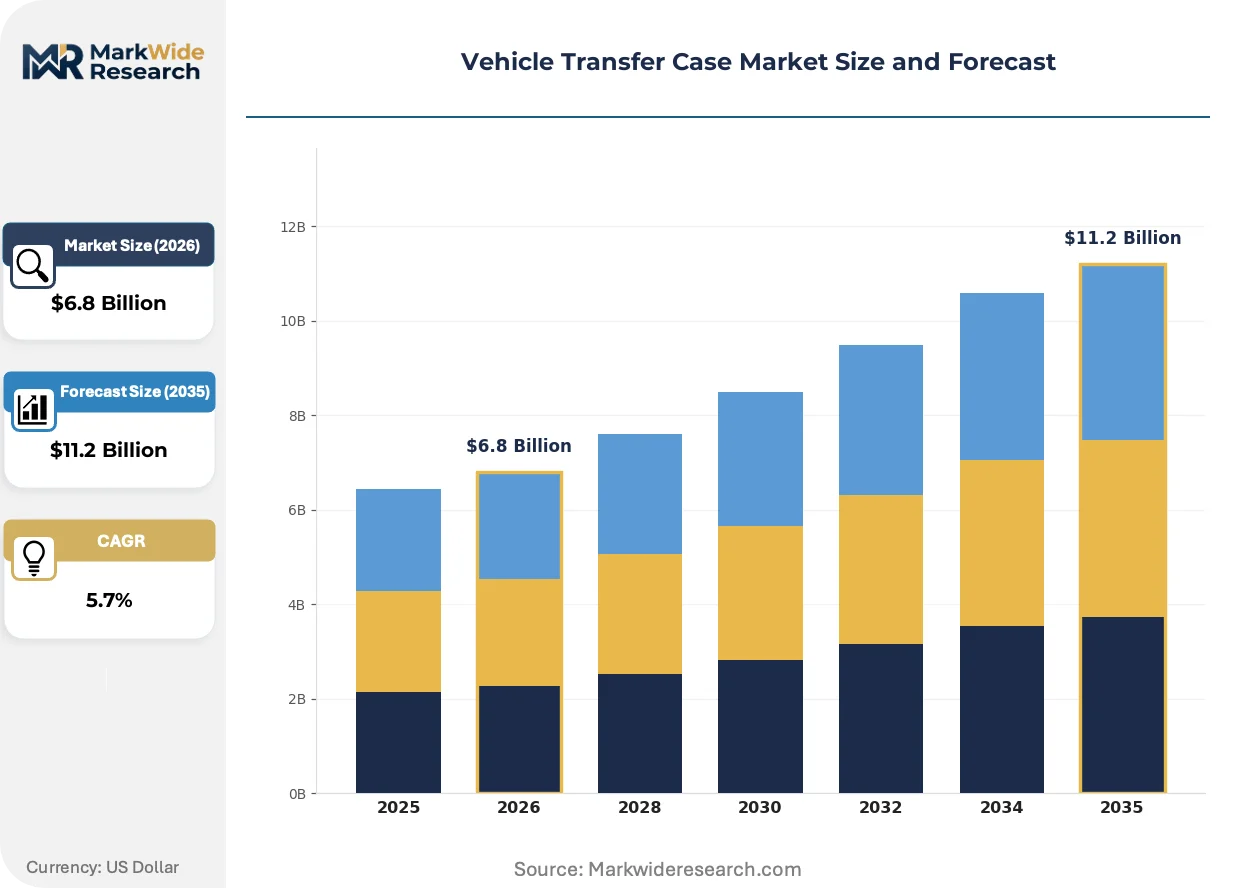
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Electronic, Hybrid End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Transmission Type: Four-Wheel Drive, All-Wheel Drive, Two-Wheel Drive, Torque-Vectoring Material: Aluminum, Steel, Composite, Magnesium |
| Companies Covered | BorgWarner Inc., Magna International Inc., ZF Friedrichshafen AG, Aisin Corporation, GKN Automotive Ltd., Schaeffler AG, Dana Incorporated, American Axle & Manufacturing, Inc., JTEKT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Transfer Case Market Strategic Shifts
Actuation mechanisms are bifurcating between electromechanical precision and cost-optimized mechanical durability as OEMs stratify platform architectures. The competitive frontier now centers on firmware-enabled feature differentiation rather than hardware torque capacity alone.
Electromechanical clutch packs with integrated position sensors are rendering obsolete cable-actuated range selectors in premium SUV segments. BMW and Mercedes-Benz specification engineers now mandate electronic shift-on-the-fly capability for all all-wheel-drive platforms above 400 Nm torque ratings. The technology is rendering obsolete supplier business models predicated on mechanical linkage production volume.
EPA-NHTSA harmonized fuel economy and safety rulemakings are accelerating multi-material housing designs. Structural aluminum castings now integrate with composite belly pans to meet pedestrian impact standards while preserving ground clearance. Heavy-duty pickup architectures in the United States absorb the highest compliance engineering costs as crashworthiness and weight reduction targets conflict.
Fleet procurement departments now unbundle after-sales service contracts from initial hardware purchase. Commercial operators in the United States negotiate separate multi-year maintenance agreements with OEM-authorized networks rather than independent repair shops. Channel restructuring concentrates service revenue at BorgWarner and Magna captive facilities equipped with proprietary diagnostic tools and firmware update capabilities.
Vehicle Transfer Case Market Segmentation
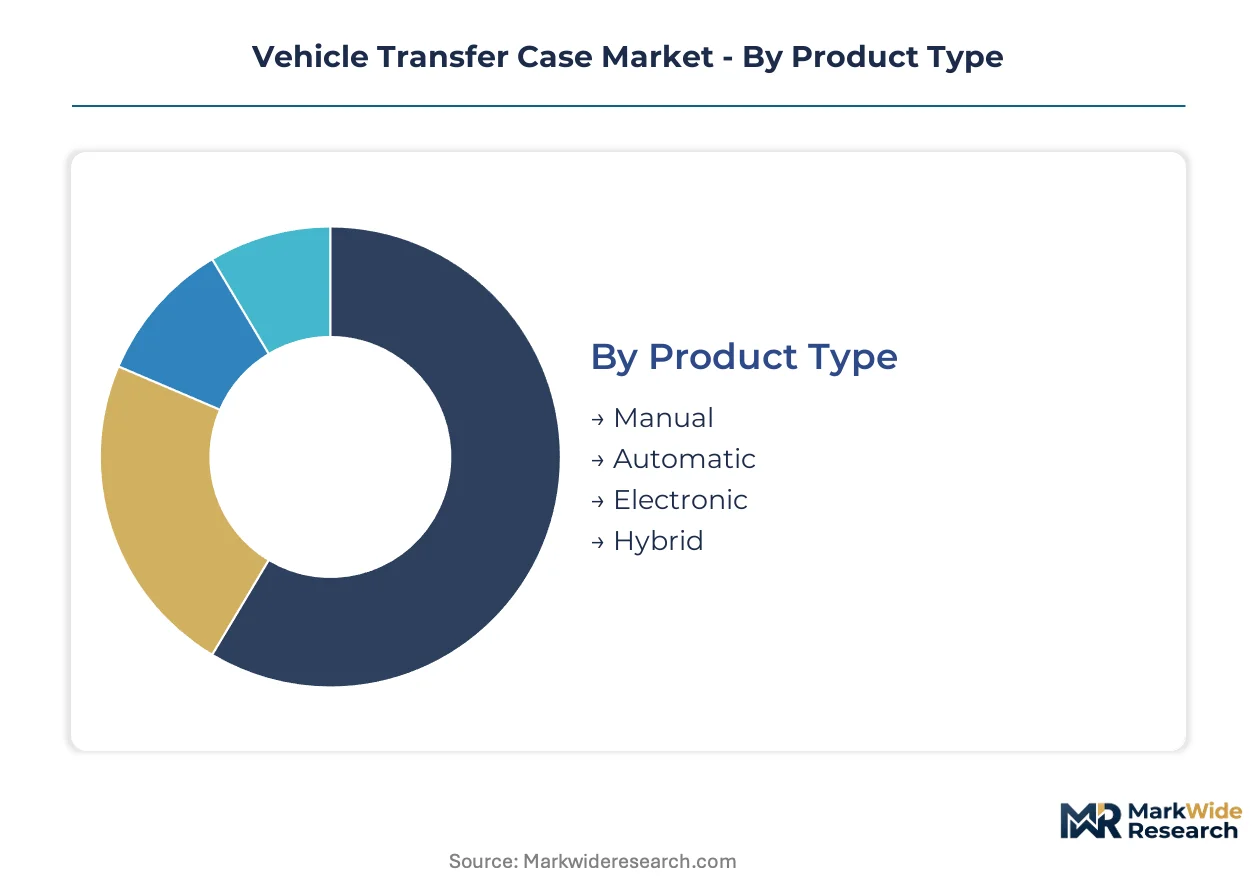
Transfer case segmentation reveals how torque distribution architectures stratify across price-performance tiers and duty cycles. Product type and transmission configuration choices directly determine manufacturing capital intensity, software validation requirements, and aftermarket service attach rates.
Product Type:
Cost tier differentiation separates entry-level mechanical systems from premium electronic architectures commanding firmware-enabled feature premiums.
- Manual:Cable-actuated range selectors with mechanical dog clutches dominate heavy-duty pickup architectures in Michigan and Ohio manufacturing corridors. Fleet procurement departments favor these units for field-serviceability and minimal diagnostic dependency in remote operating environments.
- Electronic:Electromechanical clutch packs with integrated position sensors enable shift-on-the-fly engagement without drivetrain windup. BMW and Mercedes-Benz specification engineers mandate electronic architectures for all platforms above 400 Nm torque ratings in premium SUV segments.
- Automatic:Viscous coupling or gerotor pump systems provide passive torque distribution without driver intervention. Subaru and Toyota deploy these extensively across mainstream crossover volumes where cost containment outweighs terrain-selectability requirements.
- Hybrid:Electrified transfer cases manage torque splits between combustion and electric axles in CARB-incentivized commercial truck platforms. Thermal management complexity elevates validation costs beyond conventional architectures.
Manual holds installed capacity. Electronic is rotating up the share rankings.
End User:
Customer type determines channel structure, warranty terms, and software update accessibility across the ownership lifecycle.
- OEMs:Vehicle manufacturers specify transfer cases at platform conception, locking in multi-year supply agreements with firmware exclusivity clauses. Ford and Stellantis integrate transfer case sourcing into powertrain bundling negotiations with BorgWarner and Magna.
- Fleet Operators:Commercial last-mile delivery and oil-field service truck purchasers unbundle hardware procurement from multi-year maintenance contracts. These buyers negotiate separate service agreements with OEM-authorized networks equipped with proprietary diagnostic tools.
- Aftermarket Providers:Independent repair shops face declining access as electronic complexity and ISO 26262 functional safety requirements restrict firmware updates to captive facilities. Revenue concentrates at Tier 1 supplier-owned service centers.
- Dealerships:Franchised retail channels intermediate warranty work and customer-paid repairs for passenger vehicle segments. Diagnostic equipment investments and technician certification requirements create barrier-to-entry effects favoring larger dealer groups.
OEMs anchor volume concentration. Fleet Operators are gaining procurement sophistication fastest.
Transmission Type:
Application duty cycle and terrain variability dictate engagement mode selection and torque capacity requirements.
- All-Wheel Drive:Full-time torque distribution with variable front-rear splits dominates crossover platforms operating across snow-belt states. These systems prioritize on-road stability over rock-crawling capability.
- Torque-Vectoring:Electromechanical clutch packs enable dynamic left-right torque apportionment beyond conventional front-rear splits. This architecture commands concentrated margins in premium performance SUVs where BMW and Mercedes-Benz specification engineers mandate predictive traction management.
- Four-Wheel Drive:Part-time selectable engagement with locked 50:50 splits persists in heavy-duty pickup and off-highway applications. Texas-Oklahoma shale field equipment favors these mechanical systems for harsh-cycle durability.
- Two-Wheel Drive:Single-axle configurations eliminate transfer case hardware entirely in cost-optimized fleet van and entry-level passenger car segments. Battery-electric platforms from Rivian bypass mechanical distribution through independent motor control.
All-Wheel Drive holds installed capacity. Torque-Vectoring is climbing the fastest.
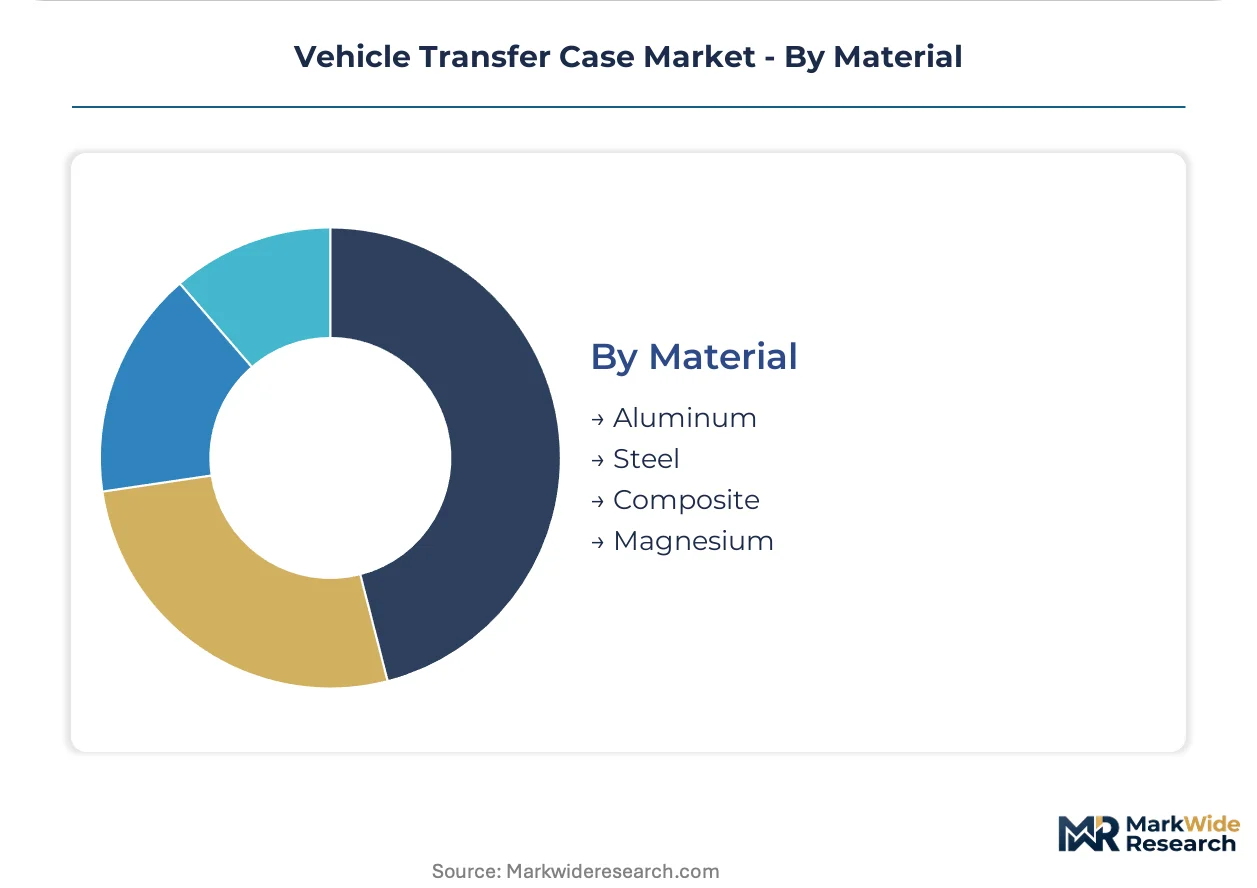
Material:
Supply concentration in foundry and machining capacity constrains lightweight substitution timelines across housing architectures.
- Aluminum:Structural castings with magnesium alloying penetrate heavy-duty architectures previously dominated by cast iron. EPA Corporate Average Fuel Economy thresholds compel rotational mass reduction in Michigan and Ohio production corridors.
- Composite:Glass-fiber reinforced polymer belly pans integrate with aluminum castings to meet NHTSA pedestrian impact standards while preserving ground clearance. These hybrid structures absorb highest compliance engineering costs in heavy-duty pickup segments.
- Steel:Conventional cast iron and stamped steel housings persist in price-sensitive commercial truck platforms where durability overrides weight targets. Foundry capacity clusters within 200-mile radius of Detroit amplify supply risk.
- Magnesium:High-pressure die-cast housings achieve maximum specific strength for electronic transfer case architectures in premium SUV segments. London Metal Exchange price volatility exposes margin compression when OEMs resist raw-material pass-through clauses.
Steel holds installed capacity. Aluminum is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Fleet buyers in North American snow-belt states accept hardware premiums for all-wheel-drive capability, while emerging-market commercial operators prioritize field-serviceability over electronic sophistication.
United States
Commercial last-mile delivery fleets in Michigan and Ohio manufacturing corridors specify electronic transfer cases for electric van platforms. EPA Corporate Average Fuel Economy thresholds compel aluminum-magnesium housing substitution in heavy-duty pickup architectures. Detroit-area foundry capacity clusters within a 200-mile radius, amplifying weather-related supply risk.
Germany
Premium SUV specification engineers at BMW and Mercedes-Benz mandate electronic shift-on-the-fly capability for platforms above 400 Nm torque ratings. KBA type-approval requirements enforce ISO 26262 functional safety validation for electronic control modules. Stuttgart labor markets face acute scarcity of embedded software talent with ASIL-D project experience.
China
Domestic OEMs accelerate torque-vectoring adoption in premium crossover segments serving affluent coastal provinces. MIIT new energy vehicle mandates create demand for electrified transfer cases managing combustion-electric axle splits. Yangtze River Delta manufacturing bases concentrate machining expertise for aluminum housing production.
Japan
Subaru and Toyota deploy viscous-coupling automatic systems across mainstream crossover volumes where cost containment dominates. METI fuel efficiency standards pressure rotational mass reduction without sacrificing durability validation heritage. Nagoya-area suppliers maintain captive foundry relationships for conventional steel housing architectures.
India
Commercial vehicle manufacturers serving Himalayan terrain prioritize mechanical selector reliability over electronic complexity. BIS automotive component standards govern structural integrity under crash loading scenarios. Maharashtra and Gujarat production corridors attract aluminum casting investments for export-oriented SUV platforms.
Vehicle Transfer Case Market Competitive Environment
Capability concentration sits with mechatronics-integrated specialists; scale advantage sits with powertrain bundling conglomerates. The supplier base stratifies across three tiers: integrated powertrain architects with firmware exclusivity, captive manufacturing scale operators with multi-OEM footprints, and regional specialists serving price-sensitive commercial segments. Consolidation pressure intensifies as electronic complexity elevates validation costs beyond mid-cap balance sheet capacity. Dominant competitive moves include backward integration into aluminum foundry capacity and exclusive multi-year service contract capture with fleet operators.
Among the integrated powertrain architects, BorgWarner Inc. and ZF Friedrichshafen AG exemplify the firmware-enabled differentiation archetype, while Magna International Inc. occupies a position representing captive manufacturing scale across multiple OEM assembly footprints. These three entities anchor the competitive structure through contrasting approaches to torque distribution hardware: one emphasizing mechatronic convergence with adjacent driveline controls, another leveraging integrated portfolio breadth for recurring service contract capture, and the third securing specification authority through manufacturing proximity to major vehicle assembly plants.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Magna International Inc. |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| GKN Automotive Ltd. |
| Schaeffler AG |
| Dana Incorporated |
| American Axle & Manufacturing, Inc. |
| JTEKT Corporation |
| Others |
Value Chain & Pricing Dynamics
Detroit-area foundry capacity clusters within a 200-mile radius of southeastern Michigan, concentrating aluminum-magnesium alloy supply for transfer case housings and amplifying pricing power for captive Tier 1 suppliers serving OEM assembly footprints. This geographic tightness creates asymmetric leverage where housing manufacturers resist raw-material pass-through clauses while commercial fleet buyers face limited alternative sourcing for electronic torque-vectoring architectures.
Pricing Analysis
Aftermarket service revenue streams now drive lifetime value capture as fleet operators unbundle multi-year maintenance contracts from initial hardware procurement. Three-tier pricing structure across premium electronic, standard all-wheel-drive, and economy mechanical selector levels reflects firmware complexity and ISO 26262 validation investment. Cost compression in aluminum alloy feedstocks intensifies margin pressure when London Metal Exchange volatility spikes. Fleet procurement departments exhibit highest price sensitivity for conventional mechanical systems, while premium SUV platforms demonstrate inelastic demand for shift-on-the-fly electronic architectures.
Supply Chain Analysis
Aluminum-magnesium alloy ingots, high-strength steel billets, and electronic clutch pack subassemblies constitute the critical upstream feedstock dependencies for transfer case manufacturing. Supply concentrates in the United States, Germany, and China, with Yangtze River Delta machining bases serving aluminum housing demand for domestic OEM electrification programs. Single-source vulnerability in Detroit-corridor foundry capacity exposes just-in-sequence assembly schedules to weather disruption cascades. Distribution runs through OEM-authorized service networks equipped with proprietary diagnostic firmware, marginalizing independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated fleet operators unbundling hardware and service procurement, fragmenting the traditional OEM-Tier 1 bundled supply relationship and forcing suppliers toward recurring revenue contract structures.
For Market Incumbents: Harden firmware exclusivity clauses in multi-year OEM supply agreements to defend against electrified axle substitution eliminating mechanical torque distribution hardware entirely. Deepen captive foundry relationships in Michigan and Ohio corridors to secure aluminum-magnesium alloy supply against commodity volatility. Prioritize ISO 26262 ASIL-D certification investment to create barrier-to-entry effects that consolidate supplier relationships around proven electronic control module developers. For New Entrants and Emerging Players: Establish a beachhead in Texas-Oklahoma shale field equipment segments where harsh-cycle durability requirements favor validated sealing and thermal management IP over electronic sophistication. Target mechanical selector reliability for Himalayan terrain commercial vehicles in India where field-serviceability overrides firmware complexity. Pursue CARB-incentivized hybrid commercial truck platforms in California as the go-to-market angle, leveraging torque-split electrification expertise between combustion and electric axles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mechatronics-integrated specialists with adjacent brake-by-wire expertise over pure mechanical hardware manufacturers. Long-term viability across the projection horizon rests on firmware-enabled feature differentiation rather than torque capacity alone. Acquisition target archetype: Tier 1 suppliers with validated electronic clutch pack integration and exclusive fleet service contract capture. The signal to watch is battery-electric platform adoption rates from Rivian and legacy OEMs bypassing transfer case hardware through independent motor control.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foundry Capacity | Secures rotational mass reduction compliance against EPA Corporate Average Fuel Economy thresholds without margin compression from London Metal Exchange volatility. |
| Firmware Exclusivity Clause Negotiation | Locks OEM platform specification authority and blocks emerging competitors from electronic shift-on-the-fly capability mandates above 400 Nm torque ratings. |
| Exclusive Fleet Service Contract Capture | Concentrates aftermarket revenue at captive facilities with proprietary diagnostic tools as vehicle complexity rises and independent repair access declines. |
| Mechatronics Convergence with Brake-by-Wire Systems | Enables predictive traction management integration that captures system-level specification authority from BMW and Mercedes-Benz engineering teams. |
| ISO 26262 ASIL-D Certification Investment | Creates barrier-to-entry effects that consolidate supplier relationships and elevate validation costs beyond mid-cap balance sheet capacity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA rulemaking documents, NHTSA Federal Motor Vehicle Safety Standards, and vehicle production databases. Primary interviews engaged Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and commercial fleet operations managers. Secondary validation drew from SEC 10-K filings, IHS Markit registration data, and ISO 26262 certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic automotive production forecasts.
Forecast inputs span vehicle class segmentation, propulsion architecture evolution, content-per-vehicle trajectories, and regional production cluster concentration across the analysis window. The modeling framework derives expansion rates from historical correlation with automotive output, EPA-NHTSA regulatory compliance cost absorption, and fleet electrification adoption curves. Segment-level projections incorporate electronic versus mechanical transfer case mix shifts, aluminum-magnesium housing penetration rates, and torque-vectoring specification intensity by OEM tier.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, aluminum alloy pricing, or electrification subsidy policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology substitution rates. Cross-checking against IHS Markit vehicle registration benchmarks and EPA compliance certification data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Tire Mold Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market