
 Camshaft Bearings Market | 2026-2036
Camshaft Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Camshaft Bearings Market Analysis
OEM procurement for camshaft bearings is pivoting toward fewer, larger supplier relationships as automakers consolidate vendor bases to cut qualification costs. MAHLE GmbH leverages its integrated engine systems portfolio to anchor long-term supply contracts with European and Asian vehicle manufacturers. SKF competes through advanced surface engineering capabilities that extend bearing life under high-load valvetrain conditions. King Engine Bearings specializes in trimetal and bimetal constructions for performance and heavy-duty segments where thermal resilience commands premium positioning.
Camshaft bearings are precision-engineered friction-reduction components that support rotating camshafts within engine blocks, typically manufactured from steel-backed alloys with bronze or aluminum-tin overlays and tolerances measured in micrometers to maintain oil film integrity. Their primary purpose is to minimize wear, dampen vibration, and maintain precise valve timing across millions of operating cycles. Shell bearings dominate volume production for automotive engines due to cost-efficient stamped construction and replaceability, while solid bearings retain share in industrial machinery where dimensional stability under sustained load outweighs serviceability concerns. Composite material formulations represent the fastest-expanding segment as OEMs pursue mass reduction targets without sacrificing fatigue resistance.
EPA fuel economy mandates and NHTSA safety standards in the United States, alongside EU Green Deal emissions frameworks and REACH material compliance requirements, compel bearing manufacturers to reformulate overlays and validate new substrates through extended durability cycles. India's BIS certification and PLI scheme for automotive components create parallel compliance pathways for suppliers serving domestic OEMs and export markets. Stakeholders must monitor regulatory divergence between Euro 7 preparation and divergent U.S. standards to avoid redundant testing regimes that compress development timelines.
Market Dynamics
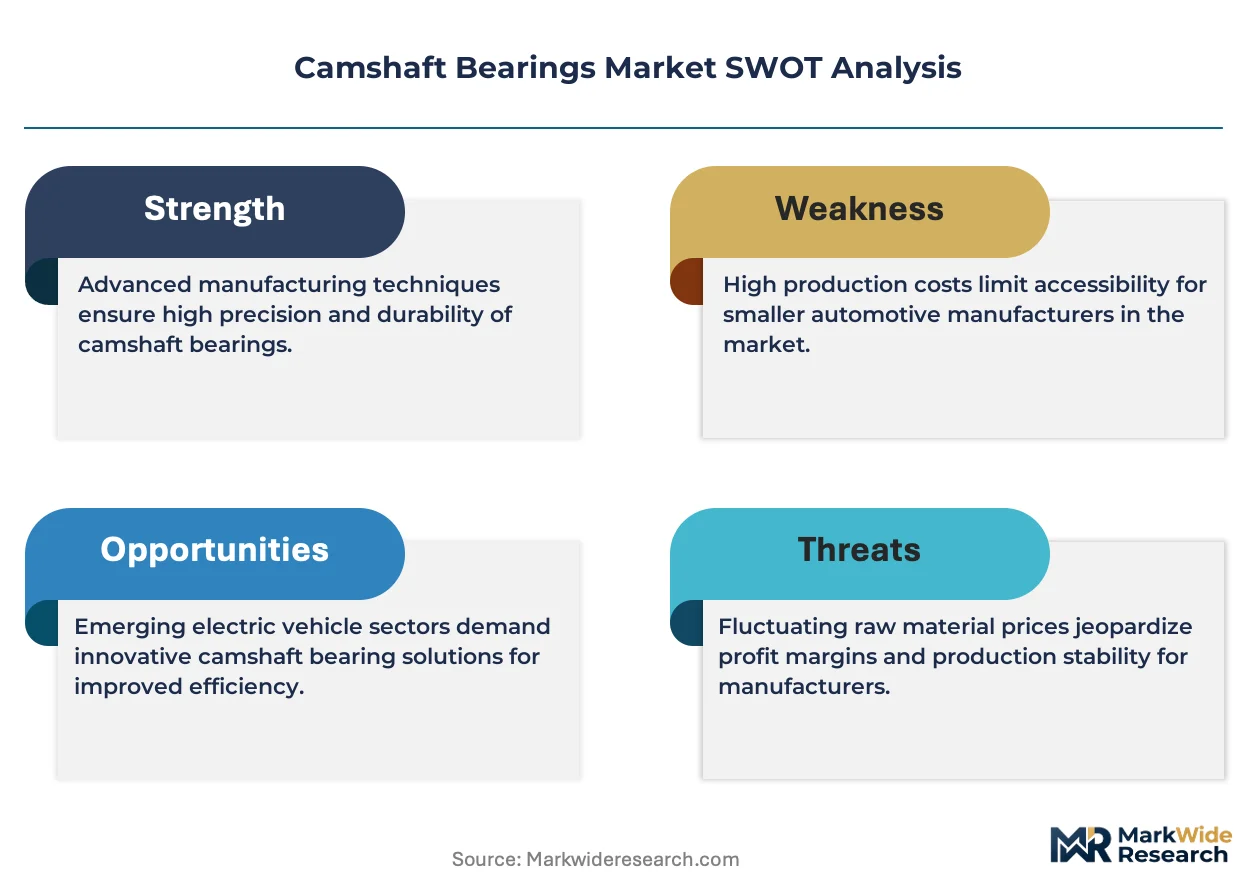
Automotive OEMs are consolidating supplier bases to slash qualification costs while simultaneously demanding lighter, more durable bearing substrates that satisfy tightening emissions mandates across multiple jurisdictions.
Growth Catalysts
- EU Green Deal emissions frameworks:European passenger vehicle manufacturers are accelerating aluminum-tin overlay adoption to reduce engine mass and meet fleet-average CO2 targets.
- India's PLI scheme for automotive components:Domestic foundries near Pune and Chennai are scaling capacity to capture incentives serving both local OEMs and export programs.
- Composite material formulations:Polymer-matrix bearing overlays are penetrating high-performance segments where thermal resilience and mass reduction converge.
Market Restraints
- Steel and copper alloy input volatility:Raw material price swings compress margin visibility for bearing overlay manufacturers operating on annual supply contracts.
- Foundry concentration in China's Yangtze Delta:Single-region dependency for precision casting capacity exposes buyers to logistics disruption and tariff friction.
- REACH material compliance complexity:Reformulating bronze overlays to eliminate restricted substances extends validation timelines by 12-18 months.
Strategic Opportunities
- Underpenetrated commercial vehicle electrification:Range-extender and hybrid powertrains in Brazil and Southeast Asia require specialized bearings for intermittent combustion cycles.
- Convergence of additive manufacturing and surface engineering:Directed energy deposition enables localized overlay customization for low-volume performance engine builders.
- India's BIS certification expansion:Streamlined approval pathways for export-grade bearings reduce time-to-market for suppliers targeting Middle East and African OEMs.
Industry Challenges
- Tribology and metallurgy skill scarcity:Foundry engineers with expertise in multi-layer bearing bonding are retiring faster than training programs replace them.
- Euro 7 validation compression:Overlapping durability test cycles for divergent U.S. and European standards strain R&D bandwidth.
- Legacy engine platform integration:New bearing substrates must maintain backward compatibility with existing block machining specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camshaft Bearings Market |
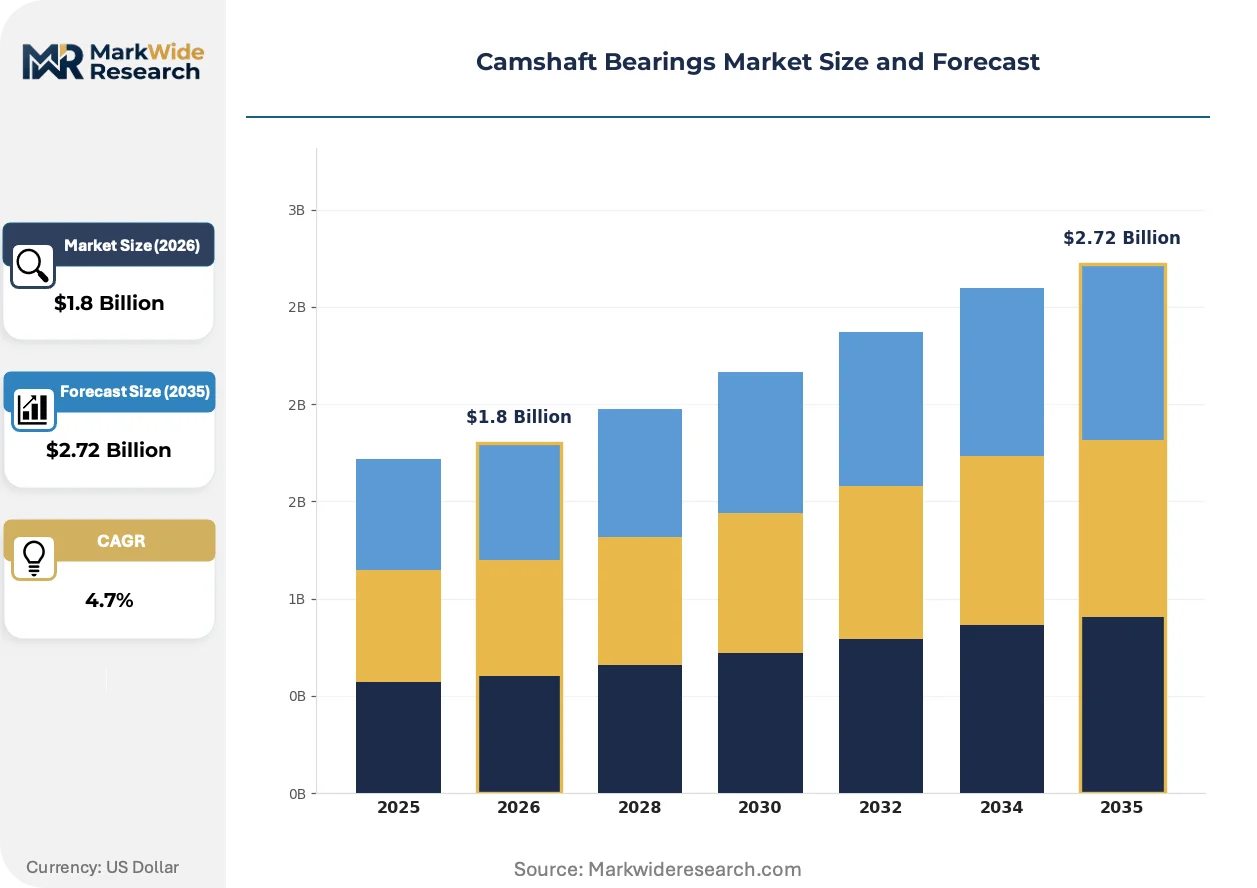
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Bearings, Shell Bearings, Leaf Bearings, Thrust Bearings Material: Steel, Aluminum, Bronze, Composite Application: Automotive Engines, Industrial Machinery, Marine Equipment, Aerospace Systems End User: OEMs, Aftermarket Providers, Maintenance Services, Distributors |
| Companies Covered | Wafangdian Bearing Group, King Engine Bearings, MAHLE GmbH, Precision Camshafts Ltd., Rane Engine Valve Limited, Federal-Mogul LLC, CCTY Bearing Company, ORS Bearings, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camshaft Bearings Market Emerging Trajectories
Surface engineering breakthroughs and procurement model compression are restructuring how bearing specifications propagate from OEM engineering centers to tier-two foundries.
Polymer-ceramic hybrid overlays are rewriting durability benchmarks for start-stop valvetrain cycles. Chinese and Indian passenger vehicle OEMs are adopting these materials for 48V mild-hybrid architectures. The technology is compressing traditional three-layer steel-bronze-aluminum constructions into single-substrate solutions.
REACH authorization requirements for lead-free bearing alloys are forcing reformulation of traditional bronze overlays across European supply chains. Manufacturers must validate new copper-tin-bismuth compositions through extended seizure-resistance testing. Powertrain divisions in Germany and Italy are absorbing the bulk of retooling costs.
Consolidated supplier programs are compressing the number of qualified bearing vendors per engine platform from six to two. Tier-one powertrain integrators now demand captive design collaboration rather than catalog selection. This concentration is most visible in Japan and South Korea, where Hyundai and Toyota have reduced their camshaft bearing supplier pools since 2022.
Camshaft Bearings Market Segmentation
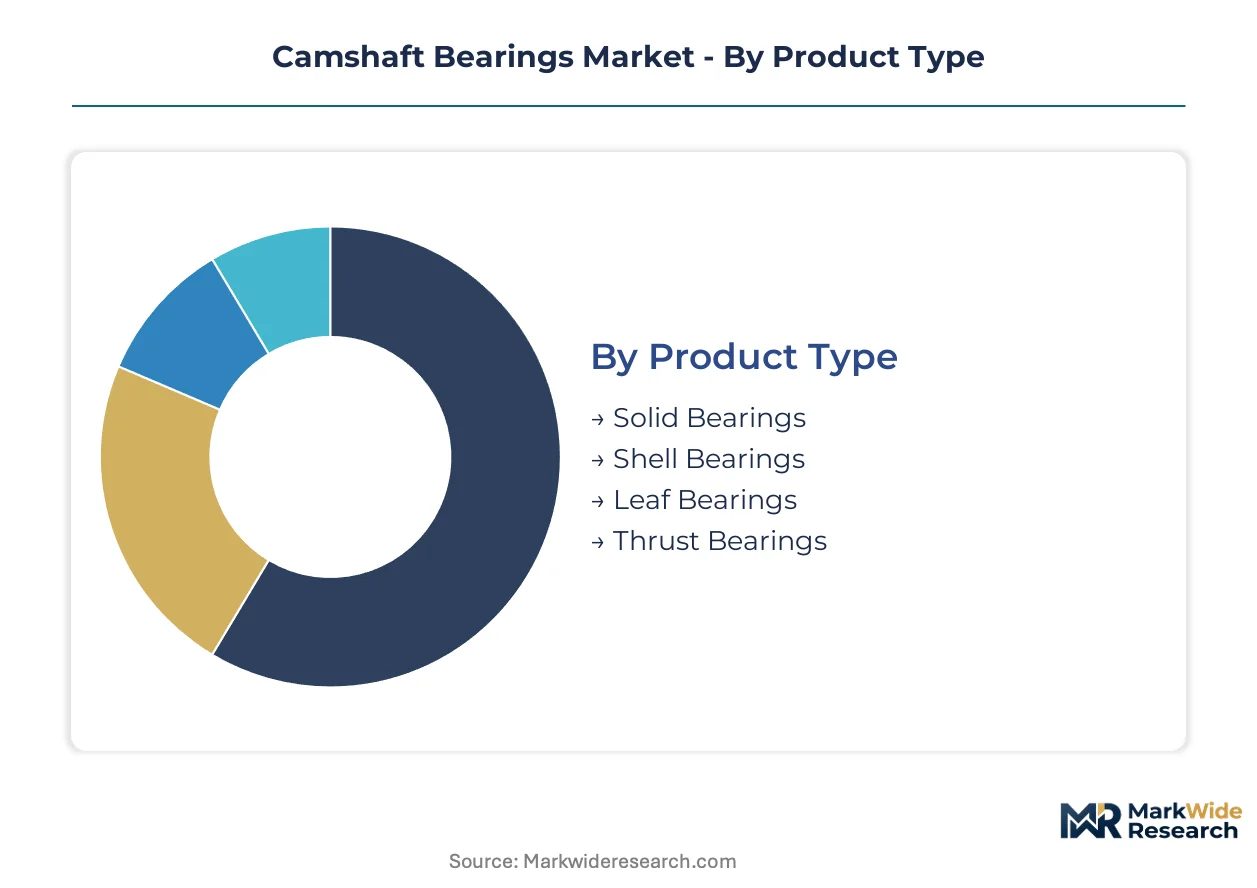
Camshaft bearing specifications diverge sharply between high-volume automotive platforms demanding stamped shell construction and low-volume industrial applications requiring solid bearing dimensional stability. Procurement teams segment supplier qualifications by material overlay chemistry, load cycle profile, and serviceability requirements rather than geometry alone.
Product Type:
Customization intensity spans from catalog-standard shell bearings to application-engineered solid designs, with cost-per-unit and service access driving the specification split.
- Shell Bearings:Stamped steel-backed constructions with bronze or aluminum-tin overlays dominate automotive volume production. Chinese and Indian passenger vehicle OEMs specify these for 48V mild-hybrid valvetrains where replaceability and cost efficiency outweigh absolute load capacity.
- Solid Bearings:Monolithic alloy or cast constructions deliver dimensional stability under sustained radial loads in industrial machinery and marine propulsion systems. German and Italian powertrain divisions specify solid bronze bearings for high-performance engines where thermal expansion tolerance commands premium positioning.
- Leaf Bearings:Multi-layer flexible strip designs accommodate misalignment in agricultural and construction equipment where contamination tolerance exceeds precision requirements.
- Thrust Bearings:Axial load specialists manage camshaft end-float in overhead cam architectures, with Japanese OEMs integrating these into compact dual-overhead-cam cylinder heads.
Leading the category by volume: Shell Bearings. Expanding most quickly: Solid Bearings in hybrid powertrain range-extender applications.
Material:
Cost tier stratification separates commodity steel substrates from performance-engineered composites, with regulatory compliance overlay requirements compressing middle-tier bronze formulations.
- Steel:Backing material standard across all stamped bearing constructions, with Shanghai and Pune foundries sourcing alloy grades from Yangtze Delta mills under annual contract structures vulnerable to input volatility.
- Aluminum:Tin-aluminum overlays displace traditional bronze in EU-bound passenger vehicles meeting Corporate Average Fuel Economy standards and EU Green Deal emissions frameworks. European OEM procurement contracts now mandate aluminum-tin chemistry for new engine platforms.
- Bronze:Leaded bronze overlays face REACH authorization pressure, forcing reformulation to copper-tin-bismuth compositions that extend validation timelines by 12-18 months.
- Composite:Polymer-matrix and polymer-ceramic hybrid overlays penetrate high-performance segments where thermal resilience and mass reduction converge. Chinese OEMs adopt these for start-stop valvetrain cycles.
Steel dominates unit economics. Composite formulations gain share fastest in electrified powertrain architectures.
Application:
Volume concentration versus margin opportunity splits procurement attention between automotive scale and aerospace specification intensity.
- Automotive Engines:Light-duty and commercial vehicle powertrains absorb the majority of bearing volume, with consolidated supplier programs compressing qualified vendor pools from six to two per platform since 2022.
- Industrial Machinery:Compressors, pumps, and stationary power units demand solid bearing durability under continuous operation where service intervals are measured in years, not kilometers.
- Marine Equipment:Saltwater corrosion resistance and seizure tolerance under boundary lubrication conditions specify specialized overlay formulations for propulsion and auxiliary systems.
- Aerospace Systems:FAA and EASA certification requirements for turbine engine and auxiliary power unit bearings impose material traceability and non-destructive testing protocols that exclude general industrial suppliers.
Automotive Engines anchor procurement volume. Aerospace Systems command the steepest specification premiums.
End User:
Customer type determines contract structure, with OEM captive programs demanding design collaboration versus aftermarket catalog selection.
- OEMs:Vehicle and equipment manufacturers consolidate supplier bases to slash qualification costs while demanding captive design collaboration rather than catalog selection. Tier-one powertrain integrators now specify overlay chemistry and bonding processes.
- Aftermarket Providers:Independent distributors and private-label suppliers serve replacement demand in mature vehicle populations, with India's BIS certification expansion streamlining approval pathways for export-grade bearings targeting Middle East and African markets.
- Maintenance Services:Fleet operators and repair facilities prioritize inventory availability and interchangeability over original specification fidelity.
- Distributors:Regional warehousing networks manage SKU proliferation across multiple OEM service part numbers, with margin compression from steel and copper alloy input volatility.
OEMs concentrate procurement value. Aftermarket Providers expand fastest in India's PLI scheme service corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the dominant share of camshaft bearing procurement, with passenger vehicle OEMs in Shanghai and surrounding Yangtze Delta clusters driving aluminum-tin overlay adoption for 48V mild-hybrid architectures.
China
Domestic OEMs expand aluminum bearing procurement to meet MIIT fuel economy mandates and dual carbon goals. SAMR enforces GB standards for automotive component quality. Foundries in Wafangdian and Shanghai scale precision casting capacity for integrated engine systems.
United States
EPA fuel economy mandates and NHTSA safety standards compel bearing reformulation for light-duty truck powertrains. The IRA incentivizes domestic manufacturing reshoring. Tier-one suppliers in Michigan and Ohio consolidate vendor bases to cut qualification costs.
Germany
EU Green Deal emissions frameworks and REACH material compliance requirements drive lead-free bronze overlay reformulation. ECHA authorization timelines extend validation cycles. Powertrain divisions in Stuttgart and Munich absorb retooling costs for copper-tin-bismuth compositions.
India
BIS certification expansion and the PLI scheme for automotive components attract foundry investment near Pune and Chennai. CDSCO oversees material traceability for export-grade bearings. Domestic suppliers target Middle East and African OEMs through streamlined approval pathways.
Japan
METI standards and JIS certification requirements anchor precision bearing specifications for hybrid powertrains. Toyota and Hyundai have compressed qualified camshaft bearing vendor pools since 2022. Nagoya-area powertrain integrators demand captive design collaboration over catalog selection.
Camshaft Bearings Market Vendor Landscape
German and Japanese producers anchor one tier; Chinese and Indian specialists hold volume positions in stamped shell construction. The vendor base concentrates around integrated engine systems providers and precision surface engineering firms. Three archetypes dominate: multi-product powertrain integrators, bearing-focused metallurgy specialists, and regional foundry-scale operators. Competitive moves center on supplier base consolidation by OEMs and captive design collaboration contracts replacing catalog procurement.
Within the integrated systems tier, MAHLE GmbH and SKF occupy positions defined by engine component portfolio breadth and surface engineering capabilities respectively. King Engine Bearings exemplifies the metallurgy specialist archetype, with company nomenclature indicating dedicated engine bearing focus. Wafangdian Bearing Group represents the regional scale operator model, with geographic naming convention signaling Chinese industrial cluster anchoring. These three patterns illustrate how competitive positioning stratifies across technology depth, geographic production concentration, and customer relationship intensity.
| Leading Market Players |
|---|
| Wafangdian Bearing Group |
| King Engine Bearings |
| MAHLE GmbH |
| Precision Camshafts Ltd. |
| Rane Engine Valve Limited |
| Federal-Mogul LLC |
| CCTY Bearing Company |
| ORS Bearings |
| SKF |
| Others |
Supply Flow & Price Mechanics
Performance-grade aluminum-tin overlay bearings command three-to-fourfold premiums over commodity bronze shell constructions, with this divergence manifesting in divergent supply chain configurations: premium chemistries source from German and Japanese metallurgy specialists under long-term offtake contracts, while volume bronze bearings flow through spot-market steel-backed stampings from Yangtze Delta foundries. OEM procurement teams exploit this bifurcation by dual-sourcing commodity tiers while single-sourcing performance grades, compressing margin visibility for mid-tier suppliers caught between input volatility and qualification barriers.
Pricing Analysis
Volume shell bearings trade on thin margins anchored to steel and copper alloy spot indices, while solid bearing constructions for industrial and aerospace applications capture substantial premiums through material traceability and non-destructive testing protocols. Three-tier pricing structure across premium, standard, and economy levels stratifies by overlay chemistry complexity and certification burden, with EU-bound aluminum-tin formulations sitting atop the value ladder. Pricing pressure stems from annual contract structures that expose manufacturers to raw material swings without pass-through mechanisms. Aftermarket distributors exhibit highest price sensitivity, while OEM powertrain divisions prioritize qualification reliability over unit cost.
Supply Chain Analysis
Steel alloy supply rests on Yangtze Delta mills serving Shanghai and Wafangdian foundries, while specialty copper-tin-bismuth chemistries draw from German and Japanese precision metallurgy houses. Bronze overlay feedstock hinges on Chilean copper concentrate and Indonesian tin flows through Singapore trading hubs. Single-region dependency for precision casting capacity in China's Yangtze Delta exposes buyers to logistics disruption and tariff friction. Distribution runs through tier-one powertrain integrators consolidating vendor bases, with captive design collaboration replacing catalog selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer-ceramic hybrid overlays are displacing traditional three-layer steel-bronze-aluminum constructions in 48V mild-hybrid architectures, compressing the technology-transition window for legacy bearing substrate specialists.
For Market Incumbents: Cement supplier base consolidation gains by absorbing tier-two foundries with proven seizure-resistance testing capabilities, insulating against REACH-driven reformulation cost spikes. Prioritize backward integration into aluminum-tin overlay metallurgy to capture OEM mandates for EU Green Deal compliance. Lock long-term offtake agreements with Yangtze Delta steel mills before commodity volatility intensifies. For New Entrants and Emerging Players: Range-extender hybrid powertrain builders in Brazil and Southeast Asia present the most penetrable white-space, as intermittent combustion cycles demand specialized bearing formulations absent from incumbent catalogs. Target India's PLI scheme corridors near Pune and Chennai for foundry partnerships that streamline BIS certification for Middle East and African export programs. Lead with additive manufacturing surface engineering capabilities for low-volume performance engine builders seeking localized overlay customization. For Investors and Strategic Acquirers: Re-rating potential sits with metallurgy specialists possessing copper-tin-bismuth validation data given REACH authorization timelines extending development cycles for competitors. Frame long-term viability around five-to-ten year electrification transition windows where combustion range-extenders sustain bearing demand. Watch Euro 7 preparation divergence from U.S. standards as the inflection signal for redundant testing cost burdens that favor consolidated integrated systems providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Overlay Metallurgy | Captures aluminum-tin chemistry margins mandated by EU Green Deal procurement contracts. |
| Captive Design Collaboration Programs | Replaces catalog selection for Toyota and Hyundai consolidated supplier pools. |
| REACH-Compliant Alloy Validation | Extends seizure-resistance testing timelines for lead-free bronze reformulations. |
| Additive Manufacturing Surface Engineering | Enables localized customization for low-volume performance engine builders. |
| India PLI Scheme Foundry Investment | Streamlines BIS certification for export-grade bearings targeting African OEMs. |
Methodological Framework
Multi-period observation of OEM supplier consolidation patterns and overlay chemistry adoption curves anchored the trend analysis, supplemented by interviews with tier-one powertrain procurement directors, foundry operations managers, and regulatory compliance officers at bearing manufacturers. Secondary validation drew from MIIT fuel economy disclosures, ECHA REACH authorization timelines, EPA fuel economy mandate filings, and BIS certification expansion notices. Bottom-up triangulation across production capacity announcements and top-down reconciliation against vehicle powertrain production databases ensured cross-verification.
Segment-weighting by material chemistry, product construction type, and end-use application intensity drove the analytical framework across the projection horizon. Modeled dimensions spanned steel-backed versus solid bearing geometries, aluminum-tin versus bronze versus composite overlay formulations, and OEM captive versus aftermarket distribution channels. CAGRs derived from slope-consistency checks against historical input cost trajectories and regulatory compliance burden escalation. Forecast inputs incorporated MIIT dual carbon goal enforcement intensity and Euro 7 durability test cycle specifications.
Revisions become necessary when REACH authorization timelines accelerate, Yangtze Delta logistics disruptions materialize, or OEM supplier consolidation reverses toward vendor base expansion. Forecasts reflect documented assumptions regarding alloy substitution elasticity and foundry capacity scaling responsiveness. Regulatory divergence between EU and U.S. emissions standards, raw material price volatility spikes, and tribology engineering talent scarcity constitute the specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Car Rack Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market