
 Two Speed Gearbox Market | 2026-2036
Two Speed Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Two Speed Gearbox Market Analytics
Electric vehicle OEMs is redrawing procurement priorities for two-speed gearboxes as torque-density requirements intensify. ZF Friedrichshafen leverages its integrated e-axle portfolio to anchor premium passenger vehicle programs. Sumitomo Heavy Industries competes through precision manufacturing scale in industrial and marine applications. Bonfiglioli Riduttori specializes in compact hybrid drivetrain architectures for construction equipment.
A two-speed gearbox contains paired gear sets with synchronized shifting mechanisms that alternate between high-torque and high-speed ratios, typically operating at input speeds up to 15,000 rpm in electric drivetrains. Its primary purpose is to extend motor efficiency bands while reducing energy losses across variable load cycles. Manual gearbox configurations retain dominant share in agricultural machinery where cost sensitivity and field-serviceability govern purchasing decisions. Electric-driven technology represents the fastest-expanding segment, though margin pools remain concentrated in dual-clutch gearbox production for heavy vehicles where thermal management complexity sustains pricing power.
The EPA and NHTSA in the United States, alongside the EU Green Deal and REACH frameworks in Europe, shape material compliance and efficiency benchmarking for gearbox housings and lubricants. China's MIIT enforces GB standards for new energy vehicle drivetrain efficiency that directly influence two-speed gearbox specification sheets. Stakeholders must monitor how divergent regional efficiency test cycles alter torque-map calibration requirements across export-bound product lines.
Market Dynamics
Electric drivetrain efficiency mandates are forcing wholesale redesign of power transmission architectures, with dual-ratio systems displacing fixed-gear e-axles across passenger and commercial vehicle platforms.
Growth Catalysts
- EU Green Deal emission benchmarks:The framework compels OEMs to optimize motor operating points, accelerating multi-speed gearbox integration into battery-electric platforms.
- Commercial vehicle electrification:Heavy-duty freight operators demand torque multiplication at launch and sustained high-speed cruising efficiency.
- Silicon carbide inverter pairing:Wide-bandgap power electronics enable higher input speeds, expanding the operational envelope of compact two-speed architectures.
Market Restraints
- Neodymium price volatility:Rare-earth magnet costs in integrated e-axle motors compress margin pools for gearbox suppliers locked into fixed-price contracts.
- German supply concentration:Precision gear machining capacity clusters in Baden-Württemberg and Bavaria, creating single-source vulnerability for synchronized hub production.
- Thermal management complexity:Dual-clutch lubrication systems require specialized coolants that face extended REACH registration timelines.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle component localization create first-mover advantage for gearbox assembly operations.
- Construction equipment hybridization:Wheel loader and excavator OEMs seek compact power-split architectures combining electric and hydraulic torque paths.
- Marine electrification standards:IMO decarbonization targets for harbor craft drive demand for water-cooled two-speed reduction gearboxes.
Industry Challenges
- NVH engineering talent scarcity:Gear whine suppression at 15,000 rpm input speeds requires specialized acoustic simulation expertise concentrated at Tier-1 suppliers.
- Functional safety certification:ISO 26262 ASIL-D compliance for shift actuation systems extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Speed Gearbox Market |
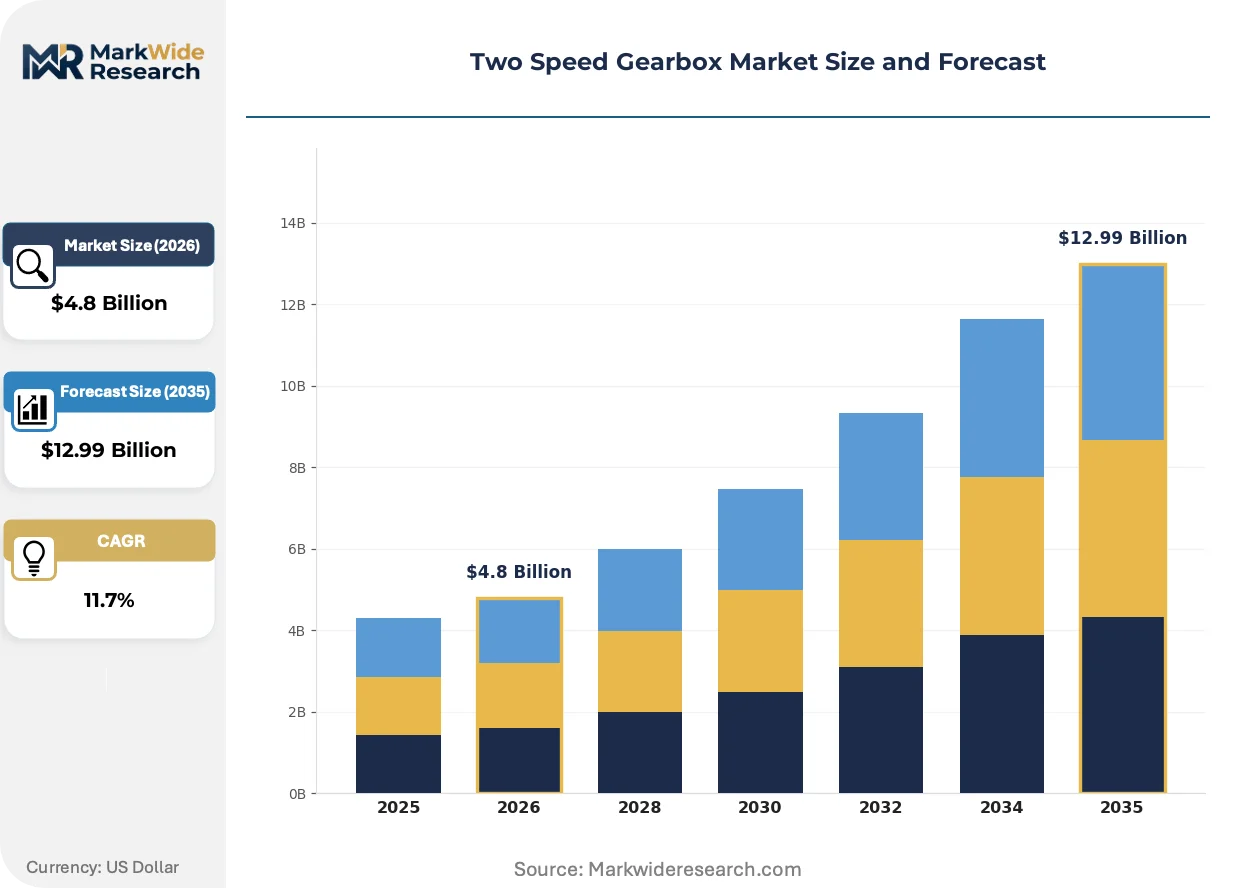
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Gearbox, Automatic Gearbox, Semi-Automatic Gearbox, Dual-Clutch Gearbox End User: Automotive, Industrial Machinery, Marine, Aerospace Technology: Traditional Mechanical, Electric-Driven, Hybrid, Pneumatic Application: Passenger Vehicles, Heavy Vehicles, Construction Equipment, Agricultural Machinery |
| Companies Covered | ZF Friedrichshafen, Sumitomo Heavy Industries, Bonfiglioli Riduttori, SEW-EURODRIVE, Flender, NORD Drivesystems, Siemens, Regal Rexnord Corporation, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Speed Gearbox Market Evolving Landscape
Power density optimization is reshaping mechanical design priorities, with material science and control algorithms converging to enable smaller, thermally robust transmission packages.
Dry-sump lubrication architectures are displacing conventional splash-fed systems in high-performance electric drivetrains. Porsche and Rimac have adopted scavenge-pump designs for their integrated e-axles, eliminating churning losses at sustained high-speed operation. This approach is displacing legacy gearbox formats in the premium passenger segment where efficiency benchmarking determines platform selection.
China's MIIT enforces GB/T 18386 energy consumption test cycles that penalize fixed-gear drivetrains in highway-speed operating modes. Domestic OEMs now specify two-speed gearboxes as baseline equipment for vehicles targeting export certification. The regulation is compressing development timelines for suppliers serving both domestic and European-bound product lines.
Fleet operators are consolidating procurement through powertrain-as-a-service contracts that unbundle hardware ownership from maintenance liability. Leasing providers specify gearbox designs with predictive health monitoring and modular clutch pack replacement. This model is most visible in German commercial vehicle fleets where total-cost-of-ownership calculations dominate acquisition decisions.
Two Speed Gearbox Market Segmentation
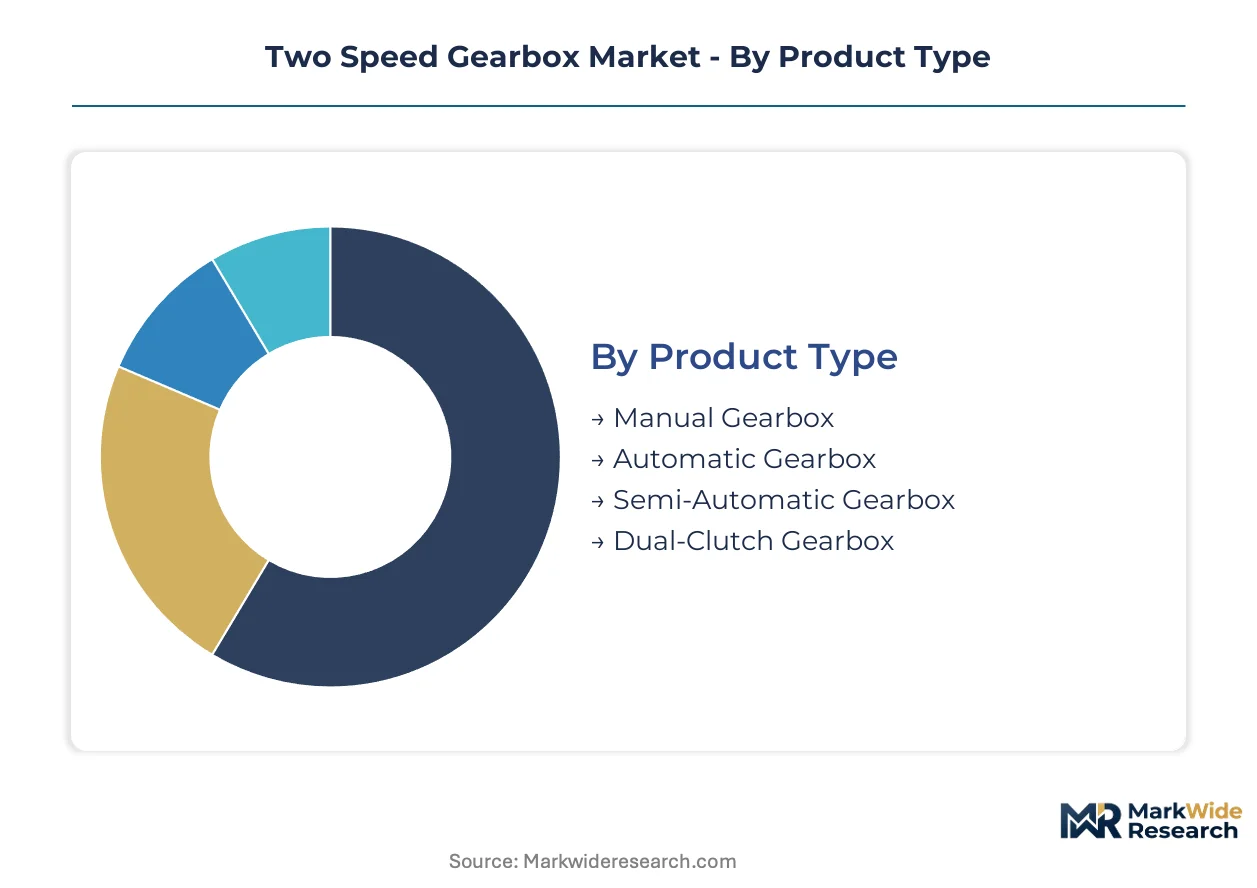
Two-speed gearbox architectures fragment across four critical dimensions that determine procurement specifications and margin structures. Product type governs manufacturing complexity and thermal management requirements. End-user verticals impose divergent duty cycles and certification standards. Technology selection dictates inverter pairing and control system integration. Application context shapes torque-density priorities and service-interval expectations.
Product Type:
Dual-clutch configurations face intensifying substitution pressure from single-speed e-axles in passenger applications, while manual architectures resist displacement in cost-sensitive agricultural and emerging-market commercial segments.
- Manual Gearbox:Synchronized hub and sliding gear mechanisms enable operator-controlled ratio selection without hydraulic actuation. Demand concentrates in Indian and Brazilian agricultural machinery markets where field-serviceability and minimal electronics exposure govern purchasing decisions.
- Automatic Gearbox:Torque converter-coupled planetary sets execute ratio changes through hydraulic pressure modulation without driver intervention. Heavy-vehicle fleets in Germany specify these configurations for urban delivery cycles where stop-start frequency degrades clutch life in manual alternatives.
- Semi-Automatic Gearbox:Automated manual transmissions retain mechanical efficiency while eliminating clutch pedal operation through electropneumatic actuation.
- Dual-Clutch Gearbox:Separate input shafts with alternating clutch engagement deliver sub-200-millisecond shifts for torque-uninterrupted power delivery.
Manual gearbox anchors the volume base in agricultural and price-sensitive commercial applications while dual-clutch configurations gain share at the steepest rate in premium electric passenger platforms.
End User:
Cost-tier differentiation separates capital-intensive marine and aerospace procurements from high-volume automotive programs where per-unit pricing faces continuous compression.
- Automotive:Passenger and commercial vehicle OEMs specify two-speed gearboxes to extend electric motor efficiency maps across highway and urban operating modes. German and Chinese manufacturers lead integration of multi-speed e-axles into dedicated battery-electric platforms.
- Industrial Machinery:Material handling and process equipment deploy two-speed reductions for variable torque demands under intermittent duty cycles.
- Marine:Harbor craft and inland waterway vessels require water-cooled reduction gearboxes to meet IMO decarbonization mandates for port operations.
- Aerospace:Electric vertical takeoff and landing prototypes specify ultra-compact two-stage reductions for rotor speed optimization.
Automotive procurement anchors the volume base while marine applications expand most quickly under regulatory pressure for harbor electrification.
Technology:
Application context drives technology selection, with electric-driven architectures displacing mechanical alternatives in passenger vehicles while pneumatic systems retain niche positions in explosive-environment industrial settings.
- Traditional Mechanical:Hardened steel gear trains with splash or pressure-fed lubrication serve established internal combustion drivetrains and industrial power transmission.
- Electric-Driven:Integrated motor-gearbox units with silicon carbide inverters enable input speeds exceeding 15,000 rpm in compact packages. Chinese GB/T 18386 test cycles penalize fixed-gear alternatives, accelerating domestic OEM adoption of dual-ratio electric architectures.
- Hybrid:Power-split configurations combine mechanical and electric torque paths for construction equipment requiring both launch traction and sustained hydraulic power.
- Pneumatic:Compressed-air actuation eliminates ignition risk in mining and petrochemical processing environments.
Traditional mechanical technology anchors the installed base while electric-driven configurations climb the fastest under efficiency mandates and inverter technology advancement.
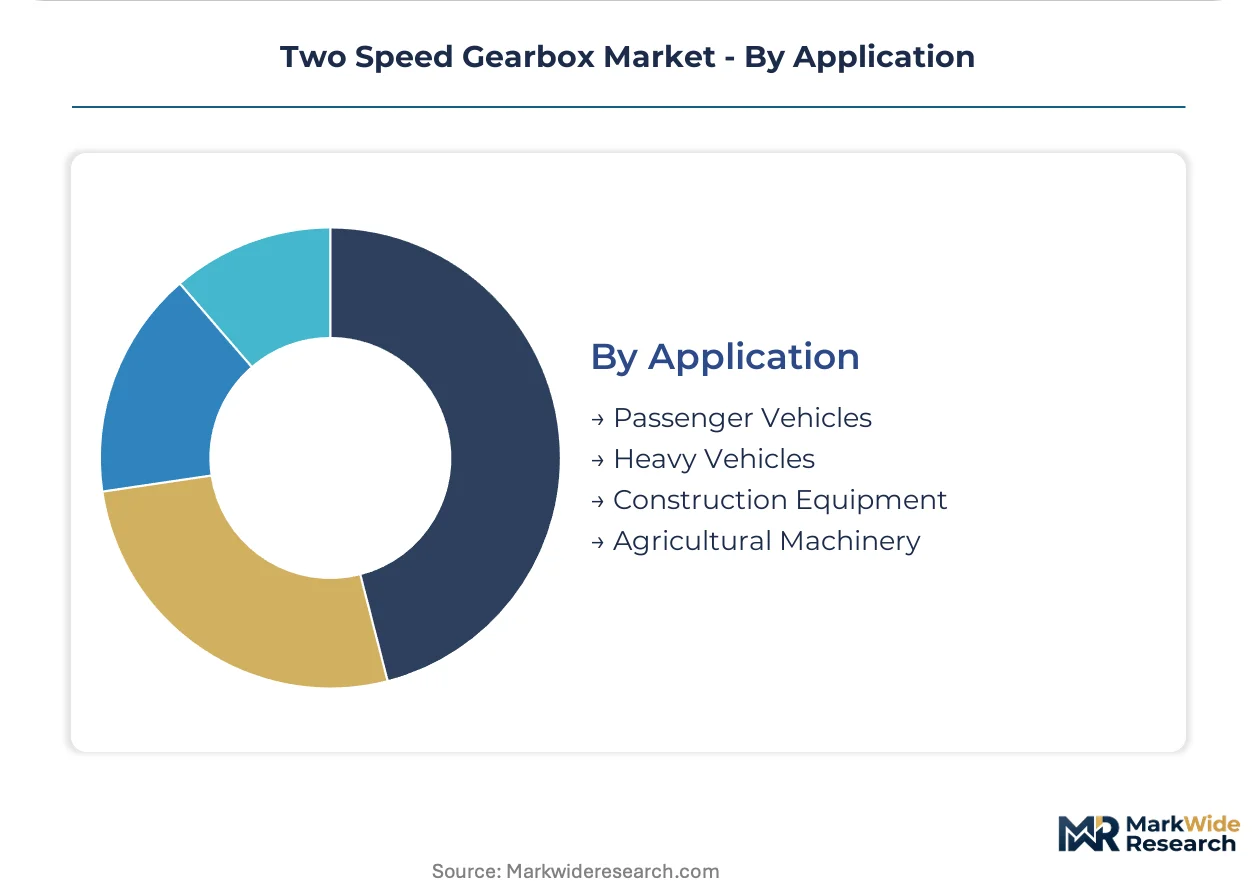
Application:
Volume concentration in passenger vehicles contrasts with margin concentration in heavy vehicles where thermal management complexity and durability specifications sustain pricing power.
- Passenger Vehicles:Compact dual-clutch and single-shaft two-speed units optimize electric motor operating points across urban and highway cycles. Porsche and Rimac production programs validate dry-sump lubrication architectures for sustained high-speed efficiency.
- Heavy Vehicles:Dual-ratio e-axles address the conflicting demands of launch torque multiplication and sustained cruising efficiency in battery-electric freight applications. German commercial fleet operators specify predictive health monitoring and modular clutch replacement through powertrain-as-a-service contracts.
- Construction Equipment:Wheel loaders and excavators demand power-split architectures combining electric and hydraulic torque paths for intermittent high-load cycles.
- Agricultural Machinery:Manual two-speed transmissions dominate tractor and combine applications where cost sensitivity and field-serviceability override automation benefits.
Passenger vehicle applications anchor the volume base while heavy vehicle segments gain share at the steepest rate under commercial electrification mandates and total-cost-of-service procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in industrialized manufacturing clusters where tier-one drivetrain suppliers maintain integrated engineering centers. Fleet operators in Germany and China dominate commercial vehicle electrification programs. Marine and industrial buyers distribute across harbor cities and heavy machinery manufacturing belts.
Germany
Baden-Württemberg and Bavaria house precision gear machining clusters serving domestic OEM e-axle programs. The EU Green Deal emission benchmarks compel drivetrain redesigns across passenger and commercial platforms. Stuttgart-based engineering centers coordinate multi-speed gearbox integration for next-generation battery-electric architectures.
China
Domestic OEMs specify two-speed gearboxes as baseline equipment under MIIT-enforced GB/T 18386 energy consumption test cycles. The country's dual carbon goals accelerate adoption of dual-ratio electric drivetrains in export-bound vehicle lines. Yangtze River Delta manufacturing corridors concentrate motor-gearbox assembly operations for both domestic and European markets.
United States
EPA and NHTSA efficiency standards shape gearbox housing material compliance and lubricant specifications. Commercial fleet operators in the Midwest specify predictive health monitoring through powertrain-as-a-service contracts. Michigan and Ohio industrial corridors anchor heavy-vehicle electrification engineering for freight applications.
Japan
METI industrial policy supports precision manufacturing scale for integrated e-axle components. JIS standards govern torque-density benchmarking for compact two-speed architectures in passenger vehicles. Kansai and Chubu manufacturing regions concentrate hybrid drivetrain development for construction equipment applications.
India
PLI scheme incentives for electric vehicle component localization attract gearbox assembly investments. Agricultural machinery demand concentrates in Maharashtra and Gujarat where manual two-speed transmissions dominate tractor procurement. Domestic commercial vehicle OEMs pilot dual-ratio e-axles for urban delivery cycles under BIS efficiency guidelines.
Two Speed Gearbox Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive drivetrain divisions. Market structure exhibits moderate consolidation with tier-one automotive suppliers holding premium passenger vehicle positions while specialized gear manufacturers serve industrial and marine verticals. Three strategic archetypes dominate: integrated e-axle system houses, precision gear machining specialists, and diversified power transmission conglomerates. Competitive moves center on silicon carbide inverter pairing partnerships and dry-sump lubrication technology licensing.
Within the integrated system house tier, ZF Friedrichshafen and Aisin Corporation represent archetypes of automotive-tier suppliers extending into electrified drivetrain architectures. Among diversified industrial conglomerates, Siemens and Sumitomo Heavy Industries occupy positions spanning automation, heavy machinery, and marine applications. SEW-EURODRIVE and NORD Drivesystems exemplify mid-scale specialists concentrated in industrial power transmission where modular platform strategies sustain margin pools.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Sumitomo Heavy Industries |
| Bonfiglioli Riduttori |
| SEW-EURODRIVE |
| Flender |
| NORD Drivesystems |
| Siemens |
| Regal Rexnord Corporation |
| Aisin Corporation |
| Others |
Value Network & Pricing Analysis
Silicon carbide inverter substitution for conventional silicon IGBTs is redrawing supplier geography and pricing economics across the two-speed gearbox value chain, compressing margin pools for legacy machining clusters in Baden-Württemberg while elevating power electronics integration premiums for Yangtze River Delta assembly operations.
Pricing Analysis
Fixed-gear e-axle pricing versus dual-clutch two-speed systems versus dry-sump integrated architectures stratifies across premium, standard, and economy tiers based on thermal management complexity and shift-actuation certification grade. Price differentiation separates ISO 26262 ASIL-D validated units from lower-tier alternatives, with German commercial fleet operators showing lowest sensitivity through powertrain-as-a-service contracts while Indian agricultural OEMs resist automation premiums. Pricing pressure stems from neodymium magnet cost volatility in integrated e-axle motors, forcing gearbox suppliers into fixed-price contract renegotiations.
Supply Chain Analysis
Strait of Malacca transit underwrites rare-earth magnet flows from Chinese processing facilities to German precision gear machining centers in Bavaria. Supply geography clusters in China for neodymium processing, Germany for synchronized hub production, and Japan for compact bearing assemblies. Raw material dependencies span rare-earth magnets, hardened alloy steel gear blanks, and specialized REACH-compliant lubricants. Single-source vulnerability concentrates in Baden-Württemberg precision machining capacity. Distribution runs through tier-one automotive supplier networks with captive e-axle integration lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Two-speed gearbox demand is accelerating under EU Green Deal emission benchmarks and China's MIIT-enforced efficiency test cycles, creating a high-growth disruption window where drivetrain electrification mandates outpace incumbent supplier adaptation capacity.
For Market Incumbents: Secure silicon carbide inverter pairing partnerships before wide-bandgap power electronics consolidate around dominant semiconductor suppliers, and lock in long-term rare-earth magnet offtake agreements to defend margin position against neodymium price volatility. Capacity expansion in Yangtze River Delta assembly corridors captures Chinese OEM dual-ratio specification momentum.
For New Entrants and Emerging Players: Lead with construction equipment hybridization programs where power-split architecture demand outpaces established supplier coverage, targeting wheel loader and excavator OEMs seeking electric-hydraulic torque path integration. Field-serviceable manual gearbox designs for Indian agricultural machinery offer lowest competitive density.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision gear machining specialists with captive dry-sump lubrication IP and ISO 26262 certification infrastructure. Long-term viability hinges on e-axle integration depth rather than standalone gearbox production. Watch silicon carbide inverter adoption rates in German premium passenger platforms as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Partnership | Enables 15,000 rpm input speeds that expand compact two-speed operational envelopes for Porsche and Rimac programs. |
| Dry-Sump Lubrication Licensing | Eliminates churning losses at sustained high-speed operation, differentiating premium passenger e-axle offerings. |
| ISO 26262 ASIL-D Certification Investment | Extends development cycles but unlocks German commercial fleet procurement through functional safety compliance. |
| Rare-Earth Magnet Backward Integration | Reduces neodymium price volatility exposure that compresses margin pools in fixed-price gearbox contracts. |
| India PLI Scheme Manufacturing Footprint | Captures component localization incentives for electric vehicle gearbox assembly serving domestic OEM pilot programs. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-one supplier technical documentation anchors the qualitative findings, combining structured interviews with drivetrain procurement directors, e-axle integration engineers, and aftermarket service heads with secondary validation through EPA efficiency filings, MIIT GB standard publications, and EU Green Deal regulatory impact assessments. Bottom-up production volume estimates and top-down market sizing triangulate around segmentation dimensions spanning propulsion architecture, vehicle class, and regional regulatory cluster.
Sensitivity analysis across rare-earth magnet price scenarios and silicon carbide adoption curves shapes the analytical framework over the projection horizon, with CAGRs derived from segment-level production forecasts weighted by content-per-vehicle assumptions. Modeled dimensions include gearbox product type, end-user vertical, technology architecture, and application context, with forecast inputs spanning battery-electric platform rollout schedules and commercial fleet electrification mandates.
Forecasts assume regulatory continuity in EU Green Deal emission benchmarks and China's MIIT GB/T 18386 enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as neodymium supply chain reconfigurations and REACH lubricant registration timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Global Automotive Jacks Market