
 China Automotive Lubricants Market | 2026-2036
China Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Lubricants Market Outlook
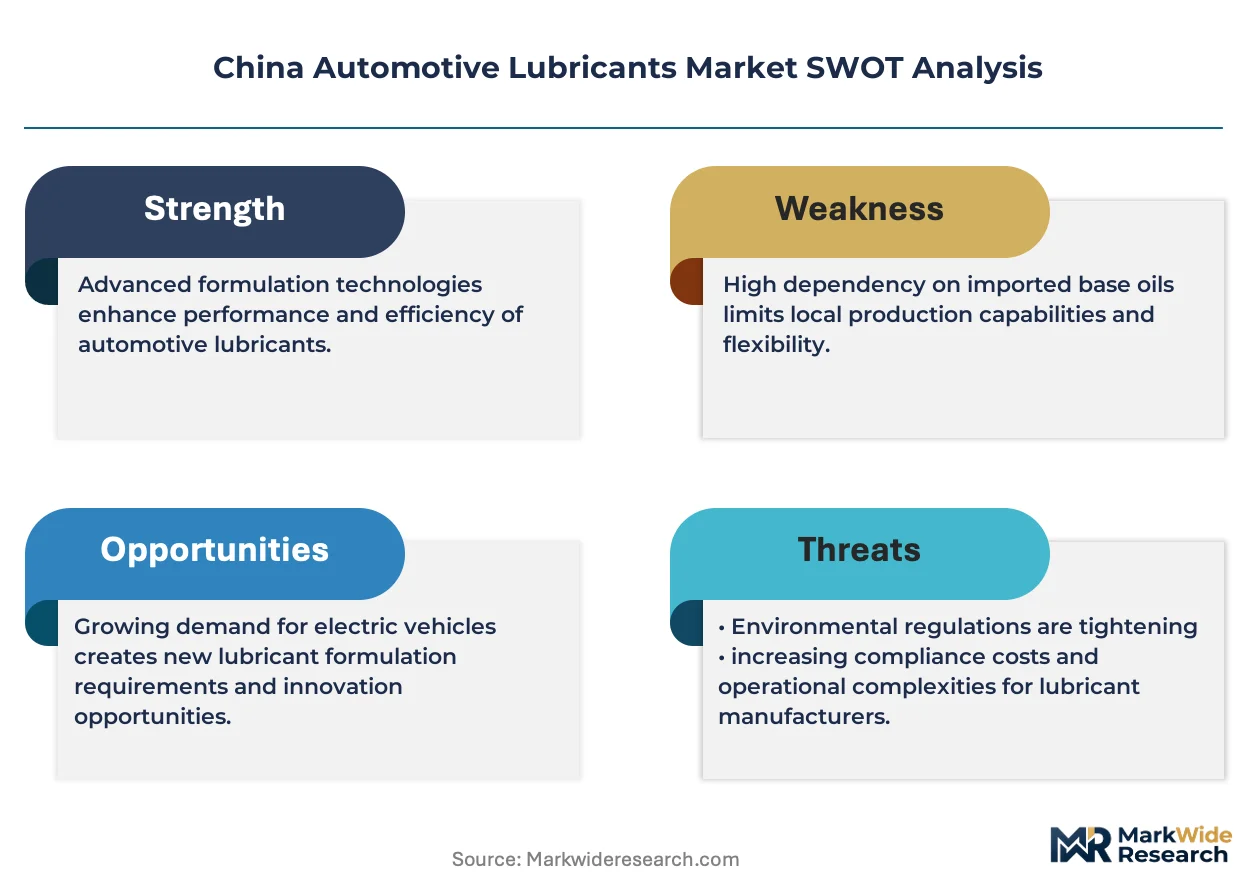
Shandong Province is reconfiguring its petrochemical hub status through expanded base oil refining and additive blending capacity. China National Petroleum Corporation leverages integrated upstream refining to sustain cost advantages across northern distribution networks. Jiangsu Lopal Tech Co., Ltd. anchors its position in synthetic formulations for passenger vehicle service centers. Shell plc competes through premium positioning in coastal metropolitan markets.
China automotive lubricants comprise formulated oils and functional fluids engineered from Group I–III base stocks and polyalphaolefin synthetics, with viscosity grades typically spanning SAE 0W-20 to 15W-40 and additive packages containing detergents, dispersants, and anti-wear agents such as zinc dialkyldithiophosphate. These formulations reduce friction, dissipate heat, and prevent component degradation in internal combustion and hybrid powertrains. Engine Oil commands the dominant revenue share due to high replacement frequency and OEM fill requirements, while Transmission Fluid generates premium margins as automatic and dual-clutch penetration deepens. Fleet Operators represent the fastest-growing end user channel as logistics consolidation drives centralized procurement and bulk purchasing agreements.
MIIT enforces fuel economy standards that elevate demand for low-viscosity lubricants, while SAMR administers product quality certifications that filter substandard formulations from retail channels. The GB standards system mandates periodic updates to lubricant performance classifications, compelling reformulation investments. Stakeholders must monitor NEV powertrain lubricant compatibility as battery-electric and range-extended hybrid architectures redefine fluid thermal management requirements.
Market Dynamics
MIIT fuel economy mandates and NEV powertrain proliferation are compressing demand for conventional high-viscosity engine oils while elevating thermal management fluid complexity. Base oil refining capacity in Shandong Province and additive formulation expertise in Jiangsu are concentrating supply-side leverage among integrated domestic producers.
Growth Catalysts
- Fleet Operator Consolidation:Logistics platform centralization drives bulk lubricant procurement contracts with standardized viscosity specifications and predictive drain-interval analytics.
- GB Standards Escalation:Periodic performance classification updates under SAMR certification protocols force continuous reformulation investment, filtering substandard competitors from retail channels.
- Hybrid Powertrain Penetration:Range-extended architectures require dedicated thermal management fluids with dielectric compatibility and extended oxidation stability.
Market Restraints
- Group II/III Base Oil Import Dependency:High-quality feedstock supply concentrates among integrated state-owned refiners, constraining independent blender margin flexibility.
- NEV Displacement Trajectory:Battery-electric powertrain proliferation eliminates engine oil demand entirely in pure BEV segments.
- Additive Package Cost Volatility:Zinc dialkyldithiophosphate and detergent precursor prices fluctuate with phosphate rock and petrochemical feedstock markets.
Strategic Opportunities
- Central China Logistics Corridors:Henan and Hubei provinces exhibit underpenetrated fleet service infrastructure relative to Yangtze River Delta density.
- Thermal Management Fluid Diversification:Battery coolant and e-motor grease formulations address NEV-specific dielectric and thermal conductivity requirements absent in ICE architectures.
- Synthetic Formulation Premiumization:Polyalphaolefin and ester-based products command pricing separation in coastal metropolitan service centers.
Industry Challenges
- Formulation Talent Scarcity:Lubricant chemists with NEV thermal management expertise remain concentrated among additive majors and state research institutes.
- Dual Certification Timelines:Parallel OEM factory-fill approval and SAMR aftermarket certification extend product launch cycles.
- Legacy Distribution Integration:Traditional automotive service channel relationships require reconfiguration for direct fleet and digital platform sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Lubricants Market |
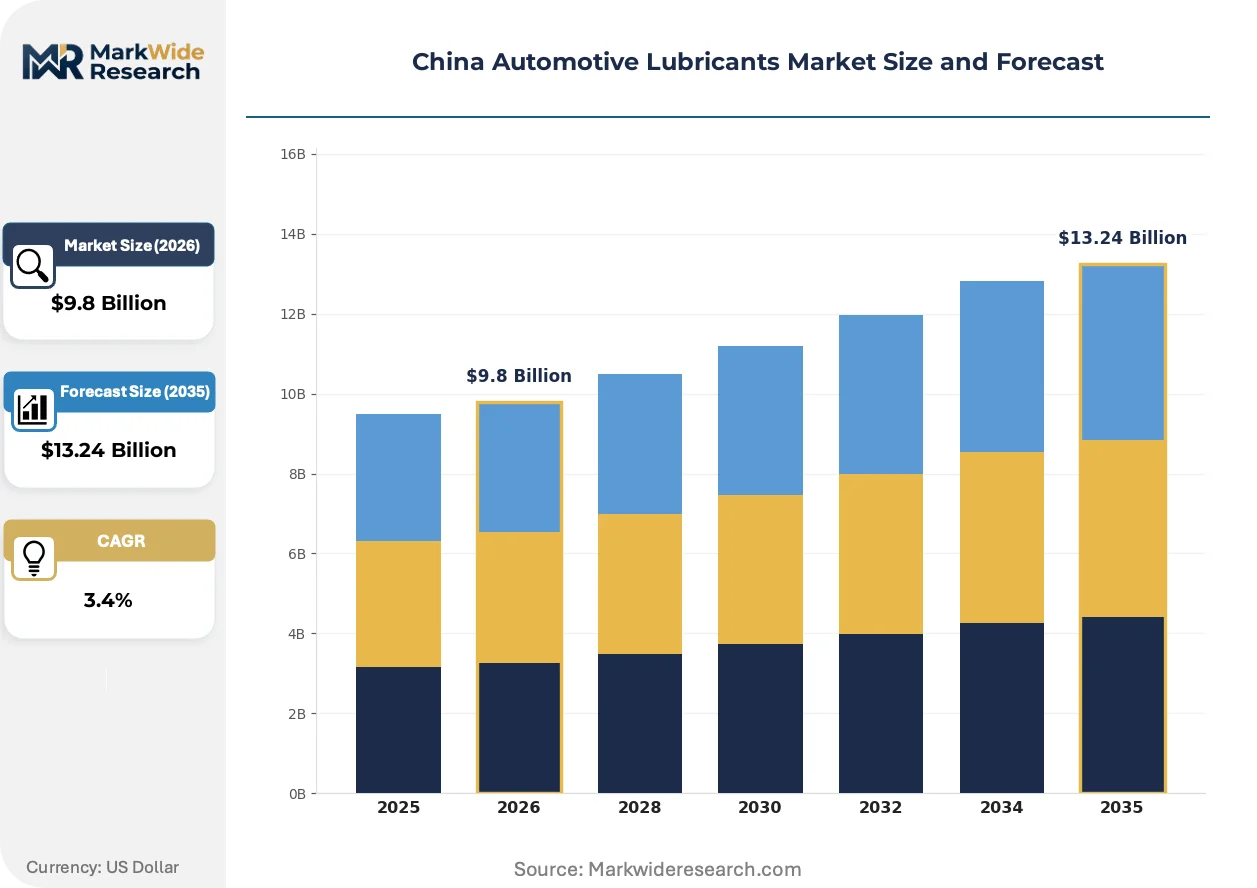
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $13.24 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Fluid End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Operators Distribution Channel: Retail Stores, Online Platforms, Auto Service Centers, Wholesale Application: Engine Lubrication, Gear Lubrication, Hydraulic Systems, Cooling Systems |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, China National Petroleum Corporation, Tongyi Petrochemical Co., Ltd., Jiangsu Lopal Tech Co., Ltd., China Petroleum & Chemical Corporation, BP PLC, Qingdao COPTON Technology Co., Ltd., Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Lubricants Market Strategic Shifts
Sensor-embedded lubricant monitoring and predictive maintenance algorithms are compressing traditional fixed-interval drain schedules. Formulation chemistry, regulatory compliance protocols, and procurement contracting models are evolving in parallel.
Smart lubricant condition monitoring is digitizing fleet maintenance operations. Telemetrics-equipped commercial vehicles transmit real-time viscosity, oxidation, and contamination data to centralized fleet management platforms. Predictive algorithms calculate remaining useful life, eliminating calendar-based drain intervals and compressing lubricant consumption volumes per vehicle-mile.
MIIT fuel economy standards are tightening low-viscosity lubricant specifications across passenger vehicle OEM fill requirements. SAE 0W-20 and 0W-16 grades displace 5W-30 formulations in new vehicle production. Domestic automakers accelerate factory-fill approvals for synthetic formulations to meet corporate average fuel consumption targets.
Logistics platform procurement is consolidating aftermarket demand around national account pricing structures. E-commerce fleet operators and ride-hailing aggregators negotiate centralized lubricant supply agreements with volume-tiered pricing and embedded technical service support. This channel shift concentrates purchasing power among platform intermediaries, compressing traditional distributor margins in tier-one cities.
China Automotive Lubricants Market Segmentation
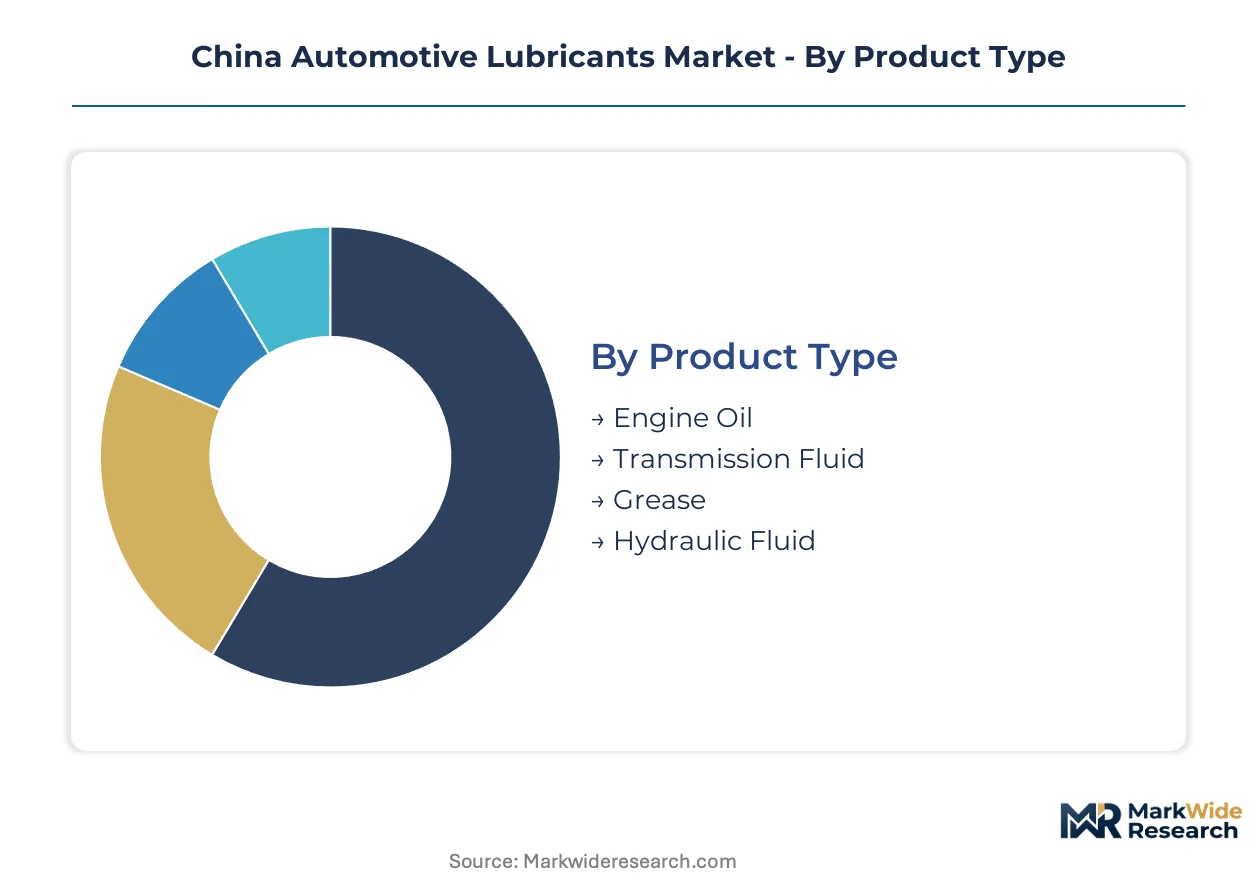
Segmentation in China's automotive lubricants market reveals how product specifications, procurement channels, and powertrain architectures diverge across customer types. Understanding these splits exposes where formulation investments concentrate and which distribution pathways are compressing.
Product Type:
Use-case spectrum spans friction reduction in combustion powertrains to thermal management in electrified architectures.
- Engine Oil:Formulated from Group II/III base stocks with SAE 0W-20 to 15W-40 viscosity grades, these lubricants reduce piston ring friction and dissipate combustion heat. Demand concentrates in passenger vehicle service centers across the Yangtze River Delta as MIIT fuel economy mandates tighten low-viscosity specifications.
- Transmission Fluid:Synthetic formulations for automatic and dual-clutch transmissions deliver shear stability and extended drain intervals. Fleet operators in Shandong Province are negotiating bulk procurement contracts for standardized ATF specifications as logistics platform consolidation accelerates.
- Grease:Lithium-complex and polyurea-thickened lubricants protect chassis components and wheel bearings from water ingress and high-load wear.
- Hydraulic Fluid:Anti-wear formulations with zinc-free additive packages serve commercial vehicle braking and steering systems requiring fire-resistance ratings.
The dominant share belongs to Engine Oil, while Transmission Fluid is closing the gap fastest.
End User:
Cost tier segmentation separates premium synthetic adopters from bulk procurement price-optimizers.
- Fleet Operators:Centralized lubricant procurement through logistics platforms drives predictive drain-interval analytics and national account pricing. Henan and Hubei provinces exhibit underpenetrated service infrastructure relative to coastal density, creating expansion corridors.
- Passenger Vehicles:Individual owners purchasing through retail channels or OEM-affiliated service centers prioritize factory-fill approved formulations for warranty compliance.
- Commercial Vehicles:Owner-operators and small fleet managers balance extended drain synthetic premiums against total cost of ownership calculations.
- Two-Wheelers:High-replacement-frequency lubricants for motorcycles and scooters move through independent repair shops with minimal brand loyalty.
Fleet Operators command the steepest expansion trajectory, while Passenger Vehicles retain the largest volume base.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements.
- Auto Service Centers:Franchise and independent workshops combine lubricant sales with maintenance bundling, capturing margin through technical diagnostics and OEM certification compliance.
- Wholesale:Bulk distribution to fleet depots and industrial buyers leverages volume-tiered pricing with embedded fluid analysis services.
- Online Platforms:E-commerce penetration concentrates in tier-one cities where price transparency and direct-to-consumer logistics compress traditional distributor margins.
- Retail Stores:Hypermarkets and automotive specialty chains serve emergency top-up demand and price-sensitive DIY segments.
Auto Service Centers anchor current volume, though Wholesale is gaining share fastest through fleet platform consolidation.
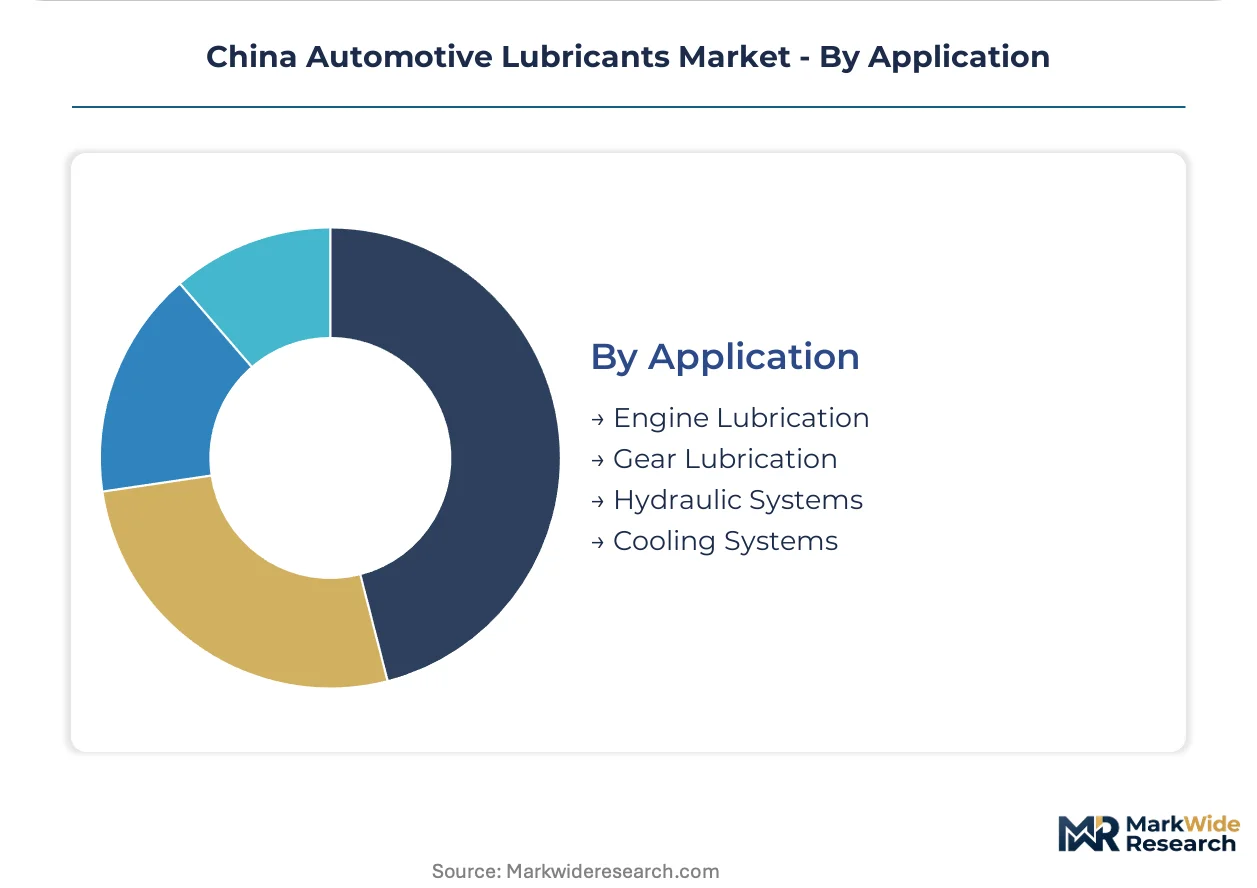
Application:
Functional segmentation tracks how powertrain electrification is redrawing fluid requirements.
- Engine Lubrication:Conventional crankcase oils face demand compression as battery-electric powertrains eliminate internal combustion entirely in pure BEV segments.
- Cooling Systems:Battery coolant and e-motor thermal management fluids with dielectric compatibility address NEV-specific requirements absent in ICE architectures, commanding formulation premiums.
- Gear Lubrication:Axle and differential oils for commercial vehicle drivetrains maintain steady replacement cycles independent of electrification trends.
- Hydraulic Systems:Power steering and brake fluids face gradual displacement by electro-mechanical actuation in advanced driver-assistance platforms.
Engine Lubrication retains dominant share, while Cooling Systems is climbing the fastest on NEV penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT anchors the dominant geography through fuel economy mandates that reshape lubricant specifications across provincial manufacturing clusters. GB standards enforcement varies by regional industrial density.
Yangtze River Delta
Passenger vehicle production concentration in Shanghai and Jiangsu drives premium synthetic demand. SAMR certification protocols filter substandard formulations from retail channels in this corridor. Jiangsu Lopal Tech Co., Ltd. anchors synthetic formulation capacity for service centers across Suzhou and Nanjing.
Shandong Peninsula
Base oil refining capacity expansion in Qingdao and Yantai concentrates supply-side leverage among integrated producers. GB standards escalation forces continuous reformulation investment from independent blenders. Fleet operators in Jinan negotiate bulk procurement contracts with predictive drain-interval analytics.
Pearl River Delta
NEV powertrain proliferation in Shenzhen and Guangzhou compresses conventional engine oil demand while elevating thermal management fluid complexity. MIIT dual carbon goals accelerate battery-electric factory fill approvals. Cooling system fluid specialists occupy positions in Dongguan manufacturing zones.
Beijing-Tianjin-Hebei
Logistics platform centralization around Tianjin Port drives national account pricing structures for fleet lubricant procurement. SAMR administers product quality certifications that govern aftermarket channel access. China National Petroleum Corporation leverages integrated upstream refining across northern distribution networks.
Sichuan-Chongqing
Underpenetrated fleet service infrastructure in western China creates expansion corridors for centralized procurement models. MIIT fuel economy standards tighten low-viscosity specifications for passenger vehicles manufactured in Chongqing. Chengdu-based distributors develop digital platform sales channels for direct fleet engagement.
China Automotive Lubricants Market Competitive Environment
Capability concentration sits with additive formulation specialists; scale advantage sits with integrated state-owned refiners. The vendor base organizes around three tiers: multinational premium-positioned players, domestic integrated producers with captive base oil supply, and independent blenders serving price-optimized segments. Two strategic archetypes dominate competitive positioning: synthetic formulation premiumizers and fleet procurement consolidators. Capacity expansion in Shandong Province and backward integration into base oil refining represent the dominant competitive moves.
Within the integrated state-owned tier, China National Petroleum Corporation and China Petroleum & Chemical Corporation exemplify scale-driven positioning through captive refining assets and northern distribution network control. Shell plc occupies a premium-tier position in coastal metropolitan markets, competing through factory-fill approval depth and technical service bundling. Jiangsu Lopal Tech Co., Ltd. represents the domestic specialist archetype, anchoring synthetic formulation capabilities for passenger vehicle service centers in the Yangtze River Delta manufacturing corridor.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| China National Petroleum Corporation |
| Tongyi Petrochemical Co., Ltd. |
| Jiangsu Lopal Tech Co., Ltd. |
| China Petroleum & Chemical Corporation |
| BP PLC |
| Qingdao COPTON Technology Co., Ltd. |
| Shell plc |
| Others |
Value Chain & Pricing Dynamics
Base oil overcapacity in Shandong Province compresses feedstock costs for integrated refiners while squeezing independent blender margins, creating divergent pricing power between state-owned producers and regional formulators.
Pricing Analysis
Coastal metropolitan markets command 15-25% premiums over inland provinces for identical SAE-grade formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by base oil group and SAMR certification tier. Price differentiation stems from synthetic content ratio and factory-fill approval depth. Fleet operators in Henan and Hubei exhibit highest price sensitivity due to thin logistics margins, while Yangtze River Delta service centers absorb premium synthetic markups for OEM warranty compliance. Cost compression in the independent blender tier is intensifying because Group II/III import dependency erodes margin flexibility against captive-refiner competition.
Supply Chain Analysis
Integrated base oil refining concentrates among China National Petroleum Corporation and China Petroleum & Chemical Corporation facilities in Shandong and Liaoning provinces. Formulation chemistry draws from phosphate rock derivatives for ZDDP anti-wear additives and polyalphaolefin feedstocks from petrochemical crackers. Single-source vulnerability sits with additive package supply from Lubrizol, Infineum, and Afton Chemical concentration. Distribution runs through state-owned petroleum wholesale networks to regional depots, with final-mile delivery via franchised service centers and direct fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vehicle utilization cycles are recovering from trough levels, with logistics platform consolidation acting as the cyclical driver pulling lubricant procurement volumes upward through centralized fleet contracts.
For Market Incumbents: Pre-empt NEV thermal management fluid displacement by accelerating battery coolant and e-motor grease formulation approvals before pure BEV penetration eliminates conventional engine oil demand in premium passenger segments. Secure backward integration into Group III base oil refining in Shandong to defend margin position against independent blender price erosion. Deepen SAMR certification moats through parallel OEM factory-fill investment to extend product launch cycle advantages. For New Entrants and Emerging Players: Central China logistics corridors in Henan and Hubei represent the most penetrable entry point, where fleet service infrastructure remains underdeveloped relative to coastal density and national account pricing structures have not yet consolidated procurement. Target thermal management fluid specialization for range-extended hybrid architectures, where dielectric compatibility requirements create formulation complexity barriers. Pursue direct digital platform sales channels to bypass entrenched distributor relationships in tier-one cities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet procurement consolidators with embedded predictive maintenance analytics and multi-year bulk supply agreements. Long-term viability over a 5-10 year window favors additive formulation specialists with NEV thermal management expertise concentrated among state research institutes. Monitor MIIT fuel economy mandate tightening velocity as the inflection indicator signaling synthetic formulation premium acceleration or conventional lubricant demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Refining | Captive feedstock supply insulates margin pressure from import dependency volatility. |
| NEV Thermal Management Fluid Development | Battery coolant and e-motor grease address dielectric requirements absent in ICE architectures. |
| Fleet Platform Direct Procurement Contracts | National account pricing with predictive analytics compresses traditional distributor channel margins. |
| SAMR Certification Parallel to OEM Factory-Fill | Dual approval timelines extend competitive moats against faster-moving independent blenders. |
| Synthetic Formulation Premium Positioning | Polyalphaolefin products command pricing separation in Yangtze River Delta service centers. |
Study Parameters
The analysis maps engine oil, transmission fluid, grease, and thermal management fluid sub-sectors, each validated through lubricant chemists, fleet procurement managers, aftermarket distributors, and OEM platform engineers. Primary interviews with additive formulation specialists and state refinery planning officers combined with secondary validation from MIIT fuel economy filings, SAMR certification registries, customs base oil import data, and vehicle production databases. Bottom-up volume triangulation across viscosity grades and end-user channels reconciled with top-down market sizing from integrated producer capacity disclosures.
Assumptions held fixed include MIIT corporate average fuel consumption targets and GB standards enforcement intensity, while NEV penetration trajectories and logistics platform consolidation rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end-user archetype, distribution channel, and propulsion architecture across the analysis window. CAGRs derived from regression against commercial vehicle utilization indices and synthetic formulation adoption curves, with thermal management fluid complexity and fleet procurement centralization as key forecast inputs.
Practitioners should monitor NEV powertrain proliferation velocity and Group II/III base oil import tariff adjustments for early signals of demand structure shifts. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock supply continuity. Quarterly review of MIIT mandate updates and fleet platform procurement contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Friction Pads Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market