
 Automotive Piston System Market | 2026-2036
Automotive Piston System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Piston System Market Outlook
ISO/TS 16949 qualification is unwinding the supplier base as tier-2 foundries lose certification access. MAHLE GmbH leverages its captive aluminum casting network across Central Europe to sustain OEM supply agreements. Tenneco Inc. anchors North American aftermarket distribution through its Federal Mogul heritage channels. Aisin Seiki competes on thermal coating patents that extend piston life in downsized turbo engines.
An automotive piston system comprises the piston crown, ring belt, pin bore, and skirt assembly, typically forged from hypereutectic aluminum-silicon alloys with graphite or molybdenum disulfide skirt coatings to reduce cylinder wall friction and manage thermal expansion under combustion pressures exceeding 18 MPa. Its primary purpose is converting expanding gas energy into reciprocating mechanical motion while maintaining compression seals across varying temperature loads. Multi cylinder configurations dominate volume production for passenger car applications where bore spacing standardization drives platform economics. Aluminum alloys capture the majority material share due to weight advantages over cast iron, though steel pistons retain structural preference in heavy-duty diesel segments where peak cylinder pressures exceed 22 MPa.
EPA tailpipe standards and the EU Green Deal's CO2 fleet targets are compressing development cycles for low-friction piston architectures that support downsized engine efficiency gains. China's MIIT enforces GB 18352 emission tiers that disqualify conventional cast iron pistons from new vehicle type approvals. NHTSA corporate average fuel economy benchmarks in the United States push OEMs toward anodized ring groove treatments that reduce blow-by oil consumption. Stakeholders must monitor how electrification timelines alter ICE investment thresholds and whether hybrid duty cycles create sustained demand for pistons optimized for intermittent combustion regimes.
Market Dynamics
ICE downsizing mandates from Beijing to Brussels are compressing piston architecture development cycles, forcing suppliers to requalify thermal coating formulations for higher cylinder pressures while electrification timelines erode long-term capital planning horizons.
Growth Catalysts
- GB 18352.6-2016 Emission Tiers:China's MIIT enforcement disqualifies conventional cast iron pistons from new vehicle type approvals, accelerating aluminum alloy penetration in domestic OEM sourcing.
- Commercial Fleet Replacement Cycles:Asia-Pacific logistics operators are compressing piston assembly changeout intervals to 450,000 kilometers, expanding aftermarket volume for ring belt and skirt subassemblies.
- Hypereutectic Al-Si Alloys:Advanced aluminum-silicon compositions with 17-26% silicon content enable thinner crown designs that withstand peak combustion pressures above 20 MPa in downsized turbocharged engines.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum contract swings above $2,400 per tonne compress foundry margins and trigger force majeure clauses in annual OEM supply agreements.
- ISO/TS 16949 Certification Concentration:Tier-2 foundries in Central Europe and North America are losing quality system access, reducing qualified supplier pools for just-in-time piston deliveries.
- Steel Piston Structural Superiority:Heavy-duty diesel segments above 12-liter displacement retain forged steel architectures where cylinder pressures exceed 22 MPa, capping aluminum alloy addressable market.
Strategic Opportunities
- India Domestic Sourcing Mandates:PLI scheme incentives for automotive components attract aluminum forging investments to serve Maruti Suzuki and Tata Motors localized engine programs.
- Hybrid Duty Cycle Optimization:Intermittent combustion regimes in PHEV architectures create demand for pistons with modified skirt profiles that accommodate cold-start thermal shock.
- Anodized Ring Groove Treatments:Low-friction surface engineering reduces blow-by oil consumption, aligning with NHTSA CAFE benchmarks and creating premium pricing tiers for certified architectures.
Industry Challenges
- Thermal Coating Application Expertise:Plasma-sprayed molybdenum disulfide and graphite skirt deposition requires specialized technicians that Central European foundries struggle to recruit.
- Dual Certification Timelines:Simultaneous GB standard compliance for China and EPA validation for North American exports extends product qualification cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Piston System Market |
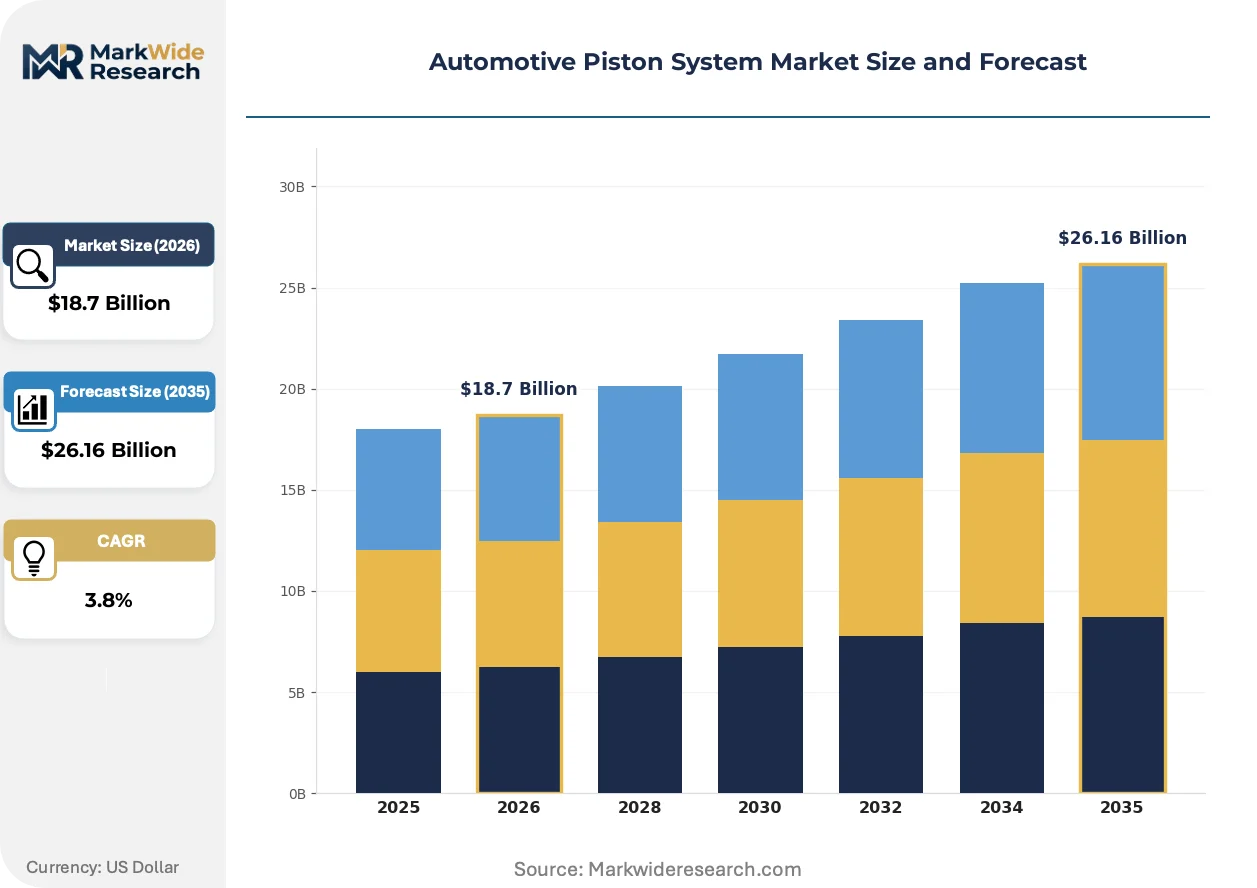
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cylinder, Multi Cylinder, Rotary Engine, Specialty Pistons Material: Aluminum Alloys, Cast Iron, Steel, Composite Materials Engine Type: Petrol Engines, Diesel Engines, Natural Gas Engines, Alternative Fuel Engines Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Off-Road Vehicles |
| Companies Covered | MAHLE GmbH, Tenneco Inc., Aisin Seiki, Rheinmetall, Federal Mogul Holding LLC, KS Kolbenschmidt Piston GmbH, Shriram Pistons & Rings Ltd, Hitachi Automotive Systems, Art Metal Mfg. Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Piston System Market Strategic Shifts
Material science advances and regulatory compression are redefining piston performance specifications. Three developments dominate supplier R&D allocation and OEM technical negotiations.
Monobloc steel pistons with integrated ring carriers are supplanting traditional aluminum architectures in heavy-duty commercial segments. Daimler Truck and Volvo Group procurement specifications now prioritize forged steel for engines above 400 kW rated output. This metallurgical shift enables crown designs that tolerate 250-bar peak firing pressures without cooling gallery complexity.
EU Green Deal CO2 fleet targets are accelerating low-friction piston architecture deployment across European OEM powertrain roadmaps. The regulation mandates 55% emissions reduction by 2030 relative to 2021 baselines. Passenger car applications respond with anodized ring grooves and reduced skirt contact patches that cut mechanical friction losses by 8-12%.
Fleet operators in Germany and California are unbundling piston replacement from full engine overhaul contracts. Independent service networks now quote ring belt and pin bore subassemblies separately from complete piston kits. This procurement fragmentation compresses supplier margins while expanding addressable aftermarket touchpoints for certified remanufacturers.
Automotive Piston System Market Segmentation
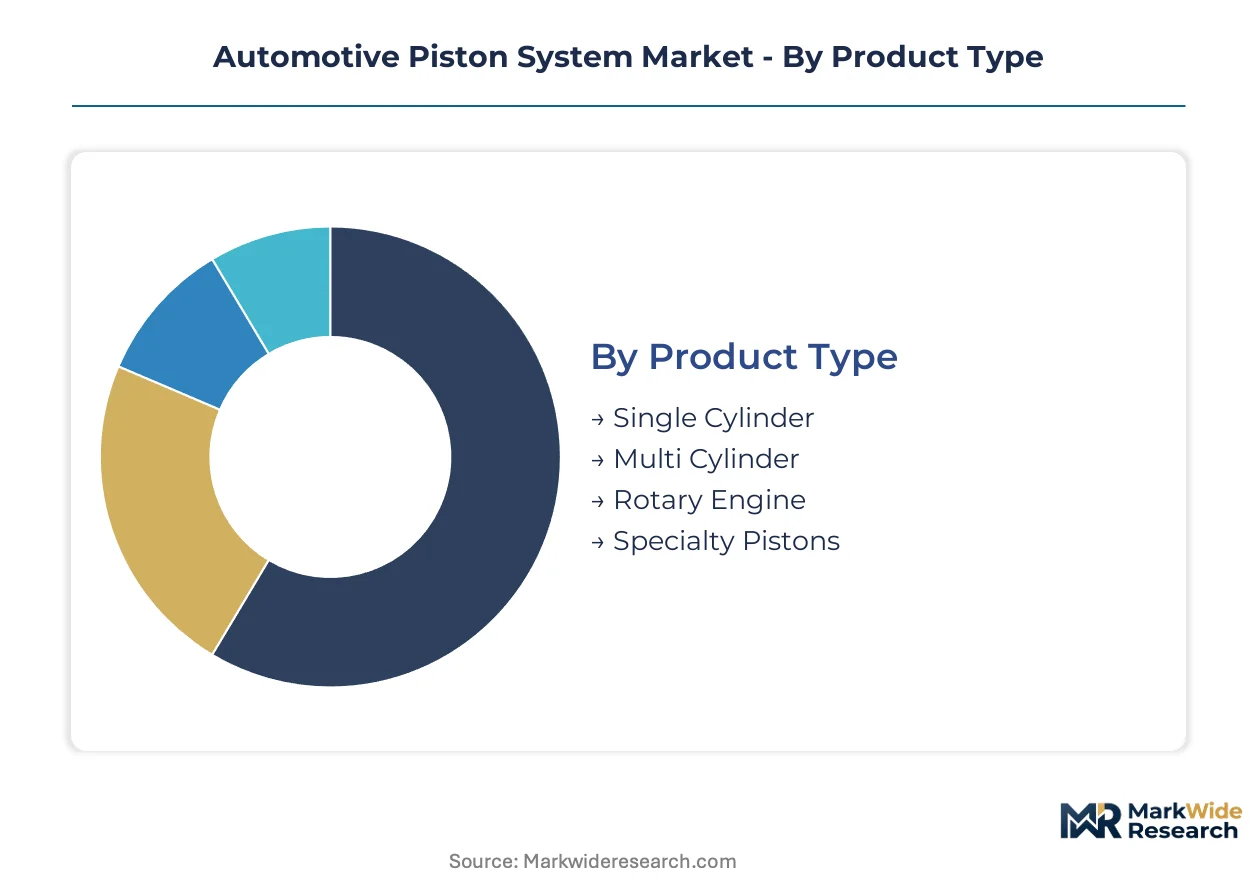
Piston system configurations diverge sharply across powertrain architectures, with material selection and cylinder count directly determining compliance pathways for emission tier enforcement. Regulatory fragmentation across major automotive markets forces suppliers to maintain parallel qualification tracks for architectures serving distinct thermal and pressure regimes.
Product Type:
GB 18352.6-2016 enforcement in China and EPA Tier 3 validation in the United States impose divergent testing protocols on piston crown geometries and ring belt configurations, with multi-cylinder architectures facing consolidated certification burdens that single-cylinder industrial applications largely bypass.
- Multi Cylinder:Configurations with four to sixteen cylinders integrate hypereutectic aluminum-silicon crowns with anodized ring grooves to manage thermal gradients across bore spacing standardized for platform economics. Passenger car OEMs in Germany and Japan concentrate procurement on these architectures to meet EU Green Deal CO2 reduction mandates and METI efficiency benchmarks.
- Single Cylinder:Found predominantly in small-displacement motorcycles, agricultural equipment, and auxiliary power units where cost minimization overrides thermal optimization. India's domestic OEMs source these from local forgers under PLI scheme incentives, with BIS certification requirements less stringent than multi-cylinder passenger car equivalents.
- Rotary Engine:Wankel configurations employ epitrochoidal housings with peripheral intake ports, retaining niche applications in Mazda's range-extender hybrid programs and unmanned aerial vehicle propulsion.
- Specialty Pistons:Custom-forged architectures for motorsport and aerospace auxiliary power units where peak firing pressures exceed 25 MPa.
Established volume favors multi-cylinder architectures; emerging adoption favors specialty pistons in electrification-adjacent range extender programs.
Material:
Cost tier stratification separates premium thermal coating applications from commodity cast iron displacement, with aluminum alloys commanding price premiums tied to weight reduction credits in CAFE compliance calculations.
- Aluminum Alloys:Hypereutectic Al-Si compositions with 17-26% silicon content enable crown thickness reduction below 4mm for downsized turbocharged engines. China's MIIT enforcement of GB 18352 tiers accelerates domestic OEM sourcing from Central European casting networks qualified under dual certification protocols.
- Steel:Forged monobloc architectures with integrated ring carriers dominate heavy-duty commercial segments above 400 kW rated output. Daimler Truck and Volvo Group procurement specifications prioritize steel for peak firing pressures exceeding 250 bar.
- Cast Iron:Retained in stationary industrial engines and emerging market commercial vehicles where first-cost minimization outweighs fuel efficiency optimization.
- Composite Materials:Ceramic-reinforced aluminum matrix composites in prototype deployment for extreme downsizing applications.
Steel commands premium positioning in commercial vehicle procurement; aluminum alloys gain share fastest in passenger car downsizing programs.
Engine Type:
Application-driven thermal loading separates high-pressure direct injection diesel architectures from stoichiometric petrol combustion regimes, with natural gas and alternative fuel variants requiring modified crown geometries to manage distinct flame propagation characteristics.
- Diesel Engines:Compression ignition architectures with peak cylinder pressures above 22 MPa require steel or high-strength aluminum pistons with cooling galleries and anodized ring grooves to manage thermal shock. Commercial fleet operators in Germany compress replacement intervals to 450,000 kilometers.
- Petrol Engines:Spark ignition configurations dominate passenger car volume with downsized turbocharged displacements below 2.0 liters. EU Green Deal CO2 targets accelerate low-friction skirt coating deployment across European OEM powertrain roadmaps.
- Natural Gas Engines:Spark ignition with modified compression ratios and hardened valve seats to manage methane combustion temperatures.
- Alternative Fuel Engines:Hydrogen and synthetic fuel prototypes requiring crown geometries optimized for altered flame speeds and reduced lubricant film thickness.
Diesel retains structural preference in heavy-duty logistics; petrol architectures face steepest efficiency pressure from electrification timelines.
Vehicle Type:
Customer type segmentation separates just-in-time OEM supply agreements from aftermarket replacement cycles, with commercial vehicle fleet operators unbundling piston subassembly procurement from full engine overhaul contracts.
- Commercial Vehicles:Heavy-duty trucks and buses above 12-liter displacement retain steel piston architectures where cylinder pressures exceed 22 MPa. Fleet operators in California and Germany now quote ring belt and pin bore subassemblies separately from complete piston kits.
- Passenger Cars:Multi-cylinder aluminum architectures dominate platform economics with standardized bore spacing. NHTSA CAFE benchmarks push OEMs toward anodized ring groove treatments that reduce blow-by oil consumption.
- Motorcycles:Single-cylinder and parallel-twin configurations concentrate in India and Southeast Asia where domestic sourcing mandates reshape supplier geography.
- Off-Road Vehicles:Construction and agricultural equipment with extended service intervals and exposure to contaminated operating environments.
Passenger car volume sustains foundry utilization; commercial vehicle aftermarket fragmentation expands certified remanufacturer touchpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex anchors China's piston export capacity to Southeast Asian assembly plants. Germany's Rhine-Main corridor channels Central European casting networks toward premium OEM supply chains. India's Golden Quadrilateral highway network enables just-in-time delivery from forging clusters to Maruti Suzuki and Tata Motors engine plants.
China
Domestic OEMs source hypereutectic aluminum-silicon pistons from local forgers to meet MIIT enforcement of GB 18352.6-2016 emission tiers that disqualify conventional cast iron architectures. The Yangtze River Delta concentration around Shanghai hosts captive aluminum casting networks qualified under dual certification protocols for North American export.
Germany
Commercial fleet operators compress replacement intervals to 450,000 kilometers, expanding aftermarket volume for ring belt subassemblies. KBA enforcement of EU Green Deal CO2 fleet targets accelerates low-friction piston deployment across domestic OEM powertrain roadmaps. The Stuttgart-Munich corridor concentrates thermal coating application expertise for downsized turbocharged engines.
United States
NHTSA CAFE benchmarks push OEMs toward anodized ring groove treatments that reduce blow-by oil consumption. The Detroit-Toledo corridor anchors North American aftermarket distribution through heritage Federal Mogul channels. California fleet operators unbundle piston replacement from full engine overhaul contracts, fragmenting procurement patterns.
India
PLI scheme incentives for automotive components attract aluminum forging investments to serve localized engine programs. BIS certification requirements for single-cylinder architectures remain less stringent than multi-cylinder passenger car equivalents. The Delhi-Mumbai Industrial Corridor concentrates domestic OEM sourcing from local forgers under import substitution mandates.
Japan
METI efficiency benchmarks accelerate thermal coating patent deployment for intermittent combustion regimes in PHEV architectures. The Nagoya-Osaka corridor competes on skirt profile modifications that accommodate cold-start thermal shock. Domestic OEMs prioritize anodized ring groove treatments aligned with downsized engine efficiency gains.
Automotive Piston System Market Competitive Environment
Listed leaders compete with private specialists across certification access and captive casting capacity. The supplier base concentrates around tier-1 foundries maintaining ISO/TS 16949 qualification as tier-2 competitors lose quality system access. Three archetypes dominate: integrated aluminum casting networks, thermal coating patent holders, and aftermarket distribution anchors. Competitive moves center on dual certification timelines for China-North American export and unbundled subassembly procurement for fleet operators.
Among German-based fabricators, MAHLE GmbH and KS Kolbenschmidt Piston GmbH exemplify integrated casting network archetypes with Central European supply chain control. Tenneco Inc. occupies the aftermarket distribution anchor position through its Federal Mogul heritage channels. Aisin Seiki represents the thermal coating specialization tier competing on patent-protected skirt deposition for downsized turbo applications.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Tenneco Inc. |
| Aisin Seiki |
| Rheinmetall |
| Federal Mogul Holding LLC |
| KS Kolbenschmidt Piston GmbH |
| Shriram Pistons & Rings Ltd |
| Hitachi Automotive Systems |
| Art Metal Mfg. Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Central European foundries and German OEMs lock in aluminum alloy supply access while providing 18-24 month price visibility against LME volatility. These contract structures insulate tier-1 suppliers from spot market swings but compress margins when primary aluminum prices breach threshold levels embedded in annual supply agreements.
Pricing Analysis
Certification level creates the primary spread between tier-1 and tier-2 suppliers, with ISO/TS 16949-qualified foundries commanding 15-20% premiums over uncertified competitors. Three-tier pricing structure separates premium thermal-coated architectures from standard hypereutectic alloys and economy cast iron displacement. Cost compression in the aftermarket tier is intensifying as fleet operators unbundle piston subassemblies from full engine overhaul contracts. Commercial vehicle procurement teams exhibit highest price sensitivity, while passenger car OEMs prioritize performance consistency over unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane have extended inbound logistics costs for aluminum alloy ingots sourced from Chinese smelters. Supply concentrates in Germany, China, and India, with the Yangtze River Delta and Rhine-Main corridor anchoring captive casting networks. Raw material flows draw from primary aluminum smelters in Shanxi Province, recycled alloy processors in Bavaria, and graphite coating suppliers in Japan. Single-source vulnerability around hypereutectic Al-Si alloy formulations poses structural risk. Distribution runs through heritage Federal Mogul channels in North America and direct OEM supply agreements in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICE downsizing mandates across Beijing, Brussels, and Washington are accelerating replacement demand for high-compression piston architectures, positioning this market in an early-cycle expansion phase driven by regulatory compression rather than volume growth.
For Market Incumbents: Consolidate captive aluminum casting capacity in Central Europe to defend against tier-2 foundry attrition and ISO/TS 16949 certification concentration. Deepen backward integration into hypereutectic Al-Si alloy formulation to secure margin control against primary aluminum price volatility. Prioritize dual certification investment for simultaneous GB 18352 and EPA compliance to capture China-North American export flows. For New Entrants and Emerging Players: Anchor in India's PLI scheme incentives for automotive components to serve localized engine programs at Maruti Suzuki and Tata Motors. Target single-cylinder aftermarket replacement cycles in Southeast Asian motorcycle markets where BIS certification requirements remain less stringent. Pursue thermal coating application partnerships with established foundries rather than greenfield capacity builds. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated casting networks with dual certification capabilities. Long-term viability hinges on positioning for hybrid duty cycle optimization rather than pure ICE volume exposure. Acquisition target archetype: tier-1 foundries with thermal coating patents and established OEM supply agreements. Signal to watch: electrification timeline revisions that extend ICE investment thresholds and sustain demand for intermittent combustion-optimized architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | GB 18352 and EPA simultaneous compliance opens China-North American export corridors for qualified suppliers. |
| Thermal Coating Patent Acquisition | Plasma-sprayed molybdenum disulfide expertise addresses technician scarcity in Central European foundries. |
| India Manufacturing Footprint | PLI scheme incentives attract aluminum forging investments to serve domestic OEM localized engine programs. |
| Aftermarket Subassembly Unbundling | Ring belt and pin bore separate procurement expands certified remanufacturer touchpoints in German and California fleets. |
| Anodized Ring Groove Scale-Up | Low-friction surface engineering aligns with NHTSA CAFE benchmarks and creates premium pricing tiers. |
Study Parameters
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributors, and thermal coating application technicians converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed suppliers, and MIIT GB standard enforcement records. Bottom-up triangulation across piston architecture volumes and top-down cross-checks against powertrain production forecasts anchored the analytical framework.
Segmentation dimensions modeled include material composition, cylinder configuration, engine type, vehicle class, and regional regulatory cluster across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycle data and forward projection of emission tier enforcement timelines. Industry-specific forecast inputs incorporated commercial fleet utilization rates and OEM platform standardization roadmaps.
Material uncertainties — electrification timeline acceleration, primary aluminum price volatility, and ISO/TS 16949 certification attrition — sit outside the modeled envelope. Forecasts reflect assumptions around ICE investment thresholds and hybrid architecture penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automotive Brake Wheel Cylinder Market