
 Mobile Diesel Heaters Market | 2026-2036
Mobile Diesel Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Diesel Heaters Market Foresight
EPA Tier 4 Final is recalibrating the cost-of-entry calculus for mobile diesel heater manufacturers selling into North America. Webasto leverages its integrated burner and control systems to sustain compliance leadership across multiple output classes. Eberspächer anchors European market presence through deep specialization in compact high-efficiency units for transportation and commercial applications. Espar competes aggressively in the portable segment with simplified service architectures that reduce dealer certification burdens.
Mobile diesel heaters are self-contained combustion devices that generate thermal energy through controlled diesel fuel ignition, typically achieving heat outputs from 10 kW to over 40 kW via direct-fired or indirect-fired exchanger configurations; their primary purpose is to deliver on-demand space heating in locations lacking permanent infrastructure such as construction sites, agricultural facilities, and outdoor event venues. The portable product category dominates unit volume due to rental fleet standardization and rapid deployment requirements, while the 31-40 kW and 41+ kW heat output brackets concentrate margin pools because industrial buyers prioritize thermal density over capital economy. Application demand in construction leads absolute consumption, though event heating represents the fastest-growing segment as temporary venue operators replace propane systems with higher-BTU diesel alternatives.
The EPA, EU Stage V regulators, and California Air Resources Board collectively shape product certification pathways, emission testing protocols, and market access timelines for diesel combustion equipment across the transatlantic corridor. China's Ministry of Ecology and Environment enforces parallel GB standards that restrict particulate matter thresholds, compelling exporters to maintain dual compliance architectures. Stakeholders must monitor evolving zero-emission zone declarations in major metropolitan areas and assess hybrid-electric pre-heat integration timelines against pure diesel replacement cycles.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions standards are compressing product development cycles while forcing combustion architecture redesigns across all portable and fixed-output classes.
Growth Catalysts
- Cold-weather construction extension:Infrastructure contractors in the United States and Germany are extending work seasons through December and January, driving fleet replacement of propane units with higher-BTU diesel alternatives.
- EPA Tier 4 Final compliance:The regulation's particulate matter thresholds are accelerating R&D investment in advanced after-treatment systems, creating first-mover advantages for manufacturers with integrated burner-control architectures.
- Event venue diesel conversion:Temporary outdoor venue operators across China are abandoning propane heating systems in favor of diesel units capable of 40+ kW output for large-scale commercial gatherings.
Market Restraints
- Precision component supply concentration:High-pressure fuel injection nozzles and electronic control modules concentrate sourcing from German and Japanese specialty suppliers, exposing manufacturers to lead-time volatility.
- Steel and aluminum input cost swings:Combustion chamber housings and heat exchanger assemblies face raw material price instability that compresses margin on mid-output portable units.
- Battery-electric pre-heat substitution:Silent-operation battery systems are displacing diesel units in noise-sensitive urban construction zones where zero-emission mandates apply.
Strategic Opportunities
- Hybrid-electric pre-heat convergence:Integration of diesel combustion cores with battery buffer systems is expanding into event heating and film production applications requiring silent operation intervals.
- Rental fleet telematics unbundling:Equipment rental companies are adopting usage-based service models that monetize heater runtime data separate from unit rental fees.
- India infrastructure build-out:Highway and railway construction projects in cold-climate Himalayan states present underpenetrated demand for portable 20-30 kW units compliant with BIS emission guidelines.
Industry Challenges
- After-treatment technician scarcity:Diesel particulate filter regeneration and selective catalytic reduction system maintenance require specialized training that dealer networks struggle to staff.
- Dual certification timeline compression:Simultaneous EPA and EU Stage V homologation processes extend product launch windows and strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Diesel Heaters Market |
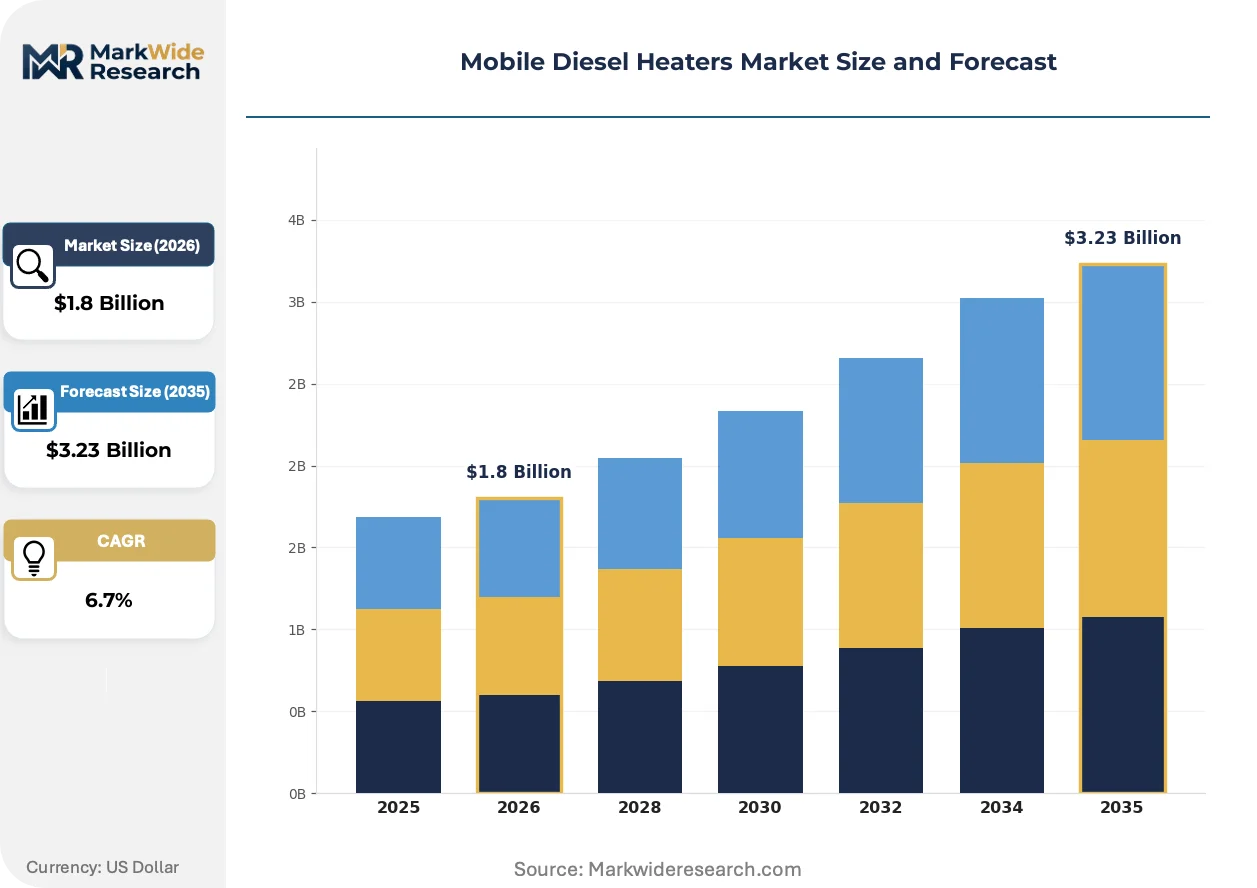
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Compact, Industrial, Commercial Application: Construction, Transportation, Agriculture, Event Heating Fuel Type: Low Sulfur Diesel, Biodiesel, Kerosene, Synthetic Fuel Heat Output: 10-20 kW, 21-30 kW, 31-40 kW, 41+ kW |
| Companies Covered | Webasto, Eberspächer, Espar, Master Climate Solutions, Thermobile Industries, Dr. Heller GmbH, Val6, L.B. White Company, Planar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Diesel Heaters Market Shifts & Advancements
Combustion efficiency architectures and connected service models are redefining competitive differentiation across portable and fixed-installation product lines.
High-pressure common-rail fuel injection is expanding into the 10-20 kW portable segment previously dominated by mechanical pump systems. Agricultural equipment buyers and small-scale construction contractors are specifying these configurations for improved cold-start reliability. The technology is expanding into rental fleet standardization programs that prioritize fuel economy metrics over capital cost minimization.
EU Stage V particulate number limits are forcing redesign of compact burner geometries for transportation-sector auxiliary heaters. German commercial vehicle OEMs are demanding integrated after-treatment packages that maintain envelope dimensions. The regulation is compressing supplier qualification timelines and favoring manufacturers with in-house combustion development capabilities.
Runtime-based service contracting is displacing traditional warranty-plus-parts models in North American rental channels. Large equipment lessors are unbundling maintenance obligations and transferring downtime risk to heater OEMs through performance guarantees. This shift concentrates most visibly in United States construction equipment pools where utilization transparency through telematics enables outcome-based pricing.
Mobile Diesel Heaters Market Segmentation
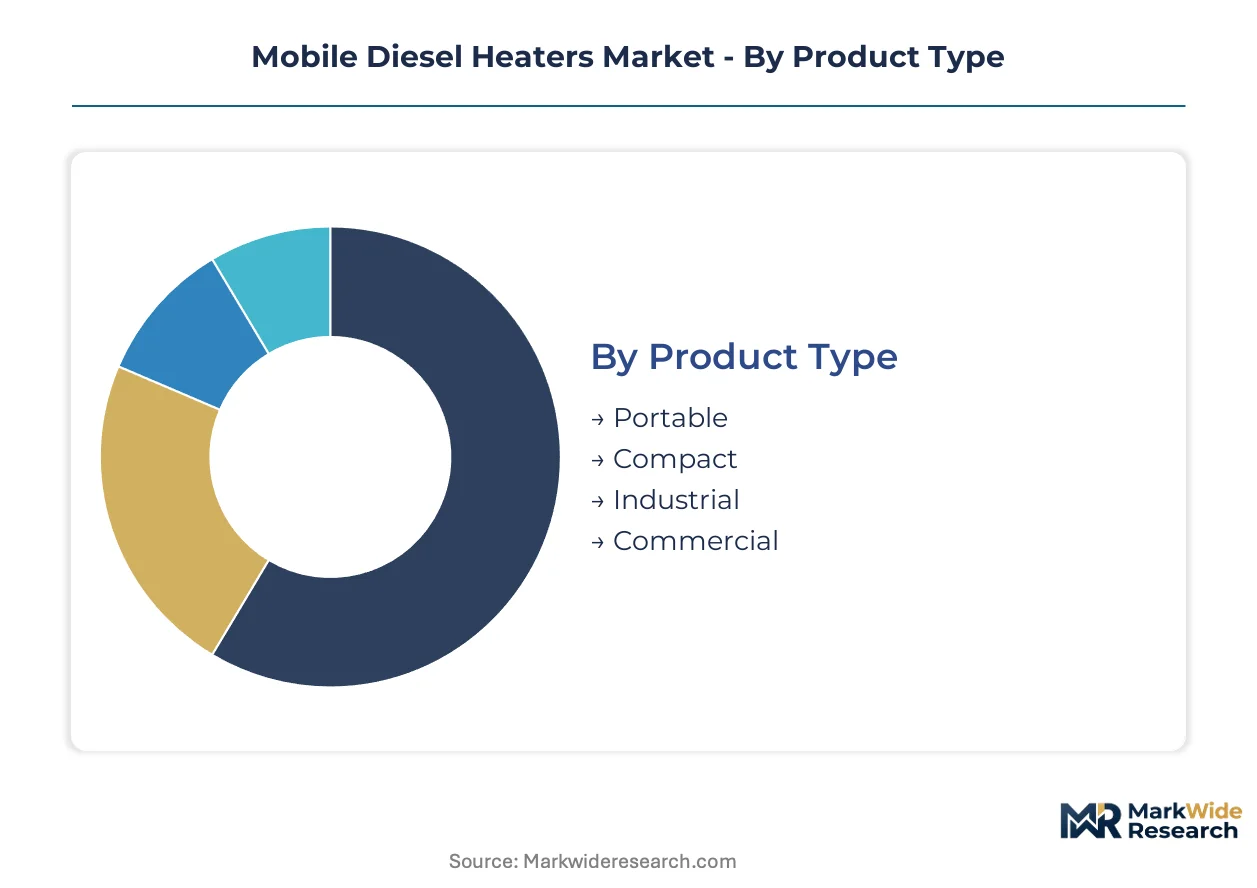
Mobile diesel heater buyers make procurement decisions across four distinct dimensions that determine unit specification, compliance burden, and total cost of ownership. Each segmentation axis carries different weight depending on whether the purchaser operates rental fleets, permanent installations, or seasonal event infrastructure.
Product Type:
Standardization pressure intensifies at the portable end of this spectrum, while industrial buyers demand bespoke combustion architectures matched to fixed infrastructure requirements.
- Portable:Self-contained units with integrated fuel tanks and rapid-deployment frames dominate rental fleet procurement across the United States and Germany. Cold-weather construction extension into December and January drives replacement of propane inventories with diesel alternatives capable of 20-40 kW output.
- Industrial:Fixed-installation systems with external fuel supply connections and modular heat exchanger banks serve permanent agricultural facilities and large-scale construction site offices. Buyers prioritize thermal density over capital economy, concentrating demand in the 31-40 kW and 41+ kW brackets where margin pools are deepest.
- Compact:Envelope-constrained units designed for transportation-sector auxiliary heating in commercial vehicles and marine applications. EU Stage V particulate number limits are forcing burner geometry redesigns to maintain dimensional compliance.
- Commercial:Mid-output stationary units serving retail, hospitality, and institutional temporary heating needs. Event venue operators in China are converting from propane to diesel configurations for large-scale commercial gatherings.
Leading the category by volume: Portable. Growing fastest: Industrial.
Application:
Seasonal intensity and regulatory exposure vary sharply across end-use contexts, with construction offering volume stability and event heating presenting expansion volatility.
- Construction:Infrastructure contractors in the United States and Germany constitute the largest addressable demand pool, extending work windows through traditional off-season months. EPA Tier 4 Final compliance requirements are accelerating fleet turnover toward after-treatment-equipped units.
- Event Heating:Temporary outdoor venue operators across China represent the steepest expansion trajectory, abandoning propane systems for diesel units delivering 40+ kW output. Silent-operation requirements in noise-sensitive urban zones are creating hybrid-electric pre-heat substitution pressure.
- Transportation:Commercial vehicle OEMs specify compact auxiliary heaters for cabin and cargo temperature management. German manufacturers are demanding integrated after-treatment packages that preserve envelope dimensions under EU Stage V.
- Agriculture:Livestock facilities and crop processing operations in cold-climate regions specify portable and compact units for seasonal deployment. High-pressure common-rail fuel injection is penetrating this segment for improved cold-start reliability.
Construction maintains absolute consumption leadership. Event heating climbs fastest by application.
Fuel Type:
Regulatory thresholds and supply chain availability determine fuel specification across geographies, with sulfur content and biofuel blend limits varying by jurisdiction.
- Low Sulfur Diesel:The baseline specification for EPA Tier 4 Final and EU Stage V compliance, requiring 15 ppm sulfur maximum. Infrastructure contractors in the United States specify this grade exclusively for fleet standardization and warranty preservation.
- Biodiesel:B20 and B100 blends gain traction in European agricultural applications where renewable fuel mandates apply. Cold-weather performance degradation limits adoption in sub-zero construction environments.
- Kerosene:Alternative fuel for units requiring cleaner combustion profiles or operating in markets with diesel supply constraints. Event heating operators in China specify kerosene-compatible burners for flexibility.
- Synthetic Fuel:Emerging specification for zero-emission zone pre-compliance and carbon intensity reduction targets. German transportation-sector pilots are testing synthetic diesel compatibility in compact auxiliary heaters.
Low sulfur diesel dominates installed base. Synthetic fuel shows steepest experimental adoption curve.
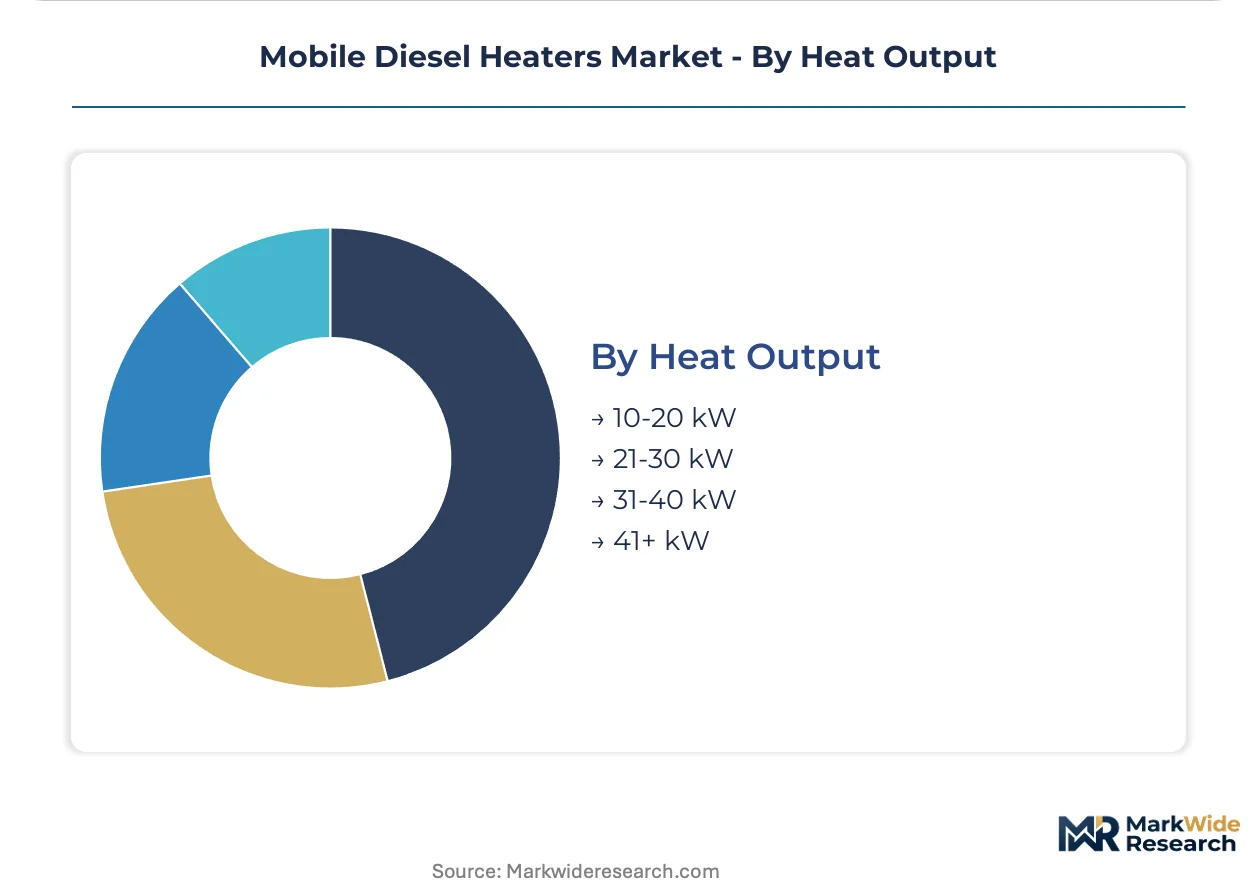
Heat Output:
Capital efficiency versus thermal density trade-offs concentrate margin pools at the upper output brackets while rental fleet standardization drives volume in mid-range configurations.
- 31-40 kW:Industrial buyers and large-scale event operators prioritize this bracket for thermal density per unit of capital deployed. Chinese infrastructure projects and German construction site offices specify these units for permanent or semi-permanent installation.
- 41+ kW:The highest-margin segment serving fixed agricultural facilities, major construction site complexes, and large outdoor commercial gatherings. EPA Tier 4 Final after-treatment costs represent smaller proportion of total system cost at this scale.
- 10-20 kW:Portable segment staple for small-scale construction, agricultural seasonal use, and compact transportation applications. High-pressure common-rail fuel injection is expanding into this bracket from mechanical pump legacy.
- 21-30 kW:Rental fleet sweet spot balancing deployment flexibility with adequate thermal output. United States equipment lessors standardize on this bracket for construction pool uniformity.
21-30 kW leads unit volume through rental channel concentration. 41+ kW delivers strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for mobile diesel heaters concentrates most acutely in the United States, Germany, and China, where infrastructure spending patterns and outdoor commercial activity drive replacement cycles across construction and event heating applications.
United States
Infrastructure contractors extend cold-weather work windows through December and January, accelerating fleet turnover toward EPA Tier 4 Final-compliant units. The Environmental Protection Agency enforces particulate matter thresholds that recalibrate combustion architecture designs. Texas and the Mountain West states concentrate equipment rental pool standardization programs.
Germany
Commercial vehicle OEMs demand compact auxiliary heaters with integrated after-treatment packages preserving envelope dimensions. EU Stage V particulate number limits compress supplier qualification timelines for burner geometry redesigns. Bavaria and North Rhine-Westphalia anchor manufacturing clusters for high-efficiency transportation-sector units.
China
Temporary outdoor venue operators abandon propane systems for diesel configurations delivering 40+ kW output at large-scale commercial gatherings. The Ministry of Ecology and Environment enforces GB standards restricting particulate matter thresholds for combustion equipment. Yangtze River Delta infrastructure projects specify industrial-grade fixed installations.
India
Highway and railway construction in Himalayan states presents underpenetrated demand for portable 20-30 kW units. The Bureau of Indian Standards enforces emission guidelines that shape product certification pathways for imported equipment. Maharashtra and Gujarat concentrate cold-climate agricultural processing facilities requiring seasonal deployment.
United Kingdom
Construction site operators adopt higher-BTU diesel alternatives as work seasons extend into traditional off-months. The Environment Agency aligns enforcement with EU Stage V transition timelines for mobile combustion equipment. London and the Southeast concentrate event heating conversions from propane to diesel systems.
Mobile Diesel Heaters Market Competitive Landscape
German producers anchor one tier; United States specialists hold portable segment positions through simplified service architectures. The vendor base distributes across integrated system architects, compact transportation-sector specialists, and rental-channel-focused fabricators. Three archetypes dominate: burner-control integrators, envelope-constrained compact designers, and fleet-standardization enablers. Capacity expansion and geographic licensing partnerships constitute the dominant competitive moves across output classes.
Within the integrated system tier, Webasto and Eberspächer occupy positions exemplifying deep combustion development capabilities and after-treatment integration. Espar represents the portable-segment archetype with architectures reducing dealer certification burdens. These three anchors illustrate how compliance leadership, transportation-sector specialization, and rental-channel accessibility stratify competitive positioning across EPA and EU regulatory corridors.
| Leading Market Players |
|---|
| Webasto |
| Eberspächer |
| Espar |
| Master Climate Solutions |
| Thermobile Industries |
| Dr. Heller GmbH |
| Val6 |
| L.B. White Company |
| Planar |
| Others |
Supply & Pricing Matrix
EPA Tier 4 Final fleet turnover mandates in the United States are compressing procurement timelines for after-treatment-equipped units, forcing manufacturers to absorb premium component costs or sacrifice margin on mid-output portable configurations. This demand-side pressure reshapes supplier negotiations and concentrates pricing power with German and Japanese specialty component houses.
Pricing Analysis
Volume concentrates in the 21-30 kW rental fleet bracket where standardized procurement limits price differentiation, while margin pools deepen at 41+ kW industrial outputs where thermal density commands premium positioning. Pricing stratifies across EPA Tier 4 Final-certified premium tiers, EU Stage V-compliant mid-tier configurations, and legacy economy units facing accelerated obsolescence. Cost compression in the portable segment intensifies as steel and aluminum input volatility erodes manufacturer flexibility. Rental fleet operators exhibit highest price sensitivity, whereas fixed-installation industrial buyers prioritize thermal performance over capital economy.
Supply Chain Analysis
Container freight rate volatility from Asia to North America and Europe directly inflates landed costs for combustion chamber housings and heat exchanger assemblies manufactured in China. High-pressure fuel injection nozzles and electronic control modules draw from German and Japanese specialty suppliers, exposing manufacturers to lead-time volatility. Single-source vulnerability concentrates in precision after-treatment components where dual qualification timelines strain engineering bandwidth. Distribution runs through equipment rental company pools in Texas and the Mountain West states, construction equipment dealers across Germany, and direct OEM channels for transportation-sector compact units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final compliance functions as a cost-of-compliance moat, elevating first-mover manufacturers with integrated burner-control architectures while elevating barriers for capital-constrained entrants lacking after-treatment development capabilities.
For Market Incumbents: Hedge against battery-electric pre-heat substitution by accelerating hybrid-electric convergence timelines for event heating and film production applications. Secure captive supply of high-pressure common-rail fuel injection systems through backward integration or long-term offtake agreements with German component houses. Reinforce dealer certification advantages by expanding telematics-enabled service contracting that transfers downtime risk from rental fleets to OEM balance sheets. For New Entrants and Emerging Players: Enter via India's Himalayan infrastructure corridor where Bureau of Indian Standards emission guidelines create compliance parity for imported portable 20-30 kW units against entrenched competitors. Target cold-climate agricultural processing facilities in Maharashtra and Gujarat with simplified service architectures that reduce technician training burdens. Pursue geographic licensing partnerships with established European burner designers to compress dual EPA-EU homologation timelines. For Investors and Strategic Acquirers: The window for entry favors integrated system architects with in-house combustion development capabilities and established after-treatment supplier relationships. Long-term viability hinges on positioning ahead of zero-emission zone declarations in major metropolitan areas that will accelerate hybrid-electric pre-heat adoption curves. Monitor California Air Resources Board rulemaking timelines as the leading indicator for federal EPA trajectory shifts that would recalibrate competitive positioning across North American channels.| Strategic Initiative | Industry Significance |
|---|---|
| After-Treatment Integration Partnership | Combines Webasto's burner expertise with Eberspächer's compact catalytic architectures for EPA Tier 4 Final compliance. |
| Rental Fleet Telematics Deployment | Enables usage-based service monetization through runtime data unbundling from United States equipment lessors. |
| Indian Manufacturing Localization | Positions portable unit assembly near Himalayan highway projects to reduce freight exposure and BIS certification friction. |
| Hybrid-Electric Pre-Heat Development | Integrates diesel combustion cores with battery buffers for silent-operation intervals in noise-sensitive urban construction zones. |
| Synthetic Fuel Compatibility Testing | Validates compact auxiliary heater performance with German transportation-sector pilots targeting carbon intensity reduction. |
Research Methodology
Document review covered EPA certification filings, EU Stage V homologation records, and equipment rental fleet procurement databases, complemented by interviews with combustion engineering directors, aftermarket service managers at major lessors, and procurement leads at German commercial vehicle OEMs. Secondary validation drew from customs trade data for high-pressure fuel injection component flows, steel and aluminum price indices, and Bureau of Indian Standards emission guideline publications. Bottom-up unit shipment estimates by output bracket and application were triangulated against top-down infrastructure spending projections across the analysis window.
Historical volume trajectories were cross-referenced against expert panel inputs from plant engineers and maintenance directors to calibrate replacement cycle assumptions across construction, event heating, and transportation applications. The analytical framework modeled segmentation across product type, heat output bracket, fuel specification, and regional regulatory cluster throughout the forecast period. CAGRs were derived from regression analysis of cold-weather construction extension patterns and event venue diesel conversion rates in China, with scenario weightings reflecting battery-electric substitution risk and synthetic fuel pilot outcomes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated zero-emission zone declarations or sustained commodity price volatility in steel and aluminum inputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Synchronous Timing Belts Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Automotive Lubricants Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Automotive Brake Linings Market