
 Turret System Market | 2026-2036
Turret System Market Size, Share, and Industry Trends Forecast 2026-2036
Turret System Market Analysis
The capital-intensity divergence between full-platform integrators and subsystem specialists is unwinding competitive hierarchies in turret manufacturing. Rheinmetall AG leverages its captive metallurgy and armored-vehicle assembly lines to dominate European land-system procurement. Elbit Systems Ltd. anchors its position through vertical control over electro-optic and fire-control subsystems. General Dynamics Corporation competes by sustaining long-term service contracts with the US Department of Defense that extend beyond hardware delivery.
A turret system constitutes a rotating weapon and sensor platform mounted on armored vehicles, naval vessels, or fixed installations, typically integrating stabilized gun mounts, ballistic protection rated to STANAG 4569 levels, and digital fire-control architectures for moving-target engagement. Its primary purpose is to deliver accurate, protected lethality while minimizing crew exposure to hostile fire. Remote-controlled turrets command expanding margin pools as militaries prioritize crew survivability over manned-gunner configurations. Electromechanical drive systems are displacing hydraulic actuation in new programs due to reduced maintenance burden and improved precision. Automated turrets remain niche but attract R&D concentration for future unmanned-ground-vehicle integration.
The US Department of Defense, NATO standardization bodies, and Israel's Ministry of Defense shape turret procurement through STANAG interoperability mandates, cybersecurity hardening requirements, and offset provisions tied to foreign military sales. These frameworks elevate barrier-to-entry for non-aligned suppliers while rewarding pre-qualified incumbents with sole-source pathways. Stakeholders must monitor how AI-enabled target-recognition modules interface with existing export-control regimes governing autonomous-weapon deliberations.
Market Dynamics
Electromechanical drive architectures are displacing hydraulic systems across NATO land-vehicle programs, compressing maintenance cycles and elevating precision requirements for subsystem suppliers.
Growth Catalysts
- STANAG 4569 Ballistic Mandates:NATO standardization bodies enforce unified protection ratings, forcing platform integrators to source interoperable turret assemblies that reduce qualification costs for cross-border procurement.
- Remote Weapon Station Prioritization:Crew survivability doctrines in mechanized infantry units pull demand toward under-armor gunner configurations that eliminate rooftop exposure.
- Electro-Optic Sensor Fusion:Multi-spectral targeting suites integrating thermal, daylight, and laser rangefinder channels are becoming baseline specifications for fire-control contracts.
Market Restraints
- Specialized Armor Steel Concentration:High-hardness plate production clusters in Germany and Sweden, exposing programs to single-source metallurgy bottlenecks during surge demand.
- Export Control Friction:ITAR and EU dual-use regulations impose multi-month licensing delays on turret systems containing US-origin fire-control components.
- Skilled Welder Scarcity:Certified armor-grade fabrication technicians remain concentrated at legacy vehicle assembly sites, constraining capacity expansion for new entrants.
Strategic Opportunities
- Unmanned Ground Vehicle Integration:Automated turret architectures designed for teleoperated and autonomous platforms open white space beyond crewed vehicle retrofit markets.
- Cybersecurity Hardening Services:NATO C4ISR interoperability mandates create recurring revenue streams for vendors supplying encrypted data-link modules and firmware validation.
- Poland Accelerated Modernization:The country's K2 tank and Borsuk IFV programs represent near-term procurement volume for turret-integrated active protection systems.
Industry Challenges
- Legacy Vehicle Retrofit Complexity:Integrating digital fire-control architectures into 1980s-era hulls requires custom mechanical interface engineering that extends program timelines.
- Software Certification Bottlenecks:NATO's evolving cybersecurity frameworks demand iterative validation cycles for weapon-control firmware, compressing delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turret System Market |
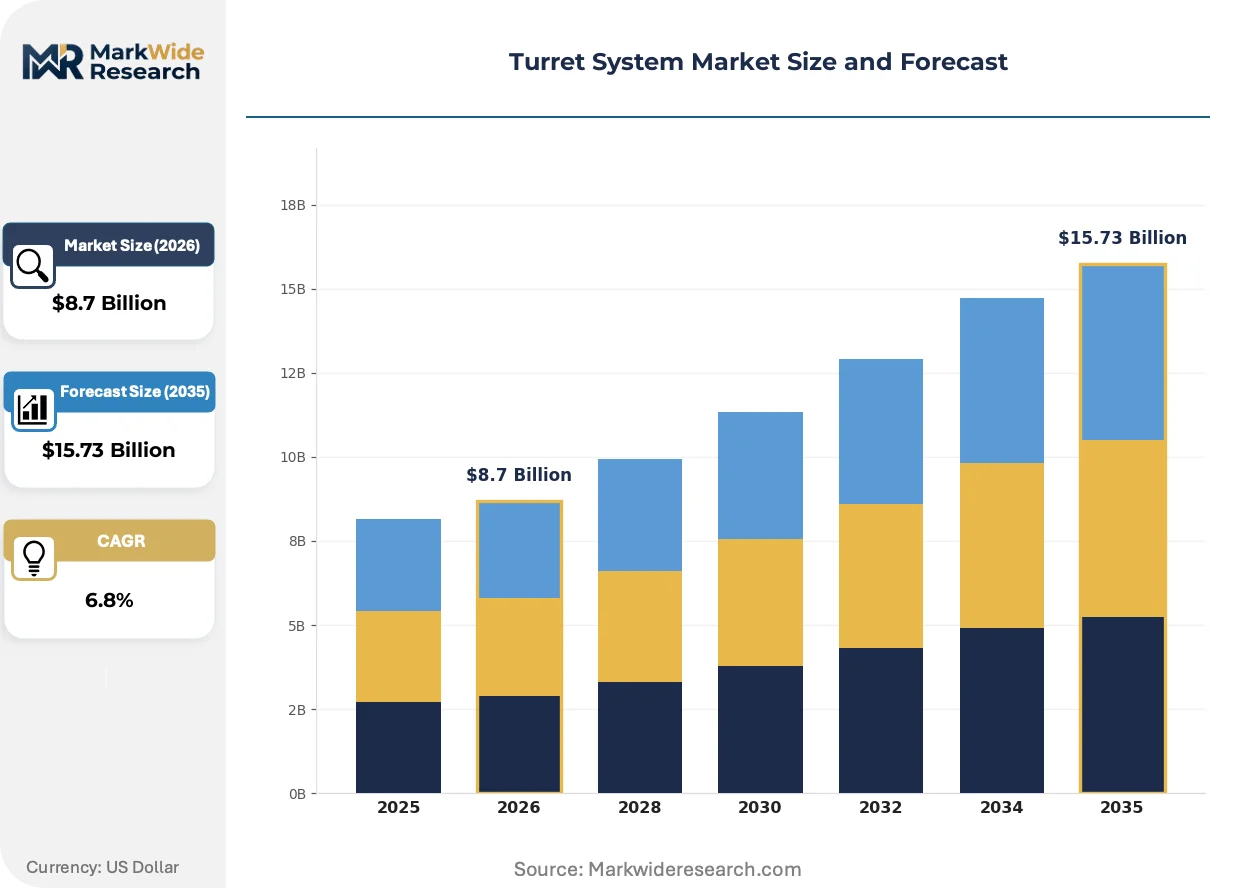
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Turrets, Fixed Turrets, Remote-Controlled Turrets, Automated Turrets End User: Military, Law Enforcement, Commercial, Defense Contractors Technology: Electromechanical, Hydraulic, Pneumatic, Manual Application: Surveillance, Combat, Training, Target Practice |
| Companies Covered | BAE Systems, Elbit Systems Ltd., Rheinmetall AG, Leonardo S.p.A., General Dynamics Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Moog Inc., RAFAEL Advanced Defense Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turret System Market Emerging Trajectories
Active protection systems and AI-assisted targeting modules are converging with traditional turret architectures, redefining the boundary between defensive and offensive subsystems in land combat platforms.
Brushless torque motors paired with harmonic drive gearboxes are displacing legacy hydraulic traverse mechanisms in new turret programs. The US Army's Next Generation Combat Vehicle requirements specify electromechanical actuation for reduced thermal signature and maintenance burden. This shift compresses supplier margins for hydraulic component specialists while rewarding precision motion-control vendors with defense-qualified production lines.
REACH and RoHS substance restrictions are tightening material specifications for turret wiring harnesses and printed circuit boards. European integrators must now certify solder alloys and cable insulation against hazardous substance thresholds, adding qualification overhead. Programs serving NATO's northern tier face the steepest compliance burden due to concurrent national environmental regulations layered atop EU directives.
Life-cycle availability contracts are supplanting discrete hardware purchases in major defense procurement frameworks. The US Department of Defense now structures turret awards around operational readiness metrics rather than unit delivery milestones. This reorients supplier engineering resources toward predictive maintenance algorithms and depot-level repair capacity, with Israel's Ministry of Defense piloting similar performance-based arrangements for border patrol vehicle fleets.
Turret System Market Segmentation
Turret system procurement patterns diverge sharply between domestic defense programs and export-oriented configurations. Platform integrators configure product lines around national STANAG compliance requirements versus bilateral foreign military sales protocols.
Product Type:
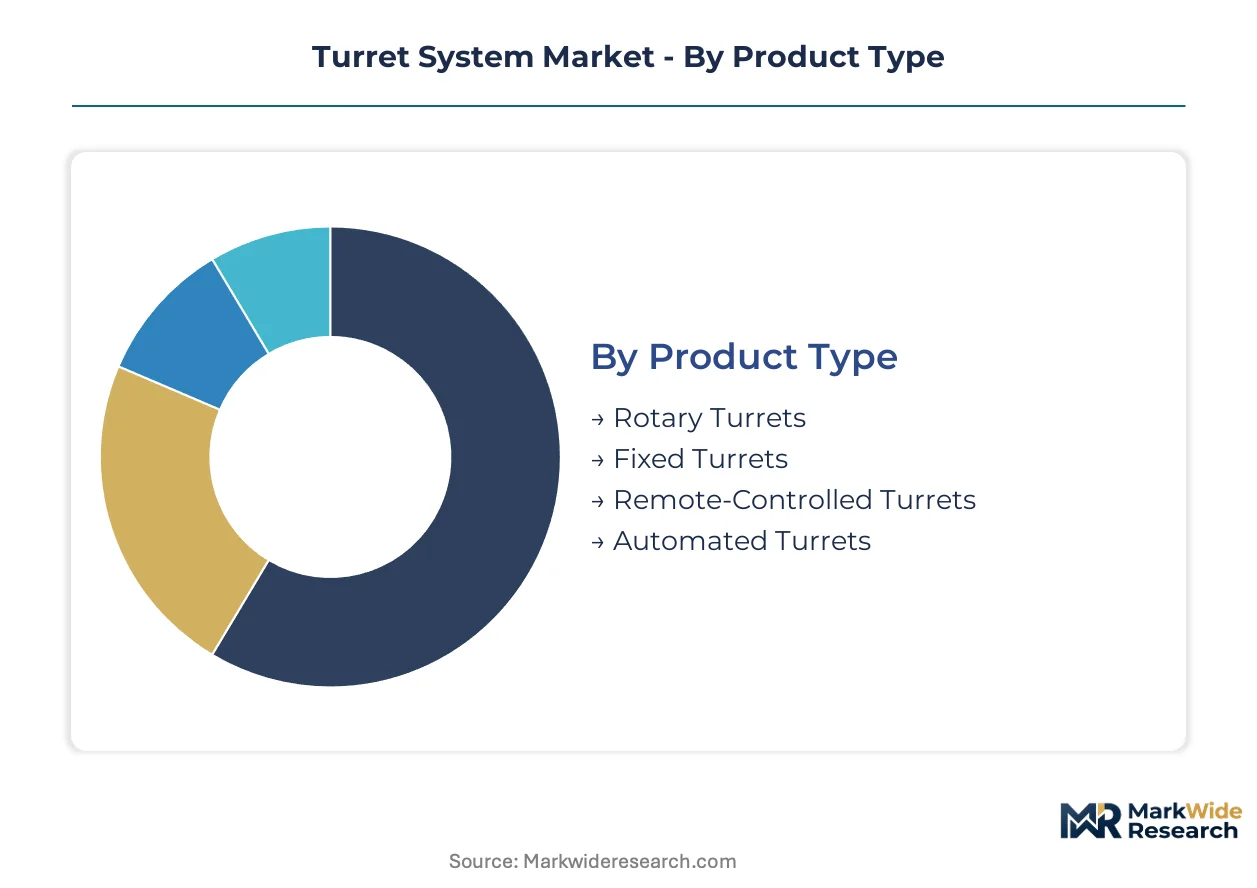
Rotary turrets dominate domestic military procurement across NATO allies, while remote-controlled and automated variants concentrate in export-led defense modernization programs. Israeli and German manufacturers prioritize under-armor configurations for Middle Eastern and Eastern European customers.
- Rotary Turrets:Traditional rotating weapon platforms integrate stabilized gun mounts with manual or assisted traverse mechanisms. Demand concentrates in US Army Bradley Fighting Vehicle recapitalization and German Puma IFV production lines, driven by STANAG 4569 ballistic protection mandates that favor proven mechanical architectures.
- Remote-Controlled Turrets:Under-armor gunner stations eliminate rooftop crew exposure through electromechanical drive systems and digital fire-control interfaces. Poland's K2 tank and Borsuk IFV programs anchor European demand, with crew survivability doctrines accelerating procurement across mechanized infantry units.
- Automated Turrets:Fully autonomous weapon platforms designed for unmanned ground vehicle integration.
- Fixed Turrets:Static installations for border fortification and critical infrastructure protection.
Rotary turrets command the established base. The steepest expansion runs through remote-controlled turrets.
End User:
Military end-users absorb the highest unit volumes through multi-year platform programs, while defense contractors concentrate on subsystem integration for export markets. Law enforcement and commercial segments operate on discrete procurement cycles with shorter qualification timelines.
- Military:National land forces procure turret systems as integrated combat vehicle subsystems under defense ministry frameworks. US Army Next Generation Combat Vehicle requirements and European NATO commitments drive specification convergence around electromechanical actuation and multi-spectral targeting suites.
- Defense Contractors:System integrators source turret assemblies for foreign military sales and co-production agreements. Israeli manufacturers leverage vertical control over electro-optic subsystems to capture Middle Eastern border security contracts, offsetting domestic volume constraints.
- Law Enforcement:Special weapons and tactical units deploy lighter turret configurations on armored personnel carriers.
- Commercial:Private security firms and critical infrastructure operators acquire fixed surveillance turrets.
Military end-users anchor procurement volume. Defense contractors are climbing the fastest as export channels deepen.
Technology:
Electromechanical systems displace legacy hydraulic architectures across cost tiers, with pneumatic and manual technologies retreating to niche retrofit and training applications. Procurement budgets bifurcate between premium digital drive systems and economy-grade mechanical alternatives.
- Electromechanical:Brushless torque motors paired with harmonic drive gearboxes deliver precision traverse with reduced thermal signature. US Army specifications now mandate this architecture for Next Generation Combat Vehicle programs, compressing margins for hydraulic component specialists while rewarding defense-qualified motion-control vendors.
- Hydraulic:Legacy fluid-power systems persist in 1980s-era vehicle retrofits where digital fire-control integration proves mechanically prohibitive.
- Pneumatic:Compressed-air actuation remains confined to training turrets with reduced lethality requirements.
- Manual:Hand-cranked traverse mechanisms survive only in museum restoration and ceremonial applications.
Electromechanical systems command the established base. The steepest expansion trajectory belongs to this same segment as NATO procurement converges on digital architectures.
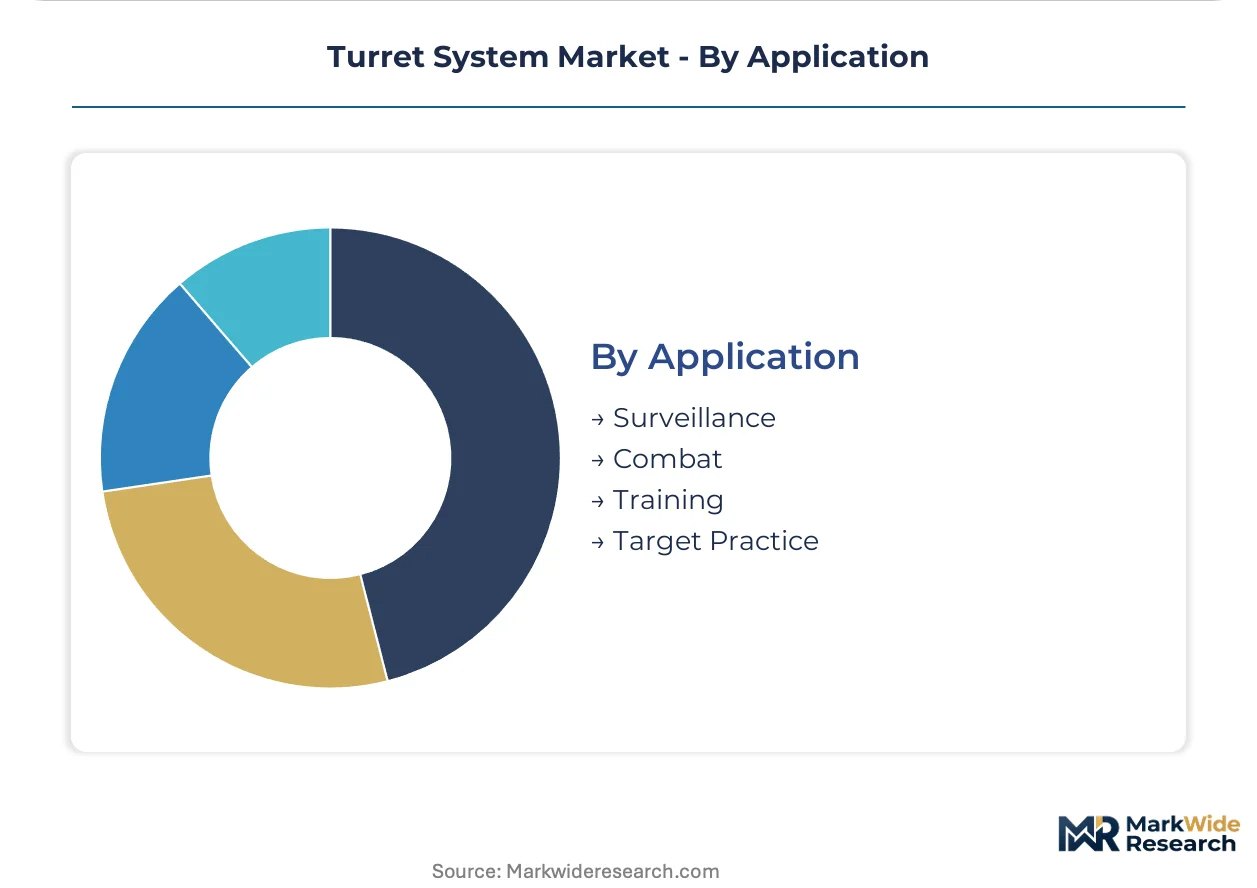
Application:
Combat applications absorb capital expenditure concentration, while surveillance and training segments operate on operational budgets with faster replacement cycles. Target practice configurations serve as entry points for new suppliers seeking qualification pathways.
- Combat:Lethality-optimized turrets integrate stabilized main guns, coaxial machine guns, and active protection systems for direct-fire engagements. Israeli border patrol vehicle fleets and NATO mechanized units drive specification intensity around moving-target engagement algorithms and ballistic protection ratings.
- Surveillance:Sensor-heavy turrets prioritize electro-optic payload capacity over weapon station mass.
- Training:Reduced-capability turrets simulate fire-control interfaces without live ordnance expenditure.
- Target Practice:Static and mobile target acquisition systems support weapons qualification ranges.
Combat applications command the established base. Surveillance is gaining share fastest as border security budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German turret assemblies runs 15-20 percent above comparable US-origin systems due to specialized armor steel concentration and captive metallurgy capacity. Israeli manufacturers command premiums through electro-optic subsystem integration. This asymmetry shapes procurement patterns across NATO and export markets.
United States
The US Army's Next Generation Combat Vehicle program drives electromechanical actuation specifications through Moog Inc. and General Dynamics supply chains. ITAR licensing requirements from the US Department of State constrain foreign military sales timelines. Detroit Arsenal and Red River Army Depot anchor domestic production clusters for Bradley Fighting Vehicle recapitalization.
Germany
Rheinmetall AG's vertical control over high-hardness steel production supports Puma IFV and Leopard 2 turret output for European NATO commitments. KBA vehicle certification standards enforce STANAG 4569 ballistic compliance across export configurations. The Unterlüß industrial complex concentrates armor fabrication and electro-optic integration capacity.
Israel
Border security vehicle fleets and active protection system integration pull demand toward automated turret architectures. The Ministry of Defense's offset provisions for foreign military sales reward domestic electro-optic subsystem suppliers. RAFAEL Advanced Defense Systems and Elbit Systems anchor Tel Aviv-area production clusters for Middle Eastern export contracts.
Poland
K2 tank and Borsuk IFV procurement volumes represent near-term turret system absorption for active protection integration. NATO C4ISR interoperability mandates from Brussels shape fire-control firmware specifications. The Wojska Polskiego industrial base near Poznań is expanding armor-grade welding capacity for platform assembly.
South Korea
KF-21 Boramae and K2 Black Panther export variants drive turret procurement with multi-spectral targeting suite requirements. DAPA acquisition frameworks prioritize domestic content thresholds for motion-control subsystems. The Changwon Defense Industry Complex concentrates Hyundai Rotem and Hanwha Aerospace turret integration lines.
Turret System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Full-platform integrators with captive metallurgy and long-term service contracts occupy premium positions, while subsystem specialists compete on electro-optic and fire-control modularity. Three archetypes dominate: vertically integrated armor manufacturers, precision motion-control vendors, and electro-optic subsystem houses. Competitive moves concentrate on strategic partnerships for unmanned vehicle integration and cybersecurity hardening service expansion.
Within the vertically integrated tier, Rheinmetall AG exemplifies European land-system dominance through captive steel production and armored-vehicle assembly lines. Elbit Systems Ltd. anchors Israeli positioning through vertical control over electro-optic and fire-control architectures. General Dynamics Corporation occupies the US defense contractor archetype, sustaining procurement relationships through performance-based availability contracts extending beyond hardware delivery milestones.
| Leading Market Players |
|---|
| BAE Systems |
| Elbit Systems Ltd. |
| Rheinmetall AG |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Moog Inc. |
| RAFAEL Advanced Defense Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
Life-cycle availability contracts lock in supply access and price visibility for turret integrators, binding General Dynamics and Rheinmetall to performance-based service agreements that extend beyond hardware delivery and compress margin volatility for qualified suppliers.
Pricing Analysis
The customization-premium spread separates configured-to-order turret assemblies from standard export configurations. Three-tier pricing structure across premium, standard, and economy levels reflects STANAG 4569 certification grade and integration complexity. Price differentiation hinges on captive metallurgy capacity and electro-optic subsystem bundling. Pricing pressure stems from electromechanical drive commoditization as NATO procurement converges on digital architectures. Defense contractors exhibit highest price sensitivity due to foreign military sales margin constraints, while national military programs absorb premium tiers for platform-specific customization.
Supply Chain Analysis
Germany and Sweden anchor high-hardness armor steel production, feeding Rheinmetall's Unterlüß complex and KBA-certified fabrication lines. The supply chain draws from specialized plate mills, electro-optic sensor foundries in Israel, and precision motion-control vendors in the United States. Single-source metallurgy vulnerability concentrates surge-demand risk in European NATO procurement. Distribution runs through defense ministry frameworks and foreign military sales channels with ITAR and EU dual-use licensing overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turret system procurement fragments across crewed vehicle retrofit, unmanned platform integration, and cybersecurity service layers, with NATO C4ISR mandates creating specialist niches beyond full-platform integrator dominance.
For Market Incumbents: Shield service-contract renewals through predictive maintenance algorithm investments and depot-level repair capacity expansion in the United States and Germany. Counter electro-optic subsystem commoditization by deepening backward integration into fire-control firmware development. Prioritize STANAG 4569 certification maintenance as a barrier against emerging motion-control specialists from South Korea. For New Entrants and Emerging Players: Cybersecurity hardening services for legacy vehicle fleets represent the most penetrable white space, as incumbents under-serve firmware validation and encrypted data-link retrofit demand. Target Polish K2 and Borsuk program subcontractors seeking NATO interoperability compliance without captive integration capacity. Enter through performance-based availability pilots rather than discrete hardware competition. For Investors and Strategic Acquirers: Capital is best deployed toward electro-optic subsystem houses with vertical control over multi-spectral targeting architectures and established foreign military sales pathways. Long-term viability centers on unmanned ground vehicle integration readiness and AI-enabled target recognition module pipelines. Watch for inflection in US Army Next Generation Combat Vehicle teleoperated platform procurement signals.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Drive Transition | Moog Inc. and precision motion-control vendors capture NATO procurement convergence on brushless torque motor architectures. |
| Cybersecurity Hardening Service Expansion | Encrypted data-link module suppliers secure recurring revenue under NATO C4ISR interoperability mandates. |
| Unmanned Ground Vehicle Integration | Automated turret architectures open procurement channels beyond crewed vehicle retrofit saturation. |
| Active Protection System Bundling | RAFAEL and Elbit Systems anchor Israeli border security contracts through subsystem integration premiums. |
| Performance-Based Availability Contracting | General Dynamics sustains US Department of Defense relationships through operational readiness metrics. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of defense ministry procurement disclosures, ITAR licensing records, and NATO standardization documentation. Interviews with platform integration engineers, electro-optic subsystem procurement leads, armor fabrication technicians, and foreign military sales contract officers informed demand-side validation. Secondary sources include US Army budget justification materials, EU defense procurement databases, and STANAG compliance certification registries. Bottom-up turret system shipment analysis triangulates against top-down defense expenditure allocation modeling.
Segmentation dimensions modeled span product type, end user, technology, and application, with additional granularity on NATO versus bilateral foreign military sales protocol configurations. CAGRs derive from platform program timeline analysis and defense modernization commitment trajectories across the projection horizon. Industry-specific forecast inputs include electromechanical actuation adoption curves and active protection system integration penetration rates.
Underlying assumptions cover NATO defense spending continuity, STANAG 4569 mandate persistence, and electromechanical drive qualification timelines, with deviation risk concentrated in export control friction and armor steel supply surge constraints. Recalibration cycles align with material shifts in US Army Next Generation Combat Vehicle specifications and European NATO procurement framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Smart Bullets Market