
 Ammunition Storage Market | 2026-2036
Ammunition Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Ammunition Storage Market Outlook
The EU Green Deal is expanding compliance requirements for ammunition storage manufacturers serving European defense and civilian markets. Mauser Packaging Solutions leverages its industrial container expertise to compete in modular military-grade systems. Mil-Spec Industries anchors its position through strict adherence to NATO standardization agreements. Safewell differentiates via specialized fireproofing and humidity control technologies for law enforcement clients.
Ammunition storage encompasses engineered containment systems designed to secure explosive ordnance, typically constructed from reinforced steel with fire-resistant ratings exceeding one hour and integrated climate control to prevent propellant degradation. These systems serve military depots, police armories, and civilian firearms owners by mitigating theft, accidental detonation, and environmental corrosion risks. Metal cabinets dominate procurement volumes among military end users due to durability and stackability in fixed installations. Modular storage represents the fastest-expanding category as armed forces prioritize rapid deployment and reconfiguration of forward operating bases. Custom solutions command premium positioning where nuclear-biological-chemical hardening or electromagnetic shielding specifications apply.
The U.S. Department of Defense mandates Environmental Protection Agency compliance for hazardous material containment, while NATO standardization agreements govern interoperability of mobile ammunition containers across allied forces. The EU's REACH regulation restricts certain flame-retardant chemicals in polymer-based storage units, redirecting R&D toward halogen-free alternatives. Stakeholders must monitor evolving explosive storage quantity-distance regulations in key procurement jurisdictions to anticipate facility redesign cycles and certification renewal demands.
Market Dynamics
NATO armory modernization programs and the EU Green Deal's sustainable manufacturing mandates are restructuring supplier requirements across military and civilian procurement channels simultaneously.
Growth Catalysts
- REACH compliance redirection:ECHA restrictions on halogenated flame retardants in polymer storage units are accelerating R&D investment in recyclable metal alloys and low-VOC coating systems for European defense contracts.
- Forward operating base mobility:Armed forces in Poland and Romania are prioritizing rapid-deployment modular containers with NATO standardization agreement interoperability for eastern flank reinforcement.
- Civilian firearms ownership:Sustained demand from regulated gun owners in the United States supports dual revenue streams for providers serving both military base infrastructure and residential security markets.
Market Restraints
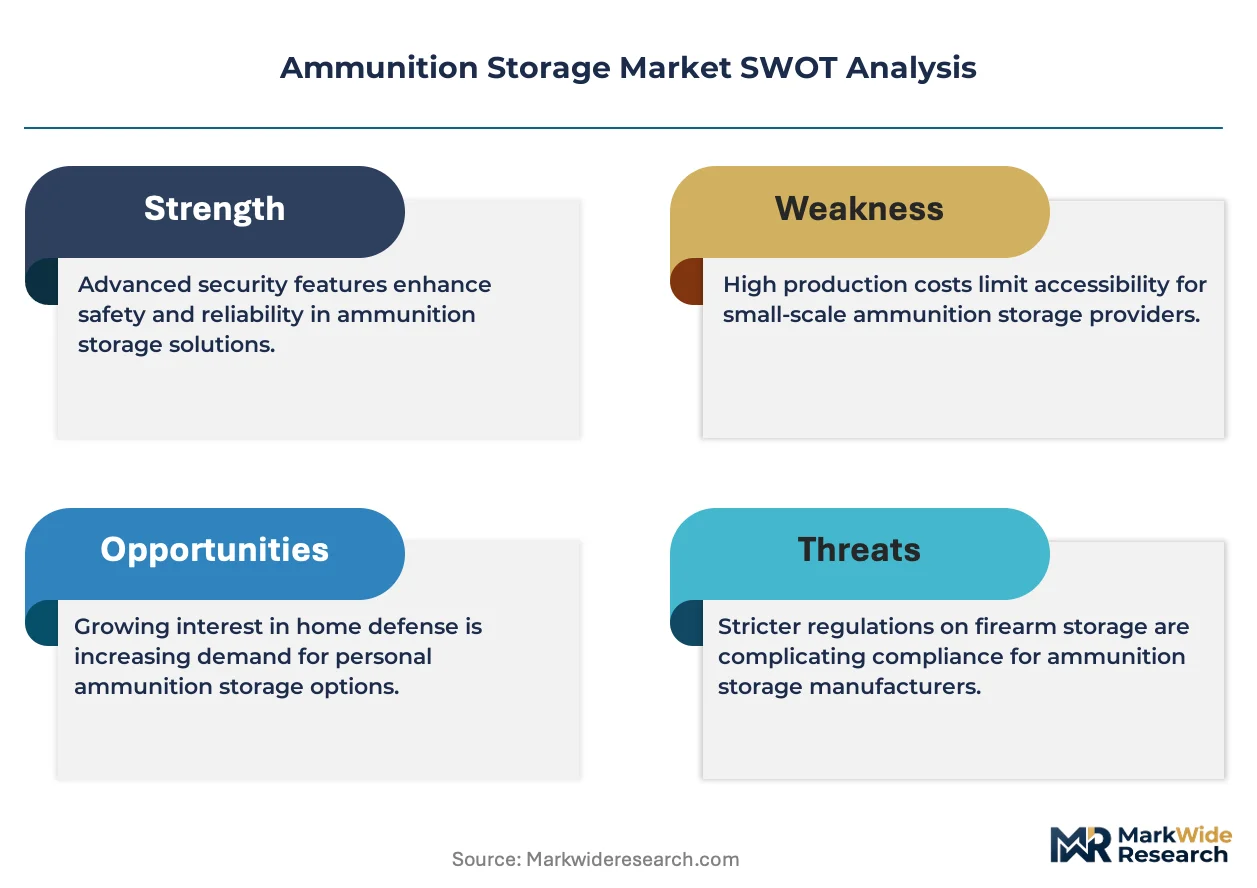
- Specialized steel alloy volatility:Input cost fluctuations for ballistic-grade steel and fire-resistant insulation materials compress margin structures for fixed-price defense contracts.
- Explosive storage quantity-distance regulations:Facility redesign cycles triggered by evolving EPA and national regulator mandates extend certification timelines and deter greenfield investments.
- Electromagnetic pulse hardening complexity:Technical limitations in integrating Faraday cage specifications with climate control systems elevate engineering costs for nuclear-biological-chemical rated installations.
Strategic Opportunities
- Law enforcement digitization:Police departments in Germany and France are adopting RFID-enabled inventory tracking integrated with armory management software, creating demand for smart-enabled cabinet retrofits.
- EU Green Deal incentives:Circular economy subsidies for sustainable manufacturing are rewarding suppliers who achieve cradle-to-cradle certification for metal storage system production.
- Climate-resilient coatings:Convergence of nanotechnology surface treatments with traditional fireproofing is opening premium positioning for humidity-controlled systems in coastal military installations.
Industry Challenges
- Explosives safety engineering talent:Shortages of certified professionals familiar with NATO STANAG requirements and EPA hazardous material containment protocols delay project execution.
- Legacy system integration:Retrofitting existing armory infrastructure with modular rapid-deployment units without disrupting operational readiness creates implementation friction for defense procurement agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammunition Storage Market |
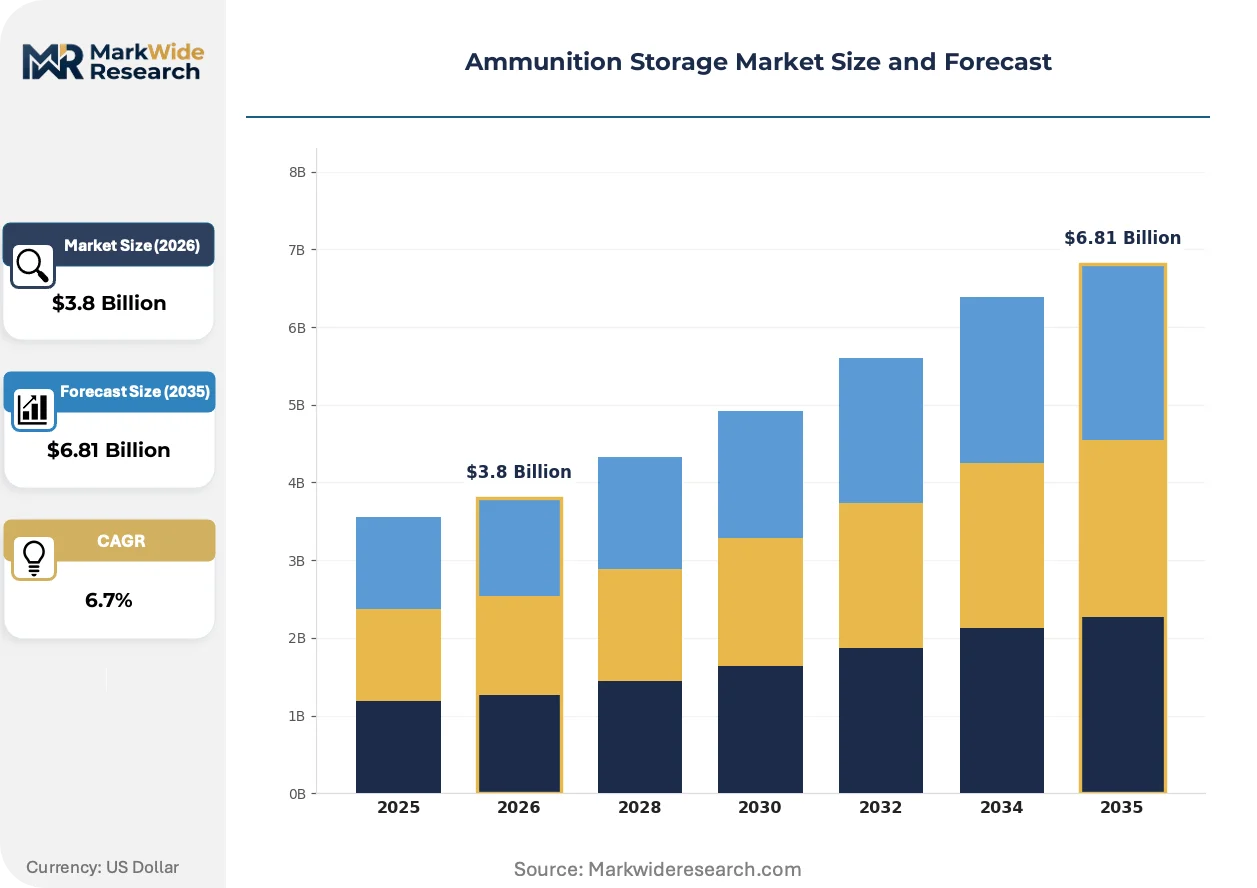
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Cabinets, Wooden Safes, Plastic Containers, Modular Storage End User: Military, Law Enforcement, Sports Shooters, Collectors Installation Type: On-site Storage, Off-site Storage, Mobile Units, Built-in Storage Storage Capacity: Small Capacity, Medium Capacity, Large Capacity, Custom Solutions |
| Companies Covered | Mauser Packaging Solutions, Milan Box Corporation, Tri-State Crating & Pallet Co., Mil-Spec Industries, Conco Inc., Modular Container Systems, CN ROMTEHNICA SA, Nordic Armoury OU, Safewell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammunition Storage Market Strategic Shifts
Active materials science breakthroughs and procurement digitization are compressing product lifecycles while elevating performance specifications for containment systems across military and civilian applications.
Smart humidity sensing technology paired with automated ventilation control is consolidating quality assurance functions previously requiring manual inspection cycles. Military depots in Norway and Sweden are deploying these systems at scale to reduce propellant degradation risks in subarctic storage conditions. The technology is consolidating maintenance schedules and reducing personnel exposure to hazardous monitoring tasks.
REACH restrictions on persistent organic pollutants in polymer components are forcing reformulation of cabinet insulation materials across European supply chains. Manufacturers serving Bundeswehr and French Armed Forces contracts are pivoting toward mineral wool and aerogel alternatives to maintain fire-resistance ratings. Modular storage categories face the steepest compliance recertification burdens due to higher polymer content in connector systems.
Defense procurement agencies are unbundling after-sales service contracts from initial equipment purchases, creating standalone revenue streams for predictive maintenance providers. Original equipment manufacturers in the United States and United Kingdom are responding with sensor-embedded units capable of remote diagnostics. Police armories in Texas and Florida represent the most visible adoption of this consumption-pattern shift, where budget constraints favor operational expenditure models over capital-intensive replacements.
Ammunition Storage Market Segmentation
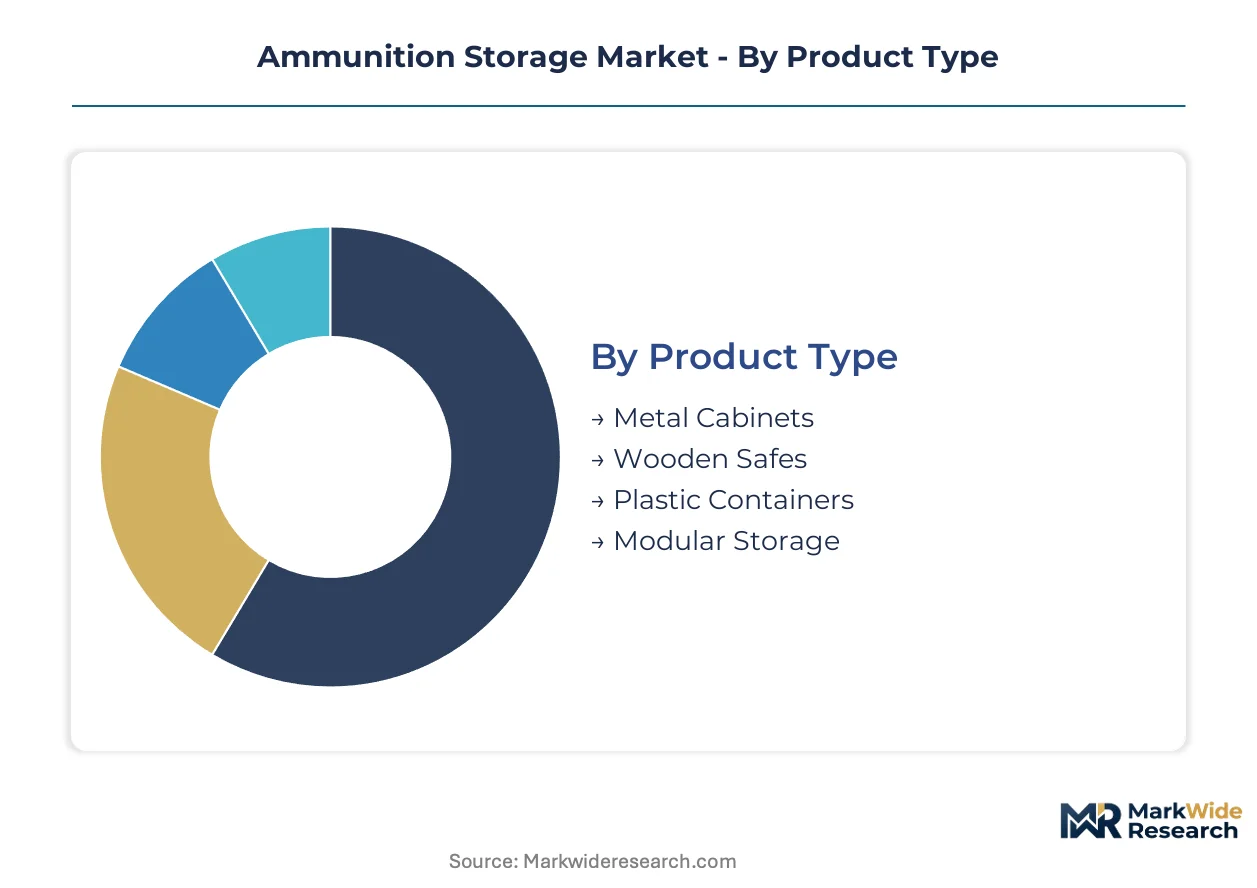
Ammunition storage procurement splits across material engineering specifications, end-use security protocols, and deployment flexibility requirements. Each segmentation axis reveals distinct margin structures, certification burdens, and customer concentration patterns that reshape supplier positioning.
Product Type:
Material composition and fire-resistance ratings define procurement specifications across defense, law enforcement, and civilian channels.
- Metal Cabinets:Constructed from reinforced ballistic-grade steel with one-hour fire ratings and integrated locking mechanisms. Military depots in the United States and Germany specify these for fixed armory installations where stackability and durability outweigh mobility requirements. NATO standardization agreements govern interoperability specifications for cross-border logistics.
- Modular Storage:Rapid-deployment container systems featuring standardized dimensions for air and sea transport. Polish and Romanian armed forces prioritize these for eastern flank reinforcement capabilities where base reconfiguration speed determines operational readiness. REACH compliance redirects polymer component sourcing toward halogen-free alternatives.
- Wooden Safes:Traditional construction with limited fire ratings, primarily serving residential collectors in jurisdictions with minimal regulatory oversight.
- Plastic Containers:Lightweight polymer units for temporary field storage; ECHA restrictions on flame retardants accelerate reformulation toward mineral-based insulation.
Mature deployment sits with Metal Cabinets. Newer deployment is concentrated in Modular Storage.
End User:
Security clearance levels and procurement budget cycles segment demand across institutional and private channels.
- Military:Large-scale depot infrastructure requiring electromagnetic pulse hardening and nuclear-biological-chemical specifications. The U.S. Department of Defense and Bundeswehr drive volume through multi-year armory modernization programs with stringent EPA and REACH compliance mandates.
- Law Enforcement:Police armories in Texas, Florida, Germany, and France adopting RFID-enabled inventory tracking with armory management software integration. Budget constraints favor operational expenditure models and predictive maintenance contracts over capital-intensive replacements.
- Sports Shooters:Regulated civilian firearms owners in the United States sustaining residential security demand through dual revenue streams.
- Collectors:Niche segment with specialized humidity control requirements for antique ordnance preservation.
Institutional procurement dominates volume concentration. Civilian channels exhibit steepest expansion trajectory in smart-enabled retrofits.
Installation Type:
Physical anchoring requirements and relocation frequency determine engineering specifications and certification complexity.
- On-site Storage:Fixed installations at military bases and police facilities requiring explosive storage quantity-distance compliance with EPA and national regulator mandates. Facility redesign cycles extend certification timelines.
- Mobile Units:Rapid-deployment containers for forward operating bases with NATO STANAG interoperability specifications. Norwegian and Swedish military depots deploy climate-controlled variants for subarctic conditions.
- Off-site Storage:Third-party managed facilities with shared compliance burdens.
- Built-in Storage:Architectural integration requiring custom engineering for structural load and ventilation specifications.
Fixed infrastructure commands procurement volume. Mobile configurations gain share fastest in eastern European defense contracts.
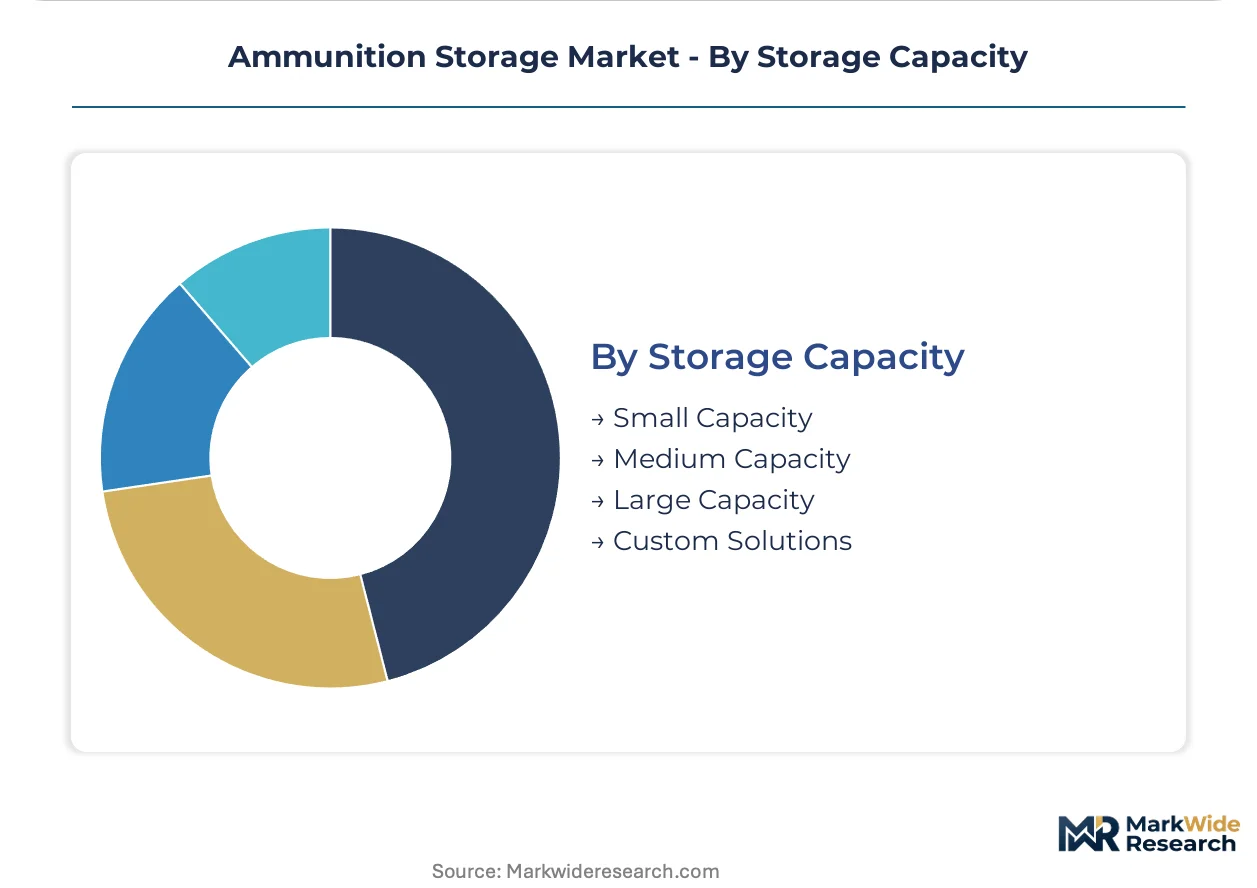
Storage Capacity:
Volume thresholds dictate regulatory tiering, insurance requirements, and facility design standards.
- Large Capacity:Depot-scale systems exceeding quantity-distance thresholds requiring dedicated facilities with perimeter security and climate control. Military end users in the United States and NATO member states specify these for centralized ammunition management.
- Custom Solutions:Nuclear-biological-chemical hardening and electromagnetic shielding for specialized ordnance categories. Premium positioning reflects engineering complexity and certification scarcity.
- Small Capacity:Residential and tactical unit specifications with simplified compliance.
- Medium Capacity:Law enforcement armory standard for precinct-level deployment.
Standardized capacity tiers anchor procurement volume. Custom configurations command margin concentration in specialized defense applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fort Worth anchors military depot infrastructure investment in the United States, where ammunition storage procurement concentrates around defense base modernization and civilian firearms security channels across NATO member states.
United States
Texas and Florida police armories drive smart-enabled retrofit demand through RFID inventory tracking integration. EPA hazardous material containment mandates govern military depot specifications. Fort Worth and San Antonio cluster defense procurement agencies executing multi-year armory infrastructure programs.
Germany
Bundeswehr modernization programs prioritize modular rapid-deployment systems for eastern flank reinforcement capabilities. REACH restrictions on halogenated flame retardants redirect polymer component sourcing toward mineral-based insulation alternatives. Bavaria and North Rhine-Westphalia concentrate defense industrial suppliers serving NATO standardization agreements.
Poland
Armed forces procurement prioritizes NATO STANAG interoperable containers for forward operating base mobility. National defense spending increases accelerate facility redesign cycles for explosive storage quantity-distance compliance. Warsaw and Krakow industrial corridors host emerging suppliers competing for eastern flank contracts.
Norway
Subarctic storage conditions drive climate-controlled system deployment with automated humidity sensing technology. Smart ventilation control systems reduce propellant degradation risks in extreme cold environments. Oslo and Bergen military depots consolidate maintenance schedules through sensor-embedded predictive maintenance contracts.
France
Police departments in Île-de-France adopt operational expenditure models favoring predictive maintenance over capital-intensive replacements. EU Green Deal circular economy subsidies reward cradle-to-cradle certification achievements. Lyon and Marseille defense industrial zones specialize in nuclear-biological-chemical hardened custom solutions.
Ammunition Storage Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and materials engineering specifications. The supplier base stratifies between industrial container specialists, defense-standard fabricators, and climate-control technology integrators. Three archetypes dominate: packaging-industry diversifiers leveraging manufacturing scale, military-specification purists anchoring on NATO compliance, and fireproofing specialists capturing law enforcement retrofit cycles. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as procurement agencies unbundle after-sales service contracts.
Among packaging-industry diversifiers, Mauser Packaging Solutions exemplifies industrial container expertise applied to modular military-grade systems. Mil-Spec Industries occupies a position within the defense-standard fabricator tier, representing strict NATO standardization agreement adherence. Safewell anchors the fireproofing specialist archetype, exemplifying differentiated positioning through humidity control technologies for law enforcement clients.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Milan Box Corporation |
| Tri-State Crating & Pallet Co. |
| Mil-Spec Industries |
| Conco Inc. |
| Modular Container Systems |
| CN ROMTEHNICA SA |
| Nordic Armoury OU |
| Safewell |
| Others |
Value Chain & Pricing Dynamics
NATO defense procurement agencies concentrate purchasing power through multi-year armory modernization contracts, anchoring value-based pricing models where certification tiers and electromagnetic hardening specifications determine premiums. Fixed-price defense contracts absorb ballistic-grade steel volatility while modular rapid-deployment systems command throughput-linked premiums for eastern flank reinforcement capabilities.
Pricing Analysis
Outcome-based pricing anchored to operational readiness uptime governs military depot procurement, with NATO STANAG certification tiers separating premium electromagnetic-pulse-hardened systems from standard fixed-installation cabinets. REACH compliance costs for halogen-free polymer reformulation intensify margin pressure on European suppliers serving Bundeswehr contracts. Law enforcement buyers in Texas and Florida exhibit highest price sensitivity through operational expenditure preferences, while nuclear-biological-chemical hardened custom solutions sustain lowest sensitivity due to engineering scarcity.
Supply Chain Analysis
EPA hazardous material containment certification and NATO STANAG qualification requirements gate supplier entry, concentrating ballistic-grade steel fabrication in the United States, Germany, and Poland. Production draws from specialized steel alloy inputs, fire-resistant insulation materials, and climate-control sensor components. Single-source vulnerability in electromagnetic shielding alloys elevates risk exposure. Distribution runs through defense procurement agency direct contracts and law enforcement cooperative purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into specialized steel alloy supply and predictive maintenance service unbundling constitutes the dominant competitive race, with incumbents capturing upstream margin and downstream recurring revenue simultaneously.
For Market Incumbents: Anticipate REACH-driven polymer reformulation costs by securing mineral wool and aerogel supplier partnerships before ECHA restriction enforcement tightens. Certify electromagnetic-pulse-hardened systems to NATO STANAG specifications ahead of eastern flank demand surges in Poland and Romania. Channel control through exclusive service contracts with U.S. Department of Defense depots defends against modular container commoditization. For New Entrants and Emerging Players: The mid-tier pricing gap between premium NATO-certified systems and economy-grade residential cabinets offers white-space entry through RFID-enabled retrofit kits for police armories. Target law enforcement digitization cycles in Germany and France where budget constraints favor smart cabinet upgrades over full replacement. Pursue cradle-to-cradle certification to capture EU Green Deal circular economy subsidies in Lyon and Marseille defense industrial zones. For Investors and Strategic Acquirers: Distressed-cycle entries favor fireproofing specialists with humidity control IP in coastal European markets where climate-resilient coatings converge with nanotechnology surface treatments. Long-term viability hinges on predictive maintenance platform scalability across NATO member state armories. Watch for explosive storage quantity-distance regulation tightening as the inflection signal triggering facility redesign investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA halogenated flame retardant restrictions force mineral wool and aerogel adoption for Bundeswehr contract retention. |
| RFID-Enabled Inventory Integration | Texas and Florida police armory software convergence creates standalone retrofit revenue streams. |
| Predictive Maintenance Platform Buildout | Sensor-embedded units with remote diagnostics capture unbundled after-sales service contracts from OEMs. |
| Electromagnetic Pulse Hardening Certification | NATO STANAG compliance for nuclear-biological-chemical specifications commands premium positioning in eastern flank markets. |
| Cradle-to-Cradle Production Certification | EU Green Deal circular economy subsidies reward sustainable manufacturing in Lyon and Marseille defense zones. |
Study Parameters
Multi-period observation of NATO armory modernization program allocations, REACH compliance implementation timelines, and civilian firearms ownership patterns anchored the trend analysis, supplemented by interviews with defense procurement officers, armory facility managers, explosives safety engineers, and climate-control technology integrators. Secondary validation drew from EPA hazardous material containment filings, ECHA restriction proposal databases, NATO standardization agreement repositories, and U.S. Department of Defense budget justification documents. Bottom-up segment sizing triangulated against top-down defense expenditure macro indicators.
Input-output matrices modeled demand drivers across product type, end user security clearance tier, installation mobility requirements, and storage capacity thresholds throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated ballistic-grade steel price indices, ECHA regulatory phase-in schedules, and NATO eastern flank reinforcement procurement announcements.
Inputs from EPA and ECHA regulatory filings were available through the study window; gaps in classified electromagnetic-pulse-hardening specification adoption rates introduce uncertainty bands around premium segment forecasts. Model refresh is warranted upon material change in explosive storage quantity-distance regulation enforcement or NATO STANAG interoperability mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market