
 Smart Bombs Market | 2026-2036
Smart Bombs Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bombs Market Analytics
The divergence between precision-guided munitions with multi-mode seekers and legacy laser-only kits is repositioning procurement hierarchies across NATO arsenals. Lockheed Martin leverages its JASSM franchise to dominate long-range standoff requirements. Raytheon Technologies sustains portfolio breadth across both tactical and strategic strike classes.
Smart bombs are air-delivered munitions incorporating guidance packages—laser, GPS, or multi-spectral infrared seekers—with fin actuation systems achieving circular error probable below three meters, designed to destroy point targets while minimizing collateral damage. GPS-Guided and Laser-Guided types occupy distinct operational niches, with satellite-aided weapons preferred in degraded visual environments and laser designator-dependent systems retaining relevance for time-sensitive targeting. Military and Defense Forces applications anchor procurement volumes, while Counter-Terrorism missions drive demand for smaller warhead variants with reduced blast radii.
The US Department of Defense, NATO standardization bodies, and national export control regimes shape market access through International Traffic in Arms Regulations and allied technology transfer frameworks. Compliance with these multilateral control systems determines foreign military sale eligibility and joint development participation. Stakeholders must track congressional appropriations cycles and allied burden-sharing negotiations to anticipate procurement timing and technology co-investment windows.
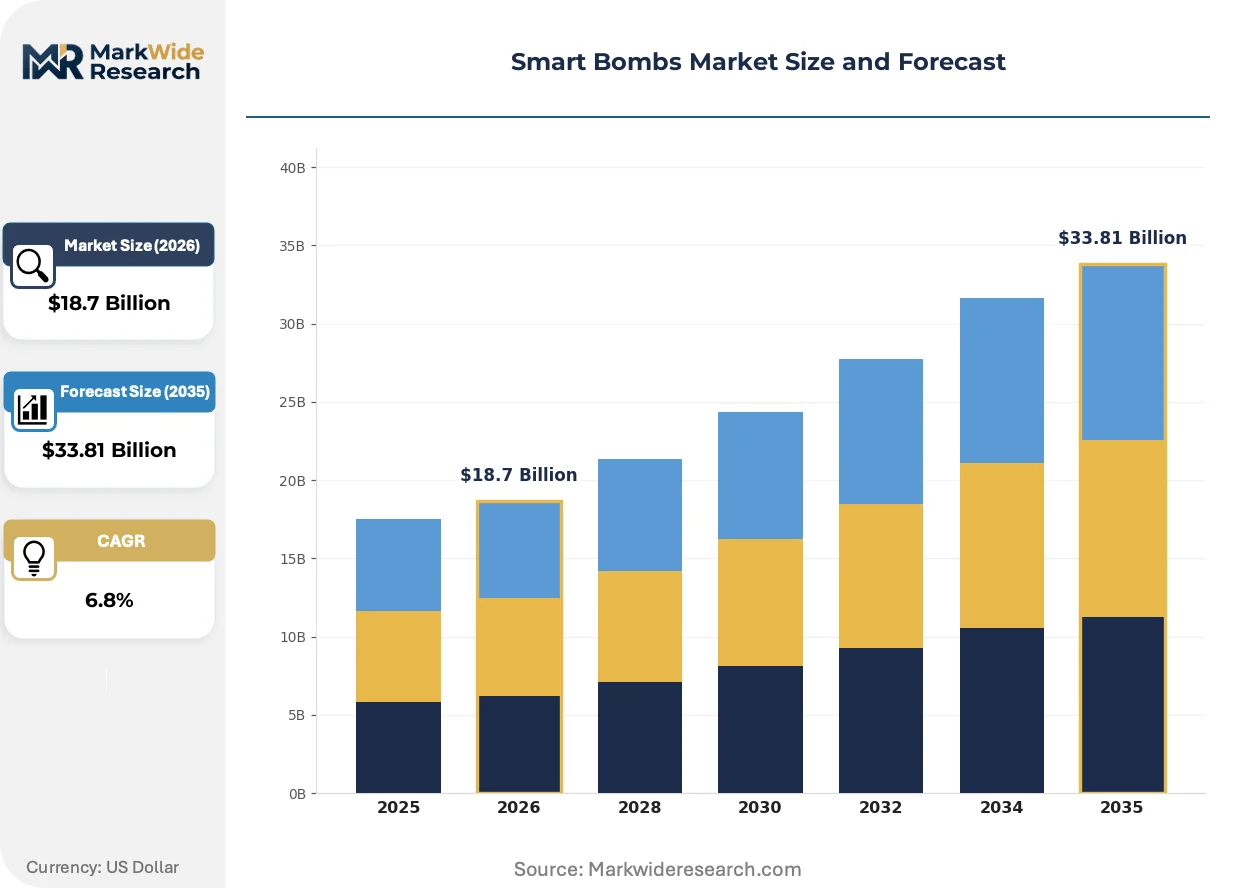
Market Dynamics
Multi-mode seeker architectures are compressing procurement timelines for NATO air forces, as legacy laser-only inventories face accelerated retirement schedules under networked munitions directives.
Growth Catalysts
- ITAR modernization:Streamlined foreign military sale licensing under revised International Traffic in Arms Regulations protocols accelerates allied burden-sharing programs and joint development access.
- Counter-terrorism targeting doctrine:Reduced collateral damage requirements drive demand for smaller warhead variants with precision below three-meter circular error probable.
- Networked kill chains:Sensor-to-shooter data link integration enables time-sensitive targeting in GPS-denied environments, expanding operational envelopes for standoff weapons.
Market Restraints
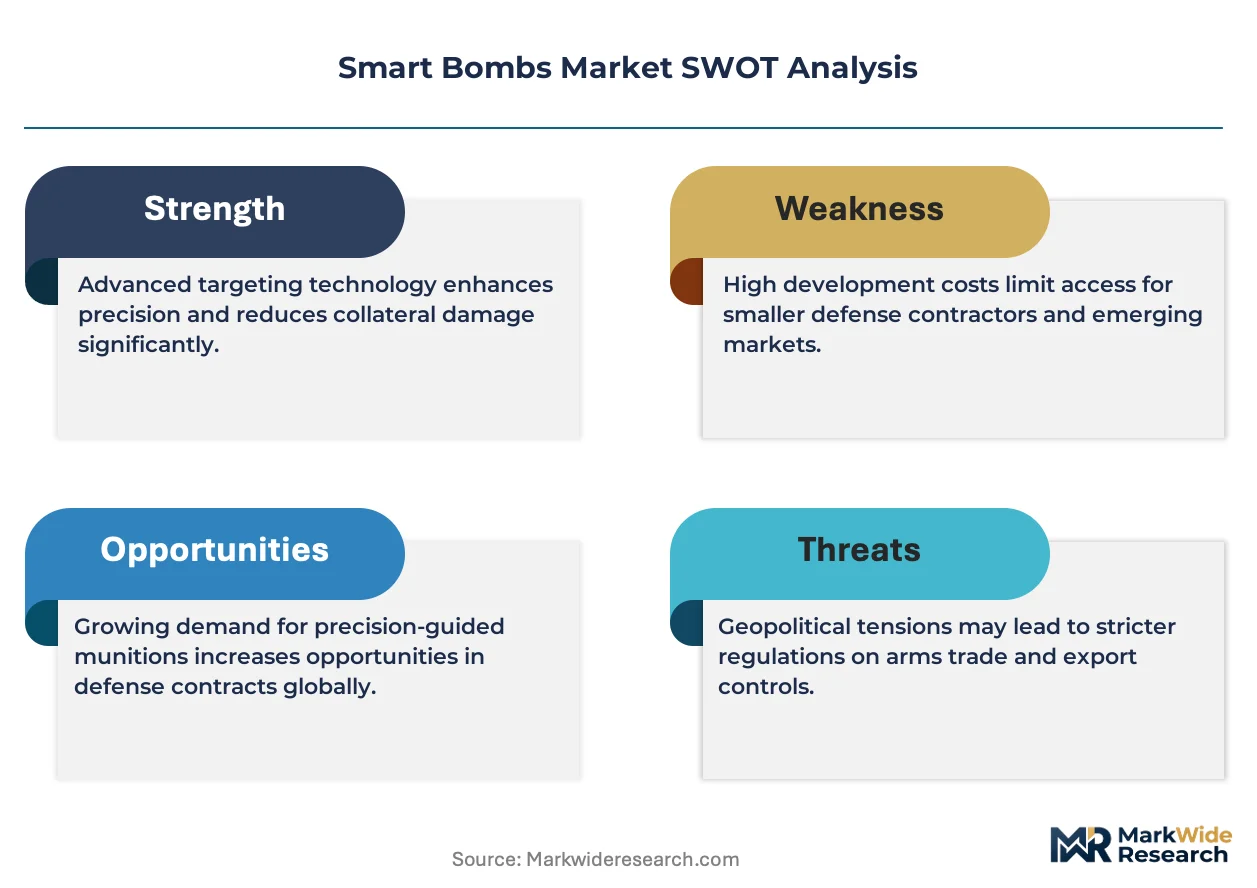
- Seeker component concentration:Infrared focal plane array production concentrates among limited qualified suppliers, creating single-source vulnerability for multi-spectral guidance packages.
- Export control friction:National disclosure policy variations between State Department and allied licensing regimes delay technology transfer timelines for co-development programs.
- Legacy platform integration costs:Retrofit of digital weapon interfaces onto analog aircraft bus architectures demands non-recurring engineering outlays that strain non-NATO procurement budgets.
Strategic Opportunities
- Pacific theater posture:Aerial denial environments in the first island chain create demand for long-range standoff munitions with autonomous target recognition.
- Dual-use seeker convergence:Commercial satellite imagery resolution advances enable military-grade navigation aid validation at reduced non-recurring cost.
- Allied industrial base expansion:NATO standardization agreements open prime contractor subcontracting tiers to qualified European and Asia-Pacific component suppliers.
Industry Challenges
- Guidance algorithm talent scarcity:Machine learning specialists with security clearances remain concentrated among defense primes, constraining mid-tier seeker house expansion.
- Environmental test infrastructure:Hardened electronics qualification against electromagnetic pulse and thermal shock requires capital-intensive range access controlled by national laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bombs Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Guided, Laser-Guided, GPS-Guided, Precision Application: Military, Defense Forces, Tactical Operations, Counter-Terrorism End User: Government, Armed Forces, Private Contractors, Defense Agencies Technology: Infrared, Satellite-Based, Inertial Navigation, Semi-Active |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, Northrop Grumman Corporation, BAE Systems plc, The Boeing Company, General Dynamics Corporation, Elbit Systems Ltd, Israel Aerospace Industries Ltd, L3Harris Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bombs Market Evolving Landscape
Autonomous target recognition capabilities are compressing the sensor-to-shooter timeline, while hardened electronics architectures adapt to contested electromagnetic environments.
Multi-spectral infrared seekers with embedded artificial intelligence processors are rewriting engagement protocols for moving targets in cluttered terrain. Air forces across NATO are fielding these systems for armored vehicle prosecution at extended standoff distances. The technology is rewriting the cost-exchange calculus between precision munitions and layered air defense networks.
REACH chemical restrictions on hazardous substances in electronics are compelling seeker manufacturers to reformulate solder compositions and conformal coatings. Industrial consequence includes extended qualification timelines for redesigned circuit card assemblies. European prime contractors are responding by qualifying alternative material sets ahead of mandated phase-out dates.
Multi-year munitions procurement contracts with fixed-price escalation clauses are displacing annual appropriation cycles for major NATO air forces. Defense ministries in Germany, France, and the United Kingdom are consolidating guided weapons acquisitions under framework agreements spanning five to seven years. This pattern is most visible in precision strike inventory modernization programs where budget predictability outweighs unit cost flexibility.
Smart Bombs Market Segmentation
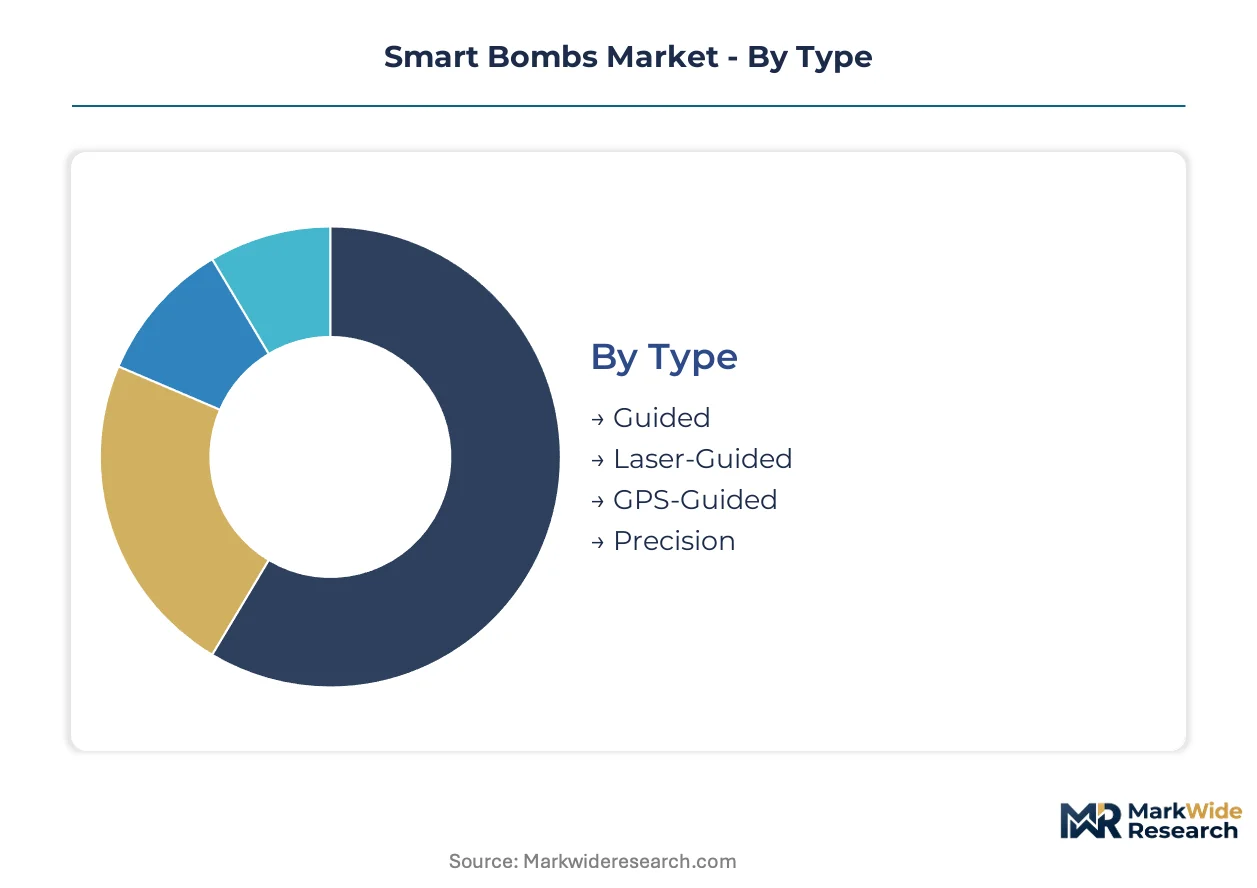
Guidance architecture and seeker technology fundamentally determine unit economics and procurement eligibility across defense arsenals. Procurement officers segment inventories by operational envelope, collateral damage tolerance, and platform integration requirements rather than warhead yield alone.
Type:
Capital intensity escalates sharply with seeker complexity and multi-mode redundancy, with satellite-aided systems demanding the heaviest upfront non-recurring engineering investments.
- GPS-Guided:Satellite-aided navigation with anti-jam waveform receivers enables all-weather delivery without target illumination. United States Air Force procurement concentrates here for contested electromagnetic environments where laser designation proves unreliable.
- Laser-Guided:Semi-active seekers dependent on external designation achieve sub-three-meter accuracy at reduced unit cost. Tactical air controllers in close air support missions drive residual demand despite weather limitations.
- Guided:Umbrella category capturing hybrid seekers with redundant guidance modes. Dual-mode architectures command premium pricing but reduce mission abort rates in degraded visibility.
- Precision:Advanced terminal guidance with millimeter-wave or imaging infrared for moving target engagement. Specialized applications in armored vehicle prosecution absorb concentrated development budgets.
GPS-Guided inventories absorb the bulk of installed capacity across NATO arsenals; Precision variants are expanding most quickly under autonomous targeting roadmaps.
Application:
Operational tempo and rules of engagement determine procurement volumes, with sustained high-intensity missions consuming munitions at rates that strain industrial surge capacity.
- Military:State-on-state conflict preparation drives bulk acquisitions for major combat operations. Pentagon budget submissions prioritize these stockpiles under great-power competition frameworks.
- Defense Forces:Territorial defense and deterrence postures sustain steady-state production lines. European NATO members channel procurement through multinational framework contracts.
- Tactical Operations:Time-sensitive targeting against mobile or emergent threats demands rapid sensor-to-shooter architectures. Special operations forces drive requirements for reduced collateral damage variants.
- Counter-Terrorism:Surgical strikes in populated areas mandate sub-hundred-pound warheads with restricted blast radii. Intelligence-driven targeting cycles favor smaller lot purchases with accelerated refresh rates.
Military applications anchor absolute procurement tonnage; Counter-Terrorism missions are climbing the fastest as urban warfare doctrine evolves.
End User:
Budget authority and accountability standards segment procurement channels, with sovereign governments retaining final release authority even for contractor-operated platforms.
- Armed Forces:Uniformed services with organic air wings constitute the dominant demand channel. Multi-year procurement contracts with fixed-price escalation clauses characterize these acquisitions.
- Government:Civilian defense ministries and national armaments directors control appropriations and release-to-target authority. Congressional oversight shapes timing and technology transfer permissions.
- Defense Agencies:Research and development organizations fund technology maturation prior to operational fielding. DARPA and equivalent European bodies seed seeker algorithm advances.
- Private Contractors:Security firms operating government-owned aircraft under lease arrangements access inventories through foreign military sale frameworks. Limited to non-strategic munitions categories under export control protocols.
Armed Forces retain the steepest expansion trajectory as allied burden-sharing agreements expand precision strike inventories.
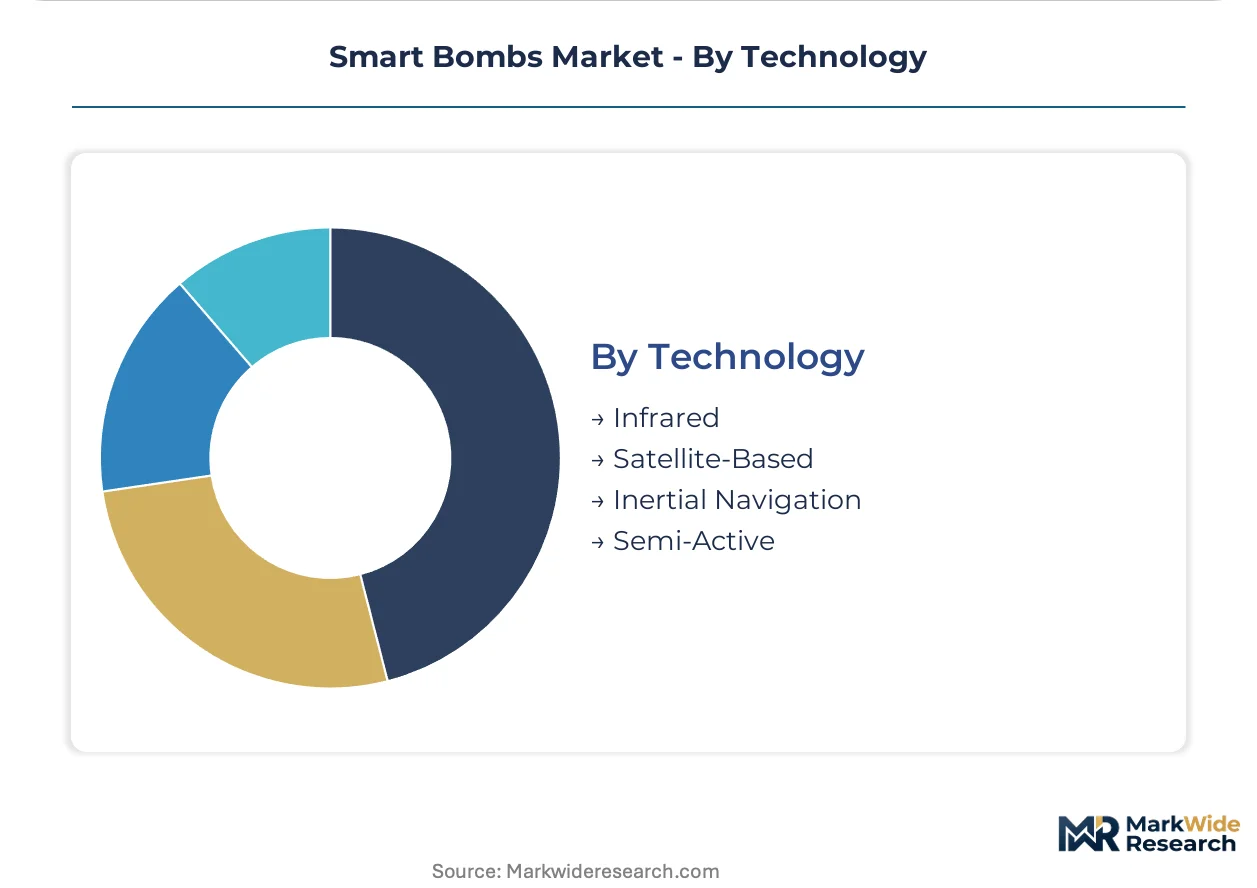
Technology:
Seeker modality determines environmental tolerance and countermeasure susceptibility, with multi-spectral fusion architectures commanding the steepest development cost curves.
- Satellite-Based:GPS and forthcoming multi-constellation receivers with military-grade anti-spoofing. Preferred for standoff delivery where line-of-sight designation proves impractical.
- Infrared:Imaging seekers with artificial intelligence-enabled target recognition for moving vehicle prosecution. Pacific theater requirements for maritime strike are accelerating fielding timelines.
- Inertial Navigation:Self-contained guidance for GPS-denied environments, typically fused with other modalities. Submarine-launched standoff weapons rely on these architectures.
- Semi-Active:Laser or radar reflectance seekers requiring continuous external illumination. Lowest unit cost but highest coordination burden on forward air controllers.
Satellite-Based seekers dominate current inventories; Infrared systems are gaining share fastest under autonomous target recognition roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C. and the surrounding defense corridor dominate smart bomb procurement planning, with congressional appropriations committees determining multi-year guided weapons acquisition cycles that ripple through allied arsenals worldwide.
United States
Pentagon budget submissions prioritize precision strike inventories under great-power competition frameworks, with the Department of Defense driving networked munitions directives. International Traffic in Arms Regulations protocols govern foreign military sale eligibility and technology transfer permissions. The Arizona-Texas defense manufacturing belt hosts final assembly operations for satellite-aided weapon systems.
United Kingdom
Royal Air Force precision strike modernization programs sustain demand for dual-mode seeker architectures capable of degraded environment operations. Ministry of Defence framework agreements consolidate guided weapons acquisitions under five-to-seven-year procurement contracts. The Stevenage-Farnborough aerospace cluster concentrates seeker integration and systems engineering expertise.
Germany
Bundeswehr participation in NATO burden-sharing agreements expands precision munitions stockpiles for territorial defense postures. Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support manages multinational framework contracting for guided weapons. The Bavaria and Baden-Württemberg industrial regions host subsystem suppliers qualified under NATO standardization agreements.
Israel
Israel Defense Forces operational requirements drive development of reduced-collateral-damage variants for urban warfare applications. Ministry of Defense directorates control release-to-target authority and technology export licensing for co-developed seeker systems. The Negev Desert test ranges support hardened electronics qualification against electromagnetic pulse and thermal shock environments.
France
Direction Générale de l'Armement oversees multi-year munitions procurement with fixed-price escalation clauses replacing annual appropriation cycles. French armed forces prioritize autonomous target recognition capabilities for armored vehicle prosecution at extended standoff distances. The Île-de-France and Provence-Alpes-Côte d'Azur corridors concentrate prime contractor engineering and integration facilities.
Smart Bombs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across seeker complexity and integration depth, with multi-mode guidance architectures commanding pricing multiples over legacy laser-only kits. The vendor base concentrates among defense primes with captive access to security-cleared engineering talent and national test infrastructure. Two strategic archetypes dominate: vertically integrated primes controlling full weapon system development, and specialized seeker houses supplying focal plane arrays and guidance algorithms. Competitive dynamics center on multi-year procurement contract capture and NATO standardization agreement participation.
Within the vertically integrated prime tier, Lockheed Martin Corporation and Raytheon Technologies Corporation occupy positions as archetypal system-of-systems providers. Lockheed Martin exemplifies the long-range standoff franchise model through its JASSM program dominance. Raytheon Technologies represents portfolio breadth across tactical and strategic strike classes. Elbit Systems Ltd anchors the specialist tier as an Israel-based defense electronics provider with integrated munitions capabilities.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| The Boeing Company |
| General Dynamics Corporation |
| Elbit Systems Ltd |
| Israel Aerospace Industries Ltd |
| L3Harris Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Infrared focal plane array pricing indices cascade through smart bomb manufacturing into three-tier pricing structure across premium, standard, and economy levels, with multi-mode seeker architectures commanding substantial premiums over legacy laser-only kits due to concentrated supplier qualification requirements under ITAR protocols.
Pricing Analysis
Circular error probable performance anchors value-based pricing tiers, with sub-three-meter accuracy specifications driving substantial premiums over standard guidance packages. Price differentiation separates ITAR-compliant multi-mode systems from export-restricted single-mode alternatives, while volume procurement under multi-year Pentagon contracts reduces unit costs for Armed Forces buyers. Cost compression in laser-guided tiers is intensifying because commercial sensor technology diffusion erodes historical seeker premiums. Defense Agencies exhibit lowest price sensitivity due to R&D mission requirements; Private Contractors face highest budget constraints under foreign military sale frameworks.
Supply Chain Analysis
Dual-sourcing mandates for infrared focal plane arrays compel prime contractors to qualify secondary suppliers across the United States, Israel, and France despite concentrated production expertise. Supply chains draw from gallium arsenide substrate foundries, precision optics manufacturers, and hardened electronics packagers. Single-source vulnerability persists for anti-jam GPS receiver modules qualified under military standards. Distribution runs through national armaments directors and foreign military sale channels rather than commercial logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITAR compliance costs create substantial barrier-to-entry moats for smart bomb market participants, with International Traffic in Arms Regulations certification timelines filtering out undercapitalized entrants and preserving incumbent pricing power.
For Market Incumbents: Extend JASSM franchise dominance through captive production of multi-spectral infrared seekers, reducing reliance on qualified focal plane array suppliers. Accelerate digital weapon interface retrofits for allied analog aircraft fleets under NATO standardization agreements. Vertical integration into seeker algorithm development mitigates machine learning talent scarcity threatening mid-tier competitors. For New Entrants and Emerging Players: Begin with counter-terrorism reduced-collateral-damage variants where lot sizes remain small and refresh cycles accelerate procurement opportunities. Private contractor foreign military sale channels offer most penetrable entry path given lower ITAR scrutiny thresholds. Partner with European subsystem suppliers qualified under NATO standardization agreements to bypass prime contractor captive supply chains. For Investors and Strategic Acquirers: The window for entry favors specialized seeker houses with security-cleared engineering talent and national test infrastructure access. Long-term viability rests on multi-year procurement contract capture rather than spot market opportunism. Congressional defense appropriations committee composition shifts signal inflection points for precision strike inventory modernization funding trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Mode Seeker Integration | Reduces mission abort rates in degraded visibility environments across NATO arsenals. |
| ITAR Compliance Investment | Unlocks foreign military sale eligibility and joint development participation with allied defense ministries. |
| Digital Weapon Interface Retrofit | Enables legacy platform compatibility for networked munitions directives without airframe replacement. |
| Autonomous Target Recognition Development | Compresses sensor-to-shooter timelines for time-sensitive targeting in GPS-denied Pacific theater environments. |
| Allied Industrial Base Expansion | Opens prime contractor subcontracting tiers to European and Asia-Pacific component suppliers under NATO agreements. |
Research Methodology
Independent corroboration across Pentagon budget justification documents, NATO standardization agreement registries, and congressional defense appropriations records underwrites the qualitative findings. Primary interviews with precision strike program officers, seeker systems engineers, foreign military sale licensing specialists, and national armaments procurement directors combined with secondary validation from Department of Defense contract announcements, ITAR regulatory filings, and allied defense ministry framework agreement disclosures. Bottom-up unit economics modeling and top-down budget allocation triangulation anchored market sizing across the analysis window.
Comparable-period anchoring to historical congressional appropriations cycles and allied burden-sharing negotiation timelines structured the forecast framework. Modeled dimensions span guidance architecture complexity, seeker technology modality, operational application intensity, and end-user budget authority tier. CAGRs derived from procurement volume trajectories and technology refresh cycle assumptions. Forecast inputs incorporated electromagnetic environment degradation scenarios and autonomous targeting roadmap maturity assessments.
Congressional appropriations delays, allied burden-sharing renegotiations, and seeker component supply disruptions are the dominant revision risks. Deviation in congressional defense committee composition would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market