
 Global Ammunition Market | 2026-2036
Global Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ammunition Market Analysis
Buyer concentration among defense procurement agencies is repositioning contract dynamics toward multi-year framework agreements with integrated logistics support. General Dynamics Corporation leverages its Lake City Army Ammunition Plant operations to sustain high-volume small-caliber supply commitments to the US military. Rheinmetall AG anchors European NATO supply through its expanded Unterlüß manufacturing complex and joint ventures in Hungary. Nammo AS specializes in niche propellant and precision munitions for Nordic and allied forces, competing on technical performance rather than scale.
Ammunition comprises projectiles, propellants, primers, and casings engineered to precise chamber-pressure and ballistic specifications for reliable firearm and artillery function. Manufacturing employs drawn brass casings, extruded propellant grains, and pressed explosive fills, with lot-to-lot consistency governed by NATO STANAG or national military standards. Small caliber rounds dominate volume flows, though smart munitions command premium margins as militaries prioritize accuracy over saturation. Artillery shells represent the most capital-intensive segment, with forge and filling capacity constraining near-term supply elasticity across Western producers.
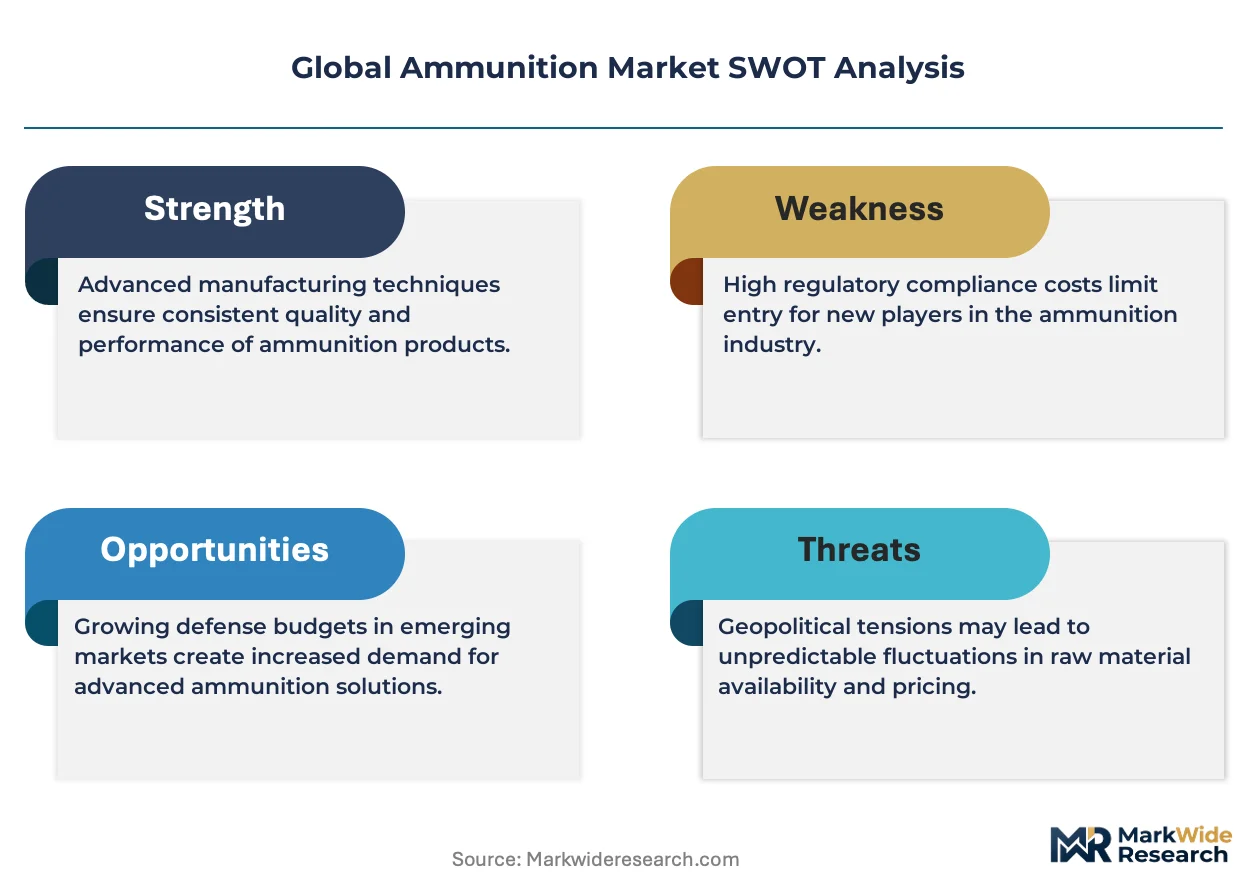
US ITAR regulations, EU REACH chemical restrictions, and NATO STANAG interoperability standards collectively shape cross-border trade eligibility and product formulation choices. The US Department of State's Directorate of Defense Trade Controls restricts technology transfer for advanced propellants and guidance packages, while ECHA scrutiny of lead and nitrocellulose supply chains forces reformulation investments. Stakeholders must monitor how diverging transatlantic environmental compliance timelines affect component sourcing and facility certification requirements.
Market Dynamics
Defense procurement agencies are consolidating ammunition orders into multi-year framework agreements that bundle manufacturing with integrated logistics support, compressing supplier margins while locking in volume commitments across NATO arsenals.
Growth Catalysts
- NATO STANAG interoperability mandates:Standardized chamber-pressure and ballistic specifications enable cross-border supply pooling, allowing member states to share stockpiles during operational surges without compatibility failures.
- Next Generation Squad Weapons acceleration:The US Department of Defense's program generates pull-through demand for advanced small-caliber systems with improved propellant chemistry and case materials.
- Artillery shell replenishment cycles:Sustained operational commitments in Eastern Europe deplete Western stockpiles, forcing Germany, South Korea, and the United States to accelerate forge and filling capacity expansions.
Market Restraints
- Lead and nitrocellulose supply chain constraints:ECHA REACH scrutiny forces reformulation investments, raising input costs for traditional propellant chemistries while alternative supply routes remain underdeveloped.
- Western forge capacity concentration:Artillery shell production relies on a limited number of certified forging facilities in Germany and the United States, creating bottleneck risk during demand spikes.
- US ITAR technology transfer restrictions:The Department of State's Directorate of Defense Trade Controls blocks cross-border collaboration on advanced guidance packages, fragmenting precision munitions development.
Strategic Opportunities
- Hungarian joint venture manufacturing:Rheinmetall AG's expanded Unterlüß complex and Hungarian partnerships create Eastern European production nodes that reduce NATO supply vulnerability.
- Smart munitions accuracy premiums:Militaries prioritize precision over saturation, opening margin expansion for guidance-enabled artillery and mortar rounds with terminal seeker integration.
- Nordic propellant specialization:Nammo AS leverages niche technical capabilities to supply allied forces with customized explosive fills outside mass-market competition.
Industry Challenges
- Skilled pyrotechnic workforce scarcity:Aging expertise in extruded propellant grain formulation and pressed explosive fill processing limits facility expansion timelines across Western producers.
- Lot-to-lot consistency certification:NATO STANAG and national military standards require exhaustive testing protocols that extend qualification cycles for new manufacturing lines.
- Legacy brass casing integration:Drawn brass supply chains must synchronize with emerging polymer and steel case alternatives without disrupting existing firearm chamber specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ammunition Market |
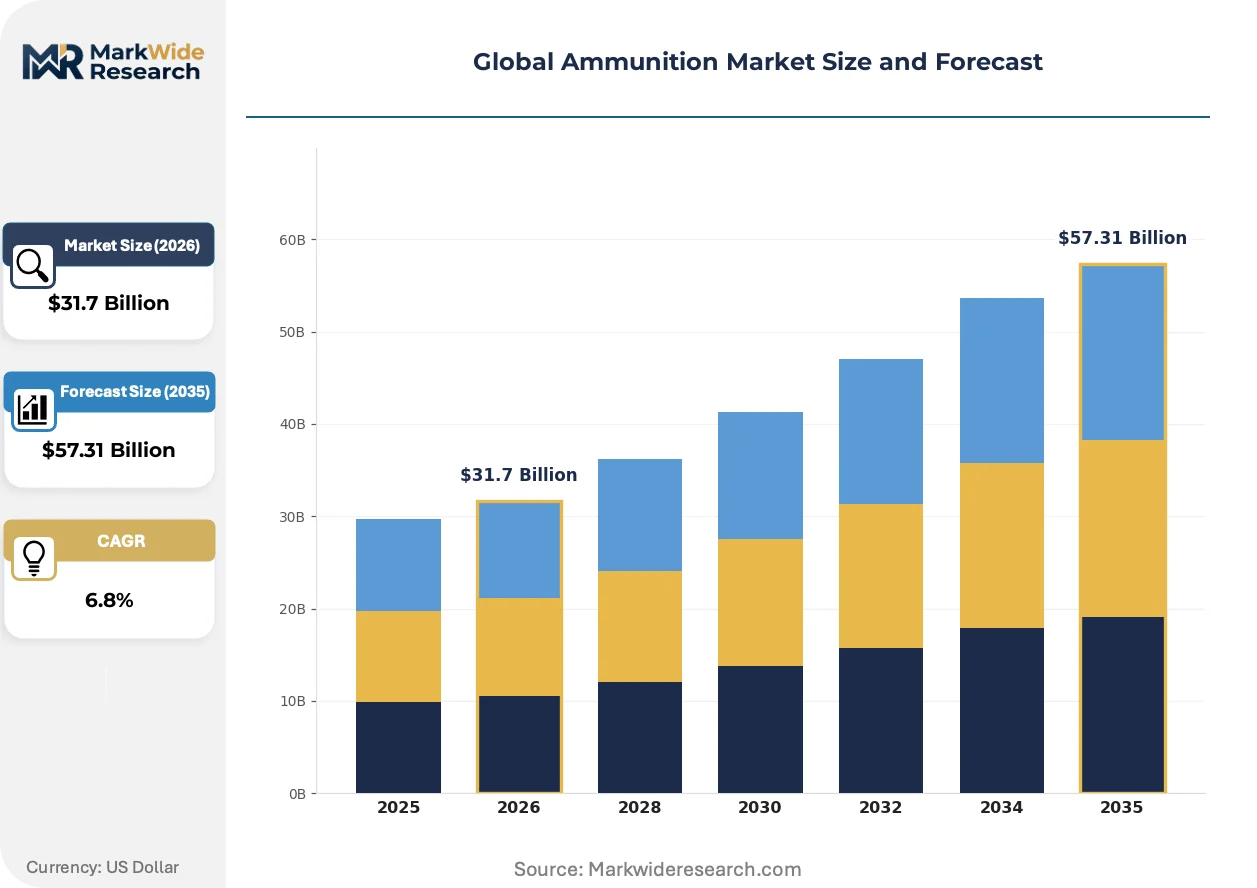
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $57.31 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Caliber, Medium Caliber, Large Caliber, Artillery Shells Application: Military, Law Enforcement, Hunting, Sports Shooting Technology: Conventional, Smart Munitions, Non-Lethal, Frangible Distribution Channel: Direct Sales, Online Retail, Wholesalers, Brick-and-Mortar Stores |
| Companies Covered | General Dynamics Corporation, AMMO, Inc., BAE Systems PLC, FN Herstal, Hanwha Corporation, Rheinmetall AG, Nammo AS, CBC Global Ammunition, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ammunition Market Emerging Trajectories
Precision guidance hardware is migrating down-caliber from artillery to mortar and small-arms systems, while environmental compliance pressures force simultaneous reformulation of propellant chemistry and primer compositions.
Modular fuze architectures are unifying proximity, point-detonating, and delay functions within standardized form factors. Artillery units across NATO forces are fielding these systems to reduce logistics burden and training complexity. This convergence is unifying previously separate supply chains for dumb and smart munitions, enabling manufacturers to convert forge capacity between product tiers with minimal retooling.
ECHA REACH chemical restrictions are tightening lead and nitrocellulose sourcing across European supply chains. Manufacturers face forced investments in green propellant alternatives and lead-free primer formulations. Small-caliber producers in Germany and Scandinavia are responding fastest, leveraging existing environmental compliance infrastructure to secure early certification advantages.
Multi-year framework agreements with embedded logistics support are displacing transactional spot purchasing across defense procurement agencies. Prime contractors capture aftermarket revenue streams previously held by third-party distributors. This consolidation is most visible in United States and German military supply, where General Dynamics and Rheinmetall anchor integrated service contracts spanning manufacturing through depot maintenance.
Global Ammunition Market Segmentation
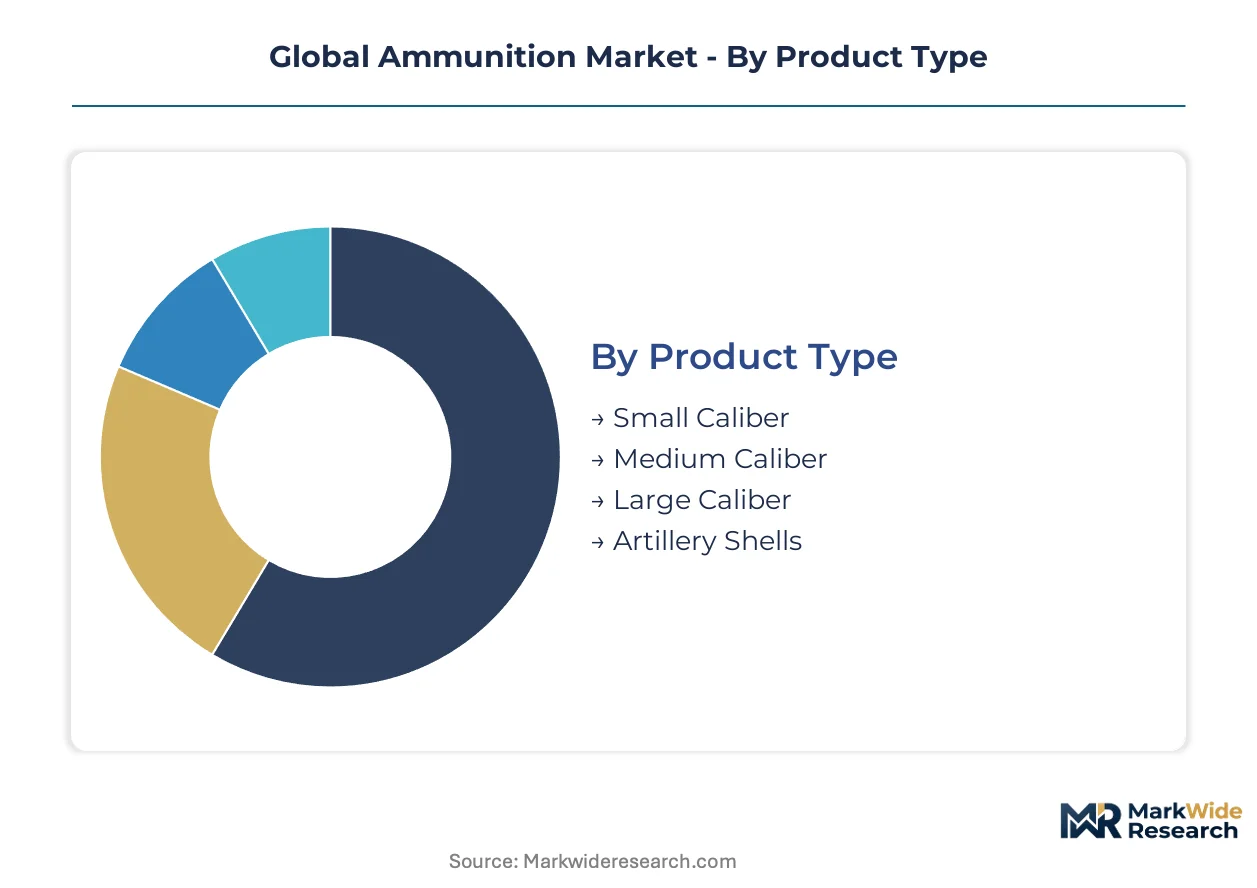
Ammunition markets segment across four critical dimensions that determine manufacturing configuration, certification requirements, and margin structure. Product caliber dictates forge and filling capital intensity. Application sets regulatory oversight and procurement channel. Technology tier separates commodity volume from precision premium. Distribution channel governs customer access and compliance burden.
Product Type:
Supply concentration clusters around artillery shell forging capacity, with Western producers maintaining tight control over certified large-caliber production nodes.
- Small Caliber:Rounds up to 20mm dominate unit volume across NATO arsenals, with drawn brass casing supply chains concentrated at General Dynamics' Lake City operations and Rheinmetall's Unterlüß complex. The US Department of Defense's Next Generation Squad Weapons program is pulling demand toward advanced propellant chemistries and polymer case alternatives.
- Artillery Shells:105mm through 155mm rounds require the most capital-intensive manufacturing, with forge capacity concentrated in Germany and the United States creating supply bottlenecks during Eastern European replenishment surges. ECHA REACH scrutiny of pressed explosive fills extends qualification cycles for new production lines.
- Medium Caliber:20mm to 40mm systems serve vehicle-mounted autocannons and naval close-in weapon systems, with demand concentrating in South Korean and German naval modernization programs.
- Large Caliber:Tank and naval gun ammunition above 40mm relies on limited Western forge certification, with NATO STANAG interoperability enabling cross-border supply pooling during operational spikes.
Today's leader: Small Caliber. Tomorrow's challenger: Artillery Shells.
Application:
Customer type determines procurement channel, with defense agencies consolidating into multi-year frameworks while commercial buyers face diverging regulatory pathways.
- Military:Defense procurement agencies across NATO member states are bundling manufacturing with integrated logistics support, compressing supplier margins while locking in volume. US ITAR regulations restrict technology transfer for advanced propellants and guidance packages.
- Law Enforcement:Domestic security agencies in Germany and the United States drive specialized non-lethal and frangible round demand, with certification requirements fragmenting supply chains between military and civilian specifications.
- Hunting:Lead-free primer mandates under ECHA REACH are forcing reformulation investments across Scandinavian and German markets, raising input costs while alternative supply routes remain underdeveloped.
- Sports Shooting:Competitive and recreational demand concentrates in the United States and Germany, with online retail channels expanding access while brick-and-mortar stores face inventory compliance burdens.
Military contracts anchor current revenue. Law Enforcement and Sports Shooting are expanding most quickly as procurement diversifies.
Technology:
Margin stratification separates commodity volume from precision premium, with guidance-enabled systems commanding multiples over conventional rounds.
- Smart Munitions:Terminal seeker integration for artillery and mortar rounds captures accuracy premiums as militaries prioritize precision over saturation. US ITAR restrictions fragment cross-border development collaboration.
- Conventional:Unguided projectiles, propellants, and primers governed by NATO STANAG specifications enable supply pooling but face margin compression from multi-year framework agreements.
- Non-Lethal:Rubber projectiles, flash-bang rounds, and chemical irritant delivery systems serve law enforcement and peacekeeping mandates, with formulation standards varying across US, German, and South Korean procurement.
- Frangible:Sintered metal and polymer composite rounds designed for close-quarters training and steel-target shooting are gaining share fastest in US and German commercial markets.
Conventional rounds dominate volume. Smart Munitions claim the steepest expansion trajectory.
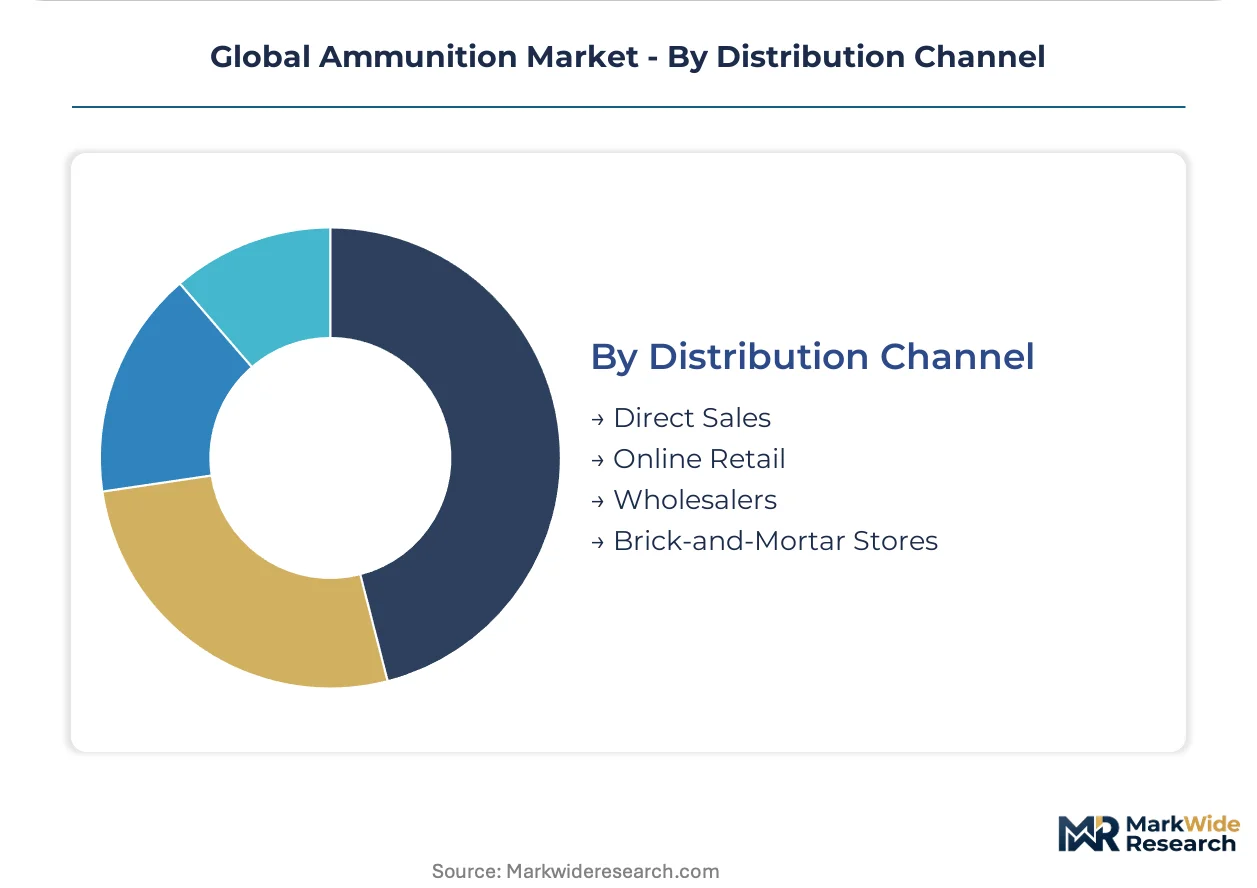
Distribution Channel:
Channel configuration reflects customer regulatory exposure, with defense direct sales insulated from commercial compliance complexity.
- Direct Sales:Prime contractors capture defense procurement agency contracts spanning manufacturing through depot maintenance, displacing third-party distributors in the United States and Germany.
- Online Retail:E-commerce platforms expand sports shooting and hunting access while navigating divergent US state-level and EU national licensing requirements.
- Wholesalers:Intermediary networks sustain law enforcement and smaller military procurement outside NATO framework agreements, with inventory certification extending lead times.
- Brick-and-Mortar Stores:Physical retail maintains hunting and sports shooting presence in Germany and the United States, facing margin pressure from online competition and storage compliance costs.
Direct Sales commands defense volume. Online Retail is climbing the fastest in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains deeper artillery shell stockpiles than Germany, yet both nations face parallel pressure to expand forge capacity amid Eastern European replenishment cycles. Demand trajectories diverge across procurement systems, with framework agreements consolidating supply in NATO members while South Korea pursues independent naval modernization.
United States
The Department of Defense's Next Generation Squad Weapons program accelerates requirements for advanced small-caliber systems with polymer case alternatives. ITAR regulations administered by the Department of State's Directorate of Defense Trade Controls restrict technology transfer for advanced propellants. General Dynamics operates the Lake City Army Ammunition Plant in Missouri, sustaining high-volume supply commitments through integrated manufacturing and depot maintenance contracts.
Germany
Rheinmetall AG anchors European NATO supply through expanded forge capacity at its Unterlüß manufacturing complex and joint ventures in Hungary. ECHA REACH scrutiny of lead and nitrocellulose supply chains forces reformulation investments across propellant chemistry. The Unterlüß cluster in Lower Saxony concentrates certified artillery shell production, creating supply bottlenecks during demand spikes that require cross-border pooling mechanisms.
South Korea
Hanwha Corporation drives naval modernization programs generating demand for medium-caliber autocannon and close-in weapon systems. The country's defense procurement agency consolidates orders into multi-year frameworks with embedded logistics support. Manufacturing activity concentrates in the Busan-Ulsan industrial corridor, where shipyard integration aligns ammunition supply with naval vessel construction schedules.
United Kingdom
BAE Systems PLC maintains precision munitions capabilities serving allied forces through NATO STANAG interoperability frameworks. UK defense procurement channels prioritize smart munitions accuracy premiums over saturation volume. Production clusters in the North West England and South West regions sustain forge and filling capacity for artillery shell qualification under exhaustive testing protocols.
Norway
Nammo AS specializes in niche propellant formulations and precision munitions for Nordic and allied forces, competing on technical performance rather than scale. National environmental compliance infrastructure accelerates lead-free primer certification under REACH-aligned domestic regulations. The Raufoss industrial park anchors specialized explosive fill processing, leveraging aging pyrotechnic expertise that limits facility expansion timelines across Western producers.
Global Ammunition Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure consolidating around multi-year framework agreements with integrated logistics support. Prime contractors capture defense procurement agency contracts spanning manufacturing through depot maintenance, displacing third-party distributors in the United States and Germany. Three archetypes dominate: scale-driven mass producers, niche technical specialists, and diversified defense conglomerates. Competitive moves center on capacity expansion at certified forge facilities and strategic partnerships establishing Eastern European production nodes.
Among diversified defense conglomerates, General Dynamics Corporation and BAE Systems PLC exemplify integrated service providers capturing aftermarket revenue streams previously held by intermediaries. Rheinmetall AG occupies a position bridging European mass production with Hungarian joint venture expansion. Nammo AS represents the specialist archetype, leveraging Nordic propellant expertise outside volume competition. These anchors demonstrate how geographic origin and corporate structure shape competitive positioning within procurement systems governed by ITAR, REACH, and NATO STANAG compliance requirements.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| AMMO, Inc. |
| BAE Systems PLC |
| FN Herstal |
| Hanwha Corporation |
| Rheinmetall AG |
| Nammo AS |
| CBC Global Ammunition |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
ECHA REACH chemical restrictions gate qualified supply for European defense procurement while simultaneously creating premium-tier pricing access for certified green propellant producers. Lead-free primer mandates and nitrocellulose reformulation requirements fragment supplier eligibility, concentrating pricing power among manufacturers with pre-positioned environmental compliance infrastructure.
Pricing Analysis
Capacity additions in Hungary and Germany are reshaping price floors for artillery shell contracts across NATO procurement frameworks. Three-tier pricing structure across precision-guided, NATO STANAG-certified, and conventional unguided tiers reflects certification investment differentials. Cost compression in conventional small-caliber rounds is intensifying because framework agreements bundle logistics support into manufacturing margins. Military buyers exhibit lowest price sensitivity for smart munitions with terminal seeker integration, while law enforcement agencies face budget constraints on frangible training rounds.
Supply Chain Analysis
Regional distribution centers in Lower Saxony, Missouri, and Busan anchor hub-and-spoke patterns for classified munitions transport. Geographic supply concentration clusters in Germany, the United States, and South Korea, with forge certification limiting qualified producers. Raw material dependencies center on drawn brass feedstock, extruded propellant grain precursors, and pressed explosive fill compounds. Single-source vulnerability persists at the artillery shell forging tier, where Unterlüß and Lake City operations dominate NATO-qualified capacity. Distribution runs through defense agency direct contracts with embedded depot maintenance, displacing third-party wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ammunition Market functions as a stable compounder, with NATO STANAG interoperability mandates generating recurring standardization revenue across multi-year procurement cycles.
For Market Incumbents: Acquire certified forge capacity in Eastern European production nodes before demand surges exhaust available qualification timelines. Consolidate backward integration into polymer case material supply to offset brass feedstock volatility. Lock in multi-year framework agreements with embedded logistics support to defend against emerging Hungarian joint venture competitors. For New Entrants and Emerging Players: Begin with niche propellant specialization for Nordic environmental compliance markets, where ECHA REACH certification barriers limit incumbent response speed. Target law enforcement frangible round segments in Germany and the United States, where procurement fragmentation exceeds military concentration. Pursue direct sales channel access through specialized non-lethal formulation expertise rather than volume competition. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap precision munitions specialists because ITAR restrictions fragment cross-border development collaboration, creating captive local demand pools. Five-to-ten year viability hinges on smart munitions accuracy premium capture rather than commodity volume exposure. Monitor Hungarian joint venture announcement velocity as inflection indicator for Eastern European supply node maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion at Certified Forge Facilities | Unterlüß and Lake City expansions address NATO artillery shell replenishment bottlenecks. |
| Joint Venture Manufacturing in Hungary | Rheinmetall's Eastern European partnerships reduce supply vulnerability during operational surges. |
| Green Propellant Reformulation Investment | ECHA REACH compliance secures premium-tier access to German and Scandinavian defense procurement. |
| Integrated Logistics Support Bundling | Prime contractors capture aftermarket revenue streams previously held by third-party distributors. |
| Smart Munitions Terminal Seeker Integration | Guidance-enabled artillery rounds command accuracy premiums over saturation volume strategies. |
Methodological Framework
Multiple input streams — defense procurement officer interviews, pyrotechnic manufacturing plant assessments, and regulatory filing analysis — were reconciled against secondary validation. Primary fieldwork engaged program managers at NATO national armaments directors, ECHA chemical compliance officers, and integrated logistics support contract administrators. Secondary sources encompassed NATO STANAG specification databases, US Department of State ITAR licensing records, and EU REACH substance restriction notifications. Bottom-up segment sizing triangulated with top-down defense budget allocation analysis across the analysis window.
Historical contract award patterns were cross-referenced against expert panel input on forge capacity utilization and qualification timeline constraints. Segmentation dimensions modeled include caliber tier, application category, technology sophistication level, and distribution channel structure. CAGRs were derived from demand elasticity modeling around Eastern European replenishment cycles and Next Generation Squad Weapons program procurement schedules. Industry-specific forecast inputs incorporated ECHA chemical restriction phase-in timelines and NATO framework agreement renewal patterns.
Several conditions sit outside the modeled scope, including classified munitions programs, non-NATO allied procurement systems, and emergency surge production scenarios. Forecasts reflect documented assumptions regarding STANAG interoperability adoption rates and REACH chemical restriction enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Land-Based Remote Weapon Stations Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
US Small Caliber Ammunition Market