
 Weapons and Ammunition Market | 2026-2036
Weapons and Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Weapons and Ammunition Market Analytics
Export-credit-backed project financing is reshaping how mid-tier defense contractors secure long-dated military contracts. Rheinmetall AG leverages its state-backed KfW credit lines to anchor European NATO artillery programs. BAE Systems sustains transatlantic competitiveness through UK Export Finance guarantees on naval gun contracts. Lockheed Martin Corporation dominates US prime contracting via Pentagon milestone-payment structures that reduce customer fiscal risk.
Weapons and ammunition encompass chemically propelled kinetic systems ranging from 5.56 mm small-caliber cartridges to 155 mm artillery shells, with propellant compositions governed by NATO STANAG pressure specifications and projectile metallurgy optimized for barrel wear and terminal ballistics. Military end users command the largest procurement volumes through multi-year defense appropriations, while sports shooting applications generate stable civilian demand through repeat ammunition purchases. Online retail channels face structural friction from age-verification mandates and interstate shipping restrictions that favor licensed wholesale distributors holding Federal Firearms Licenses.
The US State Department's Directorate of Defense Trade Controls administers International Traffic in Arms Regulations, creating compliance barriers for non-US manufacturers seeking Pentagon contracts. EU REACH chemicals regulation and the F-Gas Framework constrain propellant formulation options available to European producers. Stakeholders must monitor how ITAR waiver negotiations and emerging EU Defense Procurement Directive harmonization alter cross-border supplier eligibility before committing to capacity expansion.
Market Dynamics
Defense procurement programs are consolidating around precision-guided munitions while export-credit financing reshapes contract structures for mid-tier suppliers competing against prime contractors with milestone-payment advantages.
Growth Catalysts
- NATO STANAG harmonization:Standardized pressure specifications for artillery propellants enable cross-border ammunition pooling and reduce national inventory redundancy across member arsenals.
- US Department of Defense modernization budgets:Multi-year appropriations for next-generation small arms sustain domestic manufacturing capacity and fund advanced metallurgy research for barrel longevity.
- Resilient civilian sports shooting participation:Repeat ammunition purchases through licensed wholesale distributors generate stable revenue streams independent of defense contract cycles.
Market Restraints
- ITAR compliance barriers:The US State Department's International Traffic in Arms Regulations create structural exclusion for non-US manufacturers seeking Pentagon contracts regardless of technical merit.
- EU REACH chemical constraints:European producers face restricted propellant formulation options under ECHA oversight, limiting performance optimization compared to jurisdictions with looser environmental rules.
- Licensed distributor concentration:Federal Firearms License requirements for interstate shipping entrench wholesale intermediaries, compressing margins for direct-to-user channels.
Strategic Opportunities
- Emerging EU Defense Procurement Directive harmonization:Cross-border supplier eligibility reforms could unlock integrated European artillery programs for qualified mid-tier contractors.
- Online retail age-verification technology:Biometric authentication systems may eventually satisfy regulatory mandates, enabling direct consumer channels currently blocked by verification friction.
- Dual-use metallurgy applications:Barrel wear-resistant alloys developed for military specifications transfer to civilian precision shooting equipment, opening premium product tiers.
Industry Challenges
- Skilled propellant chemist shortages:Specialized expertise in nitrocellulose stabilization and burn-rate modulation is concentrating at legacy state arsenals, constraining private R&D staffing.
- Legacy system integration complexity:Next-generation fire-control electronics must interface with decades-old NATO artillery platforms, extending certification timelines and field-testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weapons and Ammunition Market |
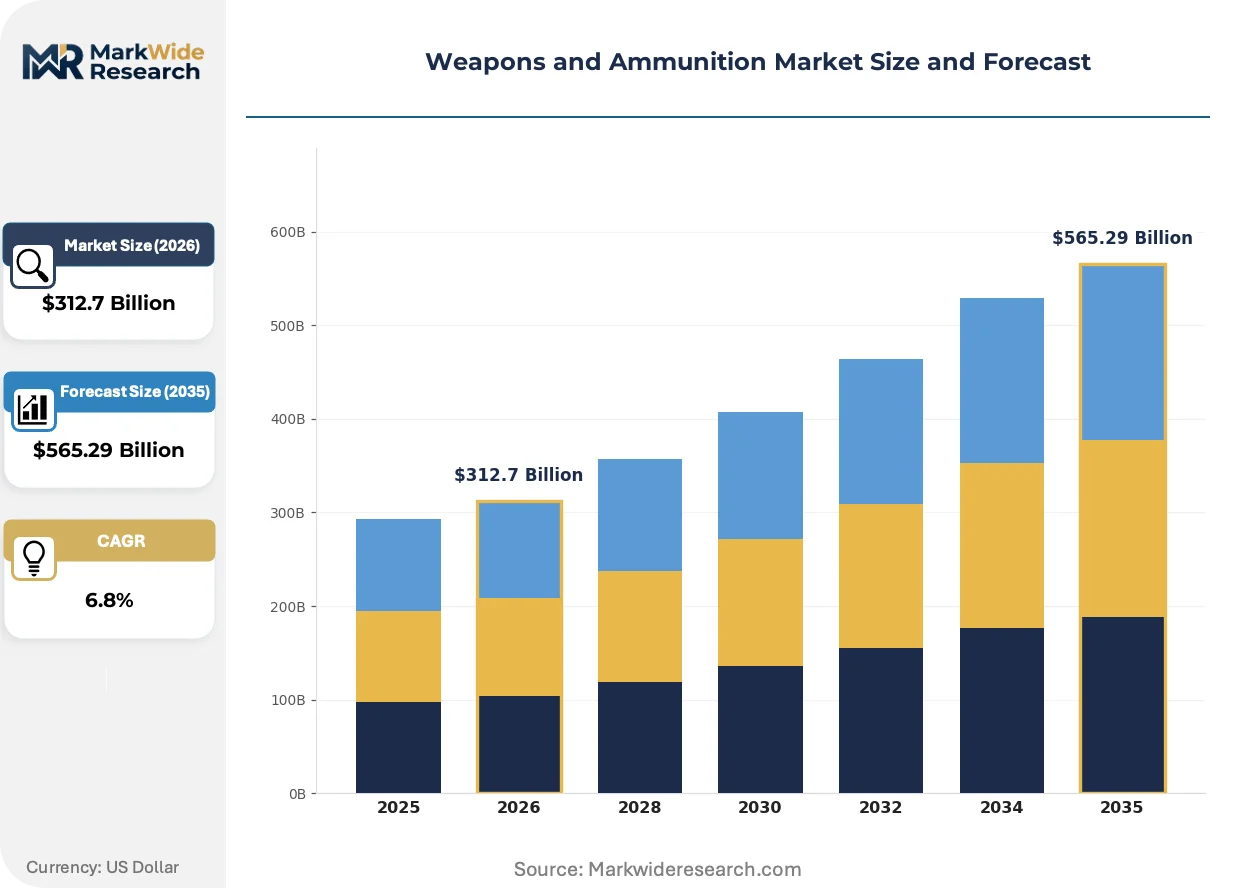
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handguns, Rifles, Shotguns, Ammunition End User: Military, Law Enforcement, Civilians, Security Personnel Application: Combat, Hunting, Sports Shooting, Self-Defense Distribution Channel: Online Retail, Sporting Goods Stores, Military Contracts, Wholesale Distributors |
| Companies Covered | Northrop Grumman Corporation, Hanwha Aerospace, Lockheed Martin Corporation, Hornady Manufacturing, CBC Global Ammunition, BAE Systems, Rheinmetall AG, Winchester Ammunition, General Dynamics Ordnance and Tactical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weapons and Ammunition Market Evolving Landscape
Digital engineering workflows are compressing prototype-to-field timelines while regulatory chemistry constraints and procurement consolidation reshape competitive positioning across defense and civilian segments.
Advanced propellant modeling software is virtualizing traditional ballistics testing. Military procurement offices in the United States and Germany now accept simulation-validated designs for artillery shell aerodynamics, cutting physical range trials by half. This compression is virtualizing the historical advantage of established arsenals with legacy test infrastructure, enabling smaller contractors to compete on computational merit rather than capital-intensive proving grounds.
The EU F-Gas Framework and REACH chemicals regulation are tightening acceptable compound lists for European manufacturers. ECHA's expanding restricted substance database forces reformulation of stabilizers and flash suppressants, raising R&D overhead for continental producers. Artillery propellant lines face the steepest compliance burden, with some legacy compositions requiring complete redesign to maintain NATO interoperability.
Buyer concentration among defense ministries is consolidating contract awards toward integrated system providers. National procurement offices increasingly demand ammunition-fire platform bundles rather than standalone munition orders, squeezing pure-play suppliers. This bundling pressure is most visible in NATO artillery programs, where Rheinmetall and BAE Systems anchor multi-year framework agreements that subordinate component vendors to subsystem roles.
Weapons and Ammunition Market Segmentation
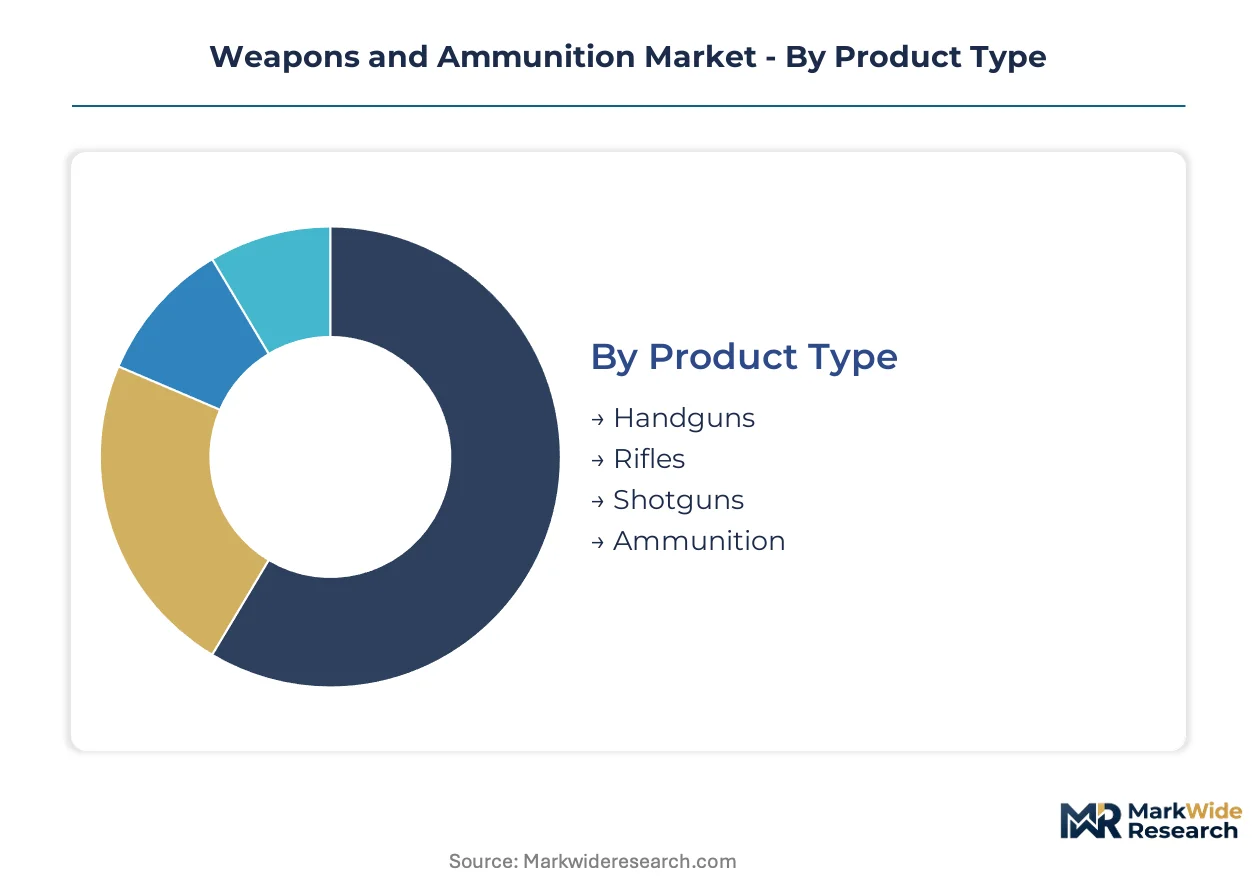
Segmentation in weapons and ammunition markets reveals how procurement authority, regulatory jurisdiction, and end-use application create distinct commercial territories. Each dimension carries unique margin profiles, compliance burdens, and customer concentration patterns that shape supplier strategy.
Product Type:
The use-case spectrum spans concealed-carry personal defense platforms through precision long-range systems to chemically propelled kinetic payloads, with each category governed by divergent technical specifications and ownership restrictions.
- Handguns:Compact chemically propelled systems chambered in 9mm Parabellum and .45 ACP dominate concealed-carry and duty applications. Civilian demand concentrates in the United States under state-level permitting regimes, constrained by National Firearms Act suppressor restrictions and magazine capacity limits in jurisdictions like California and New York.
- Rifles:Long-barrel platforms range from 5.56mm NATO carbines to .338 Lapua precision systems, with military procurement driving barrel metallurgy advances. Department of Defense next-generation squad weapon programs sustain domestic manufacturing capacity while export controls under ITAR limit non-US contractor participation.
- Shotguns:Smoothbore 12-gauge platforms serve dual hunting and tactical breaching roles with lower regulatory scrutiny than rifled systems. Repeat purchases of shotshell ammunition generate stable aftermarket revenue through licensed wholesale channels.
- Ammunition:Chemically propelled cartridges from .22 rimfire to 155mm artillery shells constitute consumable demand independent of platform replacement cycles. NATO STANAG pressure specifications enable cross-border military pooling while REACH compliance raises European production costs.
Established volume favors ammunition; emerging adoption favors precision rifle platforms.
End User:
Customer-type concentration determines contract structure, with defense appropriations offering multi-year visibility against civilian retail fragmentation.
- Military:National defense ministries command largest procurement volumes through multi-year appropriations for precision-guided munitions and next-generation small arms. Pentagon milestone-payment structures reduce fiscal risk for prime contractors while ITAR barriers exclude foreign suppliers from US contracts regardless of technical merit.
- Law Enforcement:Federal, state, and municipal agencies procure duty weapons and training ammunition through competitive bidding frameworks. Department of Homeland Security grants channel funding toward local police department modernization.
- Civilians:Sports shooting participants generate repeat ammunition purchases through Federal Firearms License holders, with online retail blocked by interstate shipping restrictions. Resilient participation in competitive disciplines sustains demand independent of defense cycles.
- Security Personnel:Private military contractors and corporate security details procure commercial variants of military-specification platforms. Demand fluctuates with geopolitical contracting cycles in conflict zones.
Procurement concentration favors military; margin stability favors civilian sports shooting.
Application:
Functional purpose dictates performance requirements from terminal ballistics through reliability standards to environmental operating ranges.
- Combat:Military end users demand reliability across temperature extremes and contamination exposure, with NATO STANAG interoperability requirements. Artillery propellant lines face steepest EU F-Gas Framework compliance burdens.
- Hunting:Seasonal demand patterns concentrate in North American and European autumn procurement windows. Lead-core projectile restrictions in California and EU jurisdictions drive copper-alloy alternative development.
- Sports Shooting:Olympic and competitive disciplines specify standardized ammunition dimensions and propellant formulations. ISSF regulations govern international competition equipment eligibility.
- Self-Defense:Concealed-carry expansion in US constitutional-carry states drives compact handgun demand. Hollow-point projectile selection prioritizes terminal performance over penetration depth.
Technology transfer favors combat-to-sports crossover; regulatory exposure favors self-defense.
Distribution Channel:
Channel structure reflects regulatory friction, with licensed intermediaries entrenched where age verification and background checks apply.
- Online Retail:Direct-to-consumer channels face structural barriers from age-verification mandates and interstate shipping restrictions. Biometric authentication technology may eventually satisfy regulatory requirements.
- Sporting Goods Stores:Brick-and-mortar retailers hold Federal Firearms Licenses enabling immediate background check processing. Staff expertise drives premium product attachment rates.
- Military Contracts:Defense procurement offices bundle ammunition with fire platforms, squeezing pure-play suppliers into subsystem roles. Export-credit financing reshapes contract structures for mid-tier competitors.
- Wholesale Distributors:Licensed intermediaries dominate civilian ammunition flow, compressing margins for manufacturers. Concentration among regional distributors creates bottleneck leverage.
Margin capture favors military contracts; volume accessibility favors wholesale distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-credit financing and defense procurement centralization are redrawing competitive maps across national arsenals. The United States anchors prime-contractor concentration through Pentagon milestone-payment structures, while European producers navigate REACH chemical constraints and emerging EU Defense Procurement Directive reforms.
United States
Department of Defense modernization budgets sustain domestic manufacturing capacity for next-generation small arms and precision-guided munitions. The State Department's ITAR regulations structurally exclude foreign suppliers from Pentagon contracts regardless of technical merit. Lake City Army Ammunition Plant in Missouri and Scranton Army Ammunition Plant in Pennsylvania represent the largest government-owned, contractor-operated propellant and metal-forming facilities in the Western Hemisphere.
Germany
Rheinmetall AG leverages KfW state-backed credit lines to anchor European NATO artillery programs and expand artillery shell production capacity. The EU F-Gas Framework and REACH chemicals regulation constrain propellant formulation options available to German producers, forcing reformulation of stabilizers and flash suppressants. The Rhineland-Palatinate cluster around Unterlüß houses Rheinmetall's primary artillery systems integration facility.
United Kingdom
BAE Systems sustains transatlantic competitiveness through UK Export Finance guarantees on naval gun contracts and munitions supply agreements. The UK Firearms Act and Policing and Crime Act 2017 impose strict civilian ownership licensing that channels commercial demand toward licensed wholesale distributors. The Lancashire manufacturing corridor around Radway Green maintains legacy propellant blending and small-arms ammunition production lines.
South Korea
Hanwha Aerospace scales artillery and ammunition output through domestic defense procurement and Middle Eastern export contracts. The country's Defense Acquisition Program Administration coordinates multi-year munitions stockpiling initiatives aligned with US-Korea alliance commitments. The Changwon industrial complex in South Gyeongsang Province concentrates precision forging and propellant manufacturing for 155mm artillery systems.
Israel
Domestic producers supply precision munitions and small-caliber systems optimized for desert operating conditions and urban combat scenarios. The Ministry of Defense's Directorate of Defense Research and Development funds indigenous fire-control integration and terminal ballistics research. The Negev Desert testing ranges near Ramat Negev enable year-round thermal and contamination exposure trials unmatched by European facilities.
Weapons and Ammunition Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent contract structures. Prime contractors with milestone-payment advantages dominate multi-year defense appropriations, while mid-tier suppliers rely on export-credit financing to anchor European NATO programs. Three archetypes define the field: integrated system providers bundling ammunition with fire platforms, pure-play munition specialists serving wholesale distributor networks, and state-backed champions leveraging sovereign credit guarantees. Competitive moves concentrate on capacity expansion for artillery propellant lines and strategic partnerships to access ITAR-waivered Pentagon contracts.
Among US-based prime contractors, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions within the integrated system-provider tier, anchoring Pentagon procurement through milestone-payment structures that reduce customer fiscal risk. Rheinmetall AG represents the state-backed European archetype, leveraging German export-credit facilities to compete for NATO artillery framework agreements against transatlantic rivals.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Hanwha Aerospace |
| Lockheed Martin Corporation |
| Hornady Manufacturing |
| CBC Global Ammunition |
| BAE Systems |
| Rheinmetall AG |
| Winchester Ammunition |
| General Dynamics Ordnance and Tactical Systems |
| Others |
Value Network & Pricing Analysis
Lake City Army Ammunition Plant and Scranton Army Ammunition Plant concentrate government-owned propellant and metal-forming capacity in the United States, anchoring margin capture downstream at prime contractors with Pentagon milestone-payment structures while compressing pure-play suppliers into wholesale distributor tiers.
Pricing Analysis
NATO STANAG certification grade creates the primary spread between military-specification and commercial-grade ammunition, with Department of Defense contract pricing commanding premiums over civilian retail channels. Three-tier pricing structure across precision-guided, standard-issue, and training-grade munitions segments military procurement, while civilian ammunition pricing stratifies across premium match-grade, standard full-metal-jacket, and economy bulk offerings. Cost compression in commercial rimfire and shotshell lines is intensifying because wholesale distributor concentration squeezes manufacturer margins. Law enforcement agencies exhibit lowest price sensitivity due to federal grant funding, whereas civilian competitive shooters show highest sensitivity to per-round cost differentials.
Supply Chain Analysis
ITAR export controls and EU REACH chemical restrictions limit cross-border flows of propellant formulations and precision components, fragmenting global supply into jurisdictional silos. Geographic concentration centers on the United States, Germany, and South Korea for artillery systems and small-caliber production, with raw material dependencies spanning nitrocellulose from cotton linter suppliers, tungsten for penetrator cores, and copper for jacketed projectiles. Single-source vulnerability runs through aged state-owned arsenals in NATO member states, where skilled propellant chemist shortages constrain capacity expansion. Distribution runs through licensed Federal Firearms License holders for civilian channels, while military procurement flows through defense ministry contracting offices with multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense modernization cycles and replenishment of depleted Western stockpiles position this market for cyclical recovery, with Pentagon multi-year appropriations and NATO artillery pooling initiatives providing demand visibility across the procurement horizon.
For Market Incumbents: Insulate prime-contractor positioning by deepening backward integration into propellant chemistry and precision forging capacity, while securing ITAR waiver eligibility to access Pentagon milestone-payment structures. Threats from state-backed European champions leveraging export-credit financing require countermeasures through domestic capacity expansion at government-owned, contractor-operated facilities.
For New Entrants and Emerging Players: Pursue white-space opportunities in biometric age-verification technology for direct-to-consumer ammunition channels currently blocked by regulatory friction, and target private military contractor demand for commercial-variants of military-specification platforms. The security personnel segment offers most penetrable entry path given fluctuating geopolitical contracting cycles and lower certification barriers than defense ministry procurement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier European ammunition specialists carrying legacy propellant blending expertise but constrained by REACH compliance costs. Long-term viability hinges on exposure to NATO artillery modernization and dual-use metallurgy applications transferring military barrel alloys to civilian precision equipment. Watch for EU Defense Procurement Directive harmonization progress as inflection signal unlocking cross-border supplier eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Artillery Propellant Capacity Expansion | Rheinmetall's KfW-backed scaling addresses NATO shell shortages from Ukraine conflict drawdowns. |
| ITAR Waiver Qualification | Non-US manufacturers unlock Pentagon milestone-payment access through State Department compliance pathways. |
| Dual-Use Metallurgy Transfer | Barrel wear-resistant alloys from military specifications open premium civilian precision shooting tiers. |
| Biometric Age-Verification Development | Technology satisfying interstate shipping mandates enables direct consumer ammunition channels. |
| Export-Credit Financing Structuring | UK Export Finance and KfW guarantees anchor European NATO artillery program competitiveness. |
Research Methodology
A spread of perspectives from defense procurement officers at NATO member ministries, propellant chemists at legacy state arsenals, Federal Firearms License wholesale distributors, and export-credit agency underwriters converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through Pentagon budget justification materials, EU Defense Procurement Directive legislative tracking, ECHA restricted substance database monitoring, and customs trade data on ammunition flows. Bottom-up triangulation across product-type demand curves and top-down reconciliation against defense appropriation totals ensured methodological consistency.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, end user, application, and distribution channel, with additional granularity on NATO STANAG compliance tiers. CAGRs were derived from regression analysis of historical procurement cycles and projected modernization timelines, incorporating inputs from Department of Defense next-generation squad weapon program schedules and EU artillery pooling initiative commitments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed champions or sudden ITAR regulatory liberalization would shift outcomes beyond modeled ranges. Material shifts in Pentagon appropriation priorities, REACH chemical restriction scope, or NATO STANAG specification revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Directed Energy Weapons Market