
 Mexico Automotive Camera Market | 2026-2036
Mexico Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Camera Market Foresight
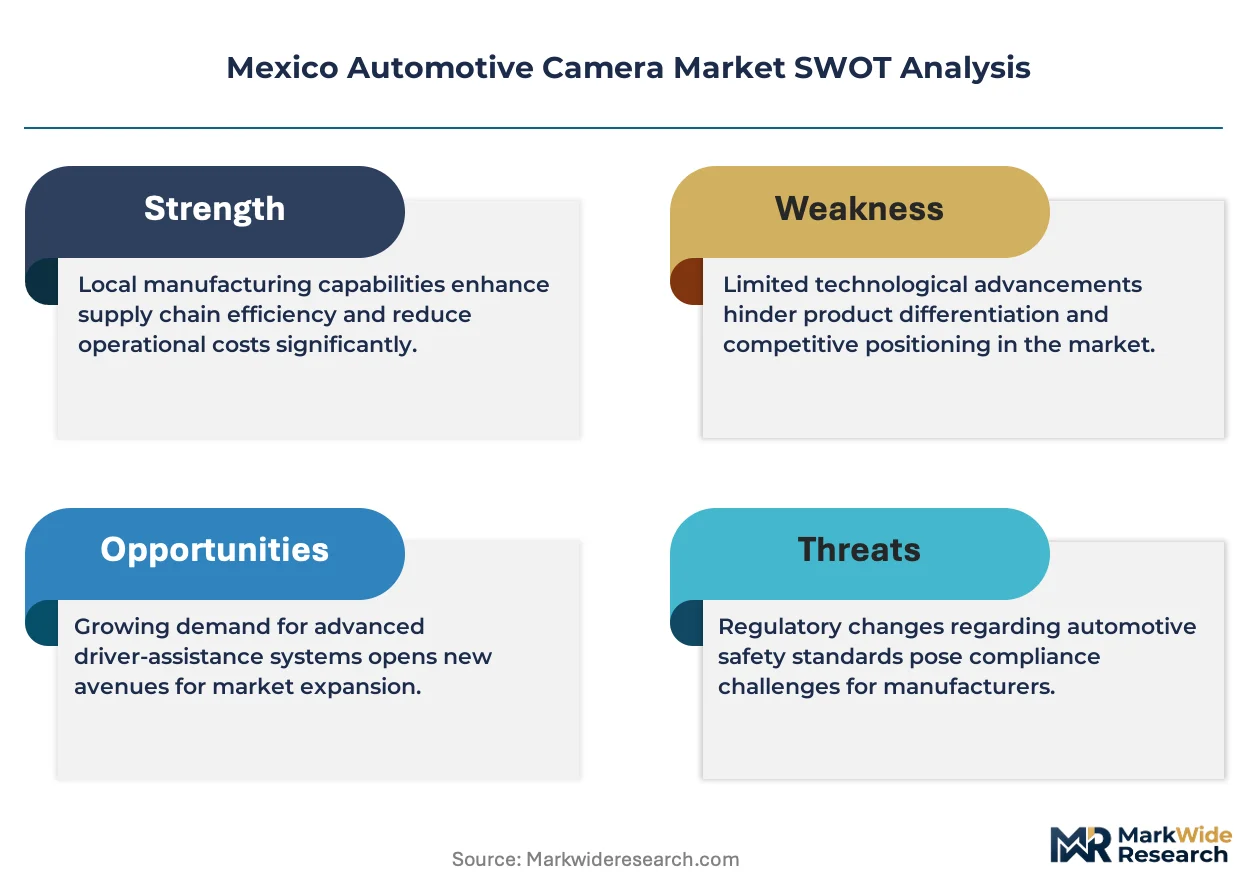
Mexico is reshaping North American automotive camera supply chains through accelerated OEM capacity expansion near the US border. Robert Bosch GmbH leverages its Guadalajara engineering base to sustain embedded vision software development for regional automakers. Continental AG anchors major production lines in Querétaro, competing on manufacturing scale for surround-view modules supplied to vehicle assemblers.
An automotive camera integrates image sensors, optical lenses, and signal-processing chipsets to capture real-time visual data for driver assistance, parking guidance, and autonomous navigation systems; CMOS sensor variants dominate current architectures due to lower power draw and superior low-light performance versus legacy CCD alternatives. Rearview camera installations represent the most mature application segment across passenger vehicles, while surround-view configurations command premium positioning among electric vehicle platforms where 360-degree perception is standard. Infrared camera adoption remains nascent but specializes in night-vision enhancement for heavy-duty commercial fleets operating across Mexican federal highways.
NOM-194-SCFI-2015 mandates from Mexico's Secretariat of Economy shape rear-visibility system requirements, while US NHTSA FMVSS 111 regulations bind cross-border OEM exports to calibrated display standards. Stakeholders must monitor how evolving SAE automation levels redefine camera resolution thresholds and cybersecurity protocols for connected vehicle architectures.
Market Dynamics
OEM production expansion along the US-Mexico border is tightening camera supply chains as automakers demand localized sourcing for advanced driver-assistance modules. Tier-1 suppliers are consolidating engineering and manufacturing footprints to match this geographic pull.
Growth Catalysts
- NOM-194-SCFI-2015:Mexico's rear-visibility mandate for passenger vehicles and light trucks creates baseline demand for backup camera installations across all new vehicle platforms.
- CMOS sensor migration:The shift from legacy CCD architectures to CMOS variants reduces power consumption and enables higher-resolution imaging for surround-view systems.
- Baja California cluster:Concentrated electronics manufacturing in Tijuana and Mexicali provides ready access to optical component suppliers and semiconductor packaging facilities.
Market Restraints
- Semiconductor input volatility:Image sensor and signal-processing chipsets face price instability tied to foundry capacity constraints in Asian manufacturing hubs.
- Single-source supply risk:Advanced lens assemblies for automotive-grade cameras concentrate among a limited set of Japanese and German optical specialists.
- Resolution ceiling limitations:Current thermal management constraints in compact camera housings restrict sustained 8K imaging for surround-view applications.
Strategic Opportunities
- Querétaro industrial corridor:Underdeveloped camera module assembly capacity in central Mexico offers greenfield expansion potential for Tier-1 suppliers serving domestic OEMs.
- Infrared night-vision integration:Commercial freight operators across Mexican federal highways represent an emerging application segment for thermal imaging systems.
- PROSEC tariff program:Mexico's sectoral promotion regime reduces duty burdens on imported optical components, improving cost structures for regional camera production.
Industry Challenges
- Embedded vision software talent scarcity:Shortages of engineers proficient in real-time image processing and neural network optimization constrain local R&D scaling.
- SAE Level 3 validation timelines:Extended certification cycles for higher-automation camera systems delay revenue recognition on next-generation platforms.
- Legacy vehicle integration complexity:Retrofit camera installations in older fleets require custom mounting solutions and electrical system adaptations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Camera Market |
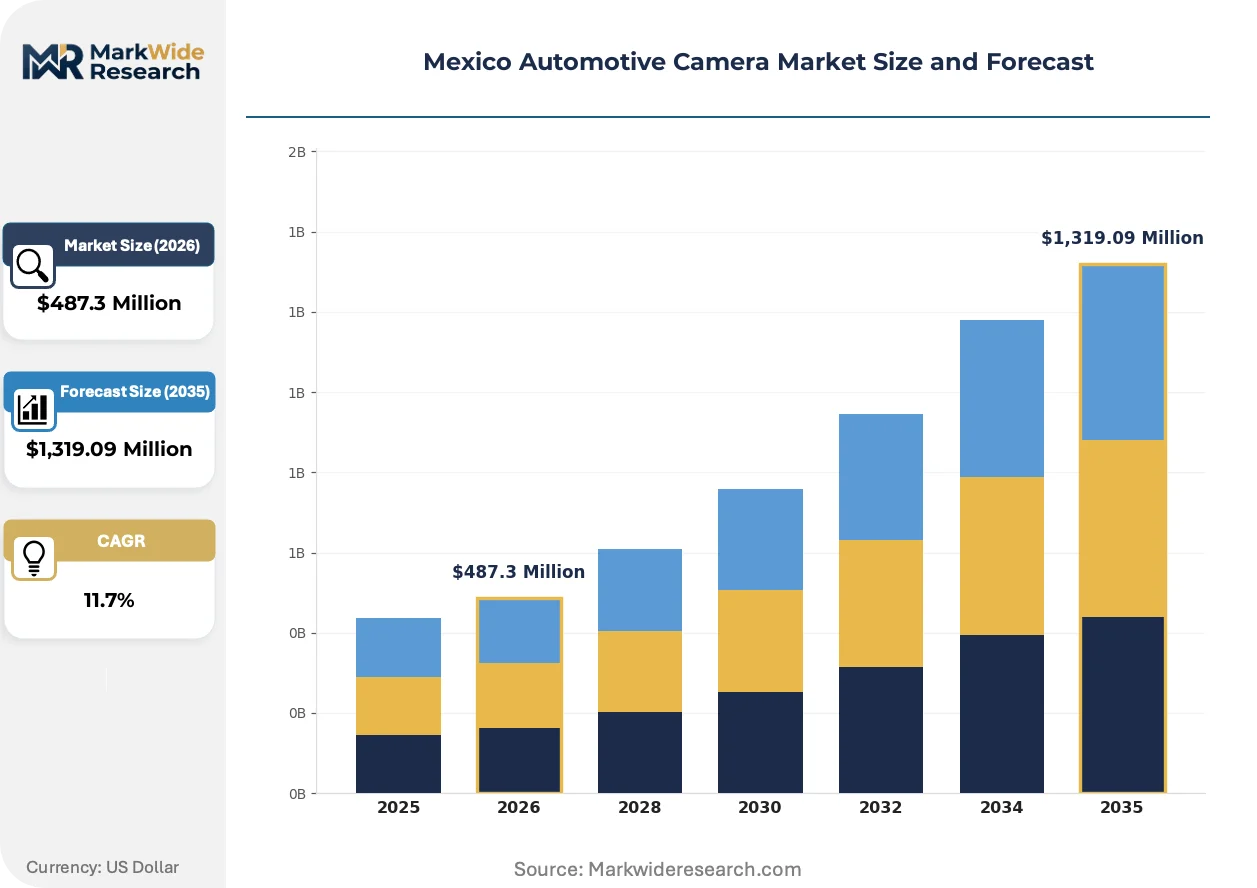
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surround View Cameras, Rearview Cameras, Front Cameras, Blind Spot Cameras Technology: Analog Cameras, Digital Cameras, Infrared Cameras, CMOS Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Heavy-Duty Vehicles |
| Companies Covered | Magna International Inc, Valeo SA, Robert Bosch GmbH, ZF Friedrichshafen AG, Garmin Ltd, Continental AG, Denso Corporation, Hella KGaA Hueck & Co, Panasonic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Camera Market Shifts & Advancements
Automotive camera architectures are converging with edge computing and artificial intelligence to enable real-time decision-making without cloud dependency. This shift is compressing hardware development cycles and redefining supplier value chains.
Deep-learning-based image signal processors are digitizing raw sensor data into structured environmental maps for path planning. Electric vehicle manufacturers in Mexico City and Guadalajara are adopting these chipsets at accelerated procurement cadences compared to internal combustion platforms. The technology is digitizing how Tier-1 suppliers partition hardware and software responsibilities in camera module contracts.
NOM-194-SCFI-2015 compliance deadlines are hardening technical specifications for rearview camera latency and field-of-view coverage. Mexican vehicle assemblers must demonstrate consistent performance across temperature and vibration ranges specified by the Secretariat of Economy. Passenger vehicle segments face the steepest certification burdens, driving consolidation among suppliers capable of delivering validated system packages.
Fleet operators are unbundling camera hardware from integrated telematics service contracts, preferring component procurement with separate software subscriptions. Commercial vehicle leasing companies in Monterrey and Puebla are piloting this split-ownership model for heavy-duty trucks. This pattern is most visible in long-haul freight corridors where operators prioritize capital expenditure flexibility over bundled system pricing.
Mexico Automotive Camera Market Segmentation
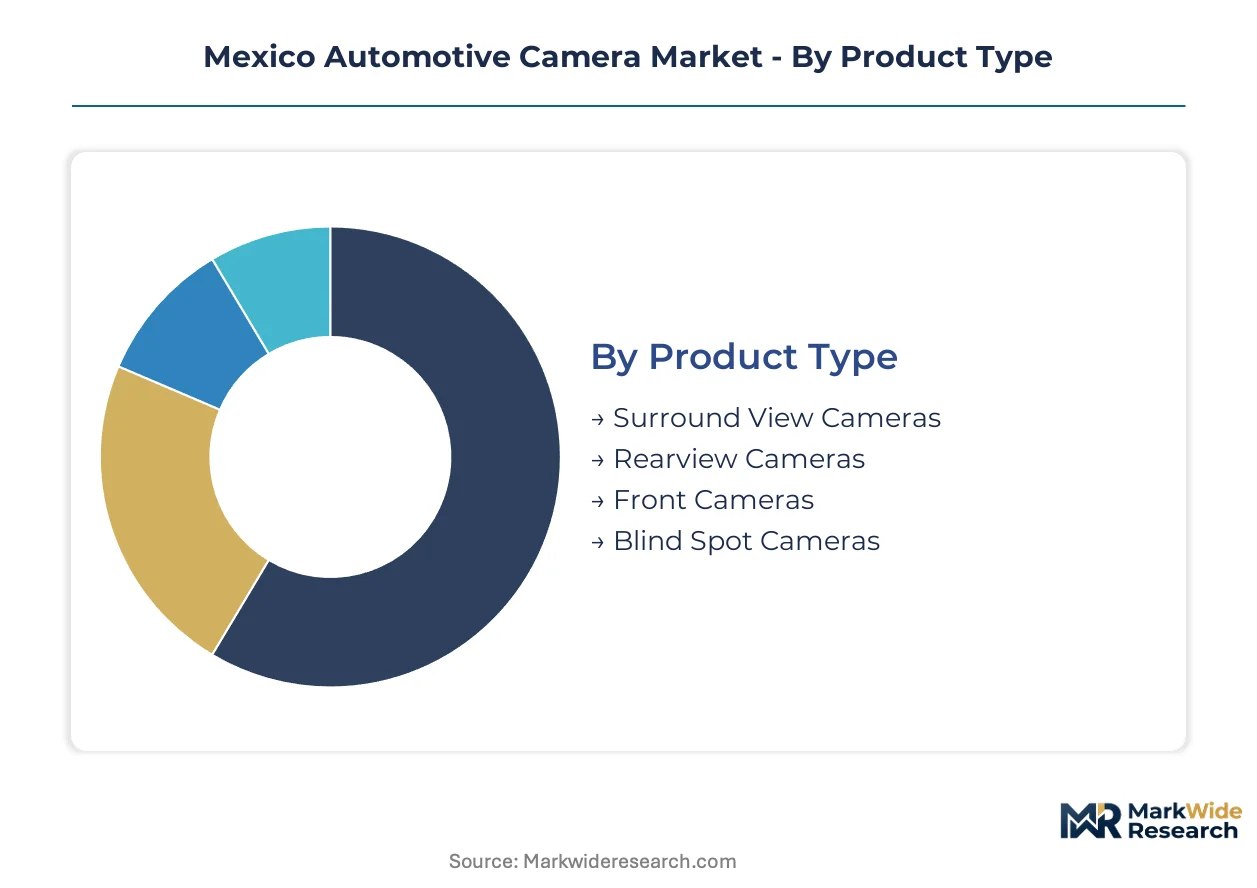
Mexico's automotive camera market fragments across hardware specifications, integration channels, and vehicle architectures. Each segment carries distinct margin profiles and service lifecycle requirements that reshape supplier priorities.
Product Type:
After-sales service intensity varies sharply across camera form factors, with surround-view systems demanding recalibration protocols that aftermarket workshops struggle to replicate.
- Surround View Cameras:Multi-lens arrays stitch four to six video feeds into a composite 360-degree vehicle perimeter view. Demand concentrates in Guadalajara-area luxury EV assembly plants where automated parking systems are standard equipment.
- Rearview Cameras:Single-lens units mounted above license plates provide reverse-trajectory guidance. NOM-194-SCFI-2015 mandates have saturated passenger vehicle installations, shifting volume toward commercial fleet retrofits in Monterrey logistics corridors.
- Front Cameras:Forward-facing modules enable lane-keeping and collision-avoidance functions. Highway safety regulations in Baja California trucking routes are accelerating procurement.
- Blind Spot Cameras:Side-mounted units eliminate mirror-angle limitations for lane-change maneuvers. Urban delivery operators in Mexico City prioritize these for dense traffic navigation.
Rearview cameras hold the largest share; momentum sits with surround-view configurations.
Technology:
Component cost tiers separate legacy analog architectures from semiconductor-intensive digital platforms, with margin compression most severe in mature sensor categories.
- Analog Cameras:Legacy NTSC/PAL signal transmission dominates heavy-duty vehicle retrofit markets where electrical system compatibility outweighs resolution demands.
- Digital Cameras:LVDS and Ethernet-based data transmission enable megapixel imaging for ADAS fusion. Querétaro OEM assembly lines specify these for new platform launches.
- Infrared Cameras:Thermal imaging arrays detect pedestrian heat signatures beyond headlight range. Freight operators across federal highway corridors are piloting night-vision integration.
- CMOS Sensors:Complementary metal-oxide-semiconductor architectures deliver low-power, high-dynamic-range imaging that has displaced CCD alternatives. Tijuana electronics clusters provide localized die packaging capacity.
CMOS sensors hold the largest share; infrared variants are climbing the fastest.
End User:
Customer type determines contract structure, with vehicle assemblers demanding system-level liability warranties that component suppliers resist underwriting.
- OEMs:Original equipment manufacturers specify camera modules as part of integrated ADAS packages. Volkswagen de México and Nissan Mexicana source through centralized procurement in Puebla and Aguascalientes.
- Tier-1 Suppliers:Delphi Technologies and Aptiv integrate cameras into larger sensor fusion assemblies. These firms dominate surround-view system contracts for premium platforms.
- Aftermarket Providers:Independent installers serve fleet retrofit demand and collision replacement. Price competition is intense in border zone retail corridors.
- Vehicle Assemblers:Contract manufacturers without captive engineering source complete camera systems from integrated suppliers. This channel is expanding in emerging EV startup partnerships.
Tier-1 suppliers hold the largest share; aftermarket providers are gaining share fastest.
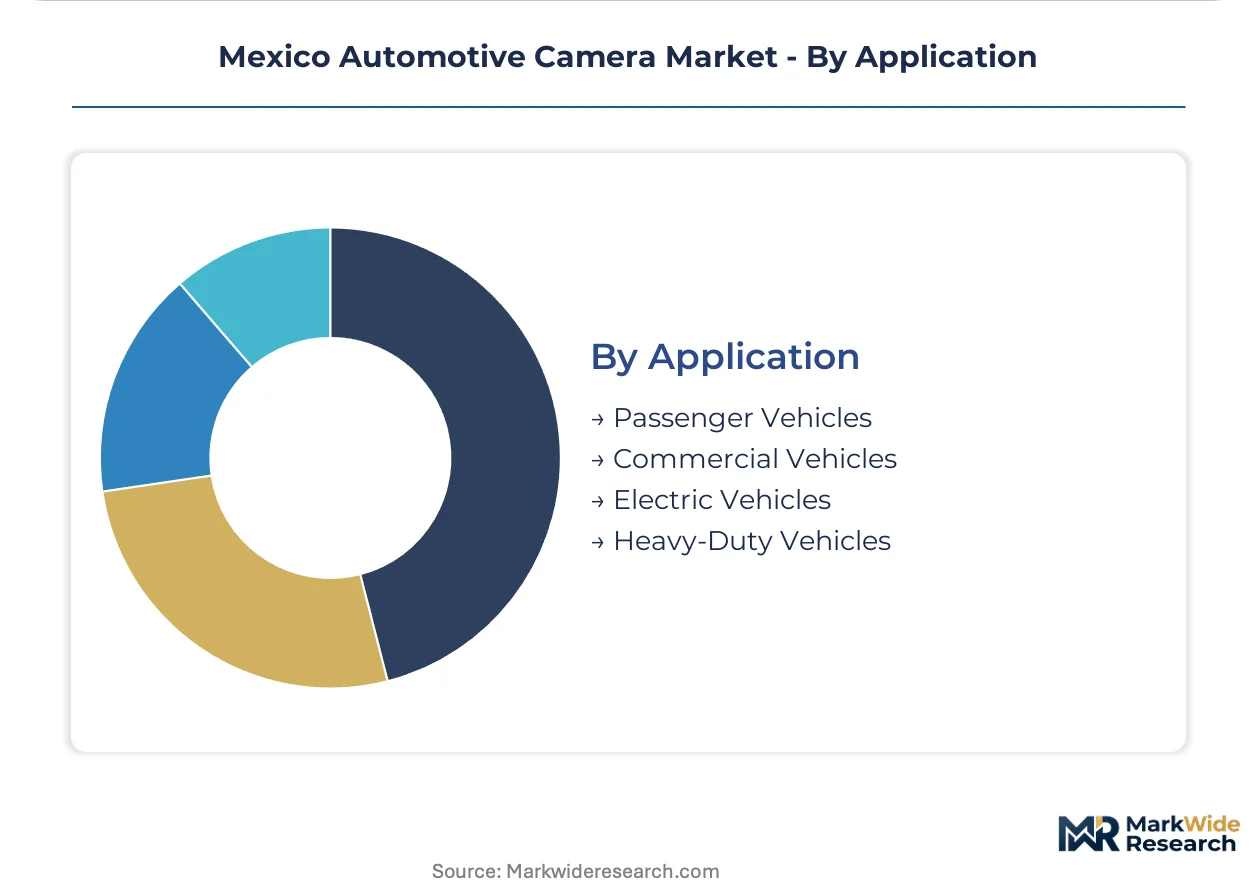
Application:
Vehicle category dictates environmental sealing specifications, with heavy-duty platforms requiring vibration resistance that passenger car modules cannot satisfy.
- Passenger Vehicles:Sedans and light SUVs represent the volume base for rearview and front-camera installations. NOM-194-SCFI-2015 compliance has standardized feature inclusion across price tiers.
- Commercial Vehicles:Light trucks and vans deploy blind-spot and backup cameras for urban delivery safety. Mexico City metropolitan freight regulations are tightening installation requirements.
- Electric Vehicles:Battery-electric platforms specify surround-view systems as standard equipment for autonomous parking functions. Guadalajara-area EV manufacturing is accelerating module demand.
- Heavy-Duty Vehicles:Long-haul trucks and construction equipment require ruggedized housings and extended temperature ranges. Federal highway night-operation rules are stimulating infrared adoption.
Passenger vehicles hold the largest share; electric vehicles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NOM-194-SCFI-2015 from Mexico's Secretariat of Economy anchors regulatory demand across North American automotive production corridors. The standard mandates rear-visibility systems for all passenger vehicles and light trucks, creating baseline procurement volumes that cascade through cross-border supply chains.
Mexico City Metro
Electric vehicle startups and established assemblers concentrate camera module procurement for automated parking systems. The metropolitan area's congestion pricing programs and emissions regulations accelerate ADAS penetration in urban delivery fleets. Santa Fe and Tlalnepantla industrial zones host Tier-1 engineering offices serving domestic OEMs.
Nuevo León
Monterrey anchors heavy-duty vehicle camera demand through long-haul freight operators piloting infrared night-vision systems. State-level commercial vehicle safety mandates exceed federal minimums for blind-spot monitoring on federal highways. Apodaca manufacturing parks attract lens assembly investments from optical component specialists.
Jalisco
Guadalajara's electronics manufacturing base sustains embedded vision software development for regional automakers. The state's PROSEC tariff incentives reduce duty burdens on imported semiconductor packaging equipment. El Salto industrial corridor concentrates CMOS sensor die bonding capacity for camera module production.
Bajío Region
Querétaro and Guanajuato vehicle assembly plants specify surround-view camera systems for premium platform launches. Automotive clusters in Irapuato and Silao lack localized camera module assembly, creating greenfield expansion opportunities for Tier-1 suppliers. State economic development agencies target optical component investments through specialized industrial parks.
Northern Border States
Baja California's Tijuana and Mexicali electronics clusters provide semiconductor packaging and optical component proximity for US-bound camera exports. Sonora and Chihuahua assembly plants face US NHTSA FMVSS 111 compliance requirements for cross-border vehicle shipments. Maquiladora operations leverage IMMEX program benefits for duty-efficient component importation.
Mexico Automotive Camera Market Competitive Landscape
Integrated system suppliers and specialized component fabricators split the market through divergent capability investments. The vendor base concentrates among Tier-1 automotive suppliers with captive electronics manufacturing and software development. Three archetypes dominate: full-stack ADAS integrators, optical component specialists, and regional contract manufacturers. Consolidation pressures favor M&A activity among mid-scale module assemblers, while technology licensing agreements proliferate between sensor designers and lens specialists.
Among Germany-based suppliers, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify full-stack integration archetypes with embedded vision competencies. Continental AG occupies a position bridging European engineering depth and regional manufacturing scale. Japanese fabricators Denso Corporation and Panasonic Corporation anchor the precision optics tier, while Magna International Inc represents North American contract manufacturing scale. Garmin Ltd exemplifies the navigation-technology crossover segment.
| Leading Market Players |
|---|
| Magna International Inc |
| Valeo SA |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Garmin Ltd |
| Continental AG |
| Denso Corporation |
| Hella KGaA Hueck & Co |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in Baja California CMOS sensor packaging facilities is driving supplier selectivity and compressing margins for camera module assemblers competing for Tier-1 contracts. Mexican OEM procurement teams face extended lead times that translate into pricing premiums for validated supply relationships.
Pricing Analysis
Price spreads between Tijuana-sourced CMOS modules and Querétaro-assembled finished cameras reflect logistics costs and PROSEC tariff optimization differentials. Three-tier pricing structure across premium surround-view, standard front-camera, and economy rearview levels stratifies by resolution grade and NOM-194-SCFI-2015 certification burden. Pricing pressure stems from semiconductor input volatility as foundry capacity constraints in Asian hubs transmit downstream. Aftermarket retrofit providers exhibit highest price sensitivity; OEM direct contracts show lowest.
Supply Chain Analysis
Export-control restrictions on advanced image signal processors limit technology flows from US and Japanese semiconductor designers to Mexican assembly operations. Camera module production draws from Taiwan for CMOS die fabrication, Germany for precision lens grinding, and South Korea for advanced packaging substrates. Supply chain risk centers on single-source vulnerability for automotive-grade glass lenses concentrated among Japanese and German optical specialists. Distribution runs through Tier-1 system integrators consolidating component procurement for OEM platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera module calibration and over-the-air software update subscriptions are expanding faster than hardware shipments as fleet operators unbundle service layers from initial procurement.
For Market Incumbents: Harden software-defined camera architectures against margin erosion from commoditized lens assembly competition. Consolidate embedded vision engineering talent in Guadalajara to defend against Tier-1 suppliers backward integrating into algorithm development. Prioritize NOM-194-SCFI-2015 certification depth as a channel control lever. For New Entrants and Emerging Players: Querétaro industrial corridor greenfield assembly capacity represents the most penetrable entry point for domestic OEM surround-view contracts underserved by incumbent footprint. Infrared night-vision retrofits for Monterrey long-haul freight operators offer specialized application white space. Pursue component-supplier partnerships with Baja California electronics clusters as go-to-market foundation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across CMOS sensor packaging as die-shrink roadmaps demand specialized cleanroom investment. Mid-scale module assemblers with validated OEM relationships and software development capabilities present acquisition targets with defensible positioning. Monitor PROSEC tariff program modifications as inflection signal for regional cost-structure competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces SKU complexity for OEMs sourcing across Puebla and Aguascalientes assembly plants. |
| Software-Defined Vehicle Investment | Enables over-the-air camera recalibration for NOM-194-SCFI-2015 compliance maintenance. |
| Geographic Manufacturing Footprint | Querétaro expansion addresses surround-view module supply gap for Bajío region OEMs. |
| Battery Supply Agreement | Guadalajara EV startups demand integrated ADAS-camera procurement with cell supply contracts. |
| Charging Infrastructure Partnership | Fleet camera-telematics bundling aligns with commercial vehicle electrification corridor planning. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement patterns anchors the qualitative findings. Primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations specialists combined with vehicle production databases, IHS Markit registration data, customs/trade records, and NOM-194-SCFI-2015 compliance filings. Bottom-up module shipment estimates and top-down OEM ADAS content analysis provide triangulation.
Calibration against historical CMOS sensor pricing cycles and foundry capacity utilization informs the projection framework. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from fitted growth curves across the analysis window. Forecast inputs include NOM-194-SCFI-2015 mandate phase-in schedules and PROSEC tariff regime stability assumptions.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates and Mexican industrial electricity pricing would shift the trajectory. Forecasts reflect documented assumptions on semiconductor supply normalization and regulatory enforcement consistency. Material shifts in US NHTSA FMVSS 111 cross-border compliance requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
India Automotive Lighting Market