
 India ECU Market | 2026-2036
India ECU Market Size, Share, and Industry Trends Forecast 2026-2036
India ECU Market Outlook
Multi-source procurement for microcontroller cores and sensor interfaces is realigning how domestic Tier-1 suppliers structure their vendor ecosystems. Bosch India leverages captive semiconductor partnerships to sustain powertrain ECU dominance across Maruti Suzuki and Hyundai Motor India supply chains. Continental AG anchors its position through chassis control modules for premium SUV platforms assembled in Gujarat and Maharashtra. Argus Embedded Systems Pvt. Ltd. competes on cost-optimized body control designs for two-wheeler and three-wheeler OEMs.
An electronic control unit integrates microprocessors, memory arrays, power conditioning circuits, and real-time operating firmware to execute closed-loop commands within vehicle subsystems. The device processes analog sensor inputs at sub-millisecond latency to modulate fuel injection, antilock braking, or infotainment responses. Engine management applications command the largest installed base, though telematics modules represent the fastest expansion trajectory under AIS-140 compliance deadlines. Microcontroller-based architectures retain volume leadership, while FPGA configurations penetrate safety-critical domains where deterministic parallel processing outperforms sequential code execution.
BIS certification requirements for electromagnetic compatibility and thermal cycling reliability shape product qualification timelines for ECU manufacturers serving Indian OEMs. The PLI scheme for automotive and auto components incentivizes domestic capital expenditure on SMT lines and cleanroom assembly capacity. CDSCO oversight applies where ECUs incorporate diagnostic data handling subject to future health-monitoring integrations. Stakeholders must track how OBD-II mandate expansions and proposed Bharat Stage VII emissions standards recalibrate firmware development roadmaps and validation budgets.
Market Dynamics
AIS-140 mandate enforcement is compressing ECU deployment timelines across Indian commercial vehicle and passenger car platforms, forcing Tier-1 suppliers to requalify telematics architectures ahead of statutory deadlines.
Growth Catalysts
- PLI scheme incentives:Automotive component manufacturers expanding SMT and cleanroom capacity in Tamil Nadu and Gujarat receive production-linked subsidies that accelerate domestic ECU assembly scale-up.
- Bharat Stage VII preparation:Emissions control firmware complexity for engine management units is pulling advanced microcontroller architectures into mid-segment powertrain applications earlier than replacement cycles would predict.
- Two-wheeler electrification:Battery management system integration into electric scooters and motorcycles is creating fresh demand for cost-optimized control modules in Pune and Chennai manufacturing clusters.
Market Restraints
- Semiconductor input volatility:Microcontroller and power MOSFET supply from East Asian foundries exposes domestic ECU assemblers to lead-time swings that distort production scheduling.
- BIS certification friction:Electromagnetic compatibility and thermal cycling test protocols extend product qualification timelines by quarters, freezing design iterations for smaller Tier-2 suppliers.
- FPGA cost premium:Deterministic parallel processing architectures for safety-critical chassis domains remain priced beyond mass-market passenger vehicle budgets, constraining penetration.
Strategic Opportunities
- Karnataka-Telangana corridor:Emerging electric vehicle and battery OEM concentration around Bengaluru and Hyderabad offers captive ECU supply contracts for power electronics specialists.
- OBD-II mandate expansion:Proposed diagnostic data standardization for commercial fleets creates firmware service revenue streams beyond hardware shipment economics.
- Health-monitoring convergence:CDSCO oversight pathways for diagnostic data handling position ECU vendors for future biometric-vehicle integration partnerships.
Industry Challenges
- Embedded firmware talent scarcity:Real-time operating system and AUTOSAR stack competency concentrates with experienced hires in Bengaluru and Pune, inflating compensation for qualified engineers.
- Legacy vehicle integration complexity:Retrofitting telematics modules into pre-AIS-140 commercial fleets demands custom harness and protocol gateway development that erodes margin on small-batch orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India ECU Market |
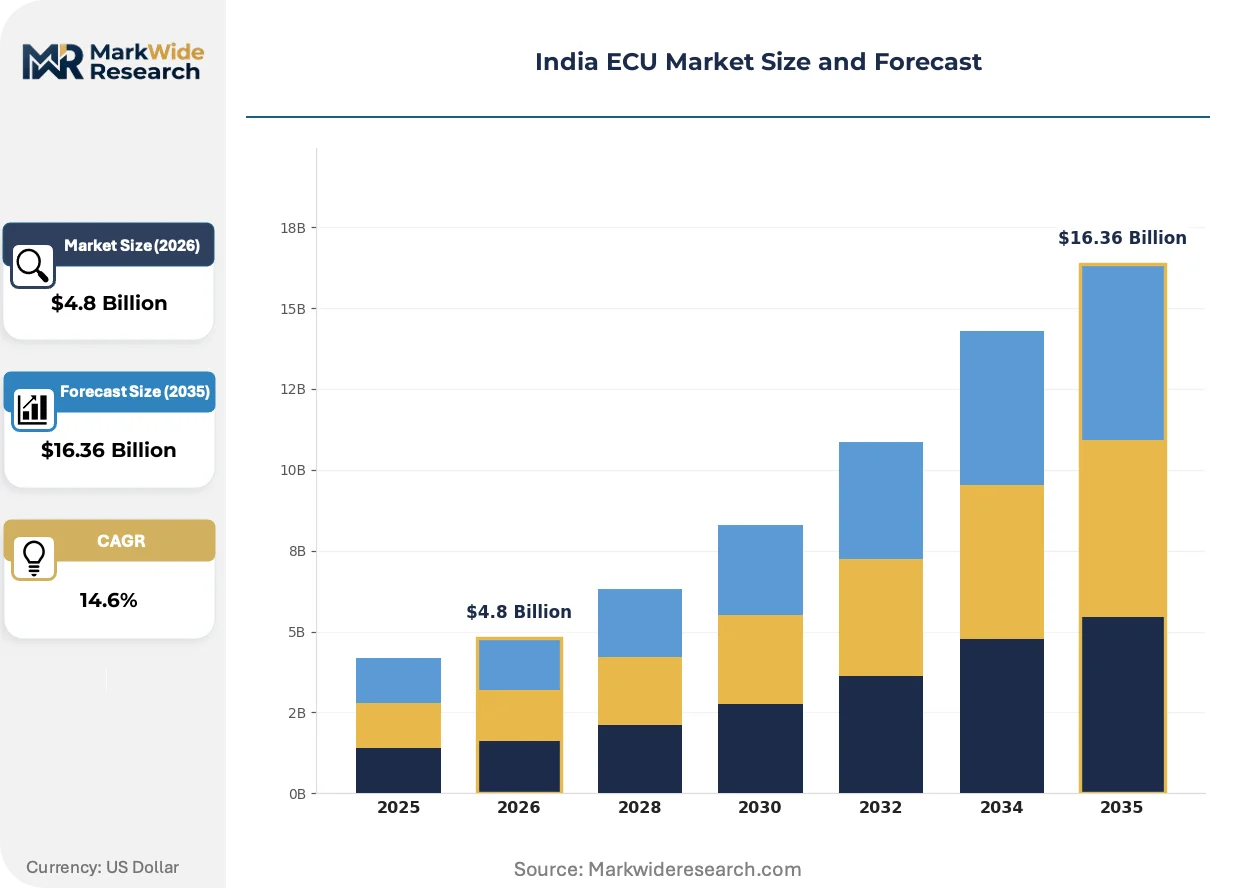
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Engine Management, Transmission Control, Body Control, Telematics Technology: Microcontroller-Based, FPGA, Mixed Signal, Digital Signal Processing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Product Type: Powertrain, Safety & Security, Infotainment, Chassis Control |
| Companies Covered | ETAS, Argus Embedded Systems Pvt. Ltd., Bosch India, AVIN Systems, SGS India, Denso Corporation, Embitel, Vector Informatik India Pvt. Ltd., Continental AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India ECU Market Strategic Shifts
Functional safety architectures and edge-computing firmware are redefining how Indian ECU suppliers partition processing loads between centralized domain controllers and distributed sensor nodes.
Domain-centralized zonal architectures are automating the consolidation of body, chassis, and powertrain control functions into fewer high-compute modules. Maruti Suzuki and Hyundai Motor India procurement teams are specifying these consolidated designs for 2027 platform refreshes. This compression is automating the displacement of discrete body control modules with integrated gateway ECUs that halve wiring harness complexity.
BIS electromagnetic compatibility testing protocols are tightening emission thresholds for 2.4 GHz telematics transceivers ahead of full AIS-140 enforcement. Domestic Tier-1 suppliers are pre-qualifying shielding designs and PCB layer stack-ups to avoid retest cycles. The commercial vehicle tracking segment is absorbing these compliance costs fastest, with fleet operators demanding certified modules to avoid registration penalties.
Fleet operators are consolidating ECU procurement through nominated Tier-1 relationships rather than direct component sourcing from electronics distributors. This channel compression favors suppliers with captive firmware development and validation capabilities. The Maharashtra and Gujarat heavy commercial vehicle assembly belts exhibit this procurement concentration most acutely, with state transport corporation tenders specifying integrated telematics-ECU packages.
India ECU Market Segmentation
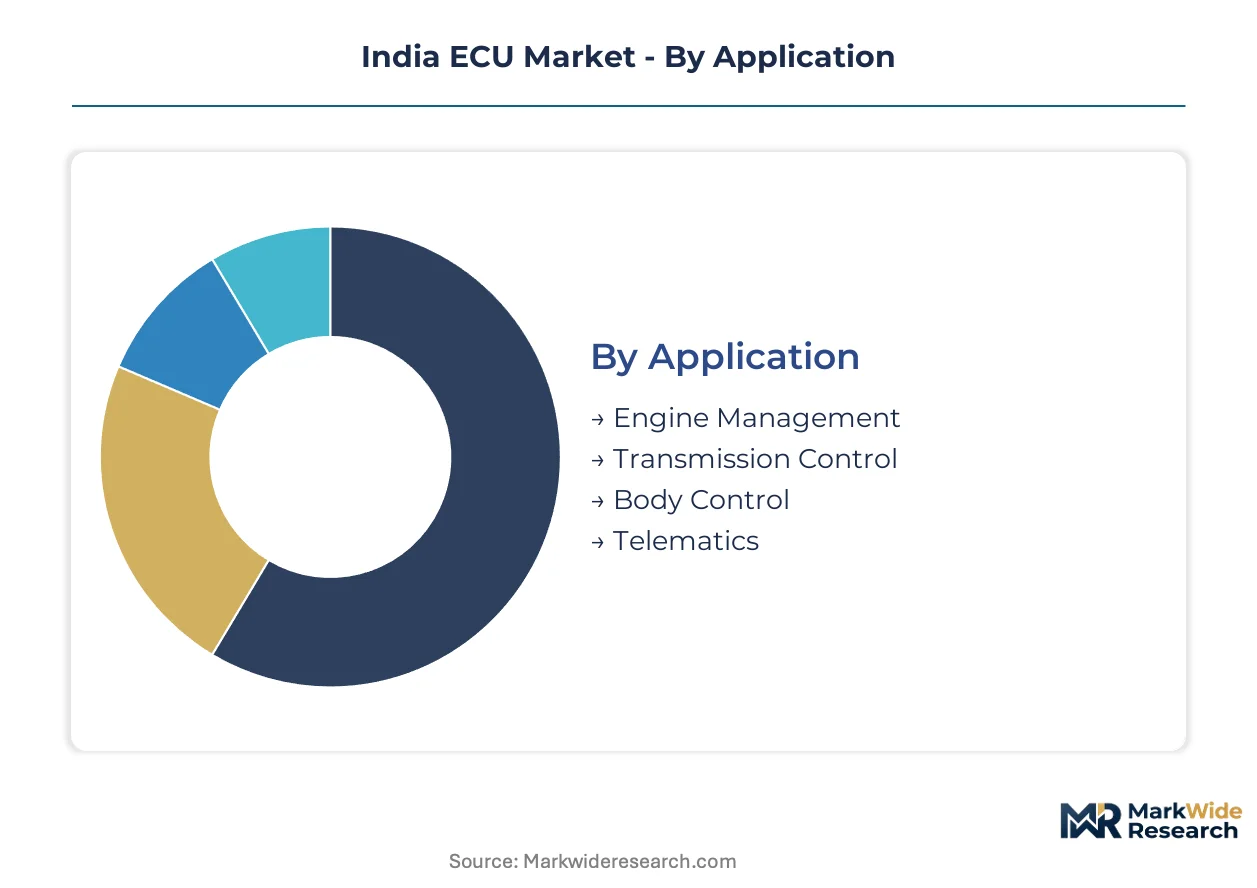
ECU procurement patterns in India diverge sharply across vehicle domains and supply chain tiers, with OEMs prioritizing integration density while Tier-1 suppliers optimize for qualification speed. Understanding these segment boundaries clarifies where firmware complexity, certification overhead, and margin pressure concentrate.
Application:
Buyers in this category differentiate by subsystem criticality and regulatory exposure, with powertrain applications demanding deterministic latency and telematics modules carrying statutory compliance burdens.
- Engine Management:These units integrate air-fuel ratio modulation, ignition timing, and exhaust gas recirculation control through 32-bit microcontroller architectures. Demand clusters with Maruti Suzuki and Hyundai Motor India powertrain programs in Haryana and Tamil Nadu, where Bharat Stage VII pre-development is accelerating 64-bit migration timelines.
- Telematics:GPS-GPRS modules with embedded SIM provisioning process location and diagnostic data streams for AIS-140 compliance. Fleet operators in Maharashtra and Gujarat commercial vehicle belts are absorbing certified units fastest to avoid registration penalties under enforcement deadlines.
- Transmission Control:Automated manual and dual-clutch actuation firmware manages clutch engagement and gear selection torque profiles.
- Body Control:Distributed modules manage lighting, window lift, and central locking through LIN bus architectures in cost-sensitive passenger car platforms.
Volume sits with Engine Management; growth tilts toward Telematics.
Technology:
Cost tier and safety integrity level drive technology selection, with mass-market powertrain applications tolerating sequential processing latency while chassis domains pay premium for parallel determinism.
- Microcontroller-Based:ARM Cortex-R and Infineon TriCore architectures execute AUTOSAR-compliant firmware with sub-100-microsecond interrupt response. Tamil Nadu and Gujarat assembly plants specify these for 90-plus percent of current ECU volume given unit economics and supplier ecosystem maturity.
- FPGA:Field-programmable gate arrays implement deterministic parallel processing for antilock braking and electronic stability control with sub-microsecond latency guarantees. Premium SUV platforms assembled in Maharashtra absorb these modules despite 3-4x cost premium over microcontroller equivalents.
- Mixed Signal:Integrated analog-digital converters condition sensor inputs without external signal conditioning components.
- Digital Signal Processing:Dedicated multiply-accumulate units execute fast Fourier transforms for knock detection and vibration analysis.
Microcontroller-Based architectures dominate current shipments; FPGA configurations are climbing fastest on safety-critical chassis penetration.
End User:
Supply chain position determines technical specification authority, with OEMs dictating integration architectures and Tier-1 suppliers managing component qualification risk.
- OEMs:Maruti Suzuki, Hyundai Motor India, and Tata Motors specify domain-centralized zonal architectures that consolidate discrete body and chassis functions into gateway ECUs. Their 2027 platform refresh timelines are compressing Tier-1 firmware development cycles by 30 percent.
- Tier-1 Suppliers:Bosch India and Continental AG manage microcontroller procurement, BIS certification, and OEM integration support through captive validation facilities in Bengaluru and Pune.
- Aftermarket Providers:Independent distributors supply replacement telematics modules for commercial fleet retrofit compliance.
- Vehicle Assemblers:Contract manufacturers in Tamil Nadu integrate ECU subassemblies without design authority.
Procurement volume concentrates with OEMs; service revenue expansion tilts toward Tier-1 Suppliers.
Product Type:
Functional domain boundaries are blurring as zonal architectures consolidate historically separate control modules, with powertrain and safety domains resisting integration due to ASIL-D integrity requirements.
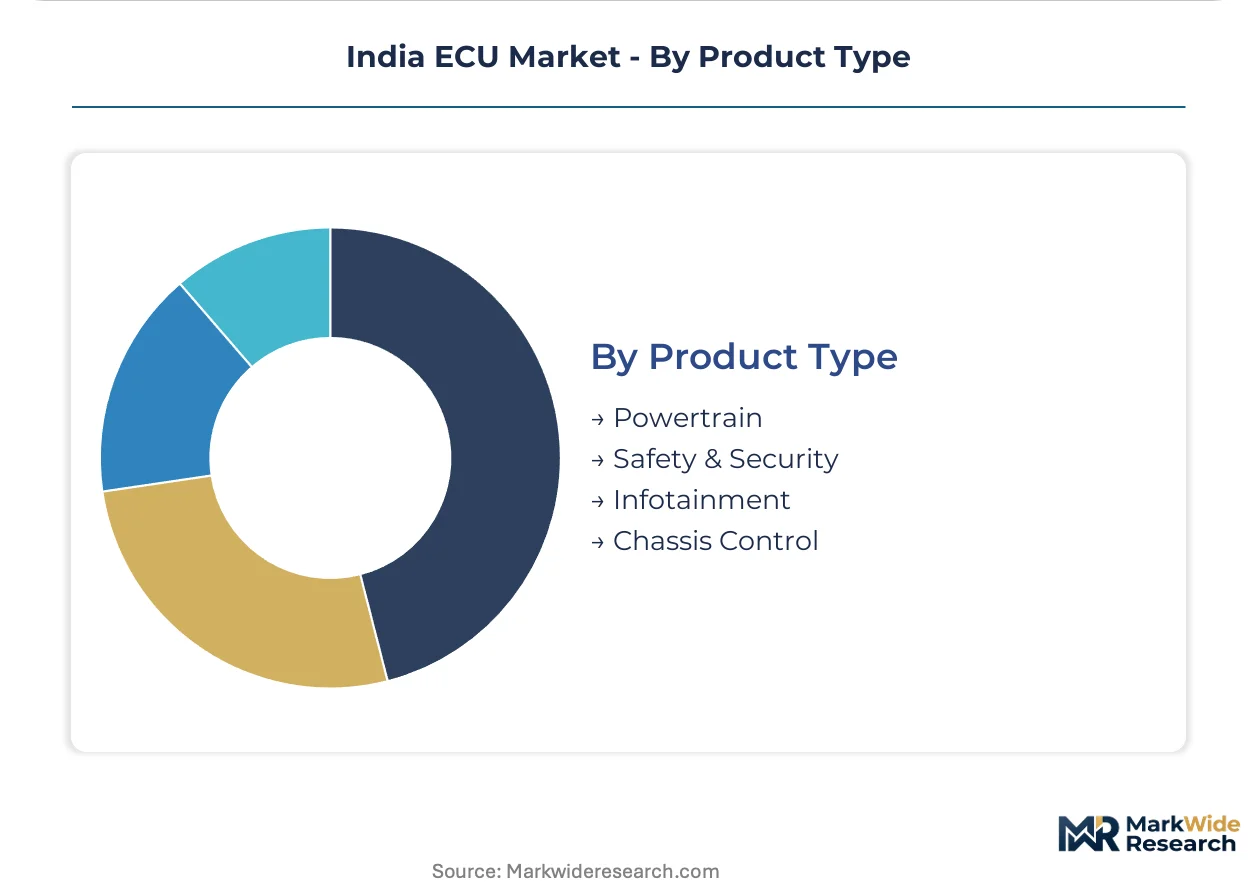
- Powertrain:Engine and transmission management units with torque arbitration and emissions feedback loops constitute the largest revenue pool. PLI scheme subsidies for SMT capacity in Tamil Nadu are reinforcing domestic assembly scale for these modules.
- Safety & Security:Airbag deployment, tire pressure monitoring, and immobilizer authentication modules carry ASIL-B through ASIL-D functional safety ratings. BIS electromagnetic compatibility testing protocols for 2.4 GHz transceivers are extending qualification timelines in this category.
- Infotainment:Android Automotive and hypervisor-based cockpit domain controllers manage display rendering and smartphone projection.
- Chassis Control:Electronic stability control and active suspension modules modulate brake pressure and damper stiffness.
Powertrain commands current installed base; Safety & Security is gaining share fastest on regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor-grade silicon feedstock from Karnataka's Bengaluru-Telangana corridor anchors India's ECU manufacturing geography. State-level electronics policies and PLI scheme disbursements are redistributing assembly capacity across five industrial clusters. Each sub-region exhibits distinct specialization patterns tied to OEM proximity and regulatory enforcement intensity.
Tamil Nadu
Passenger vehicle powertrain ECU demand concentrates around Sriperumbudur-Chennai where Maruti Suzuki and Hyundai Motor India operate integrated assembly plants. The state's Electronics Manufacturing Policy offers capital subsidies for SMT line installation that Tier-1 suppliers are capturing. Bosch India and Continental AG validation facilities in Coimbatore process BIS electromagnetic compatibility certification for telematics modules.
Maharashtra
Premium SUV chassis control modules absorb FPGA-based architectures at 3-4x cost premiums over microcontroller equivalents. The state's Industrial Policy for Electric Vehicles extends stamp duty exemptions to battery management system ECU manufacturers. Pune's Chakan-Talegaon belt hosts captive firmware development centers serving Tata Motors and Mahindra & Mahindra powertrain programs.
Gujarat
Commercial vehicle telematics procurement compresses through fleet operator-nominated Tier-1 relationships under AIS-140 enforcement deadlines. The state's Electronics Policy 2022-27 allocates land parcels in Sanand-GIFT City for automotive electronics cleanroom assembly. Domestic ECU assemblers are pre-qualifying shielding designs for 2.4 GHz transceivers to avoid BIS retest cycles.
Karnataka
Electric two-wheeler battery management system demand is creating fresh ECU supply contracts around Bengaluru's Whitefield-Electronics City corridor. The state's EV Policy 2023 mandates 100% renewable energy for electronics manufacturing units seeking PLI benefits. Argus Embedded Systems and Embitel occupy cost-optimized control module positions for scooter OEMs in this cluster.
Haryana
Engine management unit firmware complexity for Bharat Stage VII pre-development is accelerating 64-bit microcontroller migration timelines. The state's Automotive Component PLI disbursement approvals favor powertrain ECU capital expenditure in Manesar-Bawal. Maruti Suzuki's 2027 platform refresh specifications are compressing Tier-1 firmware development cycles by 30 percent here.
India ECU Market Competitive Environment
Capacity expansion dominates the current landscape as domestic Tier-1 suppliers scale SMT and cleanroom assembly to capture PLI scheme subsidies. The vendor structure concentrates around three strategic archetypes: multinational electronics conglomerates with captive semiconductor partnerships, mid-scale domestic specialists in cost-optimized body control designs, and embedded software houses with AUTOSAR stack competency. Geographic expansion into Karnataka-Telangana and strategic partnerships for microcontroller procurement constitute the dominant competitive moves.
Among multinational electronics conglomerates, Bosch India and Continental AG exemplify the integrated validation-firmware-manufacturing archetype that OEM procurement teams favor for powertrain and chassis domains. Domestic specialists including Argus Embedded Systems Pvt. Ltd. occupy positions within cost-optimized segments where LIN bus architectures and two-wheeler applications predominate. ETAS and Vector Informatik India Pvt. Ltd. represent the tool-chain and embedded software tier that underpins firmware development across supplier ecosystems. These three groupings—integrated multinational, domestic cost-optimizer, and software infrastructure—capture distinct margin pools without direct substitution.
| Leading Market Players |
|---|
| ETAS |
| Argus Embedded Systems Pvt. Ltd. |
| Bosch India |
| AVIN Systems |
| SGS India |
| Denso Corporation |
| Embitel |
| Vector Informatik India Pvt. Ltd. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Fleet operator consolidation around nominated Tier-1 supplier relationships is compressing procurement channels and forcing component vendors to absorb certification costs upfront or cede volume to integrated firmware-manufacturing houses. This buyer-driven channel compression feeds directly into margin structures, with unbundled hardware-only suppliers facing pricing pressure against competitors offering validated, BIS-certified module packages.
Pricing Analysis
Warranty and firmware update bundling now separates Tier-1 integrated suppliers from hardware-only assemblers in Indian ECU procurement. Pricing stratifies across ASIL-D safety-certified chassis modules, BIS-compliant telematics units, and cost-optimized body control designs for two-wheeler applications. Cost compression in the telematics segment is intensifying because AIS-140 enforcement deadlines force rapid requalification cycles. Fleet operators in Maharashtra and Gujarat commercial vehicle belts exhibit highest price sensitivity, while premium SUV OEMs in Maharashtra absorb FPGA-based chassis module premiums with minimal negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Maruti Suzuki and Hyundai Motor India, while Tier-1 distributors serve mid-volume aftermarket and retrofit segments. Semiconductor inputs draw from Taiwan, South Korea, and China, with microcontroller cores and power MOSFETs commanding longest lead-time exposure. Raw material dependencies center on silicon wafers, copper laminate substrates, and automotive-grade passive components. Single-source vulnerability around East Asian foundry concentration presents structural risk, particularly for 32-bit and 64-bit automotive microcontroller architectures. Distribution runs through captive Tier-1 validation facilities in Bengaluru, Pune, and Coimbatore that manage BIS certification and OEM integration support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
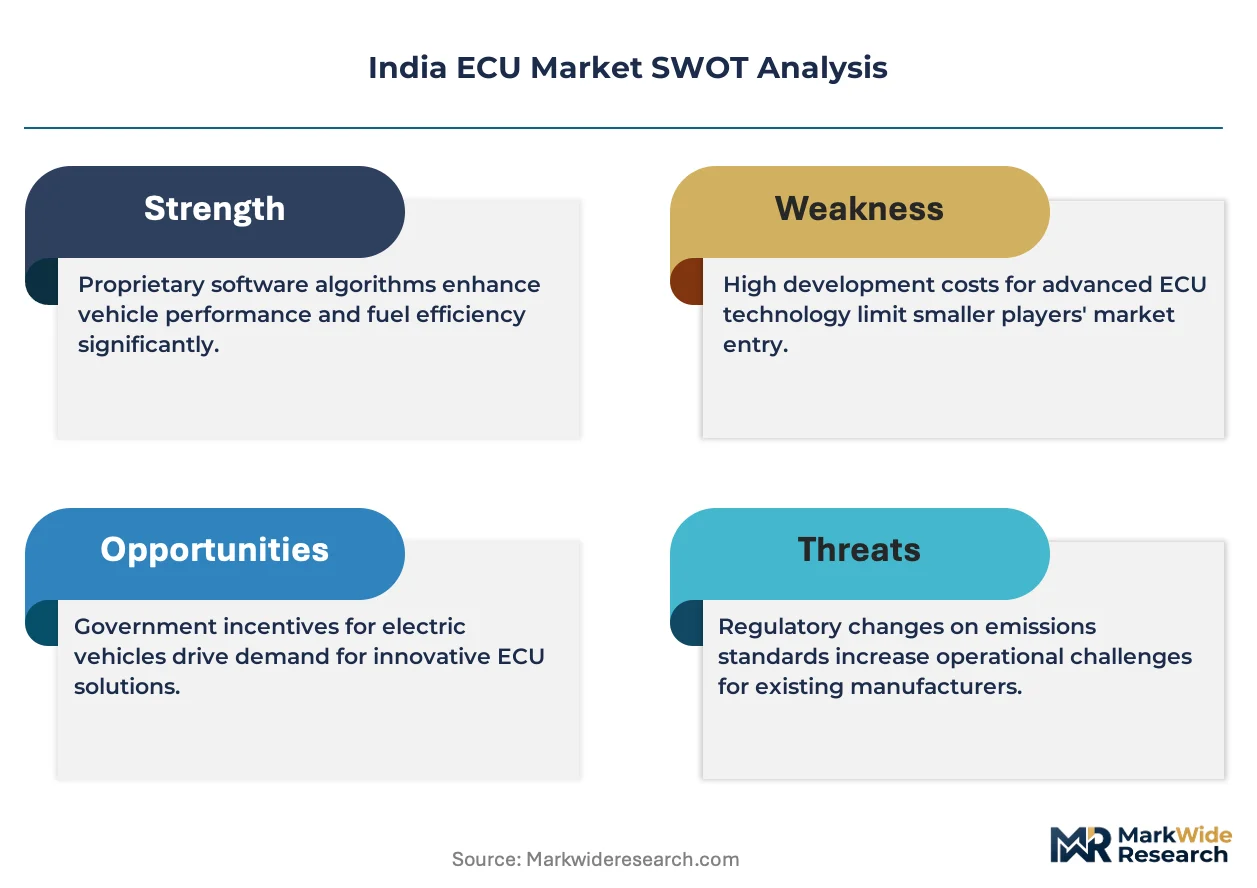
The India ECU market functions as a cost-of-compliance arena where BIS electromagnetic compatibility and thermal cycling certification creates a barrier-to-entry moat for players with captive validation infrastructure. AIS-140 mandate enforcement deepens this dynamic by compressing deployment timelines beyond what unqualified assemblers can meet.
For Market Incumbents: Hedge semiconductor input volatility through dual-sourcing microcontroller architectures from Infineon and NXP supply channels, while expanding captive SMT capacity in Tamil Nadu to capture PLI scheme disbursements before subsidy windows narrow. Defensive consolidation around firmware-automated validation pipelines protects margin against emerging domestic cost-optimizers in two-wheeler body control segments. For New Entrants and Emerging Players: Enter via Karnataka-Telangana corridor electric two-wheeler battery management system contracts, where OEM concentration around Bengaluru creates captive demand without incumbent lock-in. The most penetrable white-space sits in cost-optimized LIN bus architectures for scooter electrification programs. A go-to-market angle pairing hardware with embedded software competency—specifically AUTOSAR stack development—differentiates against pure-play assemblers. For Investors and Strategic Acquirers: The window for entry favors Tier-1 suppliers with integrated firmware validation and BIS pre-certification capabilities, as OEM procurement teams consolidate around nominated relationships. Long-term viability hinges on exposure to Bharat Stage VII powertrain firmware complexity and domain-centralized zonal architecture transitions. The signal to watch is OEM platform refresh timeline acceleration, which compresses Tier-1 development cycles and rewards suppliers with scalable validation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Domain-Centralized Zonal Architecture Investment | Maruti Suzuki and Hyundai Motor India procurement specifications for 2027 platforms consolidate discrete modules into gateway ECUs. |
| Captive Firmware Development Center Expansion | Bengaluru and Pune talent pools for AUTOSAR and real-time operating system competency anchor OEM integration support. |
| BIS Pre-Certification Infrastructure Buildout | Electromagnetic compatibility and thermal cycling validation facilities in Coimbatore accelerate product qualification timelines. |
| PLI-Aligned SMT and Cleanroom Capacity Addition | Tamil Nadu and Gujarat capital expenditure subsidies reinforce domestic assembly scale for powertrain and telematics modules. |
| Semiconductor Dual-Sourcing Partnership | Multi-foundry procurement for ARM Cortex-R and TriCore architectures mitigates East Asian supply lead-time volatility. |
Study Parameters
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, and aftermarket distributor operations underwrites the qualitative findings in this analysis. Primary interviews with embedded firmware architects, BIS certification laboratory managers, and PLI scheme disbursement officers combined with secondary validation from vehicle production databases, IHS Markit registration data, and SEC filings from multinational electronics conglomerates. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions structured the analytical framework. CAGR derivation rested on segment-level growth differential analysis and technology substitution elasticity modeling over the projection horizon. Key forecast inputs included AIS-140 compliance deadline enforcement intensity, Bharat Stage VII pre-development program acceleration, and electric two-wheeler battery management system penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or BIS certification protocol amendments. Periodic stress-testing of base assumptions is recommended, particularly around PLI scheme continuity and OEM platform refresh timeline delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Control Cable Market