
 Automotive AR HUD Market | 2026-2036
Automotive AR HUD Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive AR HUD Market Insights
Premium passenger vehicle OEMs are reorganizing their cockpit electronics procurement, shifting display budget share toward augmented reality interfaces. Continental AG leverages its integrated sensor-to-display pipeline to anchor European supply relationships. Visteon Corporation competes through software-defined HUD architectures that reduce hardware variant complexity. Bosch Mobility Solutions dominates manufacturing scale across waveguide and DLP technology lines.
An automotive AR HUD overlays navigation, ADAS alerts, and vehicle telemetry directly within the driver's forward field of view, typically projecting virtual imagery at 2.5 to 10 meters apparent distance through precision-molded freeform mirrors or holographic optical elements. Windshield displays occupy the highest installed-value tier due to optical coating complexity and windshield-forming integration requirements. LCoS technology leads resolution advancement for night-vision and pedestrian-highlighting functions, while DLP sustains cost competitiveness in mid-range vehicle programs. Glass-embedded displays are maturing fastest as laminated windshield production lines adapt to embedded holographic film insertion.
NHTSA in the United States shapes field-of-view and distraction-limitation standards that constrain HUD image placement and brightness algorithms. ECE R121 in Europe mandates minimum luminance and contrast ratios for projected information, directly influencing optical engine specification cycles. OEMs must navigate divergent photometric testing protocols across regulatory jurisdictions while anticipating CSRD-linked supplier disclosure requirements that extend through Tier-2 optical component vendors. Stakeholders should monitor which regulatory bloc first mandates AR HUD inclusion as standard equipment for Level-2-plus vehicle certification.
Market Dynamics
Windshield-integrated holographic waveguides are compressing the traditional mirror-box optical path, forcing Tier-1 suppliers to retool cleanroom assembly lines and rewrite thermal validation protocols for laminated glass insertion.
Growth Catalysts
- EU Safety Mandates:ECE R121 luminance requirements are compelling OEMs to spec AR HUDs as standard equipment for Level-2-plus vehicle certification cycles.
- LCoS Resolution Thresholds:Liquid crystal on silicon microdisplays are crossing 1080p density thresholds needed for pedestrian highlighting and night-vision fusion.
- China Cockpit Digitization:Domestic automakers in Shanghai and Shenzhen are accelerating AR HUD procurement through integrated cockpit controller consolidation programs.
Market Restraints
- Optical Engine Cost Concentration:DLP and LCoS chip supply concentrates among two Texas-based semiconductor foundries, creating single-source vulnerability.
- Windshield Coating Volatility:Precision-molded freeform mirror production requires rare-earth doped glass substrates subject to export quota fluctuations.
- Photometric Testing Fragmentation:Divergent NHTSA field-of-view standards versus ECE contrast protocols force dual-certification engineering for cross-Atlantic vehicle programs.
Strategic Opportunities
- Glass-Embedded Display Maturation:Laminated windshield production lines in Germany and the United States are adapting to holographic film insertion, collapsing assembly steps.
- ADAS Convergence:Sensor fusion between lidar point clouds and AR HUD overlays is opening subscription-based hazard-alert revenue streams.
- CSRD Disclosure Tailwinds:European sustainability reporting mandates are accelerating Tier-2 optical vendor consolidation, favoring integrated sensor-to-display pipelines.
Industry Challenges
- Optomechanical Talent Scarcity:Precision freeform mirror design requires rare combinations of geometric optics and thermal modeling expertise concentrated in Stuttgart and Detroit engineering clusters.
- Cleanroom Capex Burden:Waveguide hologram mastering demands Class-1000 fabrication facilities with multi-year depreciation timelines.
- Legacy CAN Bus Integration:Real-time AR rendering latency requirements are forcing gateway controller redesigns incompatible with 2018-era vehicle electrical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive AR HUD Market |
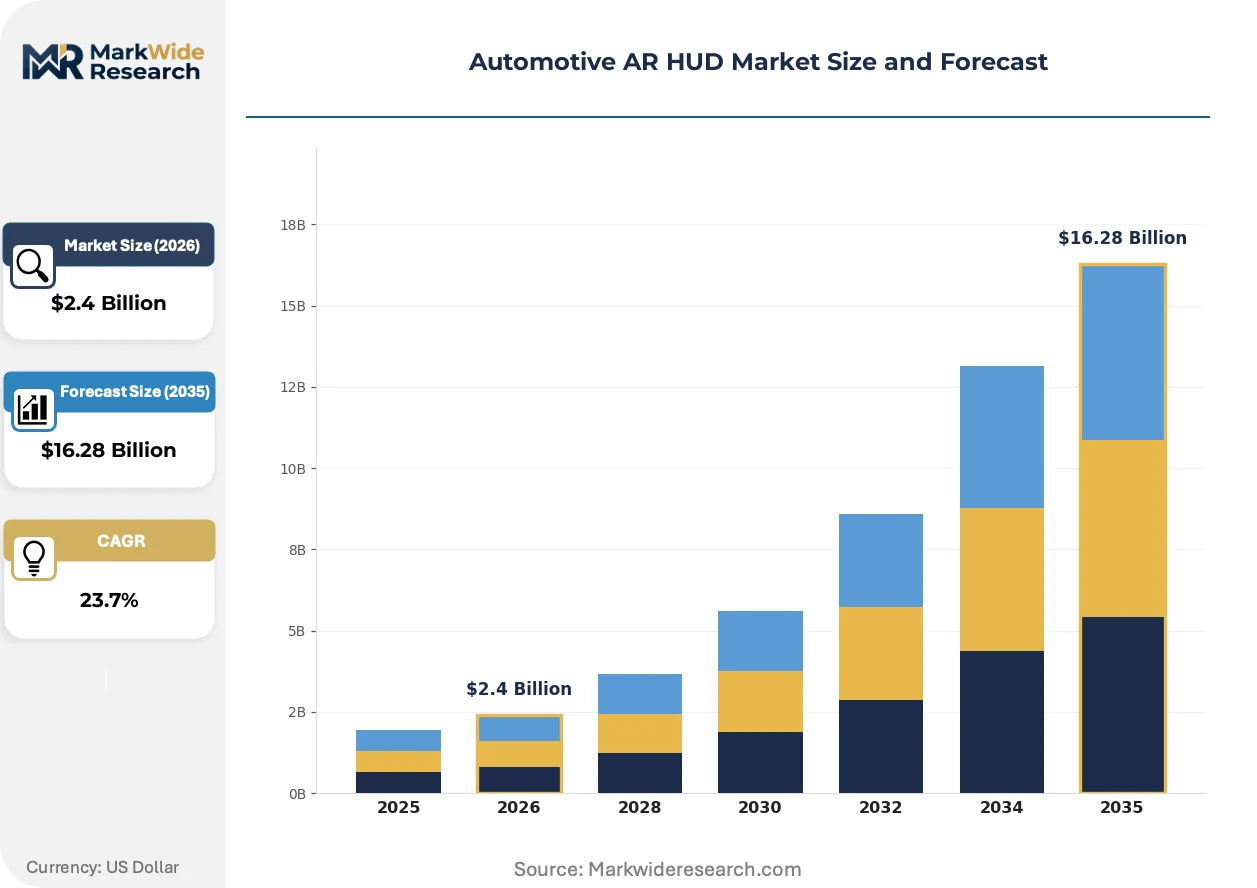
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield Displays, Glass-Embedded Displays, Combiner Displays, Smartphone-Based Systems End User: OEMs, Fleet Operators, Aftermarket Consumers, Ride-Sharing Services Technology: Optical Waveguide, DLP, LCoS, LED Installation Type: Integrated Systems, Retrofitted Solutions, Customized Displays, Modular Interfaces |
| Companies Covered | Continental AG, DENSO Corporation, Nippon Seiki Co., Ltd., Harman International, Visteon Corporation, Bosch Mobility Solutions, Yazaki Corporation, Panasonic Holdings, WayRay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive AR HUD Market Trends and Innovations
Software-defined optical architectures are separating image generation from projection hardware, enabling over-the-air calibration updates and collapsing hardware variant counts across vehicle trim lines.
Waveguide combiners are decomposing the traditional three-mirror optical bench into single-plane holographic elements laminated between windshield glass layers. German premium OEMs are piloting this architecture for 2027 model year flagship sedans. The shift is compressing optical engine volume by sixty percent while eliminating precision alignment labor from final assembly.
CSRD-linked supplier disclosure requirements are extending carbon accounting obligations through Tier-2 optical component vendors. European OEM procurement teams are now auditing holographic film coating energy intensity. Windshield manufacturers in Belgium and the Netherlands are responding with renewable-powered cleanroom certifications.
Fleet procurement managers are consolidating AR HUD specification authority from regional buying centers to global cockpit electronics directors. This centralization is displacing legacy tiered supplier arrangements with direct optical engine contracts. The pattern is most visible in United States-based premium truck and SUV programs where single-sourcing decisions now route through Michigan engineering headquarters.
Automotive AR HUD Market Segmentation
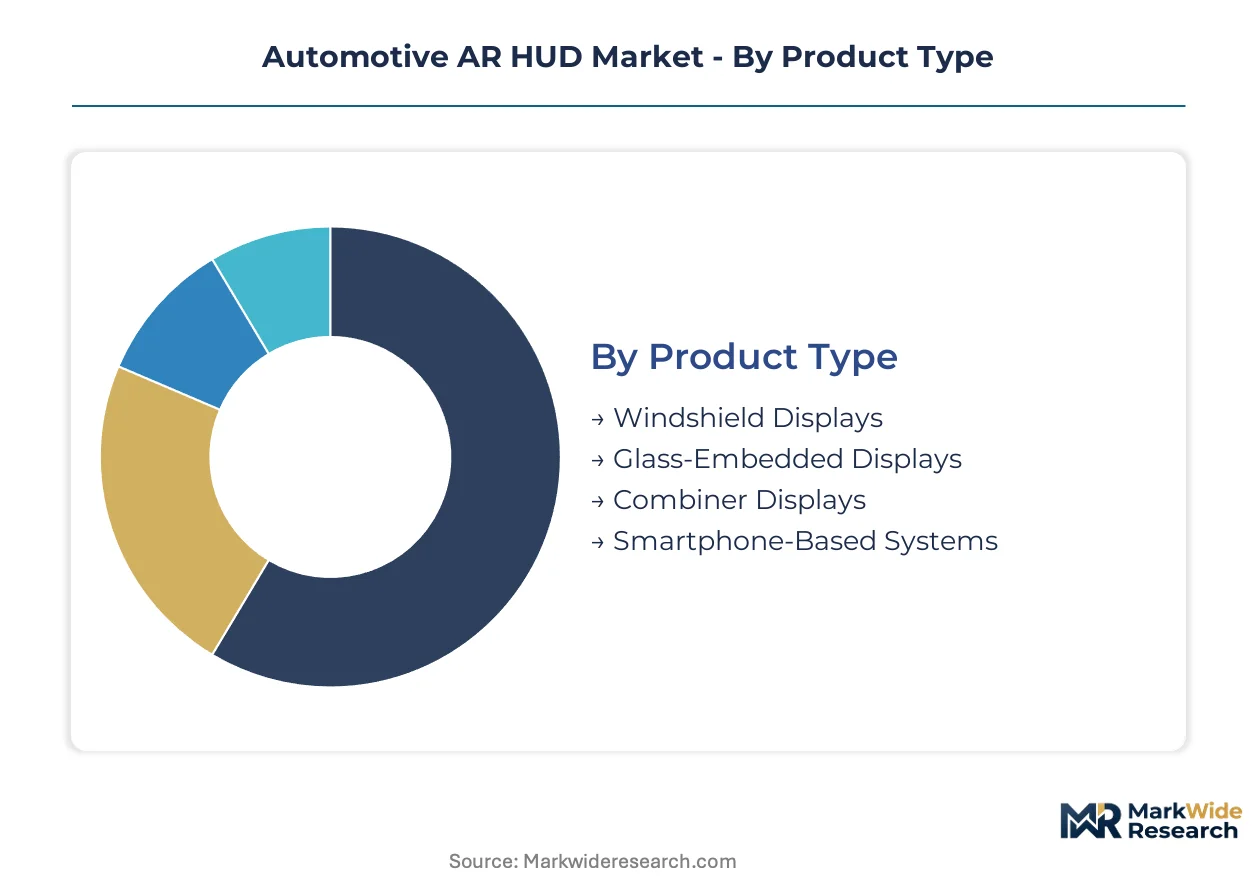
Segmentation in automotive AR HUD markets reveals how optical complexity, regulatory thresholds, and procurement authority concentrate value across distinct technology and customer configurations. Understanding these divisions exposes where specification power resides and which integration pathways command premium positioning.
Product Type:
ECE R121 luminance mandates in Europe and NHTSA field-of-view standards in the United States create divergent certification burdens that favor certain display architectures over others depending on target vehicle programs.
- Windshield Displays:Precision-molded freeform mirrors project virtual imagery at 2.5 to 10 meters apparent distance through complex optical coatings laminated into windshield glass. Demand concentrates among German premium OEMs targeting Level-2-plus certification cycles where ECE R121 compliance is mandatory. Thermal validation protocols and cleanroom assembly requirements sustain high installed-value positioning.
- Glass-Embedded Displays:Holographic film insertion between laminated glass layers collapses traditional mirror-box optical paths into single-plane elements. Shanghai and Shenzhen automakers are accelerating procurement through integrated cockpit controller consolidation programs that favor this reduced-assembly architecture. The technology is gaining share fastest as windshield production lines in Belgium and the Netherlands adapt to embedded holographic processes.
- Combiner Displays:Separate transparent screens mounted on the dashboard project imagery without windshield integration. Aftermarket channels and economy vehicle programs favor this lower-cost pathway.
- Smartphone-Based Systems:Mobile device mounts with reflective surfaces provide entry-level AR functionality. Ride-sharing fleet operators in cost-sensitive markets deploy these as interim solutions pending integrated system rollouts.
Established volume favors Windshield Displays; emerging adoption favors Glass-Embedded Displays.
End User:
Procurement authority patterns distinguish this category, with specification power shifting from regional buying centers toward centralized cockpit electronics directors.
- OEMs:Original equipment manufacturers command specification authority through direct optical engine contracts that displace legacy tiered supplier arrangements. Michigan engineering headquarters now route single-sourcing decisions for United States-based premium truck and SUV programs. CSRD-linked disclosure requirements extend carbon accounting obligations through Tier-2 optical vendors, favoring integrated sensor-to-display pipelines.
- Fleet Operators:Commercial vehicle and ride-sharing fleets consolidate AR HUD specification authority at global procurement levels. Subscription-based hazard-alert revenue streams from ADAS convergence are opening new monetization pathways for this segment.
- Aftermarket Consumers:Individual vehicle owners purchase retrofitted solutions through retail channels. Price sensitivity and installation complexity constrain penetration.
- Ride-Sharing Services:Mobility-as-a-service providers prioritize driver safety and navigation efficiency. Standardized vehicle configurations enable volume procurement of mid-tier display technologies.
Procurement consolidation favors OEMs; recurring revenue potential favors Fleet Operators.
Technology:
Supply concentration among Texas-based semiconductor foundries creates single-source vulnerability that shapes competitive positioning across optical engine architectures.
- LCoS:Liquid crystal on silicon microdisplays are crossing 1080p density thresholds essential for pedestrian highlighting and night-vision fusion functions. European premium OEMs specify these for flagship sedan programs where ECE R121 contrast requirements are most stringent. Resolution leadership sustains positioning in safety-critical applications.
- DLP:Digital light processing maintains cost competitiveness in mid-range vehicle programs through mature manufacturing scale. Bosch Mobility Solutions dominates production volume across this technology line. Supply concentration among two Texas foundries creates vulnerability that procurement teams mitigate through long-term capacity agreements.
- Optical Waveguide:Holographic elements laminated between glass layers enable sixty percent volume compression versus traditional mirror-box designs. German premium OEMs are piloting this architecture for next-generation flagship programs.
- LED:Direct-emission diode arrays provide entry-level illumination for cost-constrained applications. Simpler thermal management and supply base diversification sustain presence in economy segments.
Resolution advancement favors LCoS; manufacturing scale favors DLP.
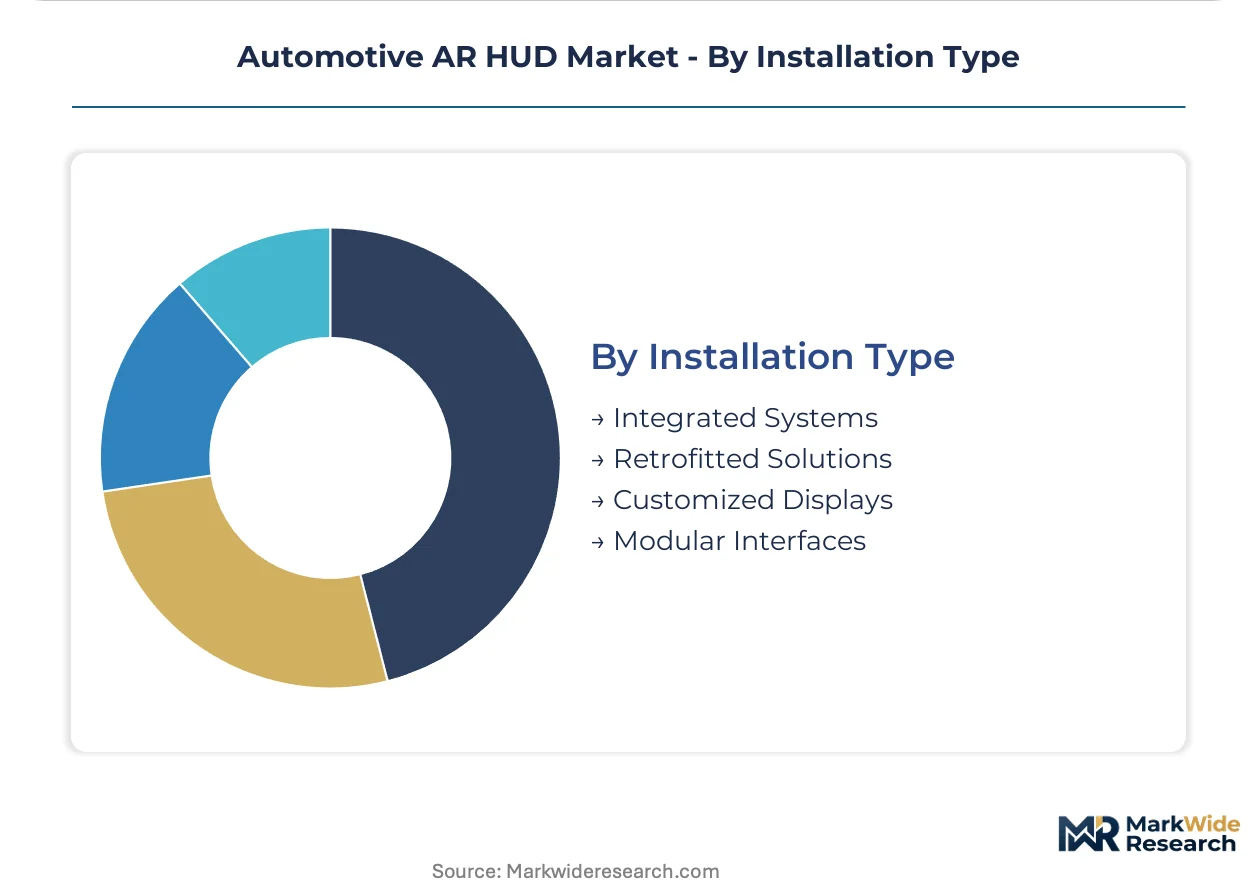
Installation Type:
Vehicle electrical architecture compatibility divides this category, with legacy CAN bus limitations forcing gateway controller redesigns for real-time AR rendering.
- Integrated Systems:Factory-installed displays embedded during vehicle assembly command highest value capture. Cleanroom fabrication and precision alignment labor sustain premium positioning. Windshield-forming integration requirements in Germany and United States production facilities favor established Tier-1 supplier relationships.
- Modular Interfaces:Standardized connection protocols enable interchangeability across vehicle platforms. Software-defined optical architectures separate image generation from projection hardware, enabling over-the-air calibration updates.
- Retrofitted Solutions:Post-production installation serves aftermarket channels and fleet refresh programs. Simpler mounting requirements trade optical performance for accessibility.
- Customized Displays:Bespoke configurations for specialty vehicle applications. Low volume and high engineering overhead constrain commercial scalability.
Value capture favors Integrated Systems; flexibility favors Modular Interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical component exports supply windshield coating systems to United States and Chinese assembly plants, establishing a transatlantic-Asia trade corridor that channels precision-molded freeform mirrors toward Detroit and Shanghai cockpit integration facilities.
United States
NHTSA field-of-view standards constrain HUD image placement algorithms for Level-2-plus vehicle certification. The IRA's domestic manufacturing incentives accelerate cleanroom fabrication investments in Michigan and Ohio. Detroit engineering headquarters now route single-sourcing decisions for premium truck and SUV programs through centralized cockpit electronics directors.
Germany
ECE R121 luminance mandates compel OEMs to spec AR HUDs as standard equipment across flagship sedan lineups. The CSRD extends carbon accounting obligations through Tier-2 optical vendors, favoring integrated sensor-to-display pipelines. Stuttgart engineering clusters concentrate precision freeform mirror design talent where geometric optics and thermal modeling expertise intersect.
China
Domestic automakers in Shanghai and Shenzhen accelerate AR HUD procurement through integrated cockpit controller consolidation programs. MIIT vehicle safety standards align with European photometric testing protocols to streamline export certification. Yangtze River Delta windshield production lines adapt to embedded holographic film insertion faster than global counterparts.
Japan
METI industrial policy directs semiconductor foundry capacity toward automotive display microdisplays. JIS standards govern optical engine reliability testing for night-vision fusion applications. Nagoya engineering centers develop LCoS resolution thresholds essential for pedestrian highlighting functions in premium vehicle programs.
South Korea
Seoul Capital Area electronics conglomerates supply DLP chip packaging services to Texas-based semiconductor foundries. MFDS automotive safety guidelines influence HUD distraction-limitation algorithms for domestic OEM export vehicles. Busan-Ulsan manufacturing corridors produce LED illumination arrays for cost-constrained economy segments.
Automotive AR HUD Market Competitive Landscape
Player mix skews toward integrated Tier-1 automotive suppliers with captive optical engineering capabilities. Market structure concentrates specification authority among five to seven dominant vendors controlling windshield-forming integration and cleanroom waveguide fabrication. Strategic archetypes separate into sensor-to-display pipeline integrators, software-defined HUD architects, and scale-driven DLP manufacturing specialists. Competitive moves center on long-term capacity agreements with Texas semiconductor foundries and backward integration into holographic film coating operations.
Within the integrated pipeline tier, Continental AG exemplifies European supply relationship anchoring through precision-molded freeform mirror production. Visteon Corporation occupies a position among software-defined HUD architects reducing hardware variant complexity across vehicle trim lines. Bosch Mobility Solutions sits within the scale-driven manufacturing archetype spanning waveguide and DLP technology lines.
| Leading Market Players |
|---|
| Continental AG |
| DENSO Corporation |
| Nippon Seiki Co., Ltd. |
| Harman International |
| Visteon Corporation |
| Bosch Mobility Solutions |
| Yazaki Corporation |
| Panasonic Holdings |
| WayRay |
| Others |
Pricing and Supply Chain Analysis
Waveguide hologram insertion replacing precision-molded freeform mirrors is redrawing procurement geography from Stuttgart engineering clusters toward Belgian and Dutch cleanroom facilities while collapsing optical engine cost structures across premium and mid-tier vehicle programs.
Pricing Analysis
Next-generation waveguide architectures command 40-60% premiums over legacy mirror-box systems, while current-generation DLP-based solutions face cost compression from LCoS resolution migration. Pricing stratifies across premium windshield-integrated, standard combiner-mounted, and economy LED-illuminated tiers. Cost compression in mid-range segments intensifies as Chinese OEMs consolidate cockpit controller procurement. Fleet operators exhibit highest price sensitivity; German premium OEMs remain least sensitive due to ECE R121 compliance mandates.
Supply Chain Analysis
Germany and China anchor precision freeform mirror production, while the United States and Belgium concentrate waveguide hologram mastering capacity. Texas-based semiconductor foundries supply DLP and LCoS chips, creating single-source vulnerability for optical engines. Supply chain risk centers on rare-earth doped glass substrate export quotas affecting windshield coating operations. Distribution runs through Tier-1 supplier direct contracts to OEM cockpit electronics directors, displacing legacy regional buying center arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive AR HUD penetration sits at early-cycle expansion, with EU Level-2-plus certification mandates accelerating standard equipment specification across European flagship lineups.
For Market Incumbents: Consolidate backward integration into holographic film coating operations to capture margin compression from glass-embedded display migration. Secure long-term capacity agreements with Texas semiconductor foundries to mitigate DLP and LCoS single-source exposure. Defensive positioning requires cleanroom fabrication scale in Belgium and the Netherlands to serve waveguide insertion demand. For New Entrants and Emerging Players: Anchor in Chinese domestic automaker procurement programs in Shanghai and Shenzhen, where integrated cockpit controller consolidation creates specification entry points. Target ride-sharing fleet operators seeking subscription-based hazard-alert monetization through ADAS convergence. Partner with Yangtze River Delta windshield manufacturers adapting fastest to embedded holographic processes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Tier-2 optical component vendors facing CSRD-linked carbon accounting disclosure requirements. Five-to-ten-year viability hinges on sensor-to-display pipeline integration depth. Monitor which regulatory bloc first mandates AR HUD inclusion as standard equipment for Level-2-plus certification as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Optical Architecture Development | Enables over-the-air calibration updates and collapses hardware variant counts across vehicle trim lines. |
| Holographic Waveguide Mastering Capacity Expansion | Belgian and Dutch cleanroom certifications position suppliers for German premium OEM 2027 flagship programs. |
| Long-Term Semiconductor Foundry Capacity Agreements | Mitigates single-source vulnerability from Texas-based DLP and LCoS chip concentration. |
| Integrated Sensor-to-Display Pipeline Consolidation | CSRD disclosure requirements favor Continental AG-style European supply relationship anchoring. |
| ADAS Convergence Platform Development | Opens subscription-based hazard-alert revenue streams from lidar point cloud fusion with AR overlays. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs records. Interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and cleanroom fabrication facility managers inform demand-side validation. Bottom-up modeling of optical engine shipments triangulates against top-down windshield production line capacity assessments.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derive from regression analysis of historical penetration rates against regulatory mandate timelines. Forecast inputs incorporate ECE R121 luminance compliance cycles and MIIT vehicle safety standard alignment patterns.
Decision-makers should treat outputs as directional under assumptions of sustained EU Level-2-plus certification mandate expansion and stable rare-earth glass substrate supply; material deviation would warrant model refresh. Recalibration cycles align with material shifts in regulatory mandate timing and semiconductor foundry capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market