
 Australia Automotive Camera Market | 2026-2036
Australia Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Automotive Camera Market Outlook
The split between premium multi-camera ADAS suites and single-function commodity units is repositioning supplier economics across the Australian market. Continental AG leverages its integrated sensor portfolio to anchor high-value OEM contracts, while Robert Bosch GmbH competes through sustained R&D intensity in image-processing algorithms. Garmin Ltd specializes in aftermarket channel control, occupying a distinct tier below factory-fit configurations.
An automotive camera is an electro-optical device comprising image sensors, signal processors, and lens assemblies engineered to capture real-time visual data for vehicle safety and navigation systems. CMOS sensors dominate current production due to lower power draw and superior low-light sensitivity compared with legacy CCD architectures. Front cameras lead product-type demand as ADAS penetration deepens, while surround-view configurations represent the fastest-growing segment as luxury and mid-range OEMs standardize 360-degree visibility. Night vision cameras retain niche positioning within premium passenger vehicles, where margin pools concentrate despite lower absolute volumes.
Australia's Design Rules under the Department of Infrastructure, Transport, Regional Development, Communications and the Arts mandate escalating crash-avoidance capabilities, directly expanding camera fitment requirements for new vehicle registrations. The Australian Competition and Consumer Commission enforces product safety standards that shape aftermarket camera quality benchmarks and market access conditions. Stakeholders must monitor regulatory calibration timelines against sensor technology refresh cycles to align inventory and certification investments.
Market Dynamics
The Australian Design Rules under the Department of Infrastructure, Transport, Regional Development, Communications and the Arts are compressing deployment timelines for camera-based safety systems, forcing OEMs and Tier-1 suppliers to accelerate certification cycles and inventory positioning ahead of mandated fitment thresholds.
Growth Catalysts
- ADR 98/00 Mandate:Australia's mandated advanced driver-assistance standards under ADR regulations require escalating crash-avoidance capabilities, directly expanding camera fitment requirements for new vehicle registrations.
- Victoria Manufacturing Cluster:Concentrated automotive assembly and component manufacturing in Victoria creates procurement pull for integrated camera systems across passenger and commercial vehicle lines.
- CMOS Sensor Maturation:Superior low-light sensitivity and reduced power draw in CMOS architectures are enabling wider deployment across mid-range vehicle segments previously served by lower-performance alternatives.
Market Restraints
- Semiconductor Input Volatility:Image sensor and signal processor supply remains concentrated among a limited supplier base, exposing Australian assemblers to allocation constraints and price instability.
- Technical Limitation in Adverse Weather:Lens soiling, glare, and precipitation degradation continue to constrain camera reliability in Australia's high-dust and tropical cyclone exposure zones.
- Regulatory Friction in Aftermarket Certification:Australian Competition and Consumer Commission enforcement of product safety standards creates compliance barriers for uncertified camera imports, limiting price-competitive supply.
Strategic Opportunities
- New South Wales Fleet Density:Commercial fleet operator concentration in Sydney and surrounding industrial corridors presents concentrated demand for retrofit camera systems and telematics integration.
- Surround-View Standardization:Luxury and mid-range OEMs are standardizing 360-degree visibility configurations, opening margin pools for multi-camera suite suppliers.
- Telematics Convergence:Integration of camera feeds with fleet management platforms and insurance risk scoring models is creating new service revenue streams beyond hardware sales.
Industry Challenges
- Embedded Vision Engineering Talent Scarcity:Shortage of specialists in image signal processing, neural network optimization, and functional safety architecture constrains local R&D expansion.
- ADR Certification Timeline Compression:Accelerated regulatory calibration cycles force suppliers to align sensor technology refresh investments with uncertain mandate enforcement dates.
- Legacy Vehicle Integration Complexity:Retrofit camera deployment in existing fleet vehicles requires adaptation to disparate electrical architectures and display systems, elevating installation cost and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Automotive Camera Market |
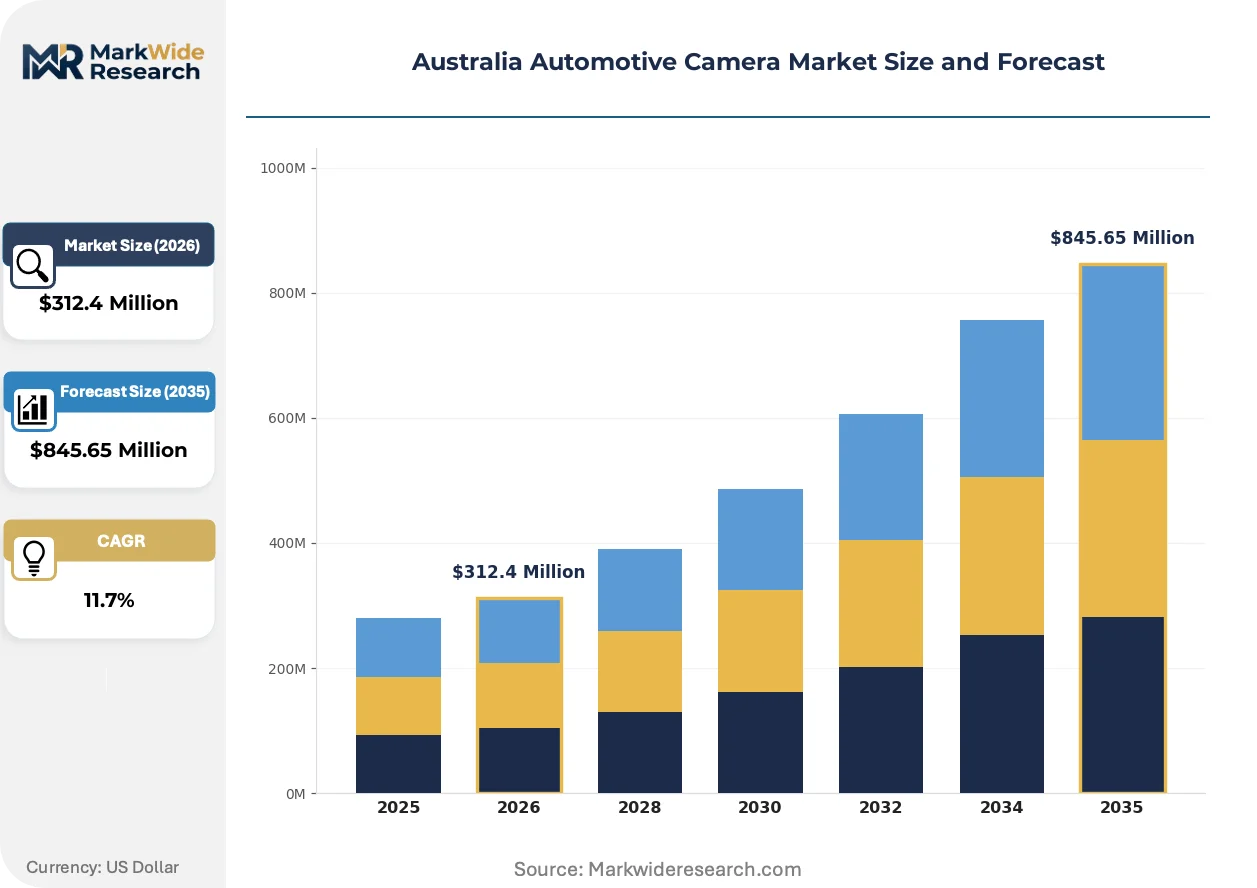
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Cameras, Rear Cameras, Surround View Cameras, Night Vision Cameras Technology: Infrared, Ultrasonic, Radar, CMOS Application: ADAS, Parking Assistance, Lane Departure Warning, Blind Spot Detection End User: OEMs, Aftermarket Providers, Fleet Operators, Insurance Companies |
| Companies Covered | Garmin Ltd, Continental AG, Panasonic Corporation, Magna International Inc, Robert Bosch GmbH, Denso Corporation, Valeo, Autoliv Inc, Aptiv PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Automotive Camera Market Strategic Shifts
Sensor fusion architectures and edge-computing penetration are restructuring how visual data is processed within Australian vehicle platforms, shifting value capture from discrete hardware toward integrated perception stacks.
CMOS image sensors with embedded high dynamic range processing are consolidating market share across Australian OEM specifications, displacing legacy CCD architectures in front-facing ADAS modules. Tier-1 suppliers are adopting these sensors for their reduced thermal management requirements and simplified peripheral circuitry. The technology is consolidating supplier margins into fewer, higher-volume sensor vendors capable of meeting ADR 98/00 performance thresholds.
Australian Design Rules under the Department of Infrastructure, Transport, Regional Development, Communications and the Arts are mandating escalating autonomous emergency braking and lane-keeping assistance capabilities. The regulation forces camera system redundancy and diagnostic self-monitoring features into base vehicle configurations. Commercial vehicle segments face the steepest compliance cost escalation as retrofit timelines compress against registration renewal cycles.
Fleet operators in New South Wales and Victoria are unbundling camera hardware procurement from installation and telematics platform subscriptions. Direct sourcing through authorized distributors is displacing traditional dealer-channel bundling for commercial vehicle retrofits. This pattern is most visible in logistics and mining fleet segments where total cost of ownership transparency drives vendor selection criteria.
Australia Automotive Camera Market Segmentation
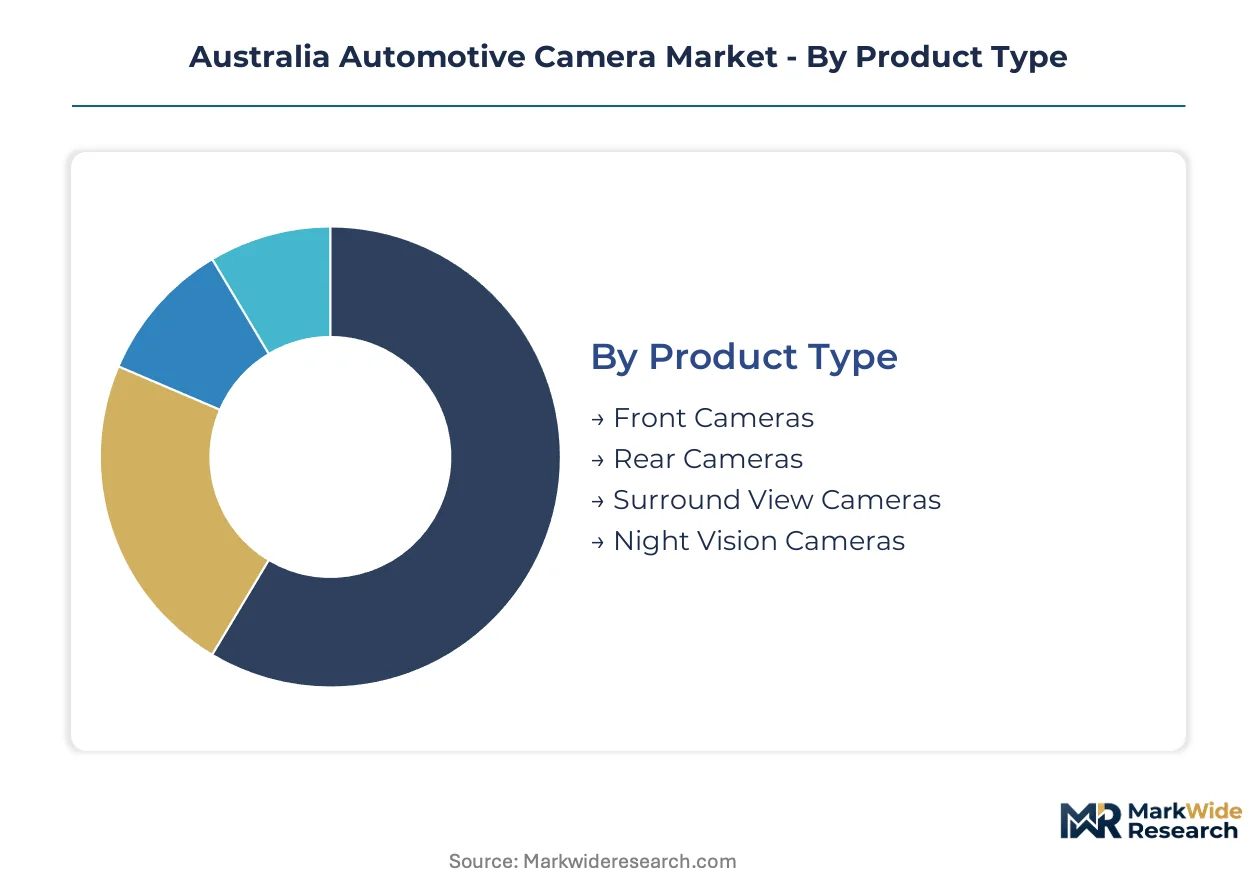
Camera specification varies sharply across Australian vehicle platforms. OEM procurement patterns favor integrated multi-sensor suites, while aftermarket channels prioritize modular retrofit compatibility with legacy electrical architectures.
Product Type:
Standardization pressure from ADR 98/00 compliance compresses specification variance in front-facing modules, while rear and surround configurations retain customization flexibility for premium positioning.
- Front Cameras:CMOS-based electro-optical assemblies with embedded HDR processing anchor autonomous emergency braking and lane-keeping assistance mandates. Victoria and New South Wales assembly lines concentrate procurement for ADAS-integrated modules as ADR deadlines tighten.
- Surround View Cameras:Multi-lens arrays generating stitched 360-degree field-of-view for low-speed maneuvering. Luxury and mid-range OEMs in Australian manufacturing clusters are standardizing these configurations, opening margin pools for multi-camera suite suppliers.
- Rear Cameras:Single-lens units for reversing assistance with parking guidance overlay. Australian fleet operators in logistics corridors drive retrofit demand for telematics-linked variants.
- Night Vision Cameras:Thermal or near-infrared sensitive sensors for pedestrian detection beyond headlamp range. Premium passenger vehicles in Australian urban centers retain niche fitment despite lower absolute volumes.
Most installed capacity flows through Front Cameras. Expansion is steepest in Surround View Cameras.
Technology:
Cost tier stratification separates mature CMOS deployment from emerging fusion architectures requiring multi-sensor calibration.
- CMOS:Dominant image sensor architecture leveraging lower power draw and superior low-light sensitivity versus legacy CCD alternatives. Australian OEM specifications increasingly mandate embedded HDR processing for ADR 98/00 threshold compliance.
- Radar:Complementary ranging technology fused with camera feeds for redundancy in adverse weather conditions. Mining and logistics fleets in Queensland exposure zones prioritize radar-camera fusion for dust and precipitation resilience.
- Infrared:Near-infrared illumination paired with sensitive detectors for nighttime pedestrian detection. Premium vehicle segments in Sydney and Melbourne metropolitan markets sustain limited deployment.
- Ultrasonic:Acoustic ranging for short-distance parking assistance, typically paired with rear cameras rather than standalone. Aftermarket retrofitters favor ultrasonic-camera bundles for installation simplicity in legacy vehicles.
Volume concentrates in CMOS sensor procurement. Technology refresh investment is climbing fastest in Radar fusion configurations.
Application:
Customer type divides between regulatory-mandated safety functions and convenience-driven parking assistance, with divergent margin structures.
- ADAS:Integrated perception stacks for autonomous emergency braking, adaptive cruise control, and lane-keeping assistance. Australian Design Rules mandate escalating capability thresholds, forcing camera redundancy and diagnostic self-monitoring into base configurations.
- Parking Assistance:Low-speed maneuvering support combining rear cameras with ultrasonic sensors or surround-view stitching. Fleet operators in New South Wales logistics corridors unbundle hardware procurement from installation and telematics subscriptions.
- Lane Departure Warning:Front-camera-based lane boundary monitoring with haptic or audible alerts. Mid-range vehicle segments drive volume as standardization spreads from premium tiers.
- Blind Spot Detection:Side-mounted cameras or radar supplementing mirror visibility for lane-change safety. Commercial vehicle retrofit timelines compress against registration renewal cycles in Victoria.
ADR compliance funnels investment toward ADAS applications. Parking Assistance is gaining share fastest in fleet retrofit channels.
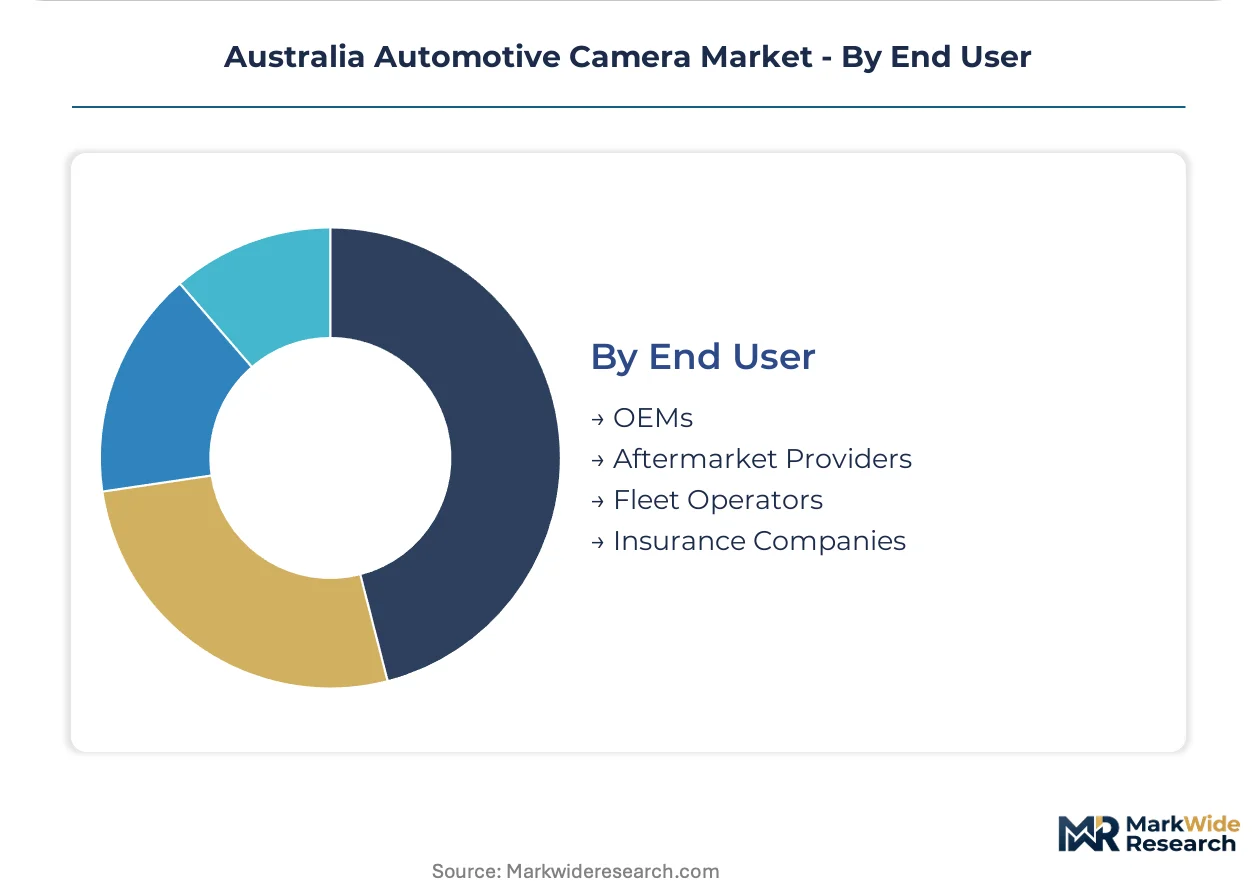
End User:
Supply concentration among Tier-1 integrators contrasts with fragmented aftermarket distribution serving dispersed fleet and retail demand.
- OEMs:Original equipment manufacturers integrating cameras at vehicle assembly. Continental AG and Robert Bosch GmbH anchor high-value contracts through integrated sensor portfolios and algorithm R&D intensity.
- Fleet Operators:Commercial vehicle owners retrofitting camera systems for safety compliance and insurance risk scoring. Direct sourcing through authorized distributors displaces dealer-channel bundling in logistics and mining segments.
- Aftermarket Providers:Independent installers and retail distributors serving consumer vehicle upgrades. Australian Competition and Consumer Commission enforcement creates compliance barriers for uncertified imports.
- Insurance Companies:Risk underwriters mandating or incentivizing camera fitment for policy pricing. Telematics convergence creates service revenue streams beyond hardware sales for integrated platform vendors.
Procurement volume concentrates in OEM channels. Fleet Operator direct sourcing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's automotive camera demand concentrates in coastal manufacturing corridors, while interior mining and logistics corridors drive retrofit procurement. Victoria and New South Wales anchor OEM integration, with Queensland and Western Australia expanding fleet retrofit channels.
New South Wales
Sydney's logistics corridors concentrate commercial fleet operators demanding telematics-integrated camera systems. The state's road safety regulator enforces heavy vehicle safety standards that mandate visual monitoring equipment for interstate freight operators. Manufacturing activity in Western Sydney industrial zones supports aftermarket installation capacity for retrofit deployments.
Victoria
Melbourne's automotive assembly clusters generate OEM procurement pull for ADAS-integrated camera modules. The Department of Infrastructure, Transport, Regional Development, Communications and the Arts calibrates ADR enforcement timelines that compress supplier certification cycles. Geelong and surrounding manufacturing corridors host Tier-1 supplier facilities serving both passenger and commercial vehicle lines.
Queensland
Mining fleet operators in the Bowen Basin and Surat Basin drive demand for ruggedized camera systems with dust and vibration resilience. The state's Department of Transport and Main Roads mandates safety equipment upgrades for heavy vehicle registration renewals. Brisbane's port logistics zone concentrates retrofit installation providers serving coastal freight corridors.
Western Australia
Pilbara mining operations require camera systems engineered for extreme heat and particulate exposure beyond standard automotive specifications. The state's Main Roads Western Australia enforces commercial vehicle safety audits that include visual monitoring compliance. Perth's industrial southern suburbs host specialized integrators serving resource sector fleet operators.
South Australia
Adelaide's remaining automotive component manufacturing supports niche camera module assembly for export markets. The state's Department for Infrastructure and Transport administers heavy vehicle safety inspections that drive periodic retrofit demand. Port Adelaide logistics facilities generate procurement for trailer-mounted camera systems in intermodal freight operations.
Australia Automotive Camera Market Competitive Environment
Top-tier vendors anchor OEM supply contracts, while mid-tier specialists capture aftermarket retrofit channels. The market structures around three distinct competitive tiers: integrated sensor conglomerates, algorithm-focused Tier-1 suppliers, and aftermarket distribution specialists. Consolidation pressure concentrates procurement leverage among vehicle assemblers. Dominant competitive moves include portfolio diversification into fused sensor architectures and strategic partnerships with telematics platform vendors.
Within the integrated sensor tier, Continental AG and Robert Bosch GmbH exemplify vendors combining hardware manufacturing with embedded software development. Garmin Ltd occupies a distinct aftermarket position below factory-fit configurations. Panasonic Corporation and Denso Corporation represent Asia-Pacific-based conglomerates with captive component supply chains. These archetypes illustrate how supplier economics split between high-value OEM integration and price-sensitive retail channels.
| Leading Market Players |
|---|
| Garmin Ltd |
| Continental AG |
| Panasonic Corporation |
| Magna International Inc |
| Robert Bosch GmbH |
| Denso Corporation |
| Valeo |
| Autoliv Inc |
| Aptiv PLC |
| Others |
Value Chain & Pricing Dynamics
Tier-1 OEM procurement concentration in Victoria and New South Wales assembly corridors anchors contract-based pricing with multi-year offtake commitments. This buyer archetype's volume scale and ADR 98/00 certification requirements compress supplier margins while rewarding integrated sensor portfolios with pricing power.
Pricing Analysis
Bundled factory-fit configurations command premium positioning against unbundled aftermarket retrofits where fleet operators direct-source hardware separately from installation and telematics subscriptions. Three-tier pricing structure across premium multi-camera ADAS suites, standard front-camera modules, and economy rear-view units separates OEM-integrated from retail-channel supply. Cost compression in commodity rear-camera tiers intensifies because semiconductor input volatility and uncertified import competition squeeze distributor margins. Fleet operators in New South Wales logistics corridors exhibit highest price sensitivity, while luxury OEMs in Victorian manufacturing clusters demonstrate lowest sensitivity due to ADR compliance mandates and brand positioning requirements.
Supply Chain Analysis
ADR 98/00 certification and ACCC product safety standards gate market access, filtering uncertified imports and consolidating procurement leverage among qualified Tier-1 integrators. Image sensor supply concentrates in Taiwan, South Korea, and Japan where CMOS foundry capacity and signal processor fabrication anchor component flows. Australian assemblers draw from concentrated semiconductor inputs, specialized lens assemblies, and automotive-grade cabling harnesses. Single-source vulnerability in advanced CMOS sensor allocation exposes local inventory positioning to global foundry scheduling. Distribution runs through authorized Tier-1 supplier networks into OEM assembly lines, with secondary channels serving aftermarket retrofitters through specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on CMOS sensor cost-down curves and surround-view standardization shifting mid-range vehicles toward premium-tier content per vehicle.
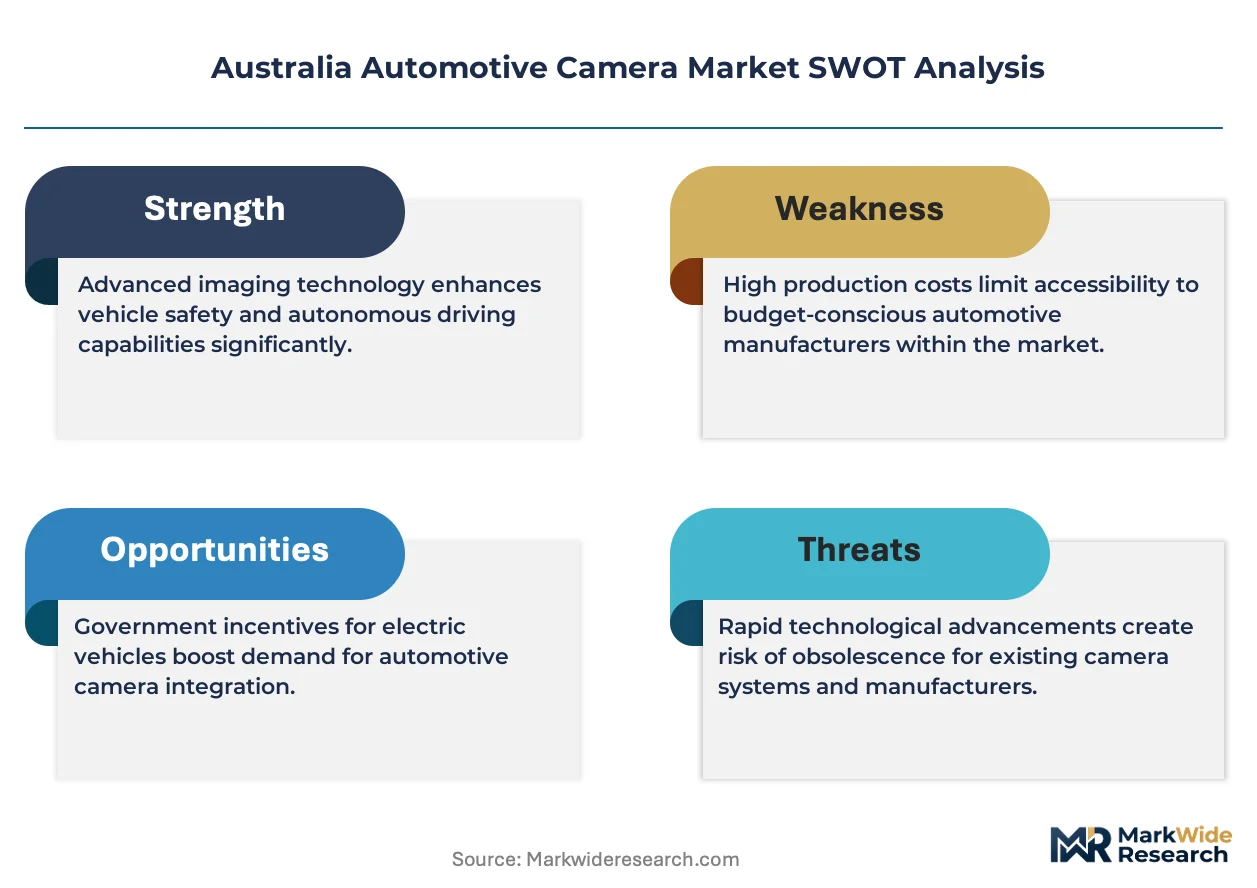
For Market Incumbents: Cement OEM contract renewal rates by embedding diagnostic self-monitoring features ahead of ADR calibration timeline compression. Deepen backward integration into CMOS sensor qualification pipelines to defend against allocation constraints from Taiwan and South Korea foundries. Channel control through exclusive telematics platform partnerships protects against fleet operator unbundling trends in New South Wales and Victoria. For New Entrants and Emerging Players: Mining fleet operators in Queensland and Western Australia represent an underserved buyer archetype requiring ruggedized camera systems with dust and vibration resilience beyond standard automotive specifications. Target retrofit installation partnerships with authorized distributors in Brisbane and Perth industrial corridors. A go-to-market angle anchored in extreme-environment reliability testing and accelerated ACCC certification pathways unlocks procurement access constrained by registration renewal deadlines. For Investors and Strategic Acquirers: Tier-1 automotive electronics conglomerates are the most active acquirer in this space, targeting algorithm-focused specialists with embedded vision engineering capabilities. Long-term viability across the analysis window hinges on sensor fusion architecture ownership and telematics data monetization potential. Acquisition target archetypes include mid-tier aftermarket distributors with fleet operator relationships and embedded software shops with functional safety certification track records. The signal to watch is ADR enforcement timeline acceleration compressing supplier certification cycles and consolidating procurement leverage among pre-qualified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Investment | Integrates camera feeds with radar and ultrasonic inputs for ADR 98/00 redundancy mandates. |
| Telematics Platform Partnership | Links camera hardware to fleet management and insurance risk scoring in New South Wales corridors. |
| ACCC Certification Acceleration | Compresses market access timelines for aftermarket providers against uncertified import competition. |
| CMOS Supplier Diversification | Reduces allocation risk from Taiwan and South Korea foundry concentration. |
| Surround-View Standardization Push | Captures margin pools as mid-range OEMs adopt 360-degree visibility configurations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, fleet operations directors, and ACCC regulatory affairs specialists. Secondary validation drew from Australian Design Rules documentation, vehicle production databases, IHS Markit registration data, and customs import records. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting approaches distributed value across product type, technology, application, and end user dimensions. Vehicle class, propulsion architecture, and content per vehicle tiers informed penetration modeling. CAGRs were derived from historical trajectory analysis and regulatory mandate enforcement schedules. Forecast inputs included ADR 98/00 compliance timelines, CMOS sensor foundry capacity expansion, and fleet operator telematics adoption curves across the projection horizon.
Inputs from OEM procurement systems and Tier-1 supplier order books were available through the study window; gaps in aftermarket channel inventory positioning introduce uncertainty bands in retrofit demand estimates. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and semiconductor supply normalization. A model refresh is warranted upon material change in ADR calibration timelines or foundry allocation priority shifts affecting Australian-bound component flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market