
 Automotive Wireless Module Market | 2026-2036
Automotive Wireless Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wireless Module Market Outlook
Market Context
UNECE R155/R156 cybersecurity certification is bifurcating the supplier landscape into qualified and non-qualified tiers. Sierra Wireless leverages its pre-certified module portfolio to anchor contracts with European OEMs requiring type approval. Quectel Wireless competes on manufacturing scale, sustaining cost advantages across 4G and 5G automotive variants. u-blox differentiates through GNSS-integrated cellular modules, occupying a specialized position in telematics hardware.
Technical Definition and Structural Segments
An automotive wireless module is a self-contained radio frequency subsystem embedding baseband processors, power management circuits, and antenna interfaces within a temperature-rated enclosure designed for under-hood or cabin deployment; these modules enable real-time data exchange between vehicles, infrastructure, and cloud services. LTE Modules dominate current production volumes given established network coverage and automotive-grade reliability, while 5G Modules capture expanding design wins as infrastructure densifies and low-latency use cases mature. Wi-Fi Modules serve high-bandwidth infotainment streams, whereas V2X technology segments remain nascent with margin pools concentrated in pilot deployments and regulatory-mandated corridors.
Regulatory Framework and Outlook
FCC Part 90 rules govern dedicated short-range communications in the United States, while ETSI standards harmonize V2X spectrum access across European member states; China's MIIT enforces domestic encryption protocols for cellular modules, creating market access conditions that favor localized certification. GDPR-linked data governance in Europe and California's CCPA extend compliance burdens to telematics data flows, reshaping module firmware architectures. Stakeholders must monitor spectrum reallocation proceedings and cybersecurity mandate timelines to align R&D roadmaps with certification windows.
Market Dynamics
Cellular-V2X protocol convergence is compressing supplier margins as automakers consolidate module sourcing around single-radio architectures capable of handling both telematics and direct vehicle-to-infrastructure communication.
Growth Catalysts
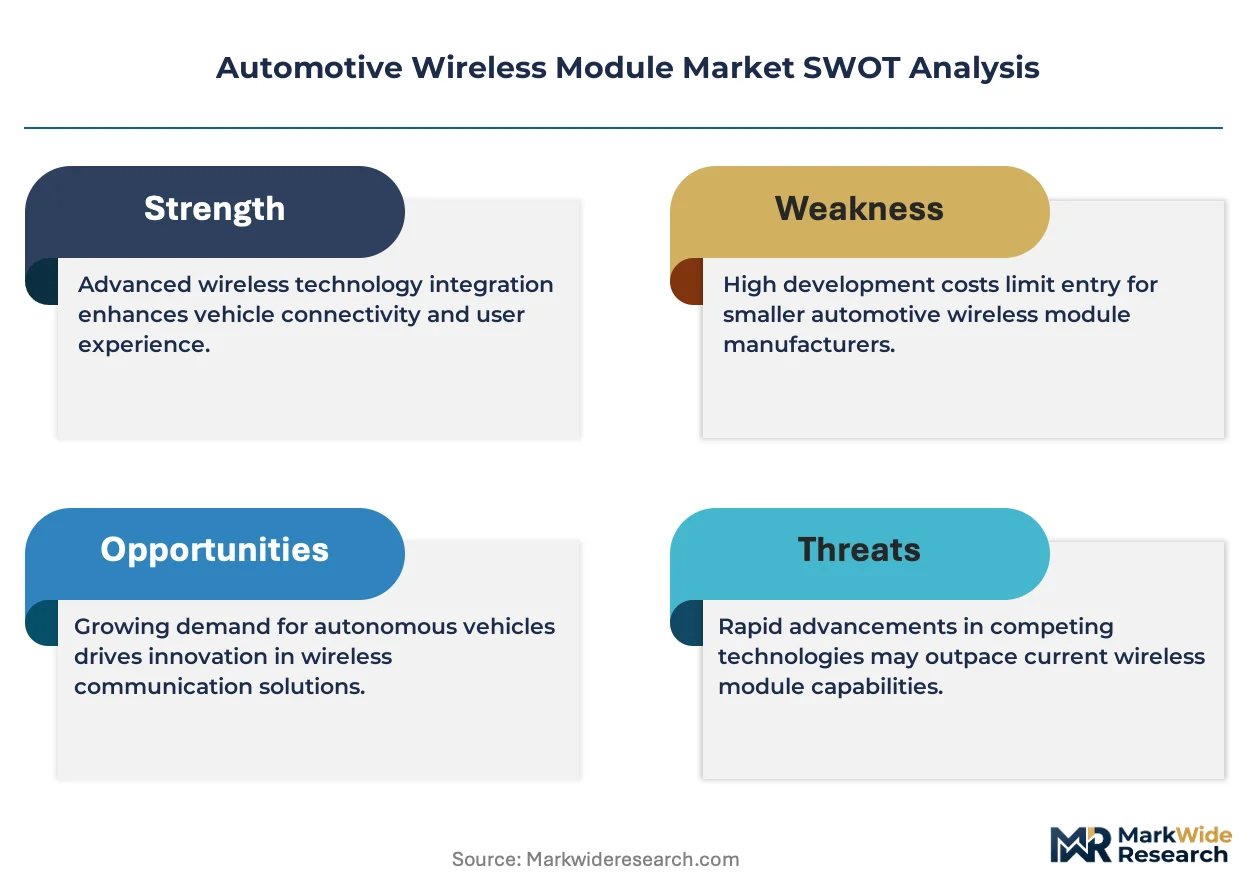
- UNECE R155 Mandate:European OEMs must deploy cybersecurity-certified modules by type-approval deadlines, creating certified-supplier preference cascades.
- China EV Production:Domestic manufacturers integrate cellular modules at factory gate, embedding connectivity as standard rather than option.
- 5G Network Densification:Low-latency roadside units in Germany and South Korea enable real-time hazard warning applications.
Market Restraints
- Semiconductor Concentration:Baseband processor supply concentrates among three foundry operators in Taiwan, exposing automotive programs to allocation volatility.
- MIIT Encryption Requirements:China's domestic cipher protocols force module redesigns for market access, extending certification timelines.
- DSRC Spectrum Reallocation:FCC Part 90 rule uncertainty in the United States stalls dedicated short-range communications deployment.
Strategic Opportunities
- Software-Defined Modules:Firmware-upgradable radio platforms allow post-deployment feature activation, shifting revenue toward recurring service models.
- India PLI Scheme:Production-linked incentives for automotive electronics attract module assembly investments targeting domestic OEMs.
- GNSS-Cellular Fusion:Integrated positioning modules command premium positioning in telematics hardware for autonomous lane-keeping systems.
Industry Challenges
- RF Engineering Talent Scarcity:Automotive-grade antenna design and thermal simulation expertise concentrates among veteran suppliers, constraining new entrant scaling.
- Multi-Protocol Certification Queues:Simultaneous 5G NR, C-V2X, and UWB qualification creates testing bottlenecks at notified bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wireless Module Market |
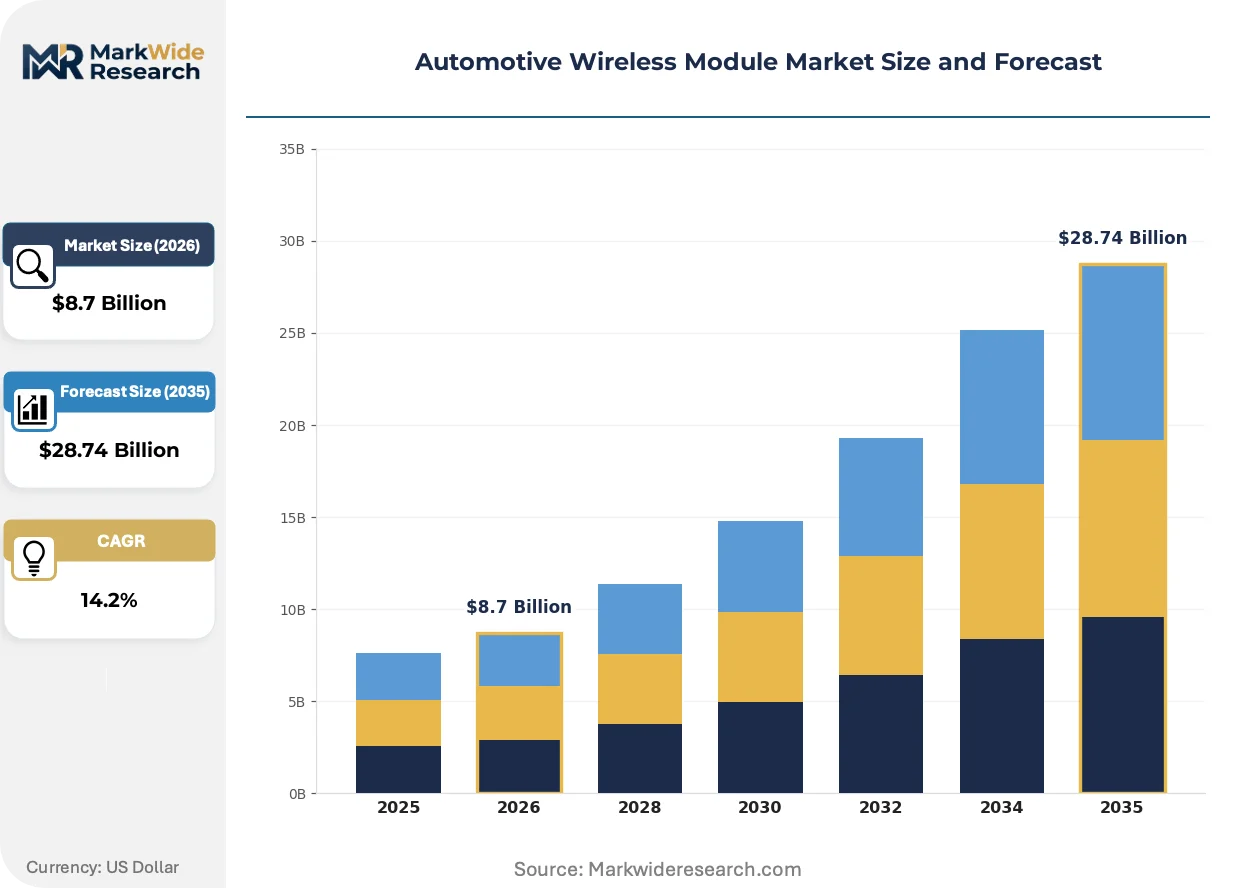
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Modules, Wi-Fi Modules, Zigbee Modules, LTE Modules Technology: 4G, 5G, V2X, DSRC End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Management Application: Infotainment, Telematics, Vehicle Analytics, Safety Systems |
| Companies Covered | Sierra Wireless, Murata, u-blox, Eagle Wireless, Quectel Wireless, Telit, Huawei, Gemalto, Fibocom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wireless Module Market Strategic Shifts
Module architectures are shedding discrete components as baseband integration accelerates, collapsing traditional hardware boundaries while forcing suppliers to defend value through software and security certification stacks.
Integrated antenna-in-package designs are decomposing the traditional separation between RF front-ends and module enclosures. Tier 1 telematics suppliers in Stuttgart and Detroit are adopting these compact units for roofline-mounted shark-fin assemblies. The technology is compressing bill-of-materials line counts and shifting electromagnetic compatibility liability onto module vendors.
REACH substance restrictions are phasing out specific flame-retardant chemistries in automotive plastics, forcing module housing reformulations. European module suppliers face supply chain requalification costs for halogen-free alternatives. The regulation most affects cabin-deployed Wi-Fi modules where polymer surface area exposure triggers stricter substance thresholds.
Fleet operators are consolidating connectivity procurement through vehicle-as-a-service platforms rather than discrete hardware purchases. Leasing companies in California and the Netherlands now specify module performance tiers in service-level agreements. This compresses upfront hardware margins while extending supplier revenue recognition over multi-year contract terms.
Automotive Wireless Module Market Segmentation
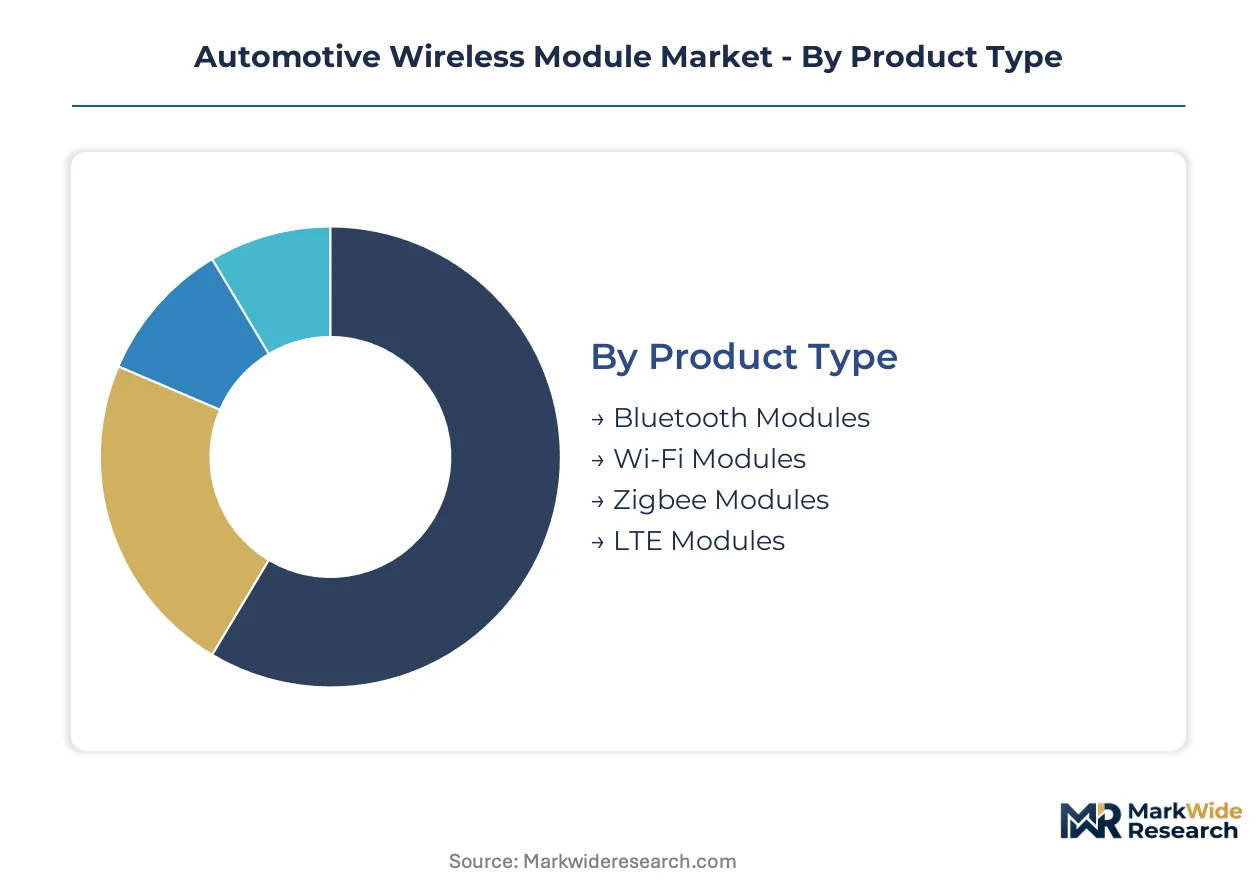
Automotive wireless modules fragment across multiple technical and commercial dimensions. Product type determines thermal and RF performance specifications. End-user channel dictates certification requirements and contract structures.
Product Type:
Module categories flow through distinct procurement channels. OEMs source LTE and Wi-Fi variants through Tier-1 telematics contracts. Bluetooth modules reach assembly lines via infotainment subsystem suppliers.
- LTE Modules:These units embed automotive-grade baseband processors with extended temperature ranges for under-hood deployment. Production volumes concentrate in China, where domestic EV manufacturers embed cellular connectivity as standard equipment. The UNECE R155 cybersecurity mandate in Europe is compressing supplier qualification tiers around pre-certified module portfolios.
- Wi-Fi Modules:High-throughput radio subsystems support 802.11ax standards for in-cabin streaming and over-the-air updates. Demand clusters in premium vehicle programs across Germany and the United States. REACH substance restrictions on flame-retardant chemistries are forcing housing reformulations for cabin-deployed units.
- Bluetooth Modules:Low-power short-range radios enable smartphone pairing and tire pressure monitoring handoffs.
- Zigbee Modules:Mesh-networking variants serve in-vehicle sensor networks with minimal power draw.
By volume, LTE Modules lead. By growth pace, Wi-Fi Modules are climbing the fastest.
Technology:
Technology tiers map to application latency requirements and infrastructure maturity. 4G dominates current production. 5G and V2X capture design wins in next-generation architectures.
- 4G:Established LTE protocols deliver reliable telematics connectivity across dense network coverage areas. Current production volumes favor this technology given automotive-grade reliability validation and cost structures.
- 5G:New Radio architectures enable sub-10 millisecond latency for real-time hazard warnings. Design wins are expanding in Germany and South Korea as roadside unit densification progresses. Baseband processor supply concentration in Taiwan creates allocation volatility for automotive programs.
- V2X:Cellular-vehicle-to-everything protocols support direct vehicle-to-infrastructure communication without network dependency.
- DSRC:Dedicated short-range communications face deployment uncertainty pending FCC Part 90 rule finalization in the United States.
By installed base, 4G holds the dominant position. By design win momentum, 5G is gaining share fastest.
End User:
Customer type determines contract scale and technical integration depth. OEMs and Tier-1 suppliers drive volume. Fleet operators are consolidating procurement through service-level agreements.
- OEMs:Vehicle manufacturers specify module performance tiers directly in platform architectures. European OEMs now mandate cybersecurity certification as a baseline qualification. Factory-gate integration in China treats cellular modules as standard rather than optional equipment.
- Tier-1 Suppliers:Telematics hardware specialists aggregate module sourcing for multiple OEM programs. These suppliers face margin compression as automakers consolidate around single-radio architectures handling both telematics and V2X.
- Aftermarket Providers:Retrofit specialists serve vehicle parc upgrades with plug-and-play connectivity solutions.
- Fleet Management:Leasing companies in California and the Netherlands specify module performance tiers in multi-year service contracts rather than discrete hardware purchases.
By contract value, OEMs lead. By procurement model innovation, Fleet Management is expanding most quickly.
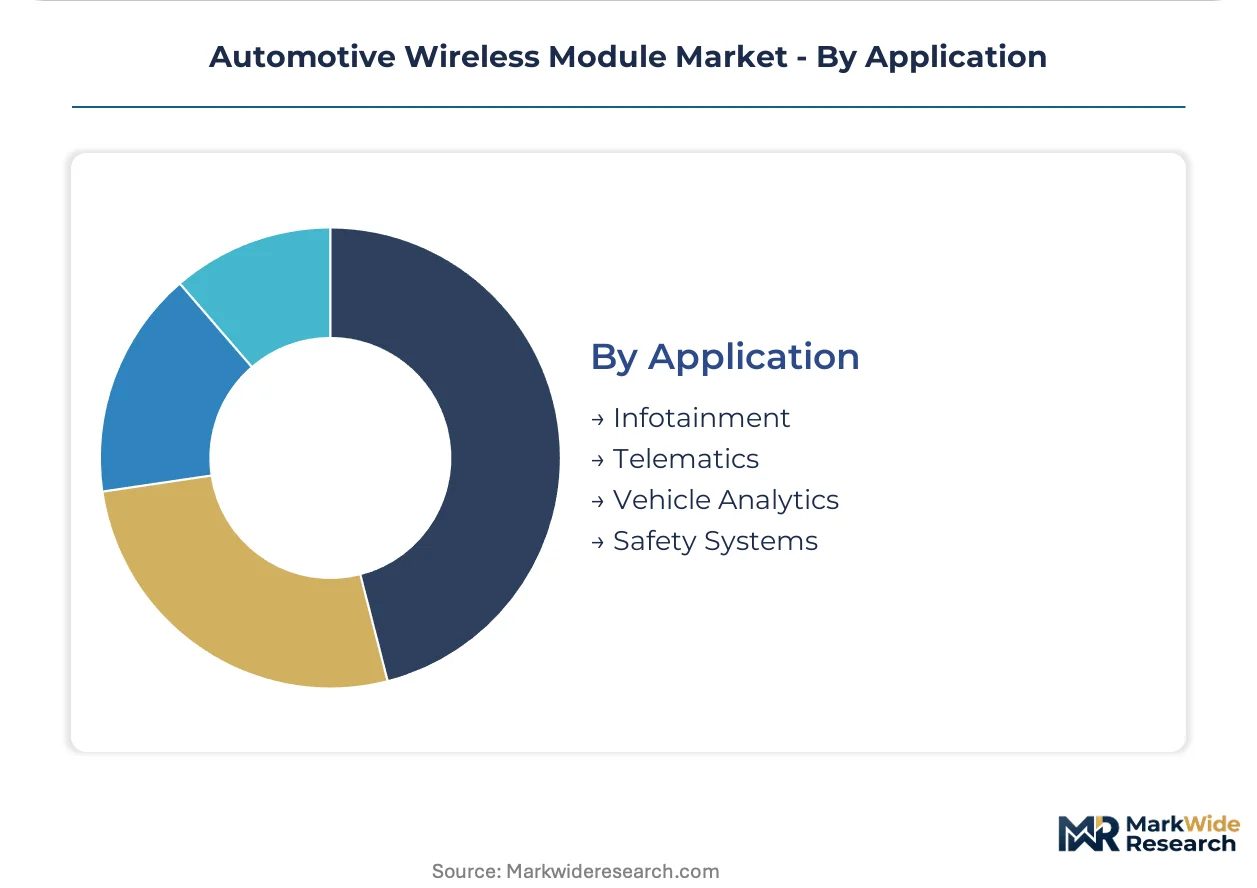
Application:
Application segments align with vehicle domain architectures. Infotainment and telematics represent mature revenue pools. Safety systems command premium positioning.
- Telematics:Modules enable cloud connectivity for remote diagnostics, stolen vehicle tracking, and usage-based insurance. GNSS-cellular fusion variants command premium positioning for autonomous lane-keeping systems. India's PLI scheme for automotive electronics is attracting module assembly investments targeting domestic OEM telematics programs.
- Safety Systems:Low-latency modules support automatic emergency braking and cooperative collision avoidance. Regulatory mandates in European corridors are accelerating V2X deployment for hazard warning applications.
- Infotainment:High-bandwidth modules stream media and enable smartphone mirroring protocols.
- Vehicle Analytics:Edge-computing modules process sensor data for predictive maintenance and driver behavior scoring.
By deployment scale, Telematics leads. By regulatory tailwinds, Safety Systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 5G network densification along Germany's A9 digital test corridor and China's Beijing-Shanghai high-speed rail fiber backbone underwrites regional leadership in low-latency automotive connectivity deployment.
China
Domestic EV manufacturers embed cellular modules at factory gate, treating connectivity as standard equipment. MIIT enforces domestic encryption protocols for cellular modules, forcing redesigns for market access. Module assembly clusters concentrate in Shenzhen and Dongguan within the Pearl River Delta.
Germany
European OEMs mandate UNECE R155 cybersecurity certification as baseline supplier qualification. ETSI standards harmonize V2X spectrum access across member states. Stuttgart-based Tier-1 telematics suppliers adopt integrated antenna-in-package designs for roofline-mounted assemblies.
United States
Premium vehicle programs in Michigan and California drive high-throughput Wi-Fi module demand for infotainment streaming. FCC Part 90 rule uncertainty stalls dedicated short-range communications deployment. Fleet operators in California consolidate connectivity procurement through vehicle-as-a-service platforms.
South Korea
5G New Radio architectures enable sub-10 millisecond latency for real-time hazard warning applications. Government-backed roadside unit densification progresses in Seoul and Busan metropolitan corridors. Baseband processor supply concentration in Taiwan creates allocation volatility for automotive programs.
India
The PLI scheme for automotive electronics attracts module assembly investments targeting domestic OEM telematics programs. TRAI spectrum allocations support cellular-V2X pilot corridors. Manufacturing investments cluster in Tamil Nadu and Karnataka to serve Maruti Suzuki and Hyundai Motor India supply chains.
Automotive Wireless Module Market Competitive Environment
Listed leaders compete with private specialists across certification depth and manufacturing scale. The supplier landscape bifurcates into cybersecurity-qualified and non-qualified tiers following UNECE mandates. Three archetypes dominate: pre-certified module specialists, high-volume manufacturing scale players, and GNSS-integrated positioning specialists. Competitive moves concentrate on strategic partnerships for certification access and portfolio diversification into software-defined radio platforms.
Among North American-listed connectivity specialists, Sierra Wireless exemplifies the pre-certified module archetype anchoring European OEM contracts. Quectel Wireless and u-blox occupy distinct positions within the competitive set, with the former representing high-volume manufacturing scale across 4G and 5G automotive variants and the latter sitting within the specialized tier for GNSS-cellular fusion modules in telematics hardware.
| Leading Market Players |
|---|
| Sierra Wireless |
| Murata |
| u-blox |
| Eagle Wireless |
| Quectel Wireless |
| Telit |
| Huawei |
| Gemalto |
| Fibocom |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts between European OEMs and Taiwanese baseband foundries lock in supply access while anchoring price visibility across multi-year automotive programs. These arrangements concentrate procurement leverage among pre-certified module specialists, compressing margin flexibility for second-tier suppliers competing on spot-market silicon allocations.
Pricing Analysis
Volume-discount tiering structures stratify across cybersecurity certification grade, with UNECE R155-qualified modules commanding sustained premiums over non-certified alternatives. Price differentiation hinges on certification tier and automotive-grade thermal validation, with factory-gate integration in China driving cost compression at the highest volume bands. Pricing pressure intensifies as automakers consolidate around single-radio architectures handling both telematics and V2X. Fleet operators exhibit highest price sensitivity through vehicle-as-a-service procurement, while premium OEM programs retain tolerance for GNSS-cellular fusion premiums.
Supply Chain Analysis
Inventory lead times for automotive-grade baseband processors stretch across foundry allocation cycles, with buffer stock strategies concentrating among Tier 1 telematics suppliers in Stuttgart and Detroit. Manufacturing gravity centers on China, Taiwan, and South Korea, with module assembly drawing from baseband silicon, RF front-end components, and halogen-free polymer housings. Single-source vulnerability in Taiwan-based foundry capacity exposes automotive programs to allocation volatility. Distribution runs through Tier 1 telematics aggregators rather than direct OEM module procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as regulatory mandates bifurcate the supplier landscape, with cybersecurity certification requirements creating defendable niches for qualified specialists alongside manufacturing-scale generalists.
For Market Incumbents: Secure UNECE R155 certification moats through accelerated qualification timelines, locking in European OEM platform wins before mandate deadlines tighten. Deepen backward integration into RF front-end component sourcing to buffer margin compression from single-radio architecture consolidation. Anchor recurring-revenue streams through firmware-upgradable module platforms, shifting contract structures toward post-deployment feature activation. For New Entrants and Emerging Players: UNECE R155 certification fast-tracks open procurement channels at European OEMs facing supplier qualification bottlenecks, creating entry wedges despite incumbent scale advantages. Target India's PLI-supported module assembly investments, where domestic OEM telematics programs lack qualified local suppliers. Pursue GNSS-cellular fusion specialization for autonomous lane-keeping system integration, commanding premium positioning outside commodity LTE module competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined module specialists with firmware-upgrade capabilities and multi-year fleet service agreements. Long-term viability favors suppliers with dual certification depth across automotive-grade thermal validation and regional encryption mandates. Monitor FCC Part 90 rule finalization as inflection signal for DSRC spectrum reallocation and C-V2X deployment acceleration in North American corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | UNECE R155 pre-certification anchors European OEM platform contracts ahead of mandate deadlines. |
| Software-Defined Module Development | Firmware-upgradeable radio platforms shift revenue toward recurring service models with fleet operators. |
| Antenna-in-Package Integration | Compact RF front-end designs compress bill-of-materials for Stuttgart-based Tier 1 telematics suppliers. |
| Regional Assembly Footprint Expansion | India PLI scheme investments target domestic OEM telematics programs with localized certification. |
| GNSS-Cellular Fusion Specialization | Integrated positioning modules command premium placement in autonomous lane-keeping hardware. |
Study Parameters
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and RF component specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, UNECE regulatory filings, and FCC docket proceedings. Bottom-up module shipment estimates triangulated against top-down automotive connectivity penetration models.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from logistic adoption curves for 5G and V2X technologies, with forecast inputs including roadside unit densification timelines and cybersecurity mandate phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EV production growth and stable foundry allocation to automotive programs; material deviation in semiconductor supply or regulatory timeline acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
North America Automotive Display Market