
 Automotive Ultrasonic Sensors Market | 2026-2036
Automotive Ultrasonic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ultrasonic Sensors Market Analysis
Buyer concentration among OEMs is expanding as vehicle manufacturers consolidate sensor procurement under centralized ADAS platforms. Continental AG leverages its integrated chassis systems division to bundle ultrasonic modules with radar and camera suites. Robert Bosch GmbH anchors European supply through captive semiconductor partnerships and in-house MEMS fabrication. VALEO competes aggressively in China through localized production facilities serving domestic electric vehicle brands.
Automotive ultrasonic sensors are electroacoustic transducers operating at frequencies between 40 kHz and 58 kHz, emitting pulsed sound waves to calculate object distance via time-of-flight measurement for parking assistance, blind spot monitoring, and low-speed collision avoidance. Parking assist sensors dominate installed volumes due to universal fitment across economy through luxury vehicle segments, while digital sensors capture expanding margin pools as OEMs demand higher resolution and software-defined signal processing. MEMS sensors represent the fastest-growing technology category, displacing conventional analog architectures in next-generation platform designs.
The U.S. NHTSA mandates rear visibility and automatic emergency braking standards that directly expand ultrasonic sensor fitment rates in light vehicles. EU REACH and RoHS frameworks restrict hazardous substances in piezoelectric ceramics and solder compositions, forcing material substitutions that alter supplier qualification timelines. China's MIIT enforces GB standards for intelligent connected vehicle components, creating domestic certification barriers for non-Chinese manufacturers. Stakeholders must monitor divergence between regional electromagnetic compatibility requirements and evolving software validation protocols as sensor fusion architectures advance.
Market Dynamics
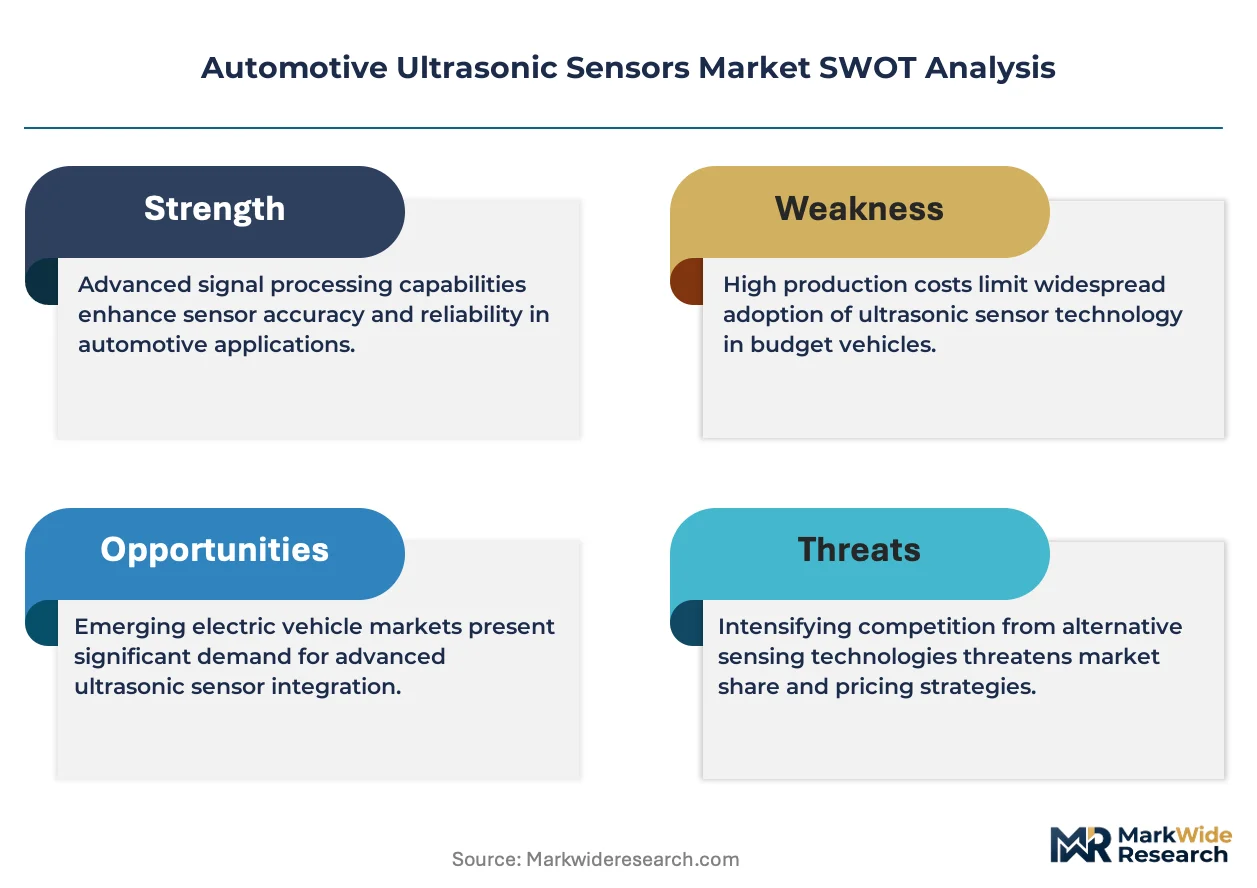
Sensor fusion architectures are compressing standalone ultrasonic module margins as OEMs demand software-defined platforms capable of real-time data integration with radar and camera arrays. This structural shift favors suppliers with signal processing IP over pure hardware manufacturers.
Growth Catalysts
- EU General Safety Regulation:Mandates for intelligent speed assistance and reverse detection expand ultrasonic fitment across all new vehicle categories sold in member states.
- MEMS fabrication advances:Wafer-level packaging reduces unit costs while improving detection accuracy, accelerating displacement of legacy piezoelectric designs in parking assist applications.
- China's electric vehicle production:Domestic brands integrate ultrasonic arrays as standard equipment across price tiers, creating concentrated demand for localized supply chains.
Market Restraints
- Piezoelectric ceramic supply:Lead zirconate titanate feedstock faces ECHA scrutiny under REACH substance restrictions, forcing qualification of alternative compositions.
- LiDAR cost curves:Solid-state optical sensors approach ultrasonic price points for short-range applications, threatening displacement in premium vehicle segments.
- Semiconductor foundry concentration:MEMS sensor ASIC fabrication depends on Taiwan and South Korea capacity, exposing supply continuity to geopolitical friction.
Strategic Opportunities
- India's PLI scheme for auto components:Localized sensor manufacturing incentives attract module assembly investments serving domestic and export markets.
- Vehicle-to-infrastructure integration:Ultrasonic arrays paired with V2X communication modules enable cooperative parking systems in smart city deployments.
- Aftermarket retrofit demand:Aging vehicle fleets in Eastern Europe and Southeast Asia create replacement sensor markets outside OEM channels.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL ratings for parking assist systems extend validation timelines by 8-14 months.
- Signal processing talent scarcity:Shortage of embedded software engineers with acoustic DSP expertise constrains R&D throughput at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ultrasonic Sensors Market |
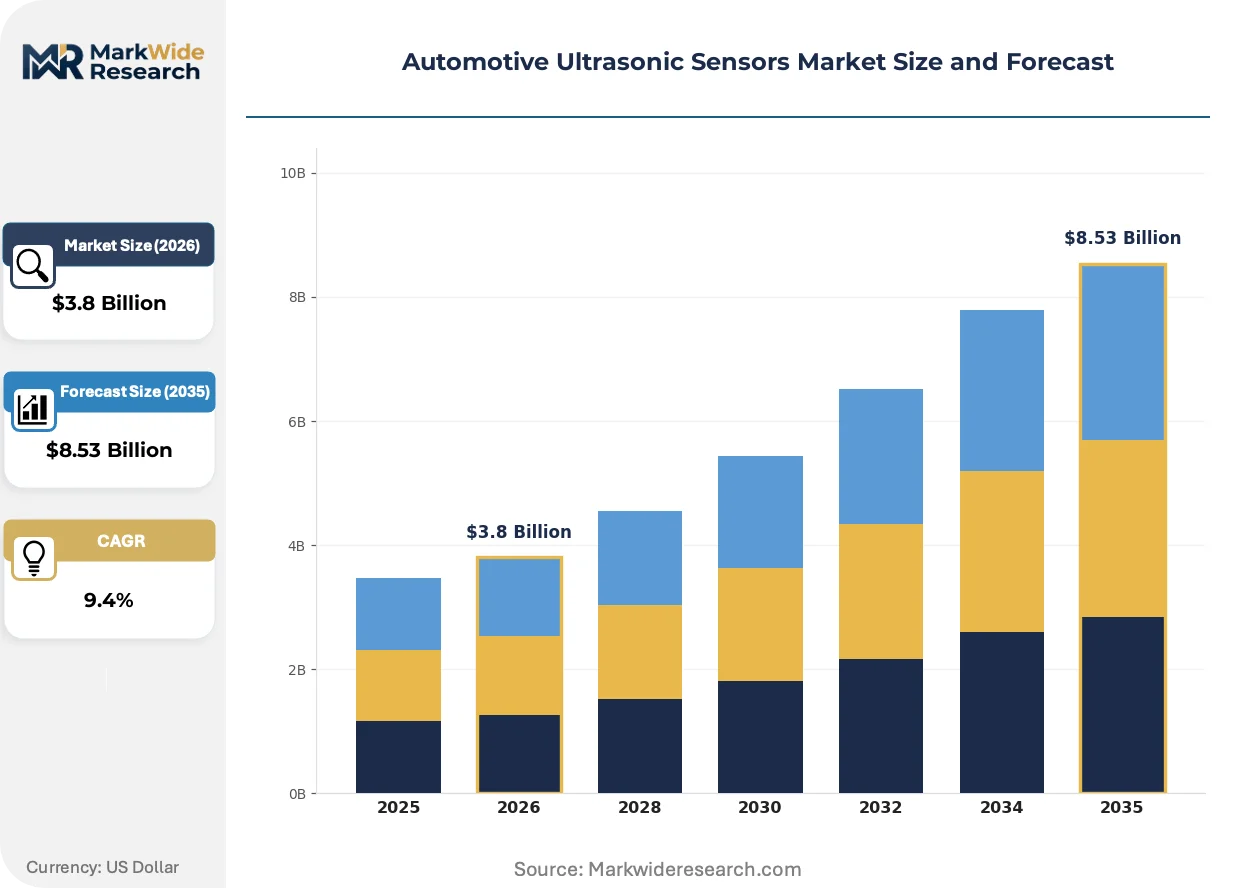
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parking Assist Sensors, Blind Spot Detection Sensors, Collision Avoidance Sensors, Distance Measurement Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Analog Sensors, Digital Sensors, MEMS Sensors, Multi-channel Sensors Installation Type: Embedded Sensors, Retrofitted Sensors, Integrated Sensors, External Sensors |
| Companies Covered | TE Connectivity, VALEO, Continental AG, Elmos Semiconductor SE, Infineon Technologies AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Hyundai Mobis, DENSO CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ultrasonic Sensors Market Emerging Trajectories
Automotive ultrasonic sensing is transitioning from discrete hardware components to integrated perception subsystems. This transformation compresses supplier margins while opening new value pools in software licensing and calibration services.
Digital signal processing architectures are modularizing ultrasonic sensor functionality into reprogrammable platforms. Tier-1 suppliers embed FPGA-based processing cores that OEMs reconfigure via over-the-air updates. This flexibility reduces hardware revision cycles from 18 months to 6 months. The technology is modularizing competitive differentiation around software stacks rather than transducer specifications.
NHTSA's automatic emergency braking mandate for light trucks and passenger vehicles expands ultrasonic sensor duty cycles beyond parking into low-speed collision mitigation. Manufacturers must recalibrate detection algorithms for pedestrian and cyclist recognition. The regulation most affects compact vehicle segments where cost constraints previously limited sensor counts.
Fleet operators now specify sensor performance through uptime guarantees rather than hardware specifications. Logistics companies contract for parking damage reduction outcomes, transferring operational risk to technology suppliers. This model is most visible in North American last-mile delivery fleets where insurance premiums drive specification decisions.
Automotive Ultrasonic Sensors Market Segmentation
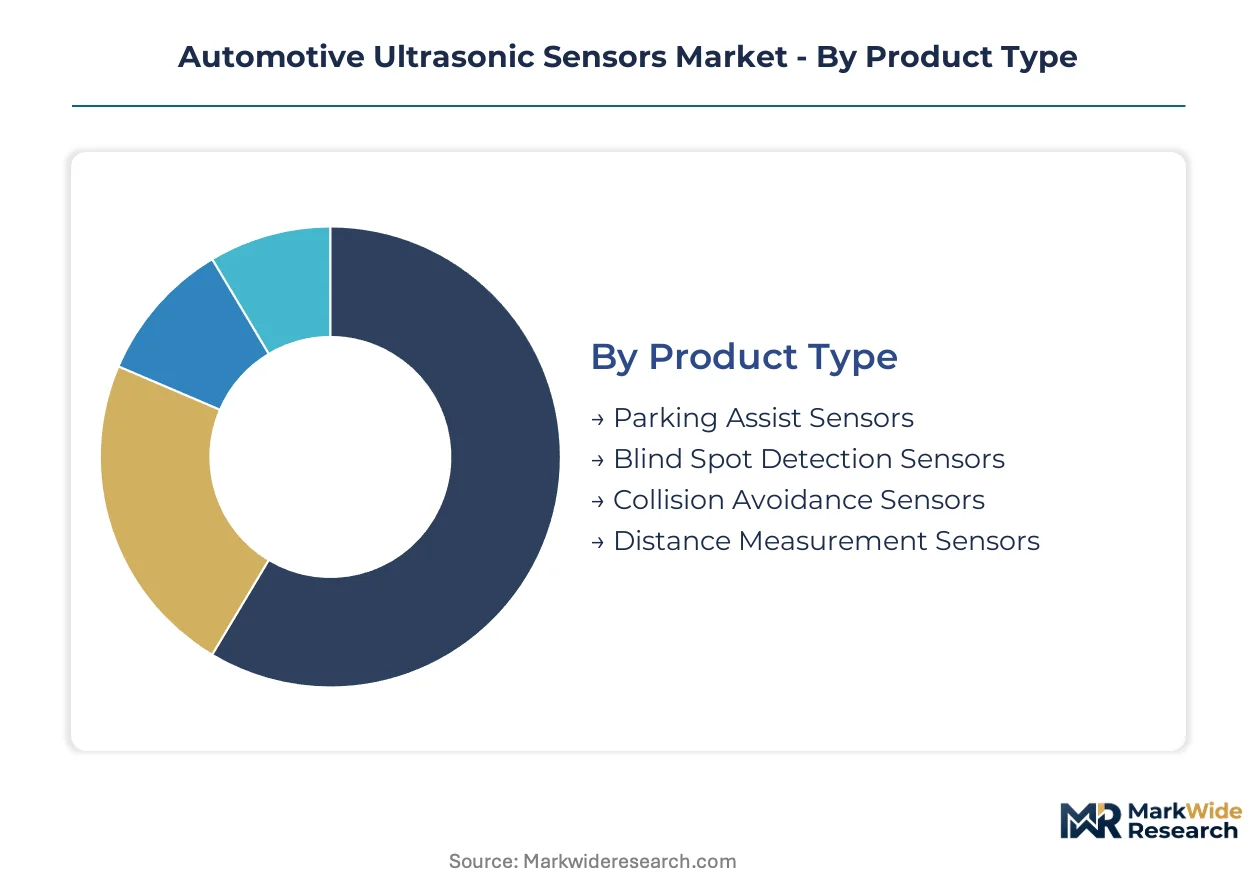
Automotive ultrasonic sensor procurement decisions cascade through four distinct lenses: vehicle integration depth, supply chain position, signal processing architecture, and physical mounting configuration. Each segmentation axis reveals divergent margin structures and qualification barriers.
Product Type:
Purchase volume concentrates where regulatory mandates intersect with mass-market vehicle economics.
- Parking Assist Sensors:Standard fitment across economy through luxury segments calculates object distance via 40-58 kHz time-of-flight measurement for low-speed maneuvering. China MIIT GB standards and EU General Safety Regulation mandate reverse detection, cementing this segment's installed base dominance across domestic electric vehicle brands and European OEM platforms.
- Blind Spot Detection Sensors:Higher-frequency variants operating at 58 kHz enable side-object monitoring during lane changes. Demand concentrates in premium vehicle segments where NHTSA visibility standards and insurance premium reductions justify per-vehicle sensor counts exceeding parking-only configurations.
- Collision Avoidance Sensors:Fusion-ready units with sub-10cm accuracy for automatic emergency braking integration.
- Distance Measurement Sensors:Specialized units for adaptive cruise support and trailer hitch alignment.
Parking assist sensors lead on scale; blind spot detection sensors lead on momentum as NCAP rating schemes expand side-impact protection weightings.
End User:
Supply chain position determines specification authority and margin capture.
- OEMs:Vehicle manufacturers consolidate procurement under centralized ADAS platforms, demanding software-defined sensor modules capable of over-the-air algorithm updates. Direct OEM contracts favor suppliers with integrated signal processing IP and ISO 26262 ASIL certification capabilities.
- Tier-1 Suppliers:Chassis systems integrators bundle ultrasonic modules with radar and camera suites for platform-level supply to multiple OEMs. Continental AG and Robert Bosch GmbH leverage this channel to anchor European supply through captive semiconductor partnerships.
- Aftermarket Providers:Retrofit specialists serve aging vehicle fleets in Eastern Europe and Southeast Asia where OEM sensor replacement costs exceed third-party alternatives.
- Vehicle Assemblers:Contract manufacturers in China and India source localized sensor modules to satisfy domestic production quota requirements.
OEMs lead on scale; Tier-1 suppliers lead on momentum as platform consolidation accelerates.
Technology:
Architecture selection trades unit cost against detection resolution and reprogrammability.
- MEMS Sensors:Wafer-level packaging reduces unit costs while improving detection accuracy through microelectromechanical transducer arrays. China's electric vehicle production lines specify MEMS as standard equipment across price tiers, displacing legacy piezoelectric designs in next-generation platform development.
- Digital Sensors:FPGA-based processing cores enable OEM reconfiguration via over-the-air updates, compressing hardware revision cycles from 18 months to 6 months. The technology modularizes competitive differentiation around software stacks rather than transducer specifications.
- Analog Sensors:Legacy piezoelectric architectures with fixed detection algorithms and lower bill-of-materials cost.
- Multi-channel Sensors:Array configurations enabling simultaneous multiple-object tracking for advanced parking assistance.
Analog sensors lead on scale; MEMS sensors gain share fastest as fabrication advances accelerate displacement curves.
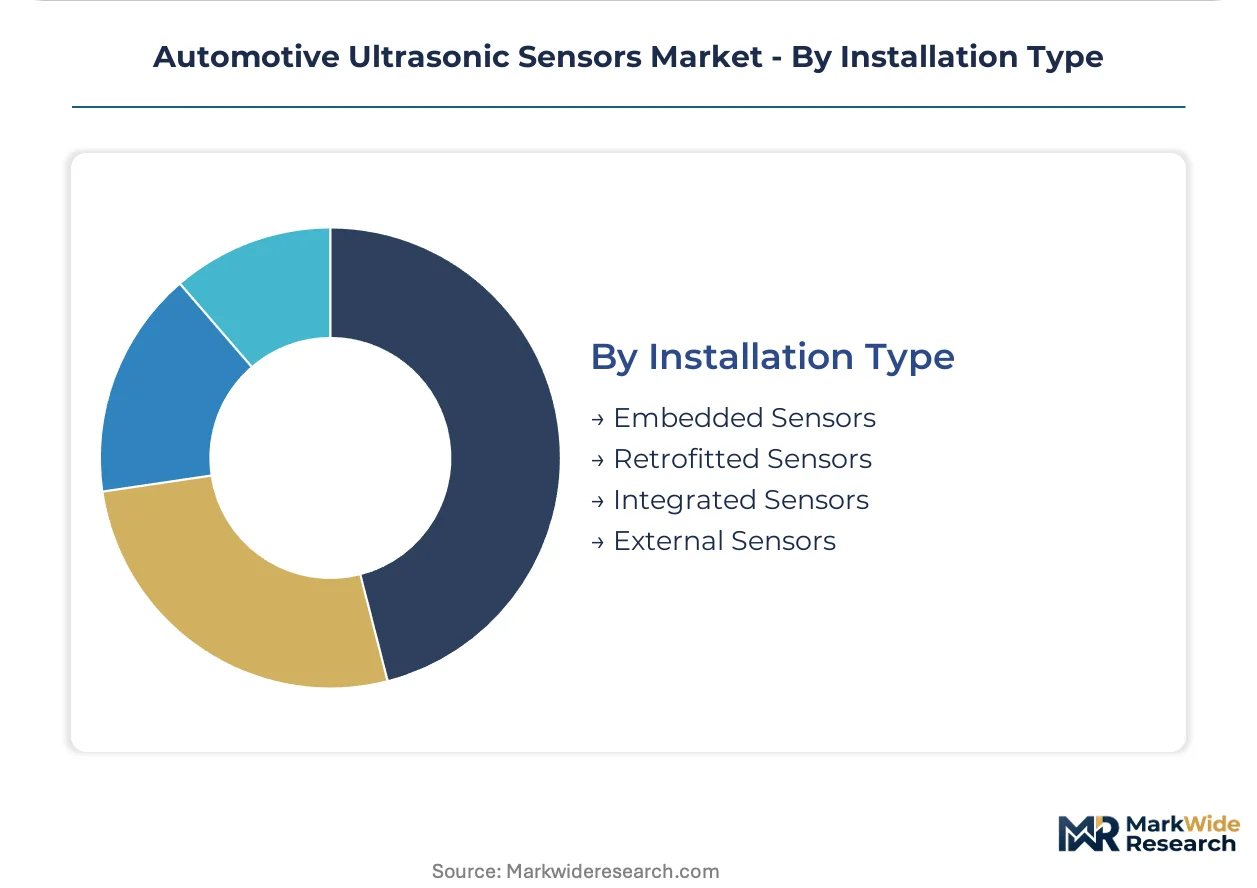
Installation Type:
Physical integration depth determines environmental sealing requirements and calibration complexity.
- Embedded Sensors:Factory-integrated units mounted behind bumper fascias with permanent wiring harness connections. OEMs specify embedded configurations for new vehicle platforms where electromagnetic compatibility validation occurs at the chassis-system level.
- Integrated Sensors:Module-in-module designs fused with lighting assemblies or license plate housings. VALEO competes aggressively in this segment through China-based production facilities serving domestic electric vehicle brands with combined sensor-lighting units.
- Retrofitted Sensors:Aftermarket add-on kits with wireless or simplified wired connections for vehicle fleet upgrades.
- External Sensors:Exposed-mount units for commercial vehicle applications requiring frequent replacement access.
Embedded sensors lead on scale; integrated sensors lead on momentum as module consolidation reduces assembly line complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic sensor engineering talent clusters in Stuttgart, Shanghai, and Detroit anchor regional production networks. These workforce concentrations shape where OEMs locate ADAS integration facilities and where suppliers establish MEMS fabrication partnerships.
United States
NHTSA mandates for automatic emergency braking and rear visibility standards drive ultrasonic sensor fitment across light truck and passenger vehicle platforms. The Department of Transportation enforces FMVSS 111 rearview camera requirements that cascade into parking assist sensor procurement. Michigan's automotive corridor hosts Tier-1 integration facilities where Continental AG and Robert Bosch GmbH anchor North American supply chains.
Germany
KBA vehicle type approval processes and EU General Safety Regulation mandates accelerate intelligent speed assistance integration across domestic OEM platforms. ECHA REACH restrictions on lead zirconate titanate ceramics force material qualification timelines that favor established suppliers with alternative piezoelectric compositions. Baden-Württemberg's precision engineering cluster concentrates MEMS foundry partnerships and acoustic R&D facilities.
China
MIIT GB standards for intelligent connected vehicle components create certification barriers that favor domestic electric vehicle brands specifying localized sensor modules. Dual carbon goals under the 14th Five-Year Plan accelerate electrification platforms where ultrasonic arrays serve as standard equipment. Yangtze River Delta manufacturing hubs host VALEO production facilities serving BYD, NIO, and XPeng with integrated sensor-lighting units.
Japan
METI industrial policy supports autonomous driving R&D consortia that specify fusion-ready ultrasonic modules for next-generation vehicle platforms. JIS standards for automotive electromagnetic compatibility require validation protocols that extend supplier qualification cycles. Toyota City and Nagoya automotive clusters concentrate DENSO CORPORATION integration facilities where Tier-1 suppliers coordinate sensor fusion architectures.
South Korea
MFDS automotive component safety frameworks align with NCAP rating schemes that expand side-impact protection weightings for blind spot detection sensors. Government-backed K-Semiconductor Belt initiatives strengthen domestic MEMS fabrication capacity for sensor ASIC production. Seoul Capital Area hosts Hyundai Mobis development centers where platform-level ADAS integration reduces per-vehicle sensor costs.
Automotive Ultrasonic Sensors Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value capture layers. The market exhibits tiered consolidation where chassis systems integrators bundle ultrasonic modules with multi-sensor suites, while semiconductor fabricators supply MEMS transducer components. Three archetypes dominate: integrated Tier-1 platform suppliers, captive semiconductor manufacturers, and specialized acoustic sensor engineers. Competitive moves center on backward integration into MEMS foundry capacity and strategic partnerships for software-defined signal processing IP.
Among European-based integrated suppliers, Continental AG and Robert Bosch GmbH occupy positions exemplifying platform-level bundling strategies. VALEO represents the geographic specialization archetype through China-focused production facilities. These three companies anchor distinct competitive vectors: chassis integration depth, captive semiconductor control, and regional manufacturing proximity to high-volume electric vehicle markets.
| Leading Market Players |
|---|
| TE Connectivity |
| VALEO |
| Continental AG |
| Elmos Semiconductor SE |
| Infineon Technologies AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| DENSO CORPORATION |
| Others |
Supply Flow & Price Mechanics
Lead zirconate titanate feedstock costs cascade through three distinct pricing tiers as wafer-level MEMS packaging displaces legacy piezoelectric architectures. OEM procurement consolidation under centralized ADAS platforms compresses module margins while elevating software-defined signal processing premiums.
Pricing Analysis
Hardware-software bundling separates pure transducer suppliers from integrated platform providers capable of over-the-air algorithm updates. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL certification grade and detection resolution specifications. Cost compression in economy-tier analog sensors intensifies as Chinese domestic brands standardize MEMS fitment across electric vehicle price tiers. Fleet operators exhibit lowest price sensitivity where uptime guarantees and insurance premium reductions justify premium-tier procurement.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundry capacity for MEMS sensor ASIC fabrication. Raw material dependencies span lead zirconate titanate ceramics, silicon wafers, and specialized acoustic encapsulation resins. Geopolitical friction around semiconductor manufacturing equipment exports represents the dominant structural risk. Distribution runs through Tier-1 chassis systems integrators bundling ultrasonic modules with radar and camera suites for platform-level OEM supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive ultrasonic sensors market functions as a stable compounder where regulatory mandate expansion for intelligent speed assistance and reverse detection creates predictable demand floors across vehicle production cycles.
For Market Incumbents: Hedge against LiDAR cost curve convergence by deepening software-defined signal processing IP and securing captive MEMS foundry partnerships. Solid-state optical sensors threaten displacement in premium segments where short-range detection accuracy specifications overlap. Backward integration into wafer-level packaging capacity anchors margin defense against pure-play hardware commoditization. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass entrenched Tier-1 supplier relationships in North American last-mile delivery segments where outcome-based contracting creates specification authority openings. Aftermarket retrofit demand in Eastern European aging vehicle fleets offers penetrable white-space with simplified calibration tooling. Target embedded software licensing models rather than hardware module manufacturing to avoid capital-intensive fabrication barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier suppliers lack ISO 26262 ASIL certification capabilities and embedded DSP engineering talent. Long-term viability favors platform-level integrators with multi-sensor fusion architectures and OEM direct relationships. Signal to watch: Tier-1 procurement contract durations shortening below 36 months indicating supplier switching flexibility and pricing pressure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Wafer-level packaging partnerships with Taiwan Semiconductor Manufacturing Company reduce unit costs while improving detection accuracy. |
| Software-Defined Sensor Platform | FPGA-based processing cores enable OEM reconfiguration via over-the-air updates compressing hardware revision cycles. |
| ASIL Certification Investment | ISO 26262 functional safety ratings extend qualification timelines but lock in premium-tier OEM procurement decisions. |
| China Localized Production | Yangtze River Delta manufacturing facilities satisfy MIIT GB standards and domestic electric vehicle brand procurement requirements. |
| Sensor Fusion Architecture Integration | Real-time data integration with radar and camera arrays creates platform-level bundling opportunities with chassis systems divisions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window combining primary discussions with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and MEMS foundry operations managers with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from diversified automotive suppliers, and ECHA REACH substance restriction updates. Bottom-up sensor unit volume estimates triangulated against top-down ADAS platform penetration forecasts.
Comparable historical periods anchored the projection horizon across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macro vehicle production forecasts and technology substitution curves for MEMS versus analog architectures. Industry-specific inputs included NHTSA mandate implementation timelines, EU General Safety Regulation phase-in schedules, and China MIIT GB standard certification trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state LiDAR cost reduction would alter the outlook. Forecasts reflect assumptions around semiconductor foundry capacity expansion, piezoelectric ceramic material qualification timelines, and OEM platform consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market