
 Veggie Chips Market | 2026-2036
Veggie Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Veggie Chips Market Analytics
Buyer concentration among health-conscious consumers is shifting from mass-market snack purchasers toward specialized wellness-oriented shoppers seeking functional ingredients. PepsiCo leverages its Bare Snacks portfolio to control premium shelf space in conventional retail. The Hain Celestial Group anchors the organic segment through Terra Chips and Sensible Portions, while Calbee North America competes on Japanese-inspired flavor innovation and manufacturing scale.
Veggie chips are thin-sliced or extruded snack products produced from root vegetables, leafy greens, or squash varieties, typically dehydrated or kettle-cooked at temperatures between 300°F and 375°F to achieve crisp texture while preserving fiber and micronutrient content. Their primary commercial purpose is to deliver permissible indulgence for consumers avoiding potato-based or grain-based snacks. Sweet Potato Chips dominate volume due to established consumer familiarity and lower raw material volatility, while Kale Chips capture the highest margin pool among health-food-store buyers despite smaller throughput. Online Retailers represent the fastest-growing distribution channel, though Supermarkets sustain the bulk of absolute revenue.
The FDA governs nutrition labeling and health claims for veggie chip products sold in the United States, while the USDA oversees organic certification requirements that many premium brands pursue. The EU Green Deal and REACH chemical safety standards shape export eligibility and packaging material selection for manufacturers targeting European markets. Stakeholders must monitor evolving clean-label enforcement and alternative-protein snack competition to preserve pricing power and shelf positioning.
Market Dynamics
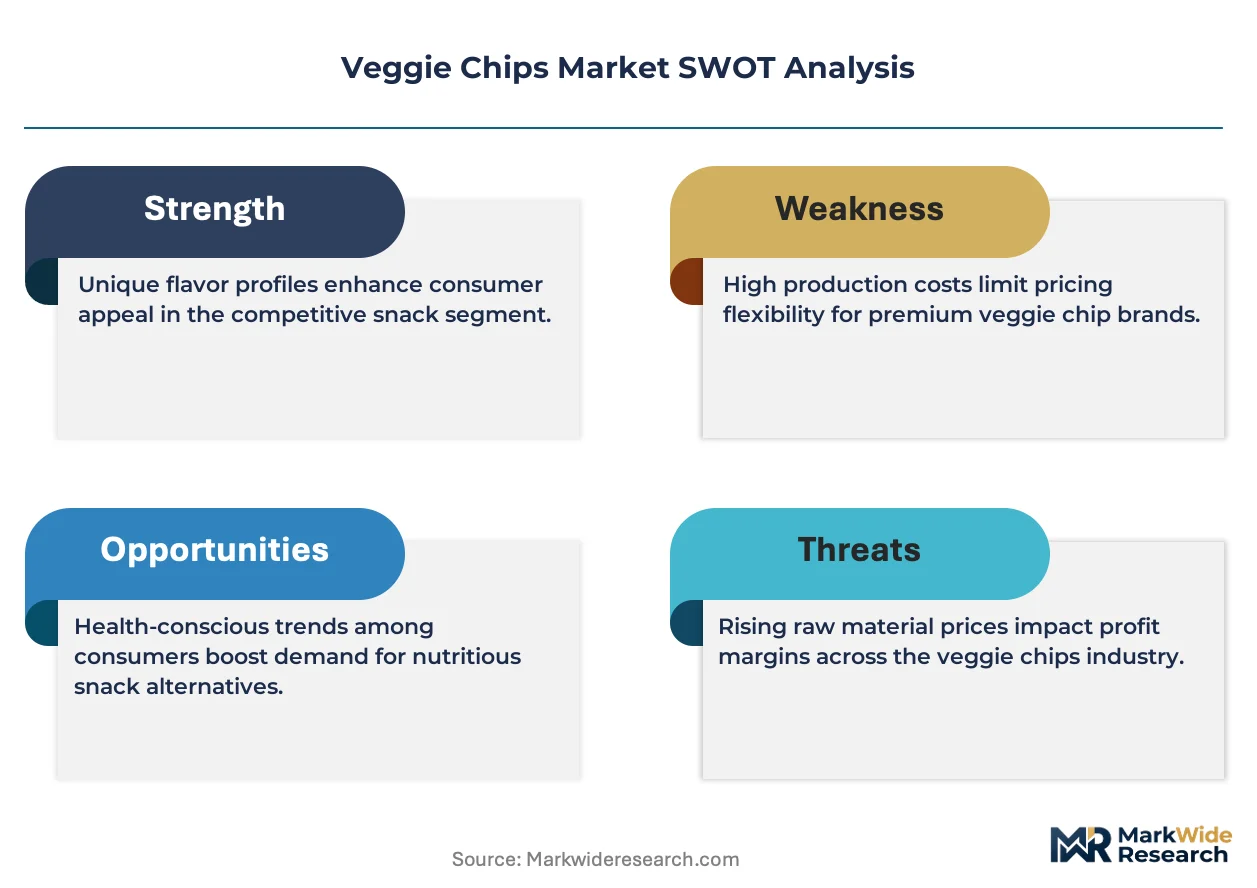
Clean-label enforcement by the FDA and USDA is compressing formulation timelines for veggie chip manufacturers while simultaneously opening premium shelf space for compliant brands. This regulatory pressure acts as the dominant structural force, filtering out commodity players and rewarding those with certified supply chains and transparent ingredient sourcing.
Growth Catalysts
- USDA Organic Certification:Federal organic standards enable price premiums of 20-40% above conventional alternatives, attracting capital investment into certified processing facilities across the Midwest and Pacific Northwest.
- Extrusion Technology Advances:Twin-screw extrusion systems now achieve 40% higher throughput than batch kettle methods, reducing unit costs for root-vegetable-based products while maintaining texture integrity.
- Health-Conscious Consumer Concentration:Wellness-oriented shoppers in metropolitan clusters demonstrate willingness to pay functional-ingredient premiums, concentrating demand in coastal urban markets.
Market Restraints
- Input Cost Volatility:Sweet potato and beet prices fluctuate with drought cycles in California and Texas growing regions, compressing margins for non-vertically integrated processors.
- Supply Concentration Risk:Domestic kale sourcing concentrates among three Central Coast growers, creating vulnerability to regional climate events and contract renegotiation.
- Regulatory Friction:The FDA's evolving definition of "healthy" claims creates compliance uncertainty, delaying new product launches and requiring legal review cycles.
Strategic Opportunities
- Underpenetrated Heartland Markets:Secondary metropolitan areas in Ohio, Indiana, and Missouri show rising scanner data for better-for-you snacks but limited premium veggie chip distribution.
- Functional Ingredient Convergence:Probiotic coating technology combined with vegetable substrates creates dual-claim products targeting gut-health seekers.
- Direct-to-Consumer Channel Innovation:Subscription snack boxes and brand-owned e-commerce bypass slotting-fee barriers in conventional retail, capturing full margin on repeat purchases.
Industry Challenges
- Specialized Equipment Talent Gap:Operators capable of calibrating low-temperature dehydration systems for nutrient preservation remain scarce, extending commissioning timelines for new production lines.
- Organic Certification Timeline:The three-year land-conversion requirement for USDA organic status blocks rapid scaling of certified raw material supply.
- Co-Packer Integration Complexity:Brands relying on third-party manufacturing face coordination friction between formulation R&D and production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veggie Chips Market |
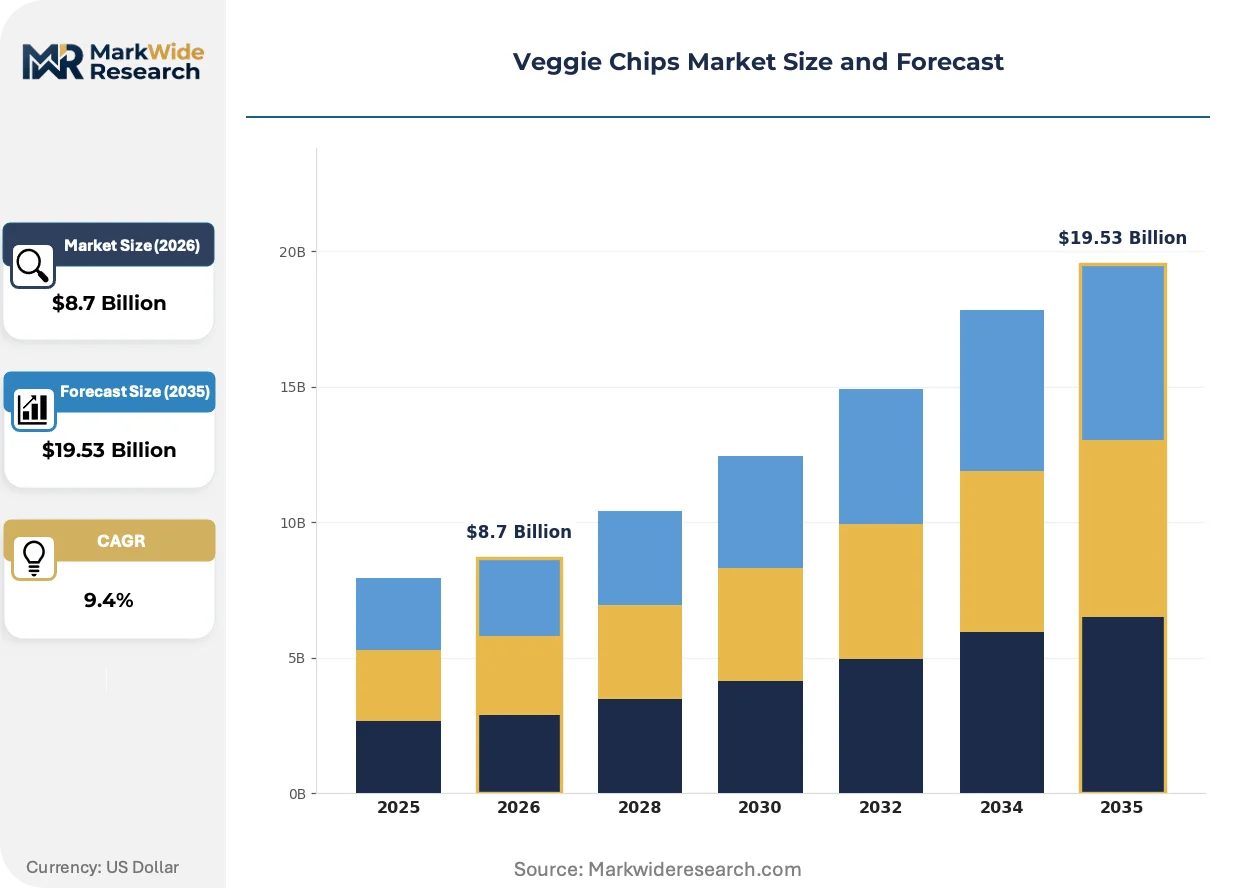
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Potato Chips, Kale Chips, Beetroot Chips, Zucchini Chips Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores End User: Health-Conscious Consumers, Snack Enthusiasts, Vegetarians, Gluten-Free Dieters Packaging Type: Bags, Pouches, Jars, Boxes |
| Companies Covered | PepsiCo (Bare Snacks), Calbee North America, The Hain Celestial Group (Terra Chips, Sensible Portions), General Mills, Kellanova, Rhythm Superfoods, Utz Brands (Good Health), Simply 7 Snacks, Luke's Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veggie Chips Market Evolving Landscape
Vacuum frying technology is rewriting cost structures and nutritional retention benchmarks across the veggie chip category. Manufacturers adopting this approach gain operational advantages that reshape competitive positioning.
Low-temperature vacuum frying at 250-280°F is rewriting oil absorption profiles and vitamin retention in finished products. Health-food retailers and premium conventional grocers are accelerating adoption of vacuum-fried SKUs to meet clean-label procurement criteria. This technology is compressing the performance gap between indulgent texture and nutritional credibility, forcing legacy kettle-cooked lines into price-competitive segments.
The FDA's updated Nutrition Facts labeling requirements mandate added-sugar disclosure and revised serving-size definitions for snack products. Manufacturers must reformulate or relabel portfolios, with sweet potato chip lines most affected due to naturally occurring sugar concentration. Brands are responding by emphasizing fiber and potassium content in revised packaging claims to maintain permissible-indulgence positioning.
Subscription-based snack procurement is disrupting conventional replenishment patterns among millennial and Gen Z households. Direct-to-consumer channels are displacing impulse purchases in brick-and-mortar environments, particularly for functional-ingredient variants. This shift concentrates most visibly in coastal urban markets where delivery infrastructure and wellness-media influence intersect.
Veggie Chips Market Segmentation
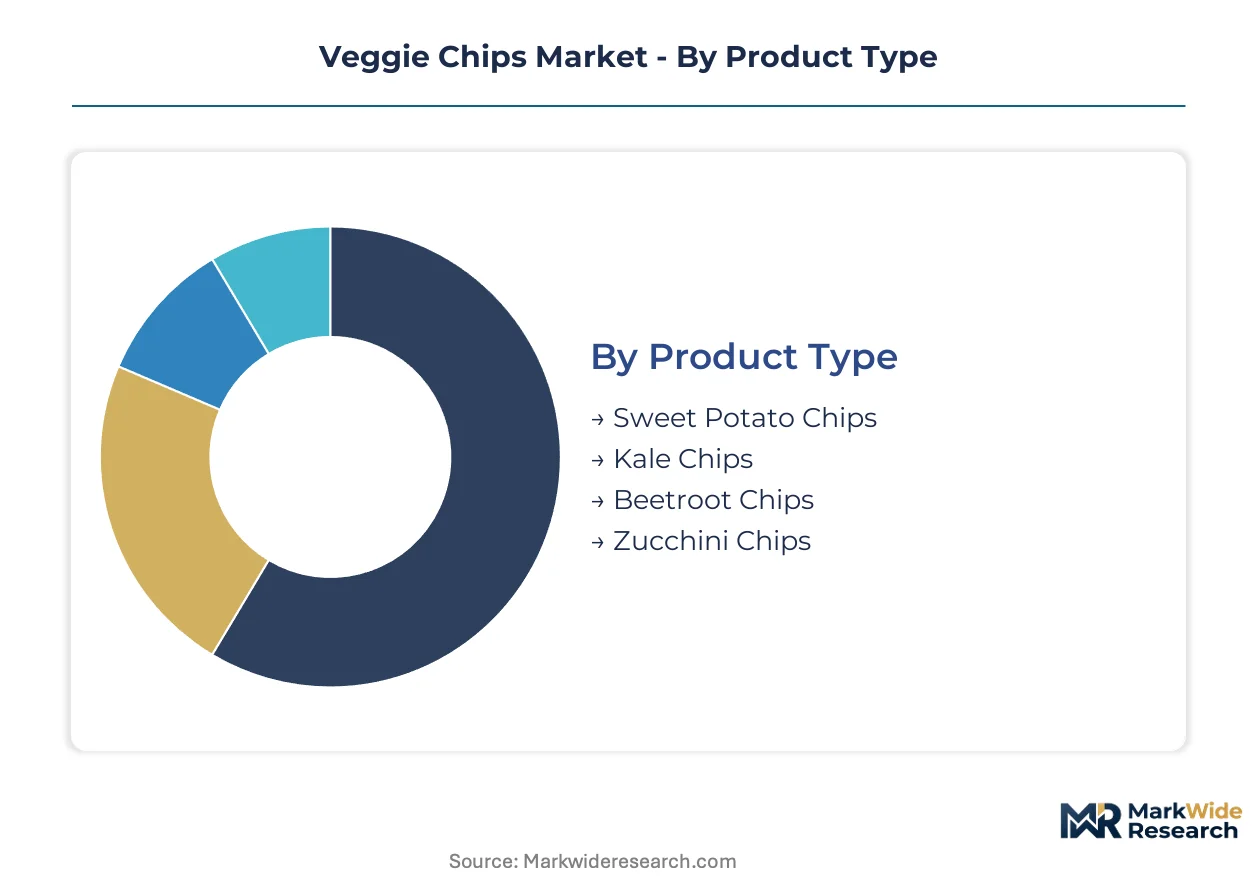
Veggie chip manufacturers configure production assets around distinct technical requirements and margin profiles. Each segment demands specialized processing equipment, from kettle cookers to vacuum fryers, shaping capital deployment decisions.
Product Type:
Capital intensity varies sharply across root vegetables versus leafy substrates, with dehydration systems requiring precision temperature control for nutrient preservation.
- Sweet Potato Chips:Sliced orange-fleshed tubers processed at 300-375°F deliver familiar crunch with elevated fiber and beta-carotene content. Demand concentrates in conventional retail channels across the United States and Canada, where permissible-indulgence positioning justifies premium shelf placement.
- Kale Chips:Low-temperature dehydration at sub-200°F preserves chlorophyll and vitamin K in curly or lacinato varieties. Health-food-store buyers in coastal metropolitan clusters drive the highest margin pool, though throughput remains constrained by batch processing limitations.
- Beetroot Chips:Earthy root slices with natural sugar concentration requiring careful moisture management during frying.
- Zucchini Chips:Summer squash rounds with high water content demanding extended dehydration cycles.
Sweet Potato Chips absorb the bulk of installed capacity; Kale Chips are expanding most quickly.
Distribution Channel:
Channel selection determines working capital requirements, with slotting fees and inventory turns varying dramatically between brick-and-mortar and digital fulfillment.
- Supermarkets:Conventional grocers command the largest absolute revenue share through high-velocity replenishment and impulse placement at checkout. Scanner data from Kroger and Albertsons banners in the Midwest and Pacific Northwest indicates sustained volume leadership despite slower growth rates.
- Online Retailers:Amazon and Thrive Market capture wellness-oriented households seeking subscription convenience and functional ingredient transparency. Direct-to-consumer velocity is climbing the fastest among millennial and Gen Z purchasers in metropolitan clusters.
- Health Food Stores:Specialty retailers like Whole Foods and Sprouts emphasize certified organic and clean-label procurement criteria.
- Convenience Stores:C-store distribution requires single-serve packaging formats and higher wholesale margins.
Supermarkets retain the dominant revenue position; Online Retailers show the steepest expansion trajectory.
End User:
User segmentation maps directly to formulation complexity, with functional ingredient premiums justified by distinct nutritional priorities.
- Health-Conscious Consumers:Wellness-focused shoppers prioritize fiber content, low sodium, and recognizable ingredient lists. Demand clusters in coastal urban markets where clean-label media influence and disposable income intersect.
- Snack Enthusiasts:Taste-driven purchasers seek bold flavor profiles and textural satisfaction without dietary restriction framing.
- Vegetarians:Plant-based adherents use veggie chips as protein-complementary snacking options.
- Gluten-Free Dieters:Celiac and sensitivity-driven buyers require certified gluten-free processing facilities.
Health-Conscious Consumers command the highest per-unit margins; Gluten-Free Dieters are gaining share fastest as certification standards tighten.
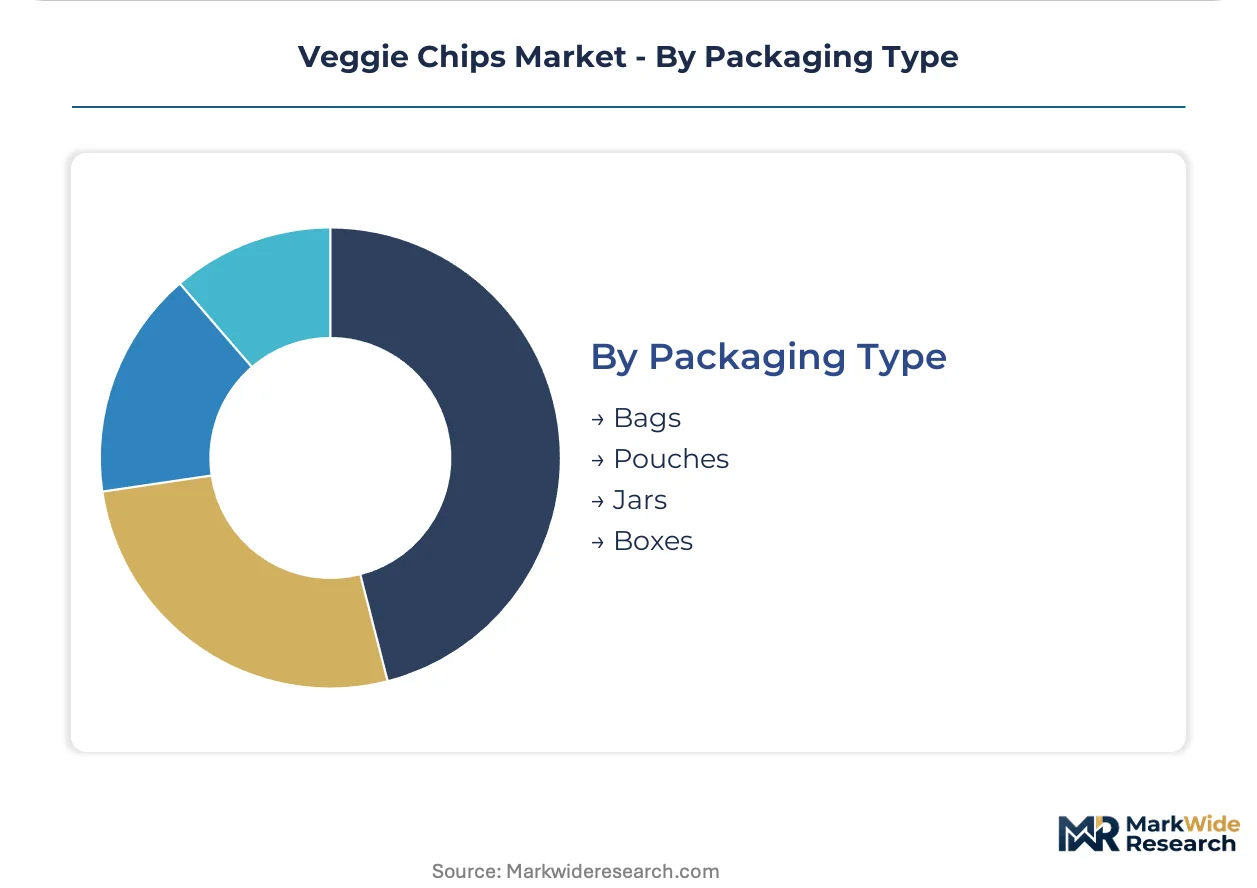
Packaging Type:
Packaging equipment investments range from form-fill-seal lines for flexible films to rigid container handling systems with modified atmosphere capabilities.
- Bags:Traditional pillow pouches dominate mass-market velocity with lowest unit cost and established supply chains.
- Pouches:Stand-up and resealable formats justify premium positioning through convenience and shelf stability.
- Jars:Rigid containers target gift and specialty channels with visual product display.
- Boxes:Multipack cartons serve club store and e-commerce bulk fulfillment requirements.
Bags carry the highest production volume; Pouches are expanding most quickly as resealability becomes standard expectation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellness-oriented households concentrate in coastal metropolitan clusters, with demand radiating inward through premium grocery expansion and e-commerce penetration into secondary markets.
United States
Health-conscious consumers in New York and Los Angeles drive premium positioning through clean-label procurement at Whole Foods and Sprouts. The FDA's updated Nutrition Facts labeling requirements mandate added-sugar disclosure, compressing formulation timelines for sweet potato chip lines. Pacific Northwest processing facilities in Oregon and Washington expand certified organic capacity to serve West Coast distribution networks.
Canada
Metropolitan Toronto and Vancouver anchor demand through diverse retail channels emphasizing permissible indulgence. Health Canada and the PMRA oversee organic certification alignment with USDA standards, enabling cross-border supply chain integration. Alberta's agricultural processing corridor attracts capital for root-vegetable dehydration infrastructure serving North American export markets.
Germany
Discerning shoppers in Berlin and Munich prioritize EU organic certification and REACH-compliant packaging materials. The EU Green Deal shapes manufacturer eligibility through chemical safety and sustainability procurement criteria. Bavaria's food technology cluster advances vacuum frying equipment for reduced oil absorption in finished products.
United Kingdom
London's wellness media influence and subscription snack box penetration accelerate direct-to-consumer velocity. The Food Standards Agency enforces nutrition labeling harmonized with post-Brexit regulatory frameworks. Southeast England distribution hubs coordinate European export logistics for premium vegetable-based snack portfolios.
Japan
Tokyo and Osaka metropolitan areas demonstrate strong uptake for functional ingredient combinations and portion-controlled formats. METI standards govern food manufacturing equipment specifications and quality assurance protocols. The Kansai region's processed food expertise supports flavor innovation pipelines for Asian export markets.
Veggie Chips Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional ingredient specialization and direct-to-consumer channel development. The vendor base stratifies across multinational snack conglomerates with diversified portfolios, mid-cap organic specialists with certified supply chains, and venture-backed innovators targeting subscription commerce. Three archetypes dominate: scale-driven mass-market suppliers, premium organic certifiers, and technology-forward niche formulators. Competitive moves concentrate on portfolio diversification into adjacent better-for-you categories and strategic partnerships with co-manufacturing facilities to bypass capital-intensive equipment investments.
Within the multinational tier, PepsiCo and Calbee North America exemplify scale-driven positioning through diversified snack portfolios and established retail relationships. The Hain Celestial Group occupies a distinct archetype as a premium organic certifier with specialized brand architecture. These three entities anchor competitive dynamics through contrasting approaches to shelf space acquisition, supply chain certification, and flavor innovation pipelines.
| Leading Market Players |
|---|
| PepsiCo (Bare Snacks) |
| Calbee North America |
| The Hain Celestial Group (Terra Chips, Sensible Portions) |
| General Mills |
| Kellanova |
| Rhythm Superfoods |
| Utz Brands (Good Health) |
| Simply 7 Snacks |
| Luke's Organic |
| Others |
Value Network & Pricing Analysis
Backward integration into sweet potato cultivation anchors both supply security and margin defense for processors operating in California and Texas growing regions. This upstream control insulates against raw material volatility while supporting premium positioning in conventional retail channels.
Pricing Analysis
Volume concentrates in mass-market sweet potato SKUs while margin pools accrue to kale chip lines targeting health-food-store buyers. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels reflects certification grade and channel positioning. Cost compression in the economy tier is intensifying because of co-packer consolidation and slotting-fee escalation at conventional grocers. Snack enthusiasts demonstrate highest price sensitivity; health-conscious consumers in coastal metropolitan clusters show lowest elasticity.
Supply Chain Analysis
Freight cost escalation from Central Coast kale growers to Midwest distribution centers is reshourcing decisions for organic processors. Raw material supply draws from California sweet potato fields, Texas beet cultivation, and Pacific Northwest dehydration facilities. Single-source vulnerability concentrates among three Central Coast kale growers exposed to regional drought cycles. Distribution runs through direct-to-consumer subscription channels and conventional supermarket replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive supply of certified organic raw materials determines shelf positioning and pricing power. Players are pursuing backward control over dehydration infrastructure and organic acreage conversion.
For Market Incumbents: Deploy vacuum frying technology upgrades to compress oil absorption and extend clean-label credibility. Acquire certified organic processing capacity in Oregon and Washington to lock in West Coast distribution access. Defend against emerging functional-ingredient specialists by accelerating probiotic coating R&D pipelines.
For New Entrants and Emerging Players: Begin with underpenetrated secondary metropolitan markets in Ohio, Indiana, and Missouri where scanner data shows rising better-for-you snack velocity but limited premium veggie chip distribution. Target subscription snack box partnerships as the most penetrable channel for bypassing slotting-fee barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational snack conglomerates seeking organic certification capabilities and direct-to-consumer infrastructure. Long-term viability hinges on defensible supply chain positioning and brand equity in wellness-oriented consumer segments. Watch FDA enforcement actions on "healthy" claim definitions as the critical inflection signal for portfolio repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA organic status enables price premiums and shelf placement at Whole Foods and Sprouts. |
| Vacuum Frying Technology Deployment | Low-temperature processing reduces oil absorption and meets clean-label procurement criteria. |
| Direct-to-Consumer Channel Launch | Subscription boxes bypass slotting fees and capture full margin on repeat purchases. |
| Functional Ingredient Convergence | Probiotic coating technology creates dual-claim products targeting gut-health seekers. |
| Heartland Distribution Expansion | Secondary metropolitan markets in Ohio and Indiana show rising scanner velocity with limited premium penetration. |
Research Methodology
Document review covered FDA labeling guidance, USDA organic certification standards, and Nielsen retail audit data, complemented by interviews with brand managers at leading processors, category buyers at conventional grocers, supply planners at co-manufacturing facilities, and R&D directors at dehydration equipment suppliers. Secondary sources included customs records, SEC filings, and trade association reports. Bottom-up volume estimates triangulated against top-down category sizing.
Historical shipment data cross-referenced against panel input from industry participants shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user archetype, and packaging format. CAGRs derived from trend extrapolation adjusted for regulatory enforcement timelines and technology adoption curves. Forecast inputs incorporated organic acreage conversion rates and vacuum frying equipment deployment schedules.
Underlying measurement precision varies by segment; online retailer velocity and health-food-store throughput carry tighter precision than emerging direct-to-consumer subscription data. Forecasts reflect assumptions about clean-label enforcement continuity and input cost stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Sodium Snacks Market
Snacks
North America Snack Bar Market
Snacks
Snacks Market
Snacks
Snack Bar Market
Snacks
Baked Savoury Snacks Market
Snacks
Dairy Protein Crisps Market
Snacks
France Energy Bar Market
Snacks
Super Low Calorie Snacks Market
Snacks
North America Savory Snacks Market
Snacks
Energy Balls Market
Snacks
Packaged Rice Snacks Market
Snacks
Germany Snack Bar Market
Snacks
High Carb Low Fat Snack Market
Snacks
Snack Pellets Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Edible Flakes Market