
 North America Snack Bar Market | 2026-2036
North America Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Snack Bar Market Insights
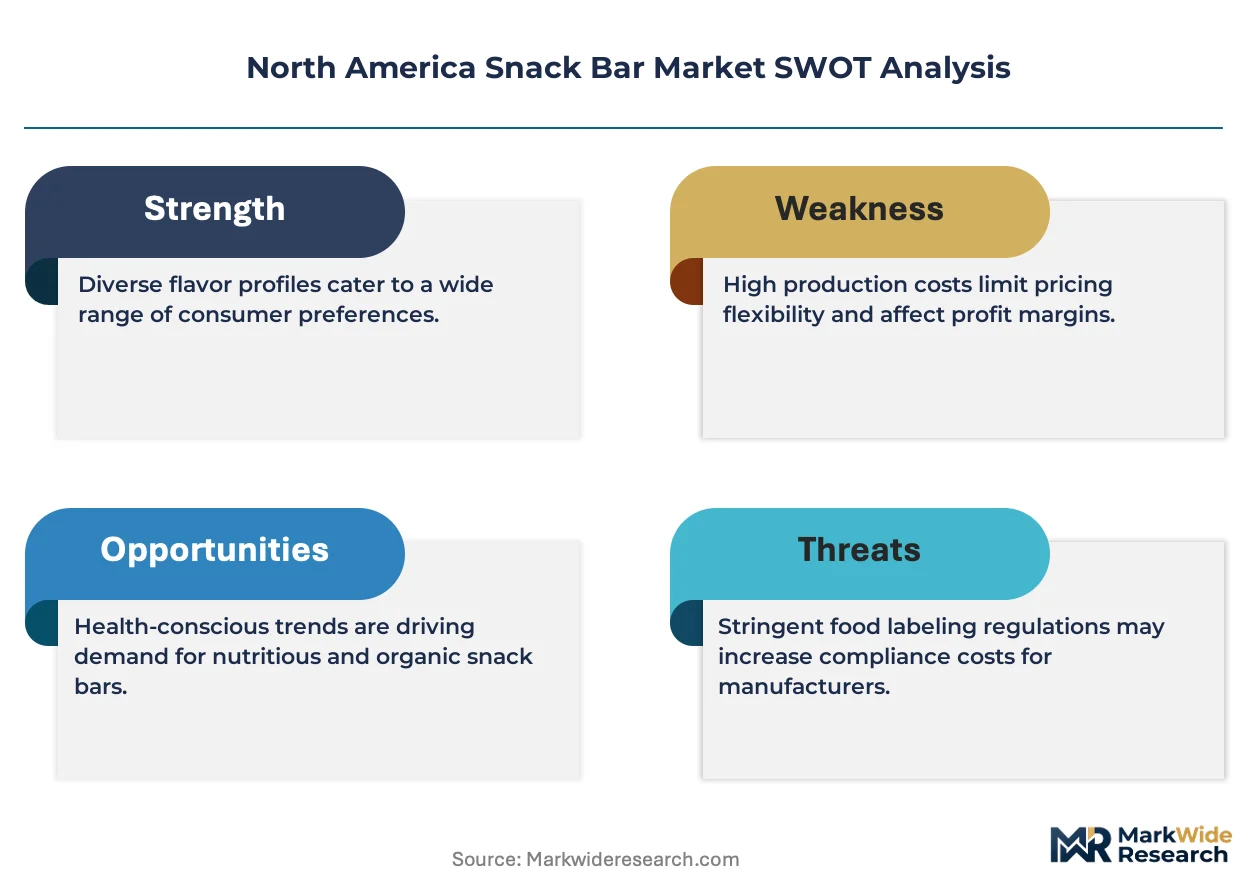
The FDA's updated Nutrition Facts panel, which mandates added sugars disclosure, is broadening reformulation activity across the North America Snack Bar Market. General Mills leverages its cereal-to-bar ingredient pipeline to control input costs and accelerate clean-label development. Mondelez International sustains its competitive edge through chocolate-coating expertise and impulse-channel distribution density. Clif Bar & Company anchors the organic and plant-based positioning that commands shelf-space premiums in natural retail.
A snack bar is a shelf-stable, extruded or cold-pressed bar typically comprising grains, proteins, sweeteners, and binders, designed to deliver macronutrient density in a portable format for on-the-go consumption. Protein Bars command the largest revenue share due to gym-culture penetration and sports-nutrition crossover, while Fruit Bars exhibit the fastest growth trajectory as no-added-sugar claims resonate with parental purchasers. The Ingredient Type dimension shows Gluten-Free and Low-Sugar variants capturing margin pools as specialty diets expand beyond celiac and diabetic populations into mainstream wellness positioning.
The USDA's National Organic Program and Canada's CFIA organic standards govern certification requirements that determine premium pricing eligibility and cross-border market access. FDA Good Manufacturing Practices and Health Canada's Safe Food for Canadians Regulations enforce allergen controls and label accuracy that shape production infrastructure investments. Stakeholders must monitor evolving state-level sugar-tax proposals and provincial packaging regulations that could fragment compliance costs across the US-Canada trade corridor.
Market Dynamics
The FDA's added-sugar disclosure mandate is compressing formulation timelines across the North America Snack Bar Market, forcing manufacturers to rebuild recipes around alternative sweeteners while maintaining taste thresholds that drive repeat purchase.
Growth Catalysts
- USDA Organic Certification:The USDA's National Organic Program unlocks shelf-space premiums in natural retail channels, with certified bars commanding placement in high-velocity perimeter locations.
- Protein fortification:Whey and plant-protein extrusion technologies enable 20g+ protein claims that convert gym-culture penetration into mainstream snacking occasions.
- California demand concentration:West Coast fitness culture and on-the-go consumption patterns generate test-market velocity that shapes national flavor and format rollouts.
Market Restraints
- Almond supply volatility:California drought cycles and water-rights disputes create input cost instability for nut-butter-based formulations that anchor the premium segment.
- Co-manufacturer concentration:Third-party extrusion capacity clusters in the Midwest, creating single-source risk for emerging brands without captive production.
- Clean-label shelf-life tradeoff:Removal of chemical preservatives compresss distribution radius and elevates spoilage rates in warm-climate retail.
Strategic Opportunities
- Canadian expansion:CFIA organic standards alignment with USDA rules enables cross-border SKU replication with minimal reformulation overhead.
- Direct-to-subscription channels:Personalized nutrition bundles bypass slotting-fee barriers and capture lifetime-value data from repeat purchasers.
- Sugar-tax anticipation:State-level proposals in California and New York create first-mover advantage for zero-added-sugar portfolios ahead of mandate.
Industry Challenges
- Food-scientist talent scarcity:Clean-label formulation expertise commands premium compensation that strains emerging brand burn rates.
- Dual certification timelines:Simultaneous USDA Organic and Non-GMO Project verification extends go-to-market cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Snack Bar Market |
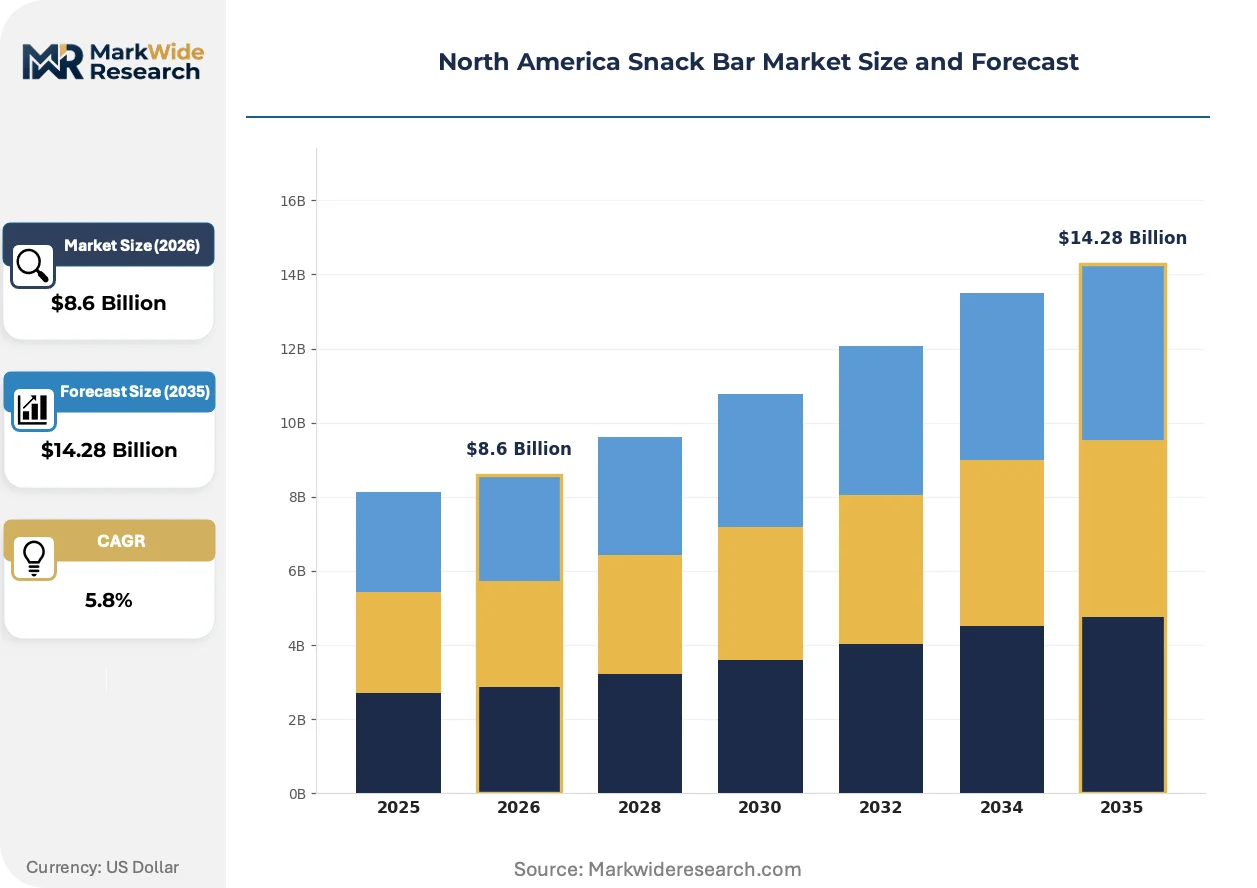
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $14.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Bars, Protein Bars, Granola Bars, Fruit Bars Ingredient Type: Organic, Gluten-Free, Low-Sugar, High-Fiber Distribution Channel: Convenience Stores, Online Retail, Supermarkets, Specialty Stores Target Consumer: Health-Conscious Individuals, Athletes, Busy Professionals, Children |
| Companies Covered | General Mills, Mondelez International, PepsiCo, Mars, Kellanova, Post Holdings, The Simply Good Foods Company, Clif Bar & Company, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Snack Bar Market Trends and Innovations
Cold-pressed manufacturing is reshaping competitive positioning in the North America Snack Bar Market, with texture and nutrient-density claims overtaking traditional extrusion as the dominant quality signal.
High-pressure processing is overtaking thermal pasteurization for raw-ingredient preservation. Premium brands targeting the yoga-studio channel have adopted HPP to deliver enzyme-active claims without refrigeration. This technology is overtaking conventional shelf-stable formats in the $4-plus price tier, compressing margins for legacy baked-bar portfolios.
The FDA's updated Nutrition Facts panel mandates added-sugar line-item disclosure that exposes hidden sweeteners in fruit-juice concentrates. Manufacturers are rebuilding binders around allulose and monk fruit to maintain palatability while achieving single-digit sugar callouts. Protein bars with chocolate coatings face the steepest reformulation burden, as cocoa liquor masks sugar content that now appears explicitly.
Subscription-based replenishment is displacing impulse-aisle discovery as the primary acquisition mode for specialty-diet consumers. Direct channels capture purchase-history data that enables flavor-matching algorithms, while natural retail loses traffic to curated monthly boxes. This shift concentrates most visibly in the Pacific Northwest, where fitness-app integration drives automated reordering tied to workout-logging behavior.
North America Snack Bar Market Segmentation
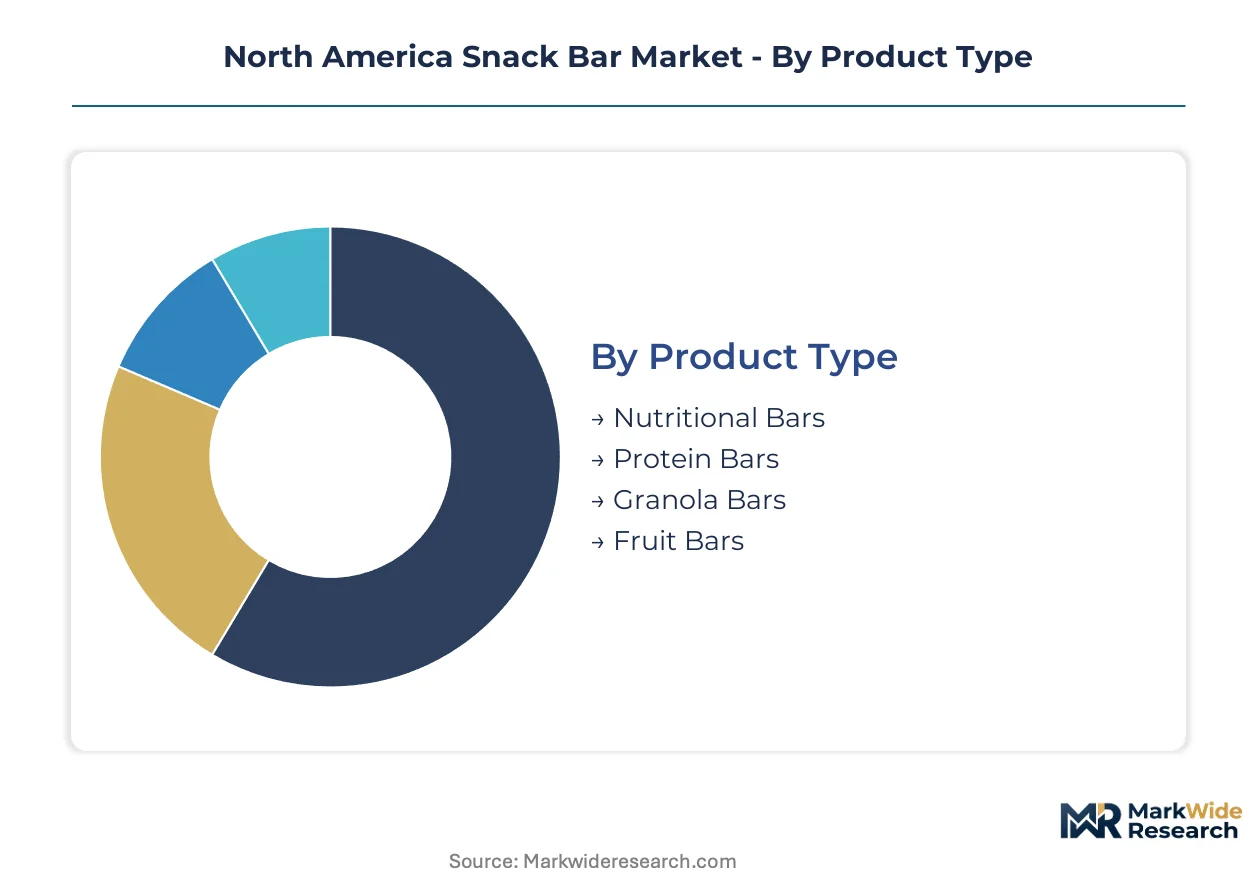
Snack bar manufacturers align portfolio architecture with distinct consumption occasions and certification premiums. Upgrade cycles in protein fortification and clean-label reformulation create tiered margin pools across each segmentation dimension.
Product Type:
Reformulation investments concentrate where gym-culture penetration and parental purchasing power overlap most densely.
- Protein Bars:Extruded or cold-pressed formats delivering 15-25g protein per serving through whey isolate, casein, or pea-rice blends. California and Texas metropolitan markets absorb the highest velocity as boutique fitness chains expand corporate wellness programs.
- Fruit Bars:No-added-sugar formulations using date paste, fruit purees, and natural binders. Pacific Northwest parental demographics drive repeat purchase rates through natural retail channels.
- Granola Bars:Oat-based clusters with honey or maple syrup binding, targeting school-lunch occasions.
- Nutritional Bars:Meal-replacement positioning with vitamin-mineral fortification for weight-management protocols.
Protein Bars sits at the top of the volume ranking, with Fruit Bars climbing the fastest.
Ingredient Type:
Certification stacking determines shelf placement economics and cross-border eligibility.
- Organic:USDA National Organic Program compliance enables placement in Whole Foods Market and Sprouts Farmers Market perimeter locations. The 18-24 month transition period for ingredient suppliers compresses new entrant timelines.
- Gluten-Free:Formulations certified below 20ppm gluten threshold capture celiac and discretionary wellness segments. Midwest grain-belt co-manufacturers dominate extrusion capacity for oat-based variants.
- Low-Sugar:Allulose and monk fruit rebuiling to achieve sub-5g sugar callouts.
- High-Fiber:Chicory root inulin and soluble corn fiber additions targeting digestive health claims.
Organic commands the certification premium tier, with Gluten-Free expanding most quickly into mainstream conventional retail.
Distribution Channel:
Channel selection dictates velocity patterns and data capture depth for repeat-purchase algorithms.
- Supermarkets:Kroger and Albertsons banner placement requires slotting fee commitments and promotional calendar alignment. West Coast banners test innovation velocity before national rollout authorization.
- Online Retail:Amazon Subscribe & Save and Thrive Market capture subscription replenishment with purchase-history personalization. Direct-to-consumer margins bypass the 25-40% retail markup.
- Convenience Stores:7-Eleven and Circle K impulse placement for single-serve protein formats.
- Specialty Stores:GNC and Vitamin Shoppe sports-nutrition positioning with staff recommendation protocols.
Supermarkets anchor volume concentration, with Online Retail gaining share fastest through subscription bundling.
Target Consumer:
Demographic targeting shapes flavor architecture, packaging format, and price point calibration.
- Health-Conscious Individuals:Clean-label seekers prioritizing ingredient list transparency over macronutrient ratios. California and Colorado urban clusters show highest per-capita spending on certified organic variants.
- Athletes:20g+ protein targets with BCAA fortification and rapid glycogen recovery formulations. Collegiate athletic departments and CrossFit affiliate networks drive bulk procurement.
- Busy Professionals:Meal-replacement positioning for desk-drawer stash and commute consumption.
- Children:Allergen-free school-safe formats with parental-approved sugar thresholds.
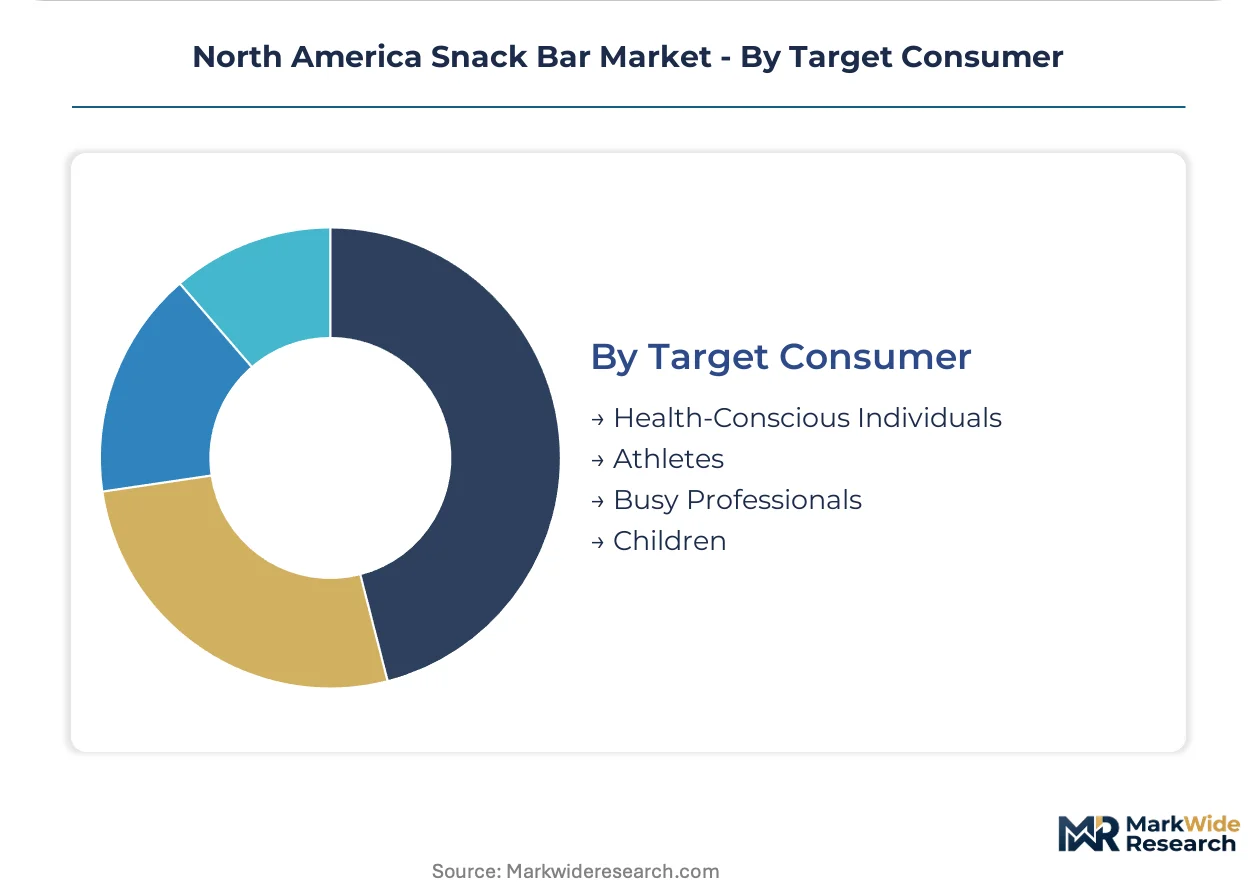
Health-Conscious Individuals represent the largest addressable base, with Athletes expanding most quickly through sports-nutrition channel convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America Snack Bar Market traces its commercial origins to California health food co-ops of the 1970s, where granola bars first scaled from homemade recipes into packaged retail formats. Distribution infrastructure and ingredient supply chains subsequently concentrated along the US West Coast before expanding across the continent.
United States
FDA Nutrition Facts labeling mandates for added sugars disclosure are accelerating reformulation timelines among domestic manufacturers. California and Texas metropolitan markets absorb the highest protein bar velocity as boutique fitness chains expand corporate wellness programs. The Pacific Northwest cluster around Portland and Seattle drives subscription-based replenishment tied to fitness-app integration.
Canada
CFIA organic standards alignment with USDA National Organic Program rules enables cross-border SKU replication with minimal reformulation overhead. Health Canada's Safe Food for Canadians Regulations enforce allergen controls that shape production infrastructure investments for exporters. Ontario and Quebec concentrate manufacturing capacity serving both domestic distribution and US market access.
Mexico
Proximity to US Southwest distribution hubs positions northern border states as emerging co-manufacturing locations for cost-sensitive bar formats. Mexico's national food safety regulator enforces labeling harmonization requirements that facilitate northbound export compliance. Guadalajara and Monterrey industrial corridors attract extrusion equipment investments serving private-label contract production.
North America Snack Bar Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with organic and clean-label portfolios commanding shelf-space premiums in natural retail channels while conventional formulations compete on velocity in mass-market banners. The vendor base distributes across diversified food conglomerates, specialized nutrition companies, and emerging private-label suppliers. Three strategic archetypes dominate: cereal-derived ingredient leverage, chocolate-coating expertise, and plant-based organic positioning. Consolidation activity concentrates on acquiring cold-press manufacturing capabilities, while capacity expansion targets Midwest extrusion clusters to reduce co-manufacturer dependency.
Within the diversified conglomerate tier, General Mills and Mondelez International occupy positions anchored by ingredient pipeline control and impulse-channel distribution density respectively. Clif Bar & Company exemplifies the specialized organic archetype that commands perimeter placement premiums in natural retail. These three entities represent distinct competitive vectors—input cost management, coating technology, and certification-driven positioning—that structure rivalry across price tiers.
| Leading Market Players |
|---|
| General Mills |
| Mondelez International |
| PepsiCo |
| Mars |
| Kellanova |
| Post Holdings |
| The Simply Good Foods Company |
| Clif Bar & Company |
| Nestle |
| Others |
Pricing and Supply Chain Analysis
Cold-pressed manufacturing adoption simultaneously compresses production costs for premium-tier entrants and redistributes supply leverage toward equipment vendors with proprietary extrusion IP. This dual effect tightens margin capture for legacy baked-bar portfolios while elevating pricing power for certified organic and HPP-enabled formats that command perimeter placement premiums in natural retail channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified bars from conventional formulations and private-label commodity SKUs. Price differentiation hinges on certification stacking depth and West Coast test-market velocity, with California-origin brands extracting brand premiums from national rollout authorization. Cost compression in the standard tier is intensifying because almond butter input volatility and co-manufacturer capacity constraints squeeze mid-market players. Bulk procurement through collegiate athletic departments shows lowest price sensitivity, while convenience-store single-serve purchasers exhibit highest elasticity to unit-price increases.
Supply Chain Analysis
Freight cost escalation from California ingredient hubs to Midwest extrusion facilities is forcing geographic repositioning of cold-press capacity toward Pacific Northwest industrial corridors. Raw material sourcing draws from Canadian prairie grain belts for oat inputs, California Central Valley nut processors for almond and cashew butters, and Mexican border states for date paste and chia seed imports. Single-source vulnerability concentrates in third-party extrusion capacity clustered around Chicago and Minneapolis, where equipment lead times extend formulation-to-shelf timelines. Distribution runs through West Coast natural retail perimeters for premium-tier velocity, with mass-market banner penetration requiring slotting-fee commitments and promotional calendar alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Snack Bar Market functions as a regulatory compounder where FDA added-sugar disclosure mandates and state-level sugar-tax proposals accelerate portfolio turnover toward zero-added-sugar formats. This regulatory momentum creates structural advantage for first-movers with existing clean-label infrastructure.
For Market Incumbents: Extend certification depth through simultaneous USDA Organic and Non-GMO Project verification to defend shelf-space premiums against emerging cold-press specialists. Acquire captive extrusion capacity in Pacific Northwest industrial corridors to reduce co-manufacturer dependency and compress reformulation-to-market timelines. Anchor defensive positioning against private-label encroachment by locking multi-year supply contracts with California almond processors ahead of drought-cycle price spikes. For New Entrants and Emerging Players: Subscription-fatigued millennials in secondary Texas metropolitan markets represent the most penetrable buyer archetype for personalized nutrition bundles bypassing slotting-fee barriers. Target white-space in allergen-free school-safe formats with parental-approved sugar thresholds, where incumbent portfolios show formulation lag. Deploy direct-to-consumer acquisition through fitness-app integration enabling automated reordering tied to workout-logging behavior, capturing lifetime-value data that retail channels cannot replicate. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap organic specialists with captive cold-press manufacturing and established CFIA-compliant export infrastructure. Long-term viability over the coming decade favors acquisition targets with dual US-Canada certification alignment and subscription-channel revenue concentration exceeding conventional retail dependence. Monitor state-level sugar-tax implementation timelines as the critical inflection signal for zero-added-sugar portfolio premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA added-sugar disclosure mandates force binder rebuilding around allulose and monk fruit to maintain palatability thresholds. |
| Cold-Press Capacity Expansion | HPP-enabled manufacturing captures enzyme-active claims and $4-plus price tier positioning in yoga-studio channels. |
| Cross-Border Certification Alignment | USDA-CFIA organic standard harmonization enables SKU replication with minimal reformulation overhead for Canadian market entry. |
| Direct-to-Consumer Subscription Launch | Purchase-history personalization bypasses 25-40% retail markup and captures lifetime-value data from repeat purchasers. |
| Ingredient Pipeline Backward Integration | Cereal-derived input cost control accelerates clean-label development and insulates against commodity price volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with brand managers, category buyers at Kroger and Albertsons banners, supply planners at co-manufacturing facilities, and channel sales heads at natural retail distributors. Secondary validation drew from Nielsen retail audit data, FDA labeling guidance documents, USDA National Organic Program certification records, and customs trade data for almond and date paste import flows. Bottom-up SKU-level velocity tracking triangulated against top-down category spend estimates to anchor market size and growth projections.
Comparable-period anchoring tied projection models to historical reference intervals spanning pre-pandemic baseline, supply disruption peak, and normalization recovery phases across the analysis window. Segmentation dimensions modeled included product type, ingredient certification tier, distribution channel, and target consumer archetype, with CAGRs derived from curve-fitting algorithms applied to annualized velocity data. Forecast inputs incorporated protein fortification technology adoption curves, state-level sugar-tax proposal tracking, and fitness-app integration penetration rates as industry-specific demand drivers.
Underlying measurement precision varies by segment; online retail subscription data carries tighter precision than convenience-store impulse velocity estimates where scan-data gaps persist. Forecasts reflect documented assumptions regarding regulatory implementation timelines and consumer clean-label preference stability. Stakeholders should weight assumptions against their own operating context, particularly regarding almond supply volatility and co-manufacturer capacity expansion trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South America Frozen Snacks Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
South East Asia Snack Bar Market
Snacks
Fried Potato Chips Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Jerky Snacks Market
Snacks
North America Frozen Snacks Market
Snacks
Savoury Biscuits Market
Snacks
Allergy-Free Snacks Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Middle East and Africa Snack Food Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Fat Free Snacks Market
Snacks
Better for You Snacks Market
Snacks
Sweet Potato Fries Market