
 Edible Flakes Market | 2026-2036
Edible Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Flakes Market Analysis
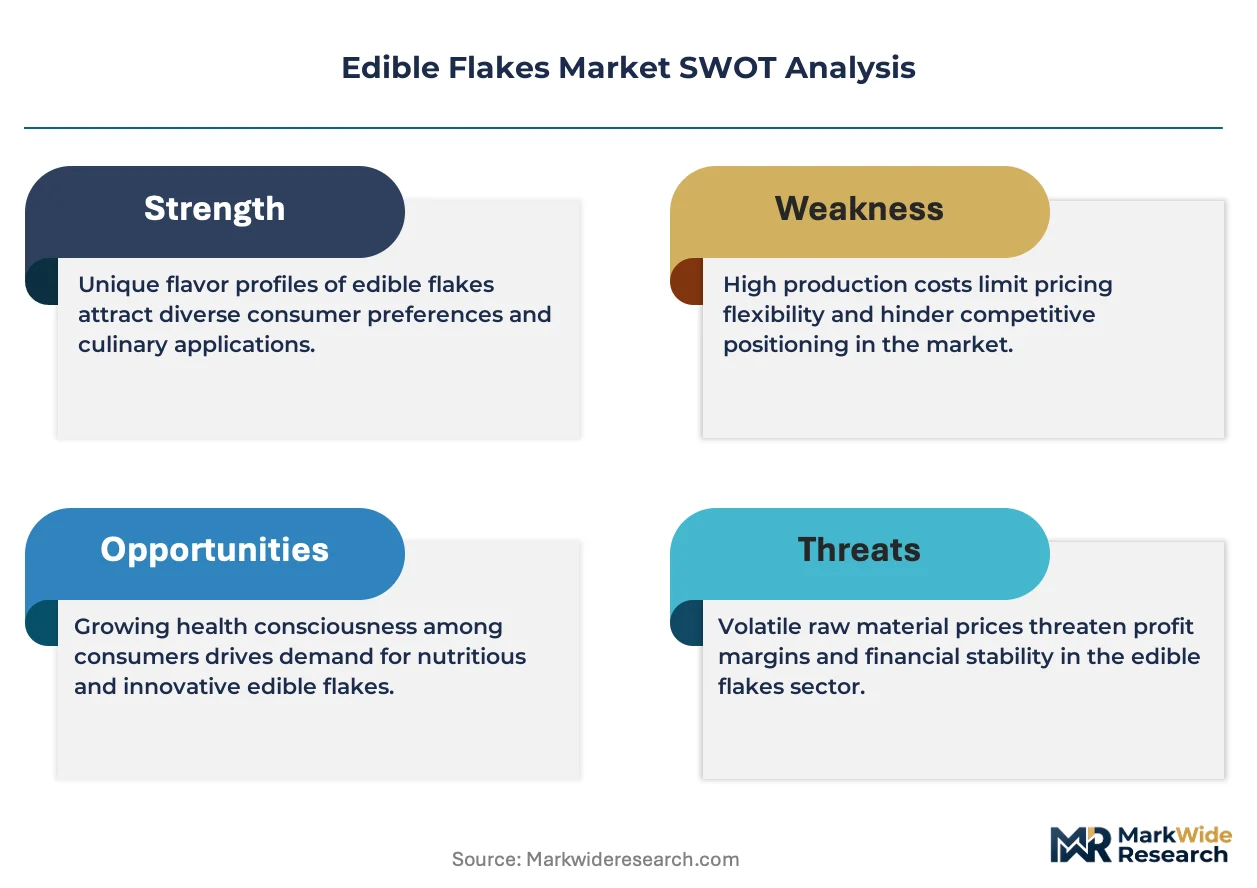
Asset-light contract manufacturing and co-packing arrangements is narrowing the capital barrier for mid-sized entrants in edible flakes. Kellanova leverages its global grain sourcing infrastructure to sustain cost advantages across multiple continents. General Mills anchors North American distribution through deep retail partnerships. Nestlé competes on R&D intensity in fortified and functional flake formulations.
Edible flakes comprise dehydrated, flattened, or rolled food substrates—typically grains, fruits, vegetables, or proteins—that rehydrate or crisp upon contact with liquid or heat, with moisture content generally below 10 percent and thickness ranging from 0.3 to 2.0 millimeters for uniform reconstitution. These products serve as ready-to-eat meal components, ingredient inputs for processed foods, or standalone snack formats across commercial and retail channels. Grain flakes dominate volume due to entrenched breakfast consumption patterns in Western markets, while protein flakes from legume and dairy sources capture expanding margin pools in sports nutrition and clinical diet segments. Vegetable flakes gain traction within food processing channels where manufacturers seek clean-label texturizers and flavor carriers without synthetic additives.
The FDA governs ingredient safety and nutrition labeling for edible flakes sold in the United States, while the EU Green Deal and EFSA standards enforce sustainability thresholds and pesticide residue limits for imported grain and vegetable substrates. BIS certification requirements in India and FSSAI fortification guidelines further segment market access by quality tier. Stakeholders must monitor evolving allergen disclosure mandates and carbon footprint auditing protocols that will determine supplier eligibility in regulated procurement channels.
Market Dynamics
Clean-label mandates from the EU Green Deal and FDA nutrition-labeling updates are forcing simultaneous reformulation across grain, protein, and vegetable flake categories, compressing R&D timelines while opening premium positioning for compliant suppliers.
Growth Catalysts
- Sports nutrition end-use:Protein flakes from legume and dairy sources capture expanding margin pools as clinical diet segments and athletic recovery applications multiply formulation orders.
- EU Green Deal sustainability thresholds:Carbon footprint auditing protocols now determine supplier eligibility in regulated European procurement channels, advantaging early certifiers.
- India FSSAI fortification guidelines:Mandatory micronutrient standards in processed foods drive technical partnerships between flake manufacturers and premix suppliers for iron-fortified grain formats.
Market Restraints
- Input cost volatility:Wheat and oat futures fluctuate with Black Sea supply disruptions, compressing margins for grain-dominant producers without forward-contract coverage.
- Technical limitation:Protein flake rehydration rates below 85 percent restrict adoption in ready-to-eat meal applications where texture parity with fresh ingredients is mandatory.
- Regulatory friction:EFSA pesticide residue limits for imported vegetable substrates block entry for suppliers from regions without equivalency agreements.
Strategic Opportunities
- Underpenetrated geography:Southeast Asian savory flake demand concentrates in Indonesia, Vietnam, and Thailand where spiced variants adapted to regional palates command local distribution premiums.
- Technology convergence:Pulse-drying combined with precision thickness control enables vegetable flake production with sub-5 percent moisture variance for industrial texturizer applications.
- Regulatory tailwind:India's PLI scheme for food processing equipment subsidizes capital expenditure for automated flake lines serving export-quality output.
Industry Challenges
- Skill gap in process engineering:Operators capable of calibrating roller-gap settings for 0.3-2.0 millimeter thickness specifications across variable substrate moisture levels remain scarce in emerging production regions.
- Certification timeline compression:BIS certification requirements in India and parallel FSSAI audits extend product launch cycles by 8-14 months for multinational entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Flakes Market |
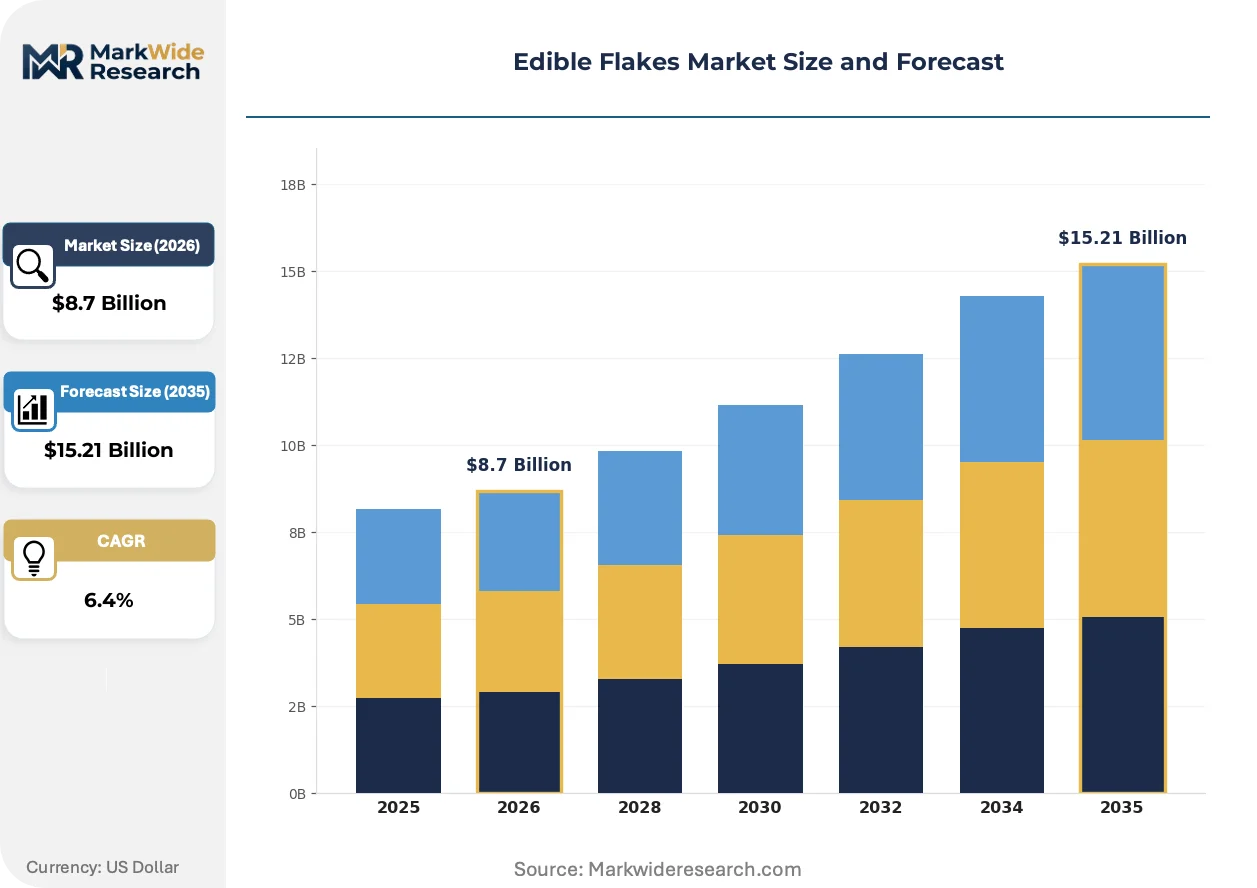
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flakes, Vegetable Flakes, Protein Flakes, Grain Flakes End Use: Snacking, Cooking, Baking, Food Processing Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Flavor Profile: Sweet, Savory, Spicy, Umami |
| Companies Covered | Kellanova, General Mills, Nestlé, PepsiCo, Post Holdings, Quaker Oats Company, Marico, Bagrry's, Weetabix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Flakes Market Emerging Trajectories
Refrigeration-free supply chains and precision dehydration technologies are collapsing traditional barriers between fresh-ingredient texture and shelf-stable convenience, redirecting capital toward equipment that preserves cellular structure through controlled moisture extraction.
High-pressure processing pretreatment is collapsing the quality gap between fresh-cut and dehydrated vegetable flakes. Foodservice manufacturers in the United States adopt this technology to meet FDA-ready meal safety standards without synthetic preservatives. The structural consequence is collapsing price premiums for IQF vegetables in prepared meal applications where rehydrated flakes now substitute at 40-60 percent lower delivered cost.
REACH authorization requirements for novel processing aids are tightening ingredient disclosure obligations for European flake manufacturers. Industrial buyers now demand full substance-level transparency through supply tiers to preempt SVHC candidate list disruptions. Protein flake segments face the steepest compliance burden as novel binding agents undergo extended EFSA safety assessments.
Direct procurement from ingredient-origin clusters is shortening the traditional three-tier distribution architecture for grain flakes. North American breakfast cereal manufacturers now contract directly with Canadian prairie oat cooperatives and Australian wheat bulk handlers, bypassing commodity traders. This pattern concentrates most visibly in organic-certified supply pools where lot-traceability requirements exceed conventional channel capabilities.
Edible Flakes Market Segmentation
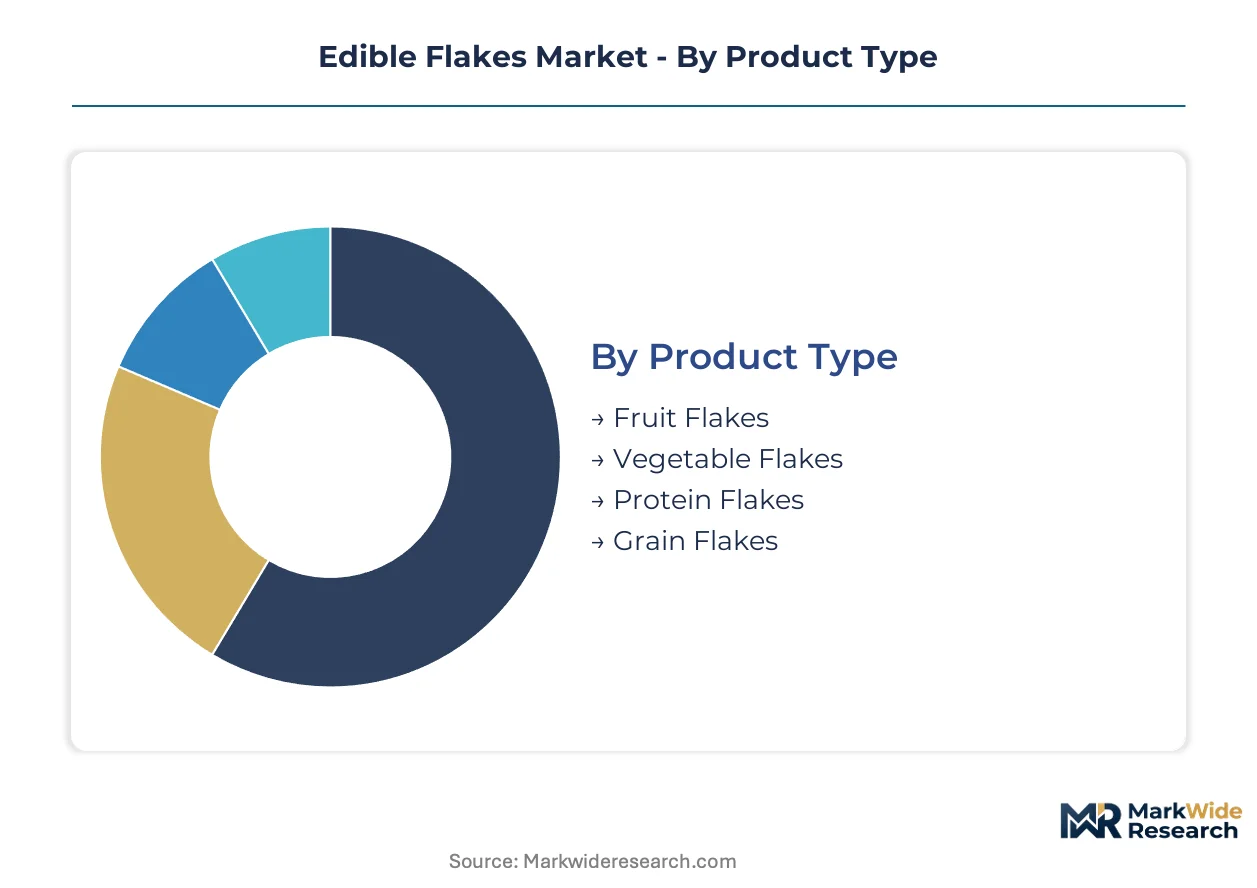
Segmentation in edible flakes reveals divergent margin profiles and inventory velocity patterns. Grain formats turn over fastest through established breakfast channels while protein and vegetable variants command longer development cycles but expanding premium realization.
Product Type:
Grain flakes rotate inventory fastest due to entrenched consumption rituals, while protein and vegetable formats require extended formulation timelines to achieve rehydration parity and clean-label compliance.
- Grain Flakes:Rolled or flattened oat, wheat, and corn substrates with moisture content below 10 percent and thickness calibrated for uniform milk reconstitution. North American breakfast cereal manufacturers anchor volume demand, though EU Green Deal carbon auditing now filters supplier eligibility for European procurement channels.
- Protein Flakes:Dehydrated legume and dairy substrates processed to 0.3-2.0 millimeter specifications for sports nutrition and clinical diet applications. Sports nutrition end-use in the United States and Western Europe captures expanding margin pools as athletic recovery formulations multiply technical orders.
- Vegetable Flakes:Dehydrated carrot, spinach, tomato, and beet substrates serving as clean-label texturizers in processed foods.
- Fruit Flakes:Dehydrated apple, berry, and tropical fruit formats for baking and snacking applications.
Grain flakes dominate installed base. Protein flakes are where expansion concentrates.
End Use:
Snacking applications concentrate highest purchase frequency while food processing channels generate volume commitments with extended contract horizons.
- Snacking:Ready-to-eat standalone consumption formats across retail and foodservice channels with immediate rehydration or dry consumption. Health-focused snack brands in India and Southeast Asia drive uptake of spiced and savory variants adapted to regional palate preferences.
- Food Processing:Ingredient inputs for prepared meals, soups, sauces, and bakery applications requiring precise moisture variance and lot traceability. FDA-ready meal safety standards in the United States accelerate adoption of high-pressure processing pretreatment to collapse quality gaps with fresh-cut alternatives.
- Cooking:Home meal preparation applications including soup bases and side dish components.
- Baking:Ingredient incorporation into bread, pastry, and confectionery formulations.
Food processing commands the longest contract cycles. Snacking is climbing the fastest.
Distribution Channel:
Supermarkets and food service channels concentrate volume throughput while online retail and specialty stores filter for premium positioning and subscription loyalty.
- Supermarkets:Mass-market retail placement requiring slotting fee structures and promotional calendar alignment. Deep retail partnerships by North American breakfast cereal manufacturers sustain dominant shelf presence and category captaincy.
- Food Service:B2B supply to restaurants, institutional catering, and prepared meal manufacturers with specification-driven procurement. Direct procurement from Canadian prairie oat cooperatives and Australian wheat bulk handlers is collapsing traditional three-tier distribution architecture for organic-certified grain flakes.
- Online Retail:Direct-to-consumer and third-party marketplace distribution with subscription model potential.
- Specialty Stores:Health food, organic, and ethnic retail channels with curated assortment and educated staff.
Supermarkets anchor volume throughput. Online retail is gaining share fastest.
Flavor Profile:
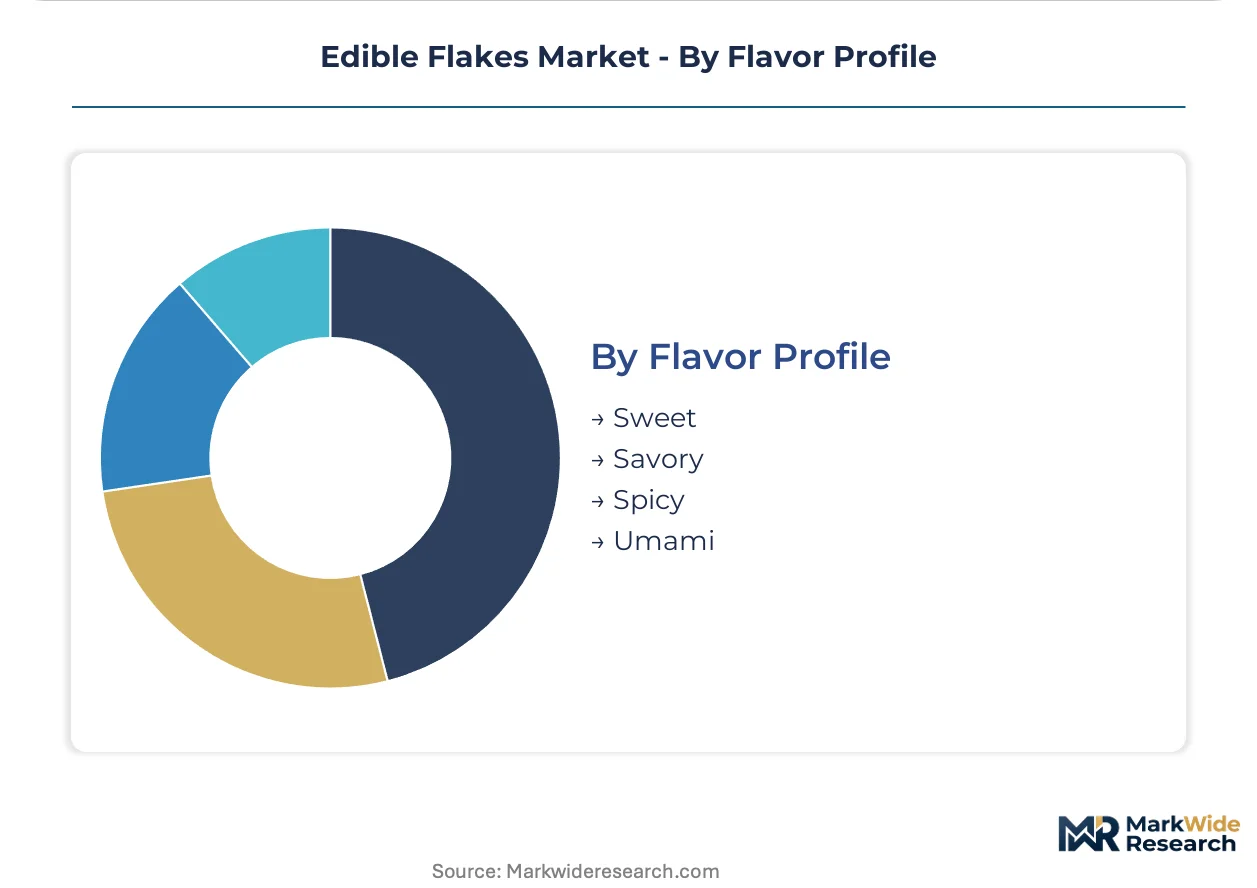
Sweet formats concentrate in Western breakfast applications while savory and spicy variants align with emerging Asian demand and protein flake positioning.
- Savory:Salt-forward and herb-infused formulations for meal-component and snacking applications. Southeast Asian demand concentrates in Indonesia, Vietnam, and Thailand where spiced variants adapted to regional palates command local distribution premiums.
- Sweet:Sugar or fruit-juice-infused formats for breakfast cereal and baking applications. Entrenched consumption patterns in Western markets sustain volume dominance despite clean-label reformulation pressures.
- Spicy:Chili, pepper, and heat-forward formulations targeting ethnic cuisine and adventurous snacking segments.
- Umami:Fermented and glutamate-rich profiles for Asian-inspired cooking and premium snacking.
Sweet formats dominate installed base. Savory is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in edible flakes tilt toward deficit positions in grain-dependent European markets and surplus generation in Canadian prairie and Australian wheat belts. Import demand concentrates in Asian processing hubs seeking clean-label texturizers. Regulatory divergence across FDA, EFSA, and FSSAI jurisdictions fragments supplier certification requirements.
United States
Sports nutrition brands and prepared meal manufacturers drive protein flake procurement from domestic dairy and legume processors. FDA nutrition-labeling updates and ready-meal safety standards compress reformulation timelines for suppliers. Minneapolis-St. Paul anchors North American grain processing capacity where breakfast cereal manufacturers maintain deep retail partnerships.
Germany
EU Green Deal carbon auditing protocols filter supplier eligibility for grain flake procurement by multinational food manufacturers. REACH authorization requirements for novel processing aids tighten ingredient disclosure obligations through supply tiers. Hamburg and the North Rhine-Westphalia industrial corridor concentrate dehydration equipment manufacturing and organic-certified grain trading.
India
Health-focused snack brands and savory flake processors multiply orders for spiced variants adapted to regional palates. FSSAI fortification guidelines mandate micronutrient standards in processed foods, driving technical partnerships between manufacturers and premix suppliers. Maharashtra and Gujarat host automated flake line installations subsidized under the PLI scheme for food processing equipment.
Indonesia
Foodservice distributors and local snack manufacturers concentrate demand for savory and spiced flake formats. The country's national food safety agency enforces halal certification and import quality standards that segment market access. Java's processing corridors, particularly around Jakarta and Surabaya, command local distribution premiums for palate-adapted variants.
Australia
Bulk wheat and oat handlers direct-export to North American breakfast cereal manufacturers bypassing commodity traders. The country's national agricultural regulator enforces residue limits and organic certification protocols for grain exports. The Murray-Darling Basin and Western Australian wheat belts sustain cost advantages through direct procurement relationships with Canadian and US processors.
Edible Flakes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in dehydration equipment and premix supply. The vendor base concentrates around grain-dominant multinational food manufacturers with captive sourcing infrastructure, mid-sized regional processors serving savory niche demand, and equipment fabricators enabling precision thickness control. Strategic moves center on direct procurement from origin clusters and backward integration into grain handling assets.
Within the multinational integrator tier, Kellanova, General Mills, and Nestlé occupy positions defined by global grain sourcing infrastructure, North American retail anchoring, and R&D intensity in fortified formulations respectively. These entities exemplify divergent competitive postures: Kellanova leverages continental-scale supply networks, General Mills deepens retail partnership structures, and Nestlé concentrates technical resources on functional flake development. Marico and Bagrry's represent the regional specialist archetype, sitting within Asia-Pacific savory and health-snack segments where local palate adaptation commands premium positioning.
| Leading Market Players |
|---|
| Kellanova |
| General Mills |
| Nestlé |
| PepsiCo |
| Post Holdings |
| Quaker Oats Company |
| Marico |
| Bagrry's |
| Weetabix |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Australian and Canadian grain processing facilities is compressing supplier margins while simultaneously granting North American breakfast cereal manufacturers enhanced negotiating leverage on long-term offtake contracts. This utilization imbalance feeds directly into pricing posture across grain flake tiers, with underutilized dehydration assets accepting lower unit economics to secure volume commitments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across grain flake categories, with three-tier pricing structure across premium, standard, and economy levels differentiated by organic certification grade and carbon audit compliance. Price differentiation stems from EU Green Deal eligibility thresholds and volume scale commitments. Cost compression in standard-tier grain flakes is intensifying because Black Sea supply disruptions have elevated wheat and oat futures volatility. Food processing channels exhibit highest price sensitivity due to ingredient cost pass-through limitations, while sports nutrition brands demonstrate lowest sensitivity given premium positioning tolerance.
Supply Chain Analysis
Asset-light contract manufacturers in India and Southeast Asia hold expanding dehydration capacity for savory flake production. Geographic supply concentration centers on Canada, Australia, and India for grain substrates, with protein flake inputs drawing from domestic dairy and legume processors in the United States and Western Europe. Raw material dependencies rest on wheat futures, oat cooperatives, and vegetable substrate imports. Single-source vulnerability persists for organic-certified grain supply from Canadian prairie cooperatives. Distribution runs through direct procurement relationships collapsing traditional three-tier commodity trading architecture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edible flakes market is exiting a cyclical trough as sports nutrition formulation orders multiply and clean-label reformulation mandates force ingredient replacement cycles across processed food channels.
For Market Incumbents: Harden supplier certification infrastructure against EU Green Deal carbon auditing protocols and FDA nutrition-labeling updates to preempt eligibility exclusion. Deepen backward integration into grain handling assets in Canadian prairie and Australian wheat belts to secure origin-cluster procurement advantages against commodity trader displacement. Lock in multi-year offtake agreements with organic-certified cooperatives before contract manufacturing capacity fully absorbs regional supply.
For New Entrants and Emerging Players: Pursue white-space positioning in Southeast Asian savory flake segments where spiced variants adapted to Indonesian, Vietnamese, and Thai palates command local distribution premiums. Target India's PLI-subsidized automated flake line installations in Maharashtra and Gujarat to achieve export-quality output at reduced capital intensity. Leverage co-packing arrangements with established dehydration equipment operators to bypass skill gaps in roller-gap calibration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional specialists with captive savory flake formulations and technical partnerships with premix suppliers for fortified grain formats. Long-term viability favors mid-sized processors with demonstrated FSSAI and BIS certification completion and established direct procurement relationships with foodservice distributors. Watch for inflection signals in high-pressure processing pretreatment adoption rates among United States prepared meal manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Procurement from Origin Clusters | Bypasses commodity traders and secures lot-traceability for organic-certified supply pools. |
| Backward Integration into Grain Handling | Captures cost advantages through captive sourcing infrastructure across multiple continents. |
| High-Pressure Processing Pretreatment Investment | Collapses quality gaps with fresh-cut vegetables for FDA-ready meal safety compliance. |
| PLI-Subsidized Automated Line Installation | Reduces capital barriers for export-quality flake production in India. |
| Carbon Audit Certification Completion | Secures supplier eligibility under EU Green Deal procurement thresholds. |
Methodological Framework
A standing panel of breakfast cereal procurement directors, dehydration equipment engineers, sports nutrition formulation scientists, and FSSAI compliance officers provided ongoing calibration throughout the analysis window. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against customs records, SEC filings of multinational food manufacturers, EU EFSA substance databases, and BIS certification registries. Bottom-up demand modeling triangulated against top-down supply capacity assessments across Canadian prairie cooperatives and Australian wheat bulk handlers.
Scenario bracketing anchored the analytical framework across product type, end-use application, distribution channel, and flavor profile dimensions over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory implementation timelines. Forecast inputs incorporated Black Sea grain futures volatility patterns and FSSAI fortification mandate compliance trajectories.
Sensitivities concentrate around EU Green Deal carbon auditing protocol enforcement intensity and India PLI scheme subsidy continuation. Forecasts reflect documented assumptions on sports nutrition demand elasticity and clean-label reformulation completion rates. Quarterly review of high-pressure processing equipment installation data and organic certification conversion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
United States Snack Bar Market
Snacks
Extruded Cereals Market
Snacks
Dairy Protein Crisps Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
North America Snack Pellets Market
Snacks
Premium Snacks Market
Snacks
Vegan Protein Balls Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
South Africa Savory Snacks Market
Snacks
Indonesia Snack Bar Market
Snacks
Crispy Fruit Chips Market
Snacks
Italy Snack Bar Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Low Fat Sweet Snacks Market
Snacks
North America Extruded Snack Food Market
Snacks
Roasted Corn Market