
 Energy Balls Market | 2026-2036
Energy Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Balls Market Analysis
The gap between premium organic energy balls and commodity-priced alternatives is broadening as ingredient provenance and certification standards diverge sharply. GoMacro leverages its certified organic supply chain to command shelf-space premiums in natural retail channels. RXBAR competes through minimalist ingredient lists that sustain consumer trust in clean-label positioning. Bounce Foods anchors its presence in European markets with protein-forward formulations that differentiate against sugar-heavy competitors.
Energy balls are shelf-stable, nutrient-dense spherical snacks manufactured through cold-pressing or extrusion processes, typically combining nut butters, dried fruits, and protein isolates into portable formats designed for satiety and convenience. Protein balls lead the product type landscape due to gym-culture penetration and sports nutrition cross-selling, while vegan balls represent the fastest-expanding ingredient-source category as plant-based eating patterns displace dairy-inclusive alternatives. Pouch packaging dominates unit economics for single-serve impulse purchases, though bulk containers capture margin pools in club retail and direct-to-subscription channels.
The FDA oversees nutrition labeling and allergen declarations for energy balls distributed in the United States, while the USDA administers organic certification thresholds that shape premium-tier formulation decisions. The EU's EFSA and ECHA frameworks govern novel ingredient approvals and pesticide residue limits that constrain European sourcing strategies. Stakeholders must monitor evolving sugar-reduction mandates and packaging sustainability directives across multiple jurisdictions to anticipate reformulation costs and channel access requirements.
Market Dynamics
The EU's Farm to Fork Strategy is tightening ingredient traceability requirements while protein-fortified formats pull manufacturing investment toward cold-pressing equipment upgrades and certified organic supply chain restructuring.
Growth Catalysts
- Clean-label certification:USDA organic thresholds and EU organic logos command shelf-space premiums in natural retail channels, pulling formulation decisions toward pesticide-free nut butter sourcing and non-GMO dried fruit procurement.
- Gym-culture penetration:Sports nutrition cross-selling at fitness centers drives impulse purchases of protein-fortified spherical formats, with placement strategies targeting locker room vending and membership bundle programs.
- Germany:The country's functional food retail sector concentrates demand for low-sugar, high-fiber energy balls, with REWE and dm-drogerie markt expanding private-label allocations in the category.
Market Restraints
- Almond butter price volatility:California drought cycles and water allocation disputes create input cost instability for nut-dominant formulations, compressing margins on premium-tier products.
- European sourcing concentration:EFSA novel ingredient approval timelines delay market entry for innovative protein isolates, constraining formulation flexibility relative to North American competitors.
- Sugar-reduction mandates:Draft EU nutrition profiling regulations threaten shelf access for date-sweetened varieties exceeding proposed thresholds, forcing reformulation toward alternative binders.
Strategic Opportunities
- Direct-to-subscription channels:Bulk container formats bypass retail margin stacking while capturing recurring revenue pools from fitness-oriented households seeking pantry-stocking convenience.
- Plant-based protein convergence:Pea protein isolate and fava bean flour combinations enable complete amino acid profiles that displace whey-based alternatives in dairy-free positioning.
- India:FSSAI functional food category clarifications and PLI scheme incentives for food processing equipment create white space for cold-pressed format localization.
Industry Challenges
- Allergen management complexity:Cross-contamination protocols for tree nut, peanut, and sesame facilities require segregated production lines that inflate capex for multi-SKU manufacturers.
- Packaging sustainability compliance:EU Single-Use Plastics Directive implementation deadlines force rapid migration from multi-layer flexible pouches to mono-material or compostable alternatives with uncertain shelf-life performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Balls Market |
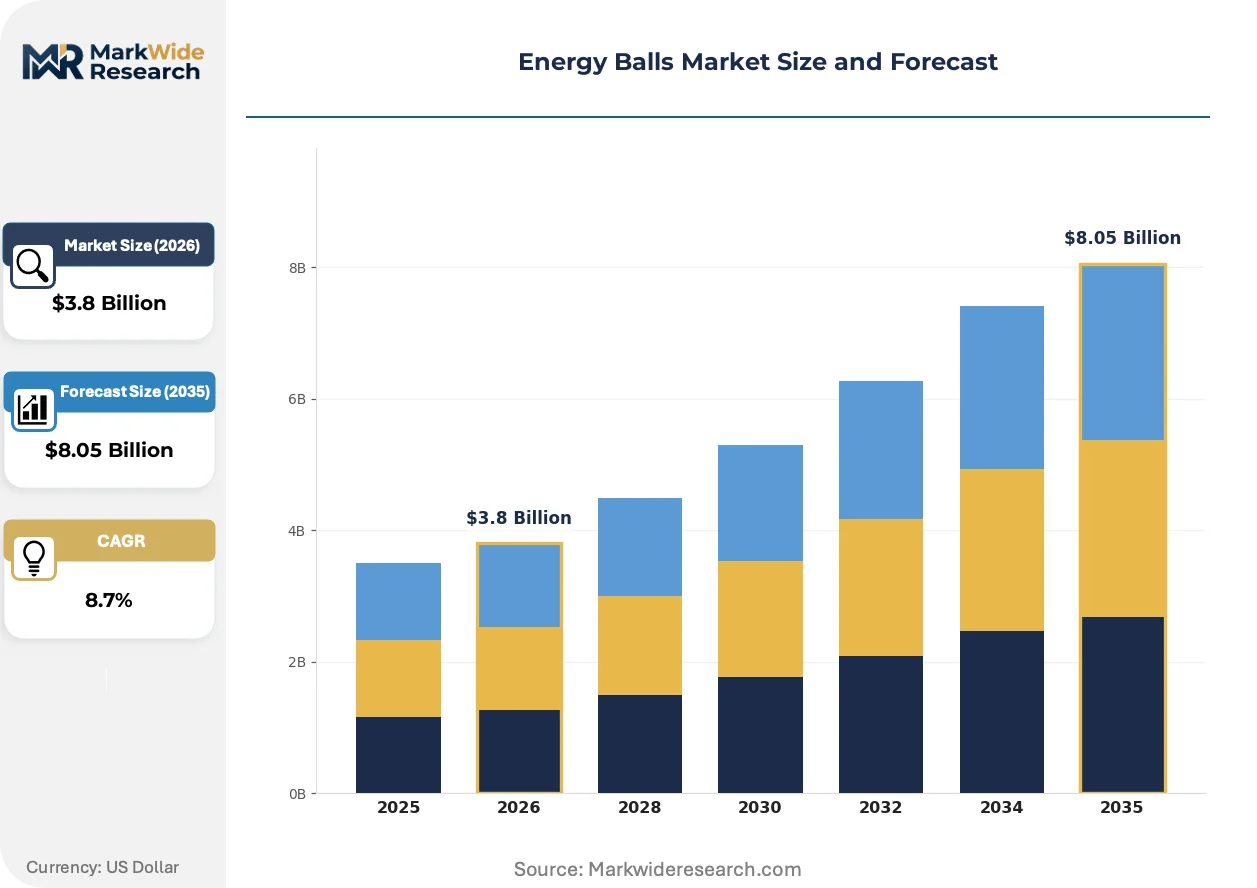
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Balls, Snack Balls, Vegan Balls, Nut Free Balls Ingredient Source: Nuts, Seeds, Grains, Dried Fruits Packaging Type: Pouches, Boxes, Jars, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | GoMacro, Health Warrior, Bounce Foods, Betty Lou's Inc., Windmill Organics, RXBAR, Perfect Snacks, Made In Nature, Inc., Larabar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Balls Market Emerging Trajectories
Cold-pressing equipment manufacturers are retrofitting extrusion lines with modular cavity molds while regulatory authorities on both sides of the Atlantic accelerate novel ingredient approval frameworks.
High-pressure processing technology is modularizing manufacturing footprints by enabling shelf-stable pasteurization without thermal degradation of heat-sensitive vitamins and plant proteins. Contract manufacturers serving mid-tier brands adopt skid-mounted HPP units to avoid centralized tolling dependencies. This distributed processing architecture compresses lead times for regional product launches while reducing working capital tied to finished goods inventory.
REACH substance restriction updates and ECHA microplastic labeling requirements are forcing reformulation of confectionery-grade coatings and external dusting agents used in energy ball production. Industrial consequence includes accelerated R&D spending on rice flour and cocoa butter alternatives. German and French manufacturers face the tightest compliance timelines, with several facilities already submitting downstream user notifications for modified recipes.
Subscription box curation is displacing single-serve impulse buying among core fitness demographics, with buyers prioritizing variety bundles and personalized macronutrient matching over grab-and-go convenience. This pattern concentrates order values and extends customer lifetime metrics. The shift is most visible in UK and US metropolitan markets where meal-kit penetration has normalized recurring food delivery relationships.
Energy Balls Market Segmentation
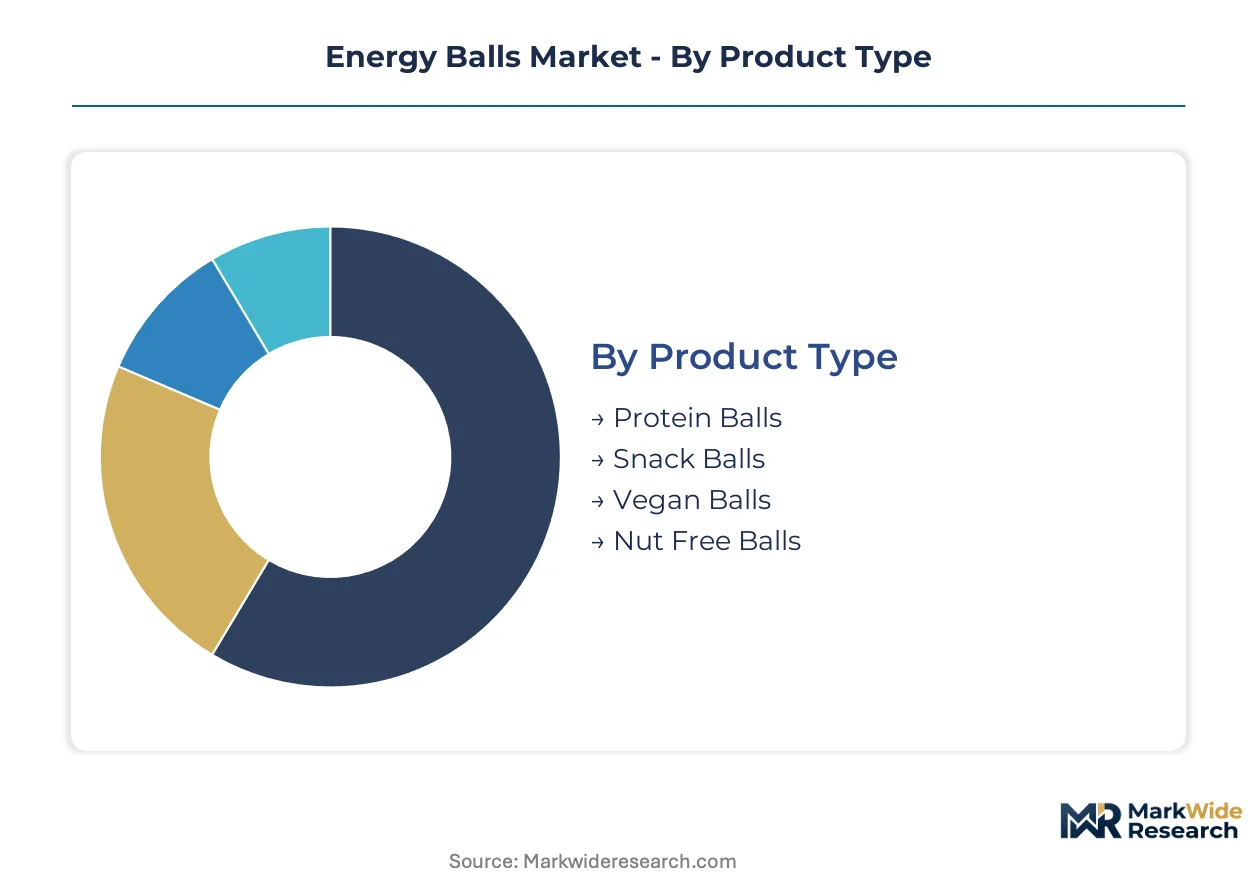
Energy balls manufacturers configure production lines and certification pathways around distinct consumer use cases and channel requirements. Segmentation choices determine cold-pressing equipment specifications, allergen management protocols, and shelf-life validation testing regimes.
Product Type:
USDA organic thresholds and EU organic logos impose divergent formulation burdens across spherical snack categories, with protein-fortified variants facing additional sports nutrition labeling scrutiny in multiple jurisdictions.
- Protein Balls:Cold-pressed spheres combining whey or plant isolates with nut butters achieve 15-20g protein per serving. Gym-culture penetration in Germany and the United States concentrates demand through fitness center vending and membership bundle programs.
- Vegan Balls:Dairy-free formulations rely on pea protein isolate and fava bean flour for complete amino acid profiles. Plant-based eating patterns in UK metropolitan markets displace whey-based alternatives fastest.
- Snack Balls:Lower-protein varieties emphasizing dried fruit sweetness and oat bases target children's lunchbox and office desk drawer occasions.
- Nut Free Balls:Sunflower seed butter and pumpkin seed formulations serve school-compliant and allergen-sensitive segments requiring segregated production lines.
Protein balls sit at the top of the volume ranking, with vegan balls climbing the fastest.
Ingredient Source:
Cost tier stratification separates commodity-grade inputs from certified organic supply chains commanding shelf-space premiums in natural retail channels.
- Nuts:Almond butter and cashew bases dominate premium-tier positioning. California drought cycles and water allocation disputes create input cost instability compressing margins.
- Seeds:Pumpkin, sunflower, and hemp seeds enable allergen-free and omega-3 positioning. European sourcing concentration for organic seed butters faces EFSA novel ingredient approval timeline constraints.
- Grains:Oat flour and quinoa puffs provide binding structure and fiber claims in mid-tier formulations.
- Dried Fruits:Date paste and raisin concentrates serve as natural sweeteners and moisture retainers. Draft EU nutrition profiling regulations threaten shelf access for date-sweetened varieties exceeding proposed sugar thresholds.
Nuts anchor the revenue base, with seeds expanding most quickly on allergen-free demand.
Packaging Type:
Volume scale determines equipment capital intensity, with single-serve formats requiring high-speed flow wrappers versus bulk container manual filling stations.
- Pouches:Multi-layer flexible films dominate unit economics for impulse purchases. EU Single-Use Plastics Directive deadlines force rapid migration to mono-material alternatives with uncertain shelf-life performance.
- Boxes:Retail-ready secondary packaging supports club store and pharmacy channel placement. German retailers REWE and dm-drogerie markt expand private-label allocations in boxed formats.
- Jars:Reusable rigid containers serve pantry-stocking households and zero-waste retail concepts.
- Bulk Containers:Direct-to-subscription channels bypass retail margin stacking while capturing recurring revenue pools from fitness-oriented households.
Pouches hold the volume lead, with bulk containers gaining share fastest on subscription channel growth.
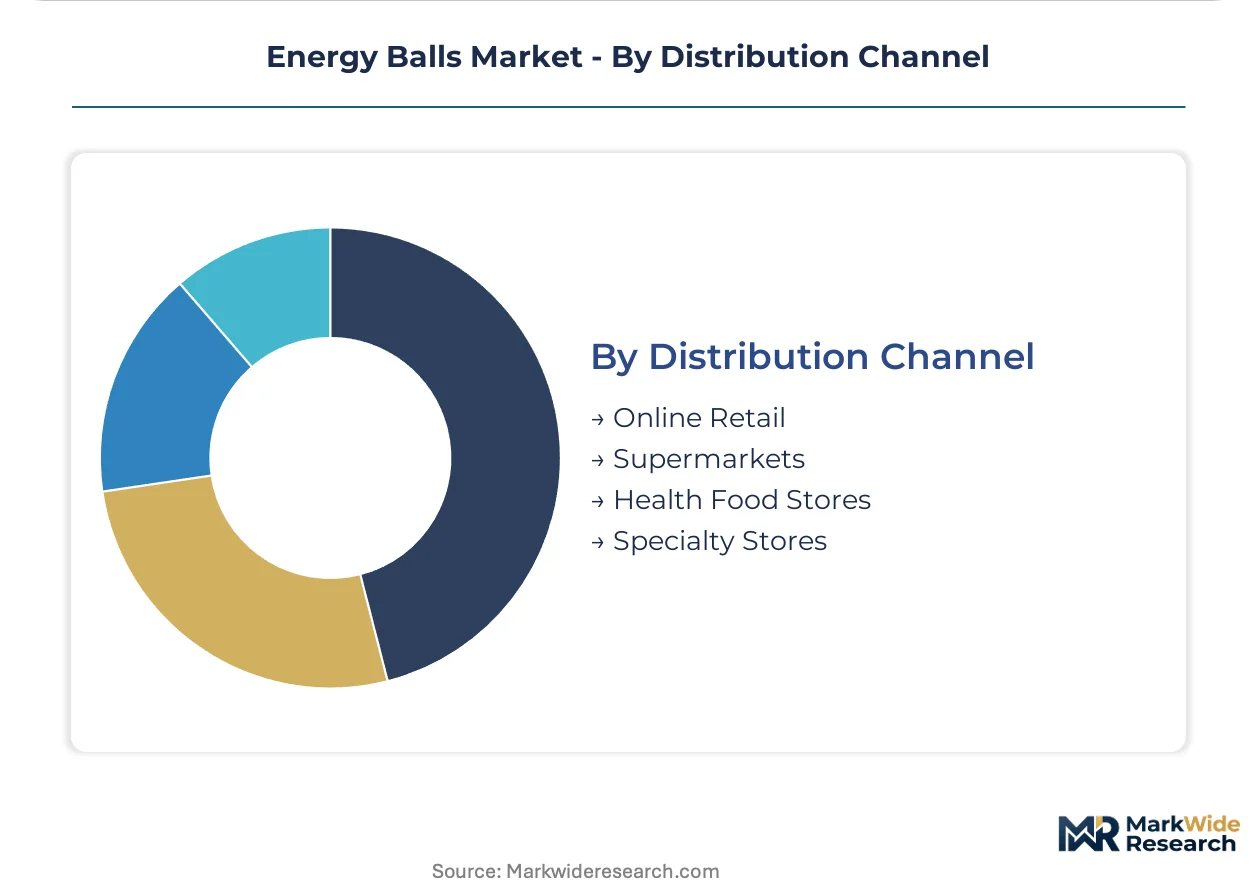
Distribution Channel:
Customer type segmentation separates fitness enthusiasts seeking macronutrient transparency from convenience-oriented shoppers prioritizing grab-and-go accessibility.
- Online Retail:Subscription box curation displaces single-serve impulse buying among core demographics. UK and US metropolitan markets show strongest recurring delivery relationship normalization.
- Supermarkets:Mass-market placement requires price competitiveness against commodity snack bars. Clean-label certification thresholds determine shelf-space allocation in natural food aisles.
- Health Food Stores:Independent retailers concentrate premium organic and raw-format SKUs with higher margin structures.
- Specialty Stores:Sports nutrition shops and yoga studio retail extend brand presence through contextual placement.
Supermarkets maintain volume dominance, with online retail expanding most steeply on subscription adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and sports nutrition formulators concentrate in Germany, the United States, and the United Kingdom, anchoring product development pipelines for protein-fortified and clean-label formats.
United States
Fitness center vending partnerships and membership bundle programs drive protein ball adoption through gym-culture penetration. FDA nutrition labeling requirements and USDA organic certification thresholds shape formulation decisions for premium-tier positioning. California's almond butter processing clusters face water allocation disputes that compress margins on nut-dominant formulations.
Germany
Functional food retail expansion at REWE and dm-drogerie markt concentrates demand for low-sugar, high-fiber energy balls. The EU's Farm to Fork Strategy under the European Green Deal tightens ingredient traceability requirements across domestic supply chains. Bavaria's organic food manufacturing corridor leads cold-pressing equipment upgrades for certified organic supply chain restructuring.
United Kingdom
Plant-based eating patterns in metropolitan markets displace whey-based alternatives fastest among vegan ball categories. EFSA novel ingredient approval timelines constrain formulation flexibility for innovative protein isolates relative to North American competitors. London's direct-to-consumer subscription ecosystem normalizes recurring delivery relationships for bulk container formats.
India
FSSAI functional food category clarifications and PLI scheme incentives for food processing equipment create white space for cold-pressed format localization. The country's national food regulator is streamlining approval pathways for protein-fortified snacks. Maharashtra's food processing parks attract contract manufacturing investment for regional product launches.
Australia
Health food retail channels concentrate premium organic and raw-format SKUs with higher margin structures. TGA complementary medicine frameworks influence sports nutrition labeling for protein-fortified products. Sydney's fitness studio retail networks extend brand presence through contextual placement strategies.
Energy Balls Market Vendor Landscape
Top-tier vendors anchor premium organic positioning through certified supply chains, while mid-tier specialists compete on minimalist ingredient transparency and protein-forward formulations. The vendor base stratifies across three archetypes: clean-label certification leaders, sports nutrition cross-sellers, and private-label contract manufacturers. Strategic moves concentrate on direct-to-subscription channel expansion and cold-pressing equipment upgrades that enable distributed processing architectures.
Among US-based clean-label specialists, GoMacro and RXBAR exemplify divergent premium positioning strategies. GoMacro occupies a position within certified organic supply chain leadership, while RXBAR anchors minimalist ingredient list transparency. Bounce Foods represents the European protein-forward formulation archetype, sitting within sports nutrition cross-selling expertise. These three companies collectively illustrate how geographic origin and structural focus shape competitive differentiation without requiring identical strategic playbooks.
| Leading Market Players |
|---|
| GoMacro |
| Health Warrior |
| Bounce Foods |
| Betty Lou's Inc. |
| Windmill Organics |
| RXBAR |
| Perfect Snacks |
| Made In Nature, Inc. |
| Larabar |
| Others |
Supply Flow & Price Mechanics
California almond butter spot pricing volatility cascades through energy ball manufacturing into three distinct cost tiers, with certified organic supply chains commanding shelf-space premiums while commodity nut butter formulations compete on unit economics in mass retail channels.
Pricing Analysis
Unbundled ingredient sourcing separates premium-tier positioning from bundled contract-manufacturing arrangements that compress margins. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic certification thresholds and cold-pressing equipment amortization schedules. Pricing pressure stems from California drought-driven almond butter cost spikes that squeeze mid-tier manufacturers lacking forward-contract coverage. Fitness center vending buyers exhibit lowest price sensitivity, while supermarket mass-market purchasers drive hard unit-cost negotiations.
Supply Chain Analysis
Trans-Pacific freight rate fluctuations ripple through nut butter import economics, with containerized shipments from California processing clusters to European co-manufacturers experiencing the most pronounced cost variability. Supply concentrates in the United States for almond and cashew bases, Turkey for organic dried fruits, and Germany for cold-pressing equipment fabrication. Formulation rests on pea protein isolate from Chinese processing facilities, date paste from Algerian cooperatives, and fava bean flour from French organic suppliers. Single-source vulnerability in California almond production exposes margin structures to climate-driven harvest volatility. Distribution runs through natural food distributors to health food stores, direct-to-subscription platforms for bulk formats, and fitness center vending operators for impulse single-serve placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy balls market compounds steadily as gym-culture penetration and clean-label certification requirements create durable pricing power for compliant manufacturers.
For Market Incumbents: To counter private-label encroachment from German retailers REWE and dm-drogerie markt, incumbents should deepen backward integration into certified organic nut butter processing and lock exclusive fitness center vending partnerships through membership bundle programs. For New Entrants and Emerging Players: Subscription box curators represent the most accessible channel partners for bulk container formats targeting metropolitan fitness households. White space concentrates in India's emerging cold-pressed localization opportunity and allergen-free seed-based formulations for school-compliant segments. A direct-to-consumer launch with personalized macronutrient matching captures recurring revenue pools faster than retail shelf-space battles. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers possessing skid-mounted high-pressure processing units and multi-SKU allergen segregation capabilities. The five-to-ten-year viability window favors facilities with EU organic certification and compostable packaging migration readiness. Watch EU sugar-reduction mandate implementation timelines as the critical inflection signal for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Supply Chain Restructuring | USDA and EU organic logos command shelf-space premiums in natural retail channels. |
| Cold-Pressing Equipment Upgrade | Modular HPP units enable distributed processing architectures that compress regional launch lead times. |
| Direct-to-Subscription Channel Expansion | Bulk container formats bypass retail margin stacking while capturing recurring fitness household revenue. |
| Allergen-Free Production Line Segregation | Sunflower seed butter formulations unlock school-compliant and sesame-sensitive consumer segments. |
| Compostable Packaging Migration | EU Single-Use Plastics Directive compliance secures channel access ahead of enforcement deadlines. |
Methodological Framework
Multiple input streams — executive interviews with brand managers and category buyers, supply chain conversations with cold-pressing equipment manufacturers, and regulatory tracking across FDA and EFSA frameworks — were reconciled against Nielsen retail audit data, USDA organic certification databases, and customs records for nut butter imports. Bottom-up SKU-level volume builds were cross-validated through top-down category spend analysis.
Historical shipment patterns were cross-referenced against panel input from sports nutrition formulators and fitness center operators to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product type tier, ingredient source certification grade, packaging format scale, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating gym-culture penetration rates and clean-label adoption thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU sugar-reduction mandate finalization and California water allocation disputes. Forecasts reflect documented assumptions about protein isolate approval timelines and packaging material shelf-life performance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Savory Snack Products Market
Snacks
Low Fat Granola Market
Snacks
Legume-Based Snacks Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
RTE Popcorn Market
Snacks
Europe Snacks Market
Snacks
Trail Mix Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Asia Pacific Snack Food Market
Snacks
North America Snack Pellets Market
Snacks
Low Fat Sweet Snacks Market
Snacks
North America Pretzel Market
Snacks
Non-Potato Veggie Chips Market
Snacks
US Potato Chips Market
Snacks
Gluten Free Snacks Market
Snacks
Low Calorie Dip Market