
 Veggie Meals Market | 2026-2036
Veggie Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Veggie Meals Market Analytics
Food service operators are rotating toward veggie-forward menu development as corporate procurement teams reset supplier criteria. Beyond Meat, Inc. leverages its protein extrusion platform to anchor food service contracts across North American quick-service chains. Impossible Foods Inc. competes on heme-based flavor replication, sustaining premium placement in burger-centric channels. Nestlé S.A. controls frozen meal shelf space through its Garden Gourmet line, dominating European retail resets.
Veggie meals comprise plant-based, ready-to-eat or ready-to-cook food preparations using legumes, grains, vegetables, and textured proteins, typically requiring under fifteen minutes of consumer preparation time and delivering complete macronutrient profiles. Their primary commercial purpose is to replace animal-protein center-of-plate items without sacrificing convenience or sensory satisfaction. Frozen meals lead volume contribution due to extended shelf stability and established cold-chain infrastructure, while meal kits capture margin pools through subscription pricing and ingredient customization. Online retail channels accelerate fastest, reshaping how households discover and replenish plant-based options.
The EU Green Deal and EFSA nutrition claims framework tighten ingredient traceability and restrict certain processed additives across member states, compelling manufacturers to reformulate or exit. The FDA and USDA co-regulate U.S. plant-based labeling disputes, creating compliance friction that delays product launches. Stakeholders must monitor evolving protein-source restrictions and carbon-footprint disclosure mandates to preserve market access and pricing power.
Market Dynamics
Food service procurement teams are rewriting supplier scorecards to prioritize carbon-labeled ingredients and extruded protein formats, forcing manufacturers to retool production lines or surrender shelf space to compliant rivals.
Growth Catalysts
- EU Green Deal carbon-footprint mandates:The framework compels reformulation toward locally sourced legumes and clean-label emulsifiers, opening contract opportunities for processors with verified supply chains.
- Quick-service chain menu rotation:Burger-centric and sandwich channels are expanding veggie-forward permanent items beyond limited-time offers, creating volume commitments that justify dedicated production capacity.
- Pulse protein extrusion advances:High-moisture extrusion of fava and lupin isolates now achieves fibrous textures matching poultry, enabling whole-muscle analogs in frozen meal formats.
Market Restraints
- Pea protein isolate cost volatility:Concentrated sourcing from Canadian and Baltic processors exposes margins to crop yield swings and ocean freight spikes.
- FDA-USDA labeling jurisdiction overlap:Disputes over "meat" and "milk" terminology create launch delays and reformulation costs for cross-border product lines.
- Refrigerated meal kit spoilage rates:Last-mile cold-chain gaps in secondary cities limit geographic expansion and inflate insurance premiums.
Strategic Opportunities
- German retail penetration leadership:Discounters and premium supermarkets alike are resetting planograms for plant-based ready meals, offering slotting fee waivers for innovation leaders.
- High-pressure processing (HPP) convergence with modified-atmosphere packaging:The combination extends refrigerated shelf life to forty-five days without frozen distribution infrastructure.
- CSRD supply-chain disclosure requirements:Early compliance creates competitive separation as downstream buyers face Scope 3 reporting deadlines.
Industry Challenges
- Food technologist specialization gaps:Formulation expertise bridging culinary arts and protein chemistry commands premium compensation, constraining R&D throughput at mid-tier processors.
- EFSA novel food authorization timelines:Fermented mycoprotein and precision-fermentation ingredients face twenty-four to thirty-six month safety evaluations, delaying pipeline commercialization.
- Legacy ERP integration with batch-level traceability:Existing manufacturing execution systems require costly middleware to meet EU digital product passport requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veggie Meals Market |
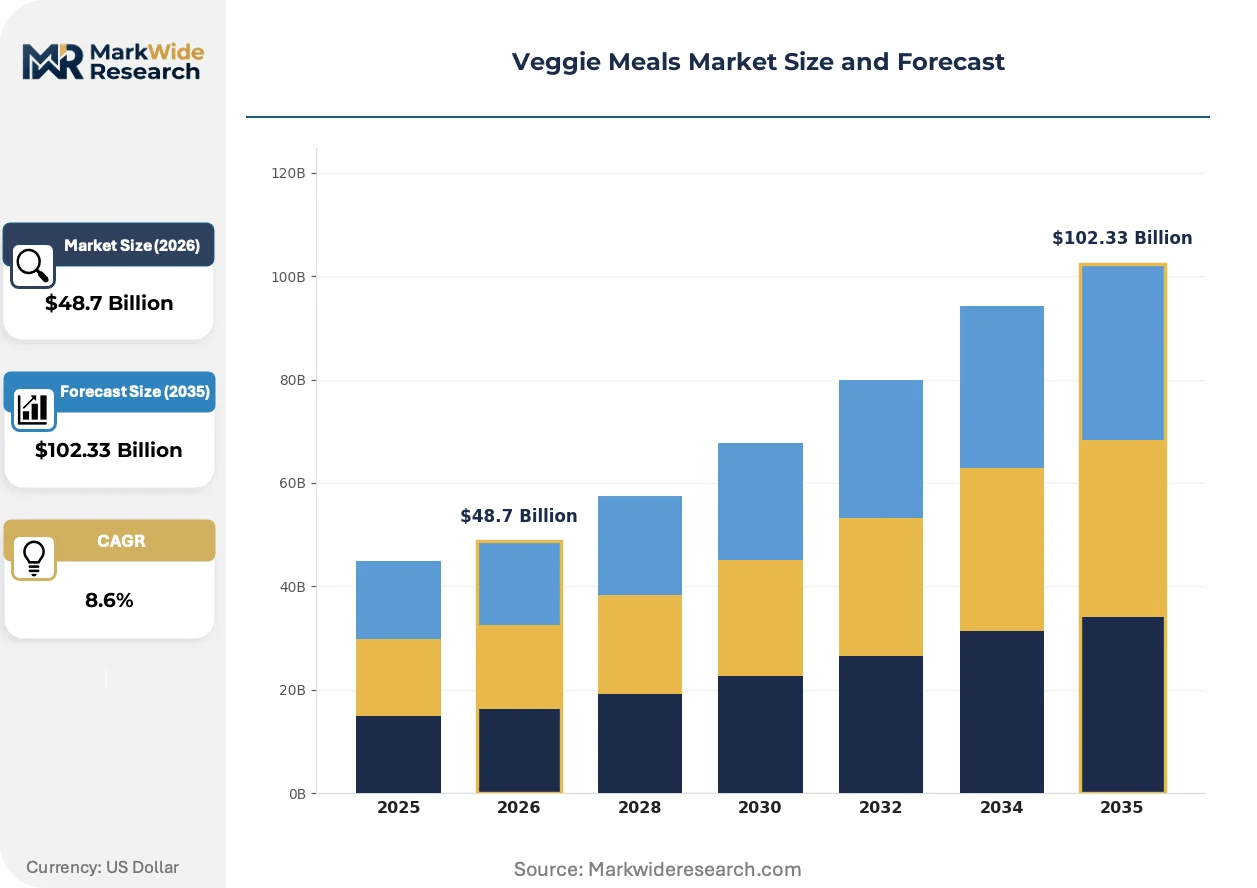
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Meal Kits, Snacks, Soups End User: Households, Food Service, Schools, Restaurants Distribution Channel: Online Retail, Supermarkets, Health Stores, Convenience Stores Price Tier: Affordable, Premium, Organic, Bulk |
| Companies Covered | Beyond Meat, Inc., Impossible Foods Inc., Nestlé S.A., Kellogg Company, Conagra Brands, Inc., Amy’s Kitchen, Inc., Quorn Foods, Hain Celestial Group, Lightlife Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veggie Meals Market Evolving Landscape
Extrusion technology, regulatory disclosure mandates, and channel fragmentation are simultaneously elevating product performance standards and compressing go-to-market timelines for new entrants.
High-moisture extrusion is bifurcating the textured protein landscape. The technology transforms pulse and oilseed flours into anisotropic fibers that replicate chicken breast mouthfeel. Frozen meal manufacturers in Germany and the Netherlands are adopting twin-screw systems at pilot scale, while North American contract manufacturers lag on capital deployment. The capability gap is concentrating premium private-label supply among equipment-heavy European processors.
EFSA's evolving nutrition claims framework is tightening permissible health assertions on plant-based packaging. The regulator now requires substantiated protein quality scores and amino acid completeness disclosures, disqualifying blends with limiting amino acids from "high protein" labeling. Ready-to-eat meal producers are responding by fortifying with lysine and methionine or abandoning claim-dependent positioning entirely.
Subscription meal kit purchasing is fragmenting traditional grocery replenishment patterns. German households under thirty-five are rotating between three to four competing services quarterly, eroding brand loyalty and forcing providers into aggressive introductory pricing. The churn dynamic is most acute in Berlin and Munich, where density supports multiple last-mile fulfillment models and switching costs approach zero.
Veggie Meals Market Segmentation
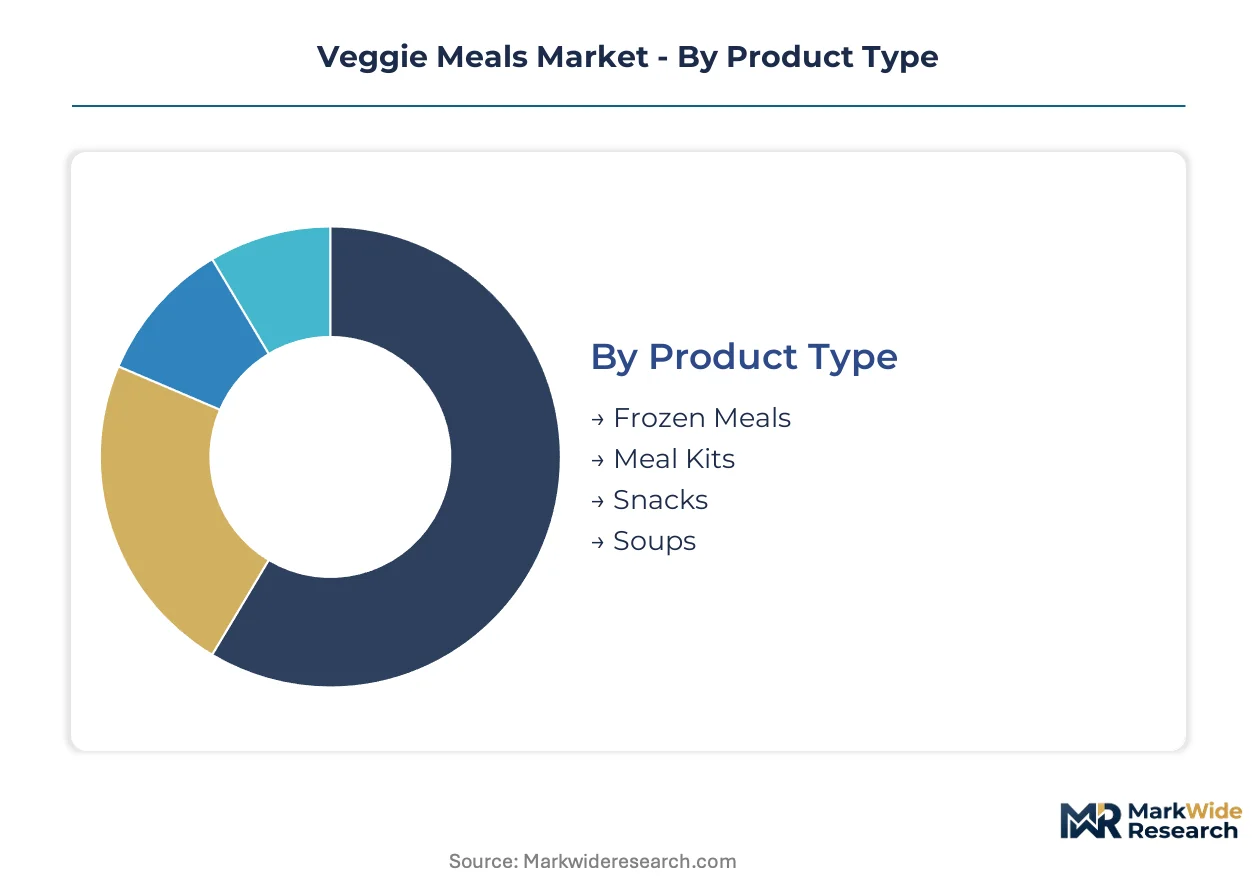
Segmentation in the veggie meals market reveals where procurement power and margin capture diverge. Frozen formats and food service contracts anchor volume economics, while meal kits and premium tiers extract value through convenience positioning and ingredient provenance claims.
Product Type:
Margin pools concentrate in frozen meals and meal kits, where shelf stability and subscription pricing create divergent profitability models.
- Frozen Meals:These products combine extended shelf life with established cold-chain infrastructure, enabling mass-market penetration through retail freezer resets. German discounters and Dutch supermarkets drive procurement volume for extruded-protein center-of-plate formats, with EFSA clean-label requirements forcing reformulation investments that compliant processors recover through slotting fee reductions.
- Meal Kits:Pre-portioned ingredients with recipe cards capture recurring revenue through subscription mechanics, though Berlin and Munich households exhibit quarterly service rotation that erodes lifetime value. High spoilage rates in last-mile distribution constrain geographic expansion beyond primary urban corridors.
- Snacks:Plant-based protein bars and savory bites target impulse purchase occasions through convenience store placement.
- Soups:Shelf-stable and refrigerated formats compete for refrigerated case space against fresh prepared alternatives.
Frozen meals hold installed capacity. Meal kits are rotating up the share rankings.
End User:
Volume concentration splits between household replenishment patterns and food service procurement scale, with divergent specification requirements.
- Households:Weekly grocery replenishment drives private-label penetration, with German households under thirty-five exhibiting the highest trial rates for plant-based ready meals. Online channel migration accelerates discovery but fragments loyalty across competing retailers.
- Food Service:Quick-service chains and contract caterers specify carbon-labeled ingredients and extruded protein formats, with procurement teams rewriting supplier scorecards to prioritize verified supply chains. North American burger-centric channels are expanding permanent veggie-forward items beyond limited-time offers.
- Schools:Public procurement frameworks in EU member states increasingly mandate plant-forward menu ratios.
- Restaurants:Independent operators seek flexible portion formats that minimize kitchen labor and inventory complexity.
Food service holds installed capacity. Households are rotating up the share rankings.
Distribution Channel:
Channel economics favor online retail's discovery mechanics and supermarket scale, with health stores capturing niche premium positioning.
- Online Retail:Subscription platforms and direct-to-consumer sites accelerate trial through algorithmic personalization, though customer acquisition costs inflate as German market density supports multiple competing fulfillment models. The channel climbs the fastest among all distribution pathways.
- Supermarkets:Planogram resets in Germany and the Netherlands concentrate shelf space among processors with extrusion capabilities, with slotting fee negotiations favoring innovation leaders over legacy frozen brands.
- Health Stores:Specialty retailers curate organic and allergen-free assortments for dedicated plant-based consumers.
- Convenience Stores:Grab-and-go placement targets immediate consumption occasions with limited cold-chain requirements.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
Price Tier:
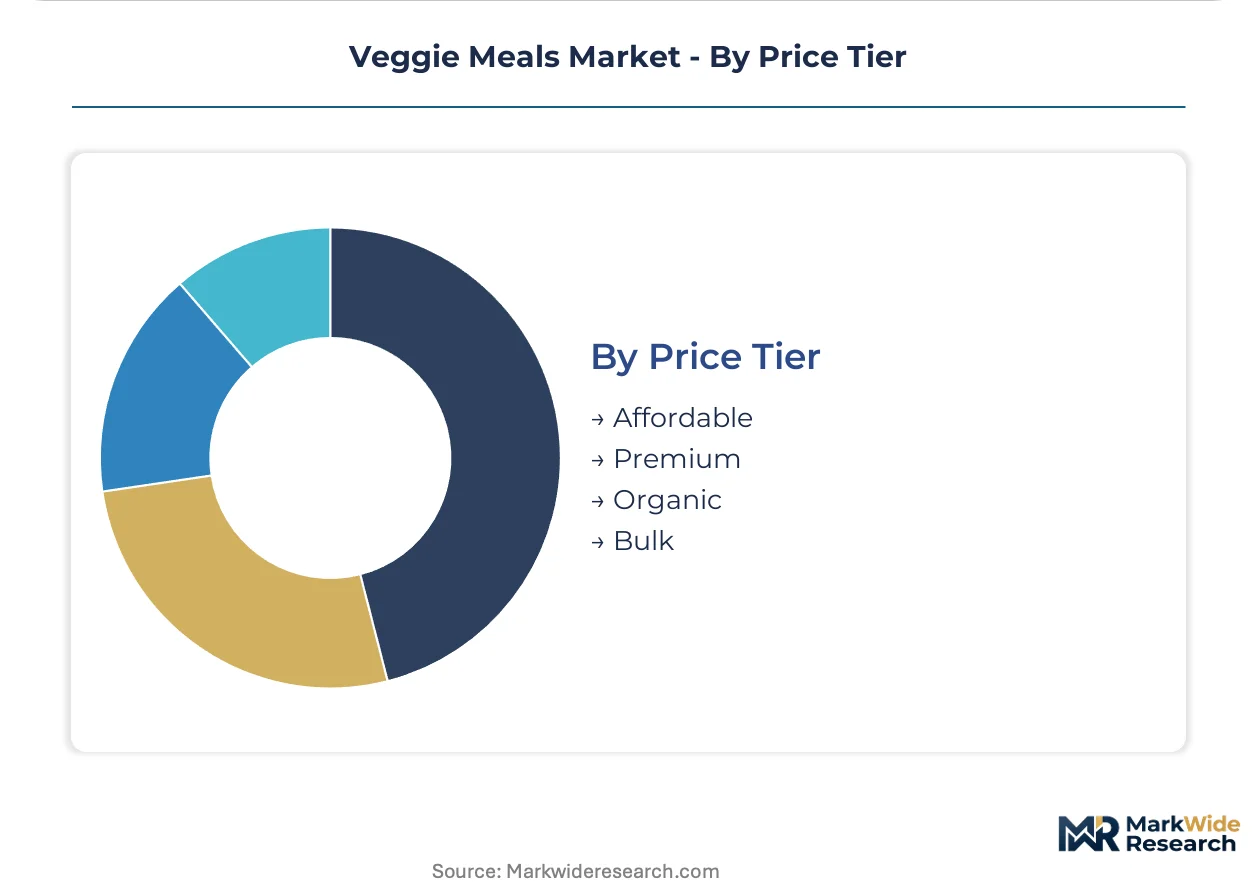
Premium and organic tiers extract value through ingredient provenance and certification claims, while affordable tiers compete on unit economics at scale.
- Premium:High-moisture extruded proteins and chef-developed recipes justify price positioning through sensory performance matching animal-protein benchmarks. German premium supermarkets reset planograms to capture this margin pool.
- Organic:EU Green Deal carbon-footprint disclosure requirements and EFSA traceability mandates create competitive separation for certified supply chains, with early CSRD compliance becoming a procurement differentiator.
- Affordable:Private-label penetration targets price-sensitive households through simplified formulations and bulk packaging formats.
- Bulk:Food service and institutional buyers prioritize unit cost minimization over individual portion convenience.
Premium holds installed capacity. Organic is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion equipment and cold-chain infrastructure cluster in Germany and the Netherlands, while North American contract manufacturers lag on capital deployment. This capability gap concentrates premium private-label supply among European processors with verified supply chains and carbon-labeled ingredient sourcing.
Germany
Discounters and premium supermarkets drive procurement volume for extruded-protein center-of-plate formats, with EFSA clean-label requirements forcing reformulation investments. The EU Green Deal carbon-footprint mandates compel manufacturers toward locally sourced legumes. Berlin and Munich households exhibit the highest trial rates for plant-based ready meals, with density supporting multiple competing fulfillment models.
United States
Quick-service chains expand permanent veggie-forward items beyond limited-time offers, creating volume commitments that justify dedicated production capacity. FDA-USDA labeling jurisdiction overlap creates launch delays and reformulation costs for cross-border product lines. California and Texas anchor food service contract growth, with procurement teams rewriting supplier scorecards to prioritize carbon-labeled ingredients.
Netherlands
Twin-screw extrusion systems operate at pilot scale for frozen meal manufacturers targeting German retail penetration. EFSA nutrition claims framework tightens permissible health assertions on plant-based packaging. The Rotterdam-The Hague corridor hosts processors adopting high-pressure processing convergence with modified-atmosphere packaging to extend refrigerated shelf life.
United Kingdom
Subscription meal kit purchasing fragments traditional grocery replenishment patterns among households under thirty-five. CSRD supply-chain disclosure requirements create competitive separation as downstream buyers face Scope 3 reporting deadlines. London and Manchester concentrate last-mile fulfillment innovation, though churn dynamics erode lifetime value through aggressive introductory pricing.
Canada
Pea protein isolate sourcing from Prairie processors exposes margins to crop yield swings and ocean freight spikes. Health Canada nutrition labeling standards intersect with provincial procurement frameworks for institutional plant-forward menu ratios. Toronto and Vancouver anchor retail freezer resets, with slotting fee negotiations favoring innovation leaders over legacy frozen brands.
Veggie Meals Market Competitive Landscape
Concentration sits with multinational food conglomerates and specialized plant-protein innovators. The vendor base splits between legacy packaged food corporations controlling frozen shelf space through established retail relationships, and venture-backed protein technology firms competing on extrusion capabilities and heme-based flavor replication. Three archetypes dominate: diversified conglomerates with global distribution networks, pure-play protein technology developers, and mid-tier contract manufacturers serving private-label demand. Competitive moves center on strategic partnerships with food service operators and capacity expansion in high-moisture extrusion equipment.
Within the protein technology tier, Beyond Meat, Inc. and Impossible Foods Inc. exemplify divergent technical approaches to sensory replication. Among diversified conglomerates, Nestlé S.A. occupies a position representing legacy packaged food corporations leveraging frozen meal infrastructure and European retail relationships. These three companies anchor the competitive structure, with technology licensing and food service contract scale serving as the primary vectors for market position.
| Leading Market Players |
|---|
| Beyond Meat, Inc. |
| Impossible Foods Inc. |
| Nestlé S.A. |
| Kellogg Company |
| Conagra Brands, Inc. |
| Amy's Kitchen, Inc. |
| Quorn Foods |
| Hain Celestial Group |
| Lightlife Foods |
| Others |
Value Network & Pricing Analysis
Extrusion equipment utilization rates above 80% in German and Dutch processing facilities create cost advantages that cascade through frozen meal pricing tiers, compressing margins for North American contract manufacturers lacking comparable scale. This capacity asymmetry concentrates premium private-label supply among European processors while forcing smaller competitors toward commodity positioning or exit.
Pricing Analysis
Volume-discount tiering structures dominate procurement between food service operators and extruded protein suppliers, with annual contract commitments exceeding 500 metric tons triggering 12-15% unit cost reductions. Pricing stratifies across premium, standard, and economy tiers based on protein content certification and carbon-label verification status. Cost compression in the economy tier is intensifying because Baltic pea protein isolate sourcing faces ocean freight volatility. Quick-service chains exhibit lowest price sensitivity due to menu price elasticity, while German discounters drive hardest bargain negotiations.
Supply Chain Analysis
Canada and the Baltic states anchor pea protein isolate production, with German and Dutch processors commanding twin-screw extrusion capacity for fibrous texture replication. Raw material flows draw from Prairie legume cultivation, Canadian rail corridors, and Rotterdam port logistics. Single-source vulnerability concentrates in mycoprotein fermentation facilities facing EFSA novel food authorization delays. Distribution runs through integrated cold-chain networks serving retail freezer resets and food service direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel fragmentation across subscription meal kits, quick-service procurement, and retail freezer resets creates multiple entry vectors for specialists lacking conglomerate scale. German household trial rate elevation above European benchmarks signals white-space availability for targeted positioning.
For Market Incumbents: Secure exclusive extrusion capacity through equipment financing partnerships with German and Dutch contract manufacturers before capital deployment gaps widen. Nestlé's Garden Gourmet line demonstrates how frozen shelf space control neutralizes emerging protein technology threats. Prioritize CSRD-compliant supply chain disclosure to maintain procurement scorecard eligibility as EU Green Deal mandates tighten. For New Entrants and Emerging Players: Differentiate on high-pressure processing convergence with modified-atmosphere packaging to capture 45-day refrigerated shelf life premiums without frozen infrastructure investment. Target Berlin and Munich meal kit subscribers exhibiting quarterly service rotation and near-zero switching costs. Lead with carbon-labeled ingredient provenance to bypass slotting fee barriers at German premium supermarkets. For Investors and Strategic Acquirers: Mid-tier contract manufacturers with installed twin-screw extrusion systems and EFSA clean-label compliance represent the most defensible acquisition archetype as capacity scarcity intensifies. Long-term viability hinges on food service contract duration extension beyond limited-time offers into permanent menu placement. Watch for FDA-USDA labeling jurisdiction resolution as inflection signal for cross-border product line expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | European processors with twin-screw systems capture premium private-label contracts from German retail resets. |
| Carbon-Label Supply Chain Certification | EU Green Deal compliance creates procurement differentiation for verified legume sourcing across member states. |
| Food Service Contract Scale-Up | Quick-service permanent menu placement justifies dedicated production lines beyond limited-time offer economics. |
| High-Pressure Processing Adoption | HPP convergence with modified-atmosphere packaging extends refrigerated shelf life without frozen distribution infrastructure. |
| Direct-to-Consumer Subscription Launch | Algorithmic personalization accelerates trial among German households under thirty-five exhibiting highest category engagement. |
Research Methodology
Desk research of EFSA novel food authorization databases, EU Green Deal regulatory filings, and food service procurement contract disclosures preceded structured interviews with extrusion technology suppliers, frozen meal category buyers at German discounters, and quick-service chain procurement directors. Primary fieldwork with pulse protein processors and meal kit fulfillment operators combined with secondary validation through customs trade data and cold-chain logistics provider capacity reports. Bottom-up segment sizing triangulated against top-down market value reconstruction across product type, end user, and distribution channel dimensions.
Variance decomposition across volume and value projections isolates drivers including extrusion equipment deployment rates, EFSA clean-label reformulation timelines, and food service contract conversion from limited-time to permanent menu status. Segmentation modeling incorporated product format, buyer archetype, channel economics, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to observed capacity utilization and procurement scorecard adoption rates. Industry-specific inputs included pea protein isolate spot price volatility indices and twin-screw extrusion system order backlogs.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable FDA-USDA jurisdictional boundaries; material deviation in either would warrant model refresh. Specific risk factors include EFSA novel food authorization timeline extension beyond historical thirty-six month averages and Baltic pea protein crop yield disruption from climate variability. Recalibration cycles align with material shifts in carbon-footprint disclosure mandates and food service procurement team supplier scorecard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Vegan Flavor Market