
 Packaged Rice Snacks Market | 2026-2036
Packaged Rice Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Rice Snacks Market Outlook
Whole-grain brown rice is shifting into formulations traditionally dominated by white rice, altering cost structures and nutritional positioning across the category. PepsiCo leverages its global distribution infrastructure to sustain volume leadership in puffed and extruded formats. Kameda Seika anchors its competitive stance through specialized rice cracker expertise honed over decades in Japan. Lundberg Family Farms differentiates via organic and regenerative sourcing credentials that command premium placement in natural retail channels.
Packaged rice snacks comprise processed rice-based foods manufactured through extrusion, puffing, baking, or frying, typically containing 60-95% rice content with seasoning, binding agents, and shelf-stabilizing ingredients designed for ambient storage and on-thego consumption. Salty snacks occupy the largest revenue pool due to established savory flavor systems and bar-format portability, while rice cakes represent the fastest-expanding segment as gluten-free and low-calorie positioning attracts wellness-oriented adults. Flexible bags dominate packaging economics through lightweight material efficiency and high-speed filling compatibility, though pouches with resealable closures are capturing incremental share in online retail channels where shipping durability matters.
FDA nutrition-labeling requirements and the USDA organic certification framework govern product claims and ingredient transparency in the United States, directly influencing reformulation investments and packaging disclosure protocols. EFSA health claim evaluations and EU Regulation on food information to consumers shape parallel compliance burdens for exporters serving European retail banners. Stakeholders must monitor evolving sodium thresholds and front-of-pack labeling mandates to anticipate which product architectures will retain distribution access across major retail networks.
Market Dynamics
Clean-label reformulations and sodium-reduction mandates are forcing manufacturers to rebuild processing lines and ingredient sourcing relationships across the packaged rice snacks category. The shift from white rice to whole-grain brown rice base materials requires new extrusion parameters and altered shelf-life management protocols.
Growth Catalysts
- US FDA Sodium Reduction Guidelines:Mandatory sodium thresholds in processed foods are accelerating low-sodium rice cake development and creating compliant product lines that secure retail distribution in conventional grocery channels.
- Gluten-Free Positioning:Celiac disease diagnosis rates and wheat-avoidance dietary patterns among wellness-oriented consumers are expanding the addressable consumer base for rice-based alternatives to wheat crackers and bread.
- Working Adult Convenience Demand:Single-serve bar formats and resealable pouch packaging are capturing commuter and office consumption occasions previously served by fresh bakery items.
Market Restraints
- Input Cost Volatility:Brown rice premiums over white rice base materials fluctuate with harvest yields in Arkansas and California, compressing margin structures for organic-positioned product lines.
- Supply Concentration Risk:Specialized organic rice milling capacity clusters in the Sacramento Valley, creating geographic vulnerability to drought-induced supply interruptions.
- Technical Shelf-Life Limitation:Clean-label formulations without synthetic preservatives exhibit shorter ambient stability windows, constraining distribution radius and inventory turns.
Strategic Opportunities
- Regenerative Agriculture Certification:USDA Organic plus regenerative sourcing credentials command price premiums in natural retail channels and unlock shelf placement with Whole Foods Market and Sprouts Farmers Market.
- Direct-to-Consumer Subscription Models:Monthly snack box services bypass conventional slotting fee structures and capture recurring revenue from millennial households.
- Protein-Fortified Formulations:Pea protein and brown rice protein integration targets fitness-oriented consumers seeking macronutrient-balanced snacking alternatives.
Industry Challenges
- Extrusion Engineering Talent Scarcity:Specialized knowledge in whole-grain rice extrusion parameters remains concentrated among aging equipment specialists, constraining production scale-up timelines.
- Clean-Label Certification Complexity:Simultaneous pursuit of Non-GMO Project Verified, USDA Organic, and Certified Gluten-Free designations extends product development cycles and multiplies third-party audit costs.
- Legacy Equipment Retrofit Requirements:Existing white-rice processing lines require capital-intensive modification to handle higher-fiber brown rice formulations without texture degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Rice Snacks Market |
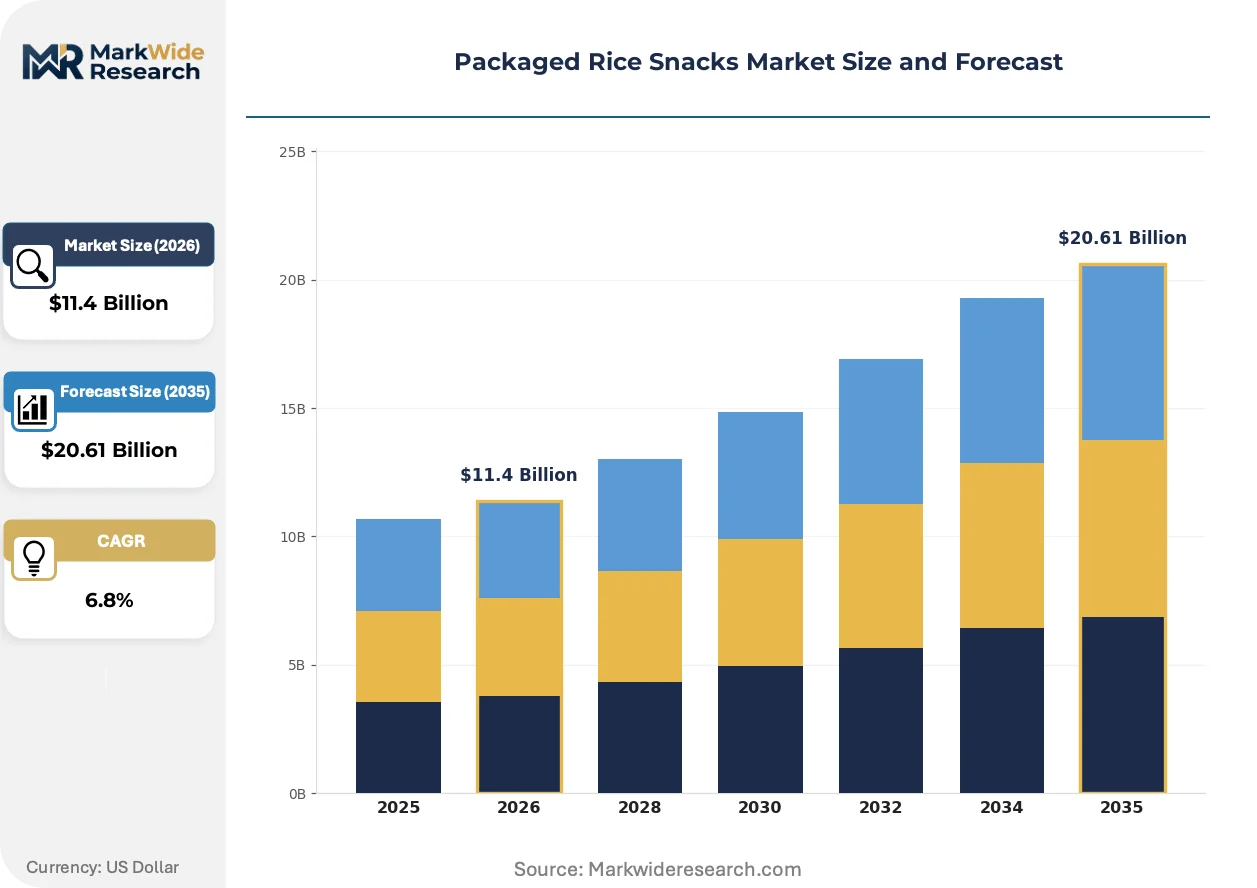
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salty Snacks, Sweet Snacks, Puffed Rice, Rice Cakes Packaging Type: Flexible Bags, Rigid Containers, Pouches, Boxes End User: Children, Teenagers, Adults, Seniors Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores |
| Companies Covered | Mars Incorporated, General Mills Inc., PepsiCo Inc., Calbee, Inc., SanoRice Holding BV, Kameda Seika Co., Ltd., Ricegrowers Limited (SunRice), Element Snacks Inc., Lundberg Family Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Rice Snacks Market Strategic Shifts
Processing technology advances and regulatory disclosure mandates are restructuring competitive advantage around transparency credentials and production efficiency rather than flavor innovation alone.
Air-puffing technology is overtaking traditional oil-frying methods for rice cake production, reducing fat content while maintaining structural integrity. Wellness-oriented retailers and private-label buyers are specifying air-puffed specifications in procurement contracts. This shift is compressing demand for legacy frying equipment and favoring suppliers with modified atmospheric processing capabilities.
EU Regulation on food information to consumers mandates expanded ingredient origin disclosure and front-of-pack nutritional labeling. Exporters serving German and French retail banners must reformulate to meet stricter sodium thresholds than US domestic products. Rice cracker manufacturers are responding by standardizing European-compliant recipes across production facilities to simplify inventory management.
Subscription-based replenishment models are displacing conventional impulse purchases in pantry-stocking behavior. Millennial households in coastal metropolitan areas favor automated delivery of low-sodium, organic-certified rice snacks. This pattern concentrates order volume with direct-to-consumer brands and reduces price sensitivity through convenience bundling.
Packaged Rice Snacks Market Segmentation
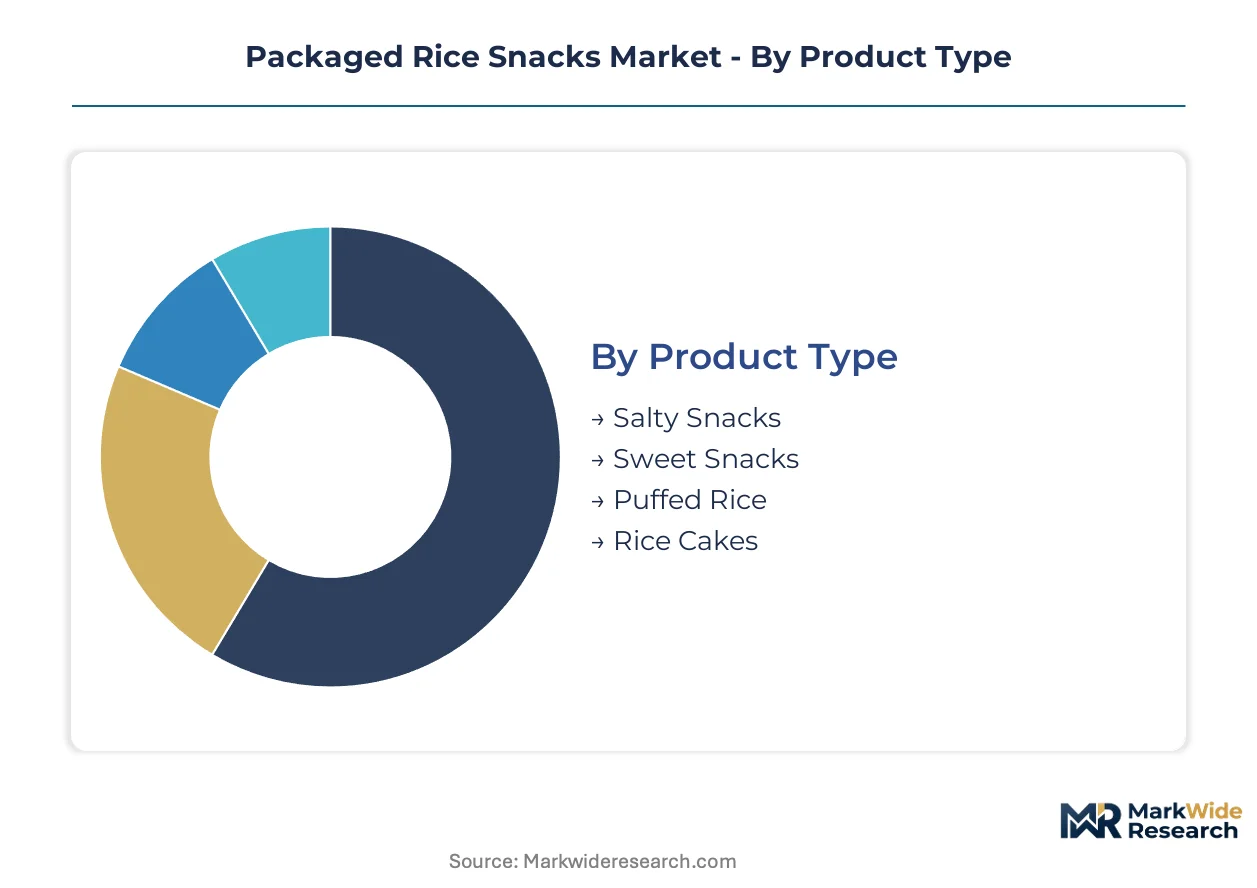
Segmentation in packaged rice snacks reveals how processing technology, packaging engineering, and demographic targeting create distinct margin profiles and shelf-space economics across retail channels.
Product Type:
Extrusion parameters and moisture content specifications differentiate competitive positioning across the four core product architectures.
- Salty Snacks:Seasoned rice crackers and savory puffed formulations contain 60-80% rice flour with soy sauce, seaweed, or chili coatings. Demand concentrates in Japanese and Korean retail banners where traditional senbei consumption persists alongside Western savory flavor adaptations.
- Rice Cakes:Compressed whole-grain brown rice discs achieve 90-95% rice content through high-pressure extrusion without binding agents. Wellness-oriented adults in California and New York metropolitan areas drive volume for organic-certified, low-sodium variants that command premium placement in natural grocery.
- Sweet Snacks:Glazed or chocolate-coated rice-based confections target impulse purchase occasions in Asian convenience retail.
- Puffed Rice:Expanded white or brown rice kernels serve as ingredient inputs for cereal bars and direct consumption in South Asian markets.
Mature deployment sits with salty snacks. Newer deployment is concentrated in rice cakes.
Packaging Type:
Material cost tiers and shelf-life engineering requirements shape procurement specifications across channel buyers.
- Flexible Bags:Multi-layer polyethylene and polypropylene laminates dominate high-velocity SKUs through lightweight shipping economics and vertical form-fill-seal compatibility. Supermarket private-label programs in the United States specify flexible bag formats for 70% of rice snack SKUs to maximize case packing density.
- Pouches:Stand-up pouches with resealable zipper closures incorporate aluminum oxide barrier layers for 12-18 month ambient stability. Online retailers including Amazon and Thrive Market mandate pouch specifications for subscription snack boxes to withstand parcel shipping stress.
- Rigid Containers:Polypropylene tubs with snap-fit lids protect fragile rice cracker integrity in club store bulk formats.
- Boxes:Paperboard folding cartons serve gift-oriented premium assortments in Japanese department store channels.
Volume leadership belongs to flexible bags. Margin expansion concentrates in pouches.
End User:
Life-stage nutritional requirements and snacking occasion patterns determine formulation sodium levels and serving size architectures.
- Adults:Working professionals aged 25-45 purchase single-serve bar formats and resealable pouches for desk and commuter consumption. Low-sodium, high-fiber positioning aligns with FDA dietary guideline awareness in U.S. urban markets.
- Children:School-lunch-compatible formats drive demand for allergen-free, nut-free rice cake varieties in North American and European markets. Portion-controlled 20-30 gram packs satisfy institutional procurement specifications.
- Teenagers:Bold flavor innovation and social media packaging aesthetics influence trial purchase in convenience retail.
- Seniors:Soft-texture rice puffs address chewing difficulty in Japanese and South Korean aging demographics.
Premium pricing power sits with adult-targeted wellness positioning. Volume expansion concentrates in child-oriented allergen-free segments.
Distribution Channel:
Slotting fee structures and inventory turn requirements create divergent product-mix strategies across retail formats.
- Supermarkets:Conventional grocery banners in the United States and Western Europe stock 40-60 rice snack SKUs across national brands and private-label lines. Reset schedules every 12-18 months favor proven velocity performers with established household penetration metrics.
- Online Retailers:Direct-to-consumer platforms and Amazon marketplace sellers bypass slotting fees while capturing subscription recurring revenue. California-based wellness brands leverage this channel to test novel flavor prototypes before conventional retail expansion.
- Convenience Stores:Grab-and-go single-serve pricing at $1.49-$2.99 price points targets immediate consumption occasions in Japanese kombini and U.S. urban bodega networks.
- Specialty Stores:Natural food co-ops and Asian grocery independents curate imported Japanese and Korean premium lines with authentic regional flavor profiles.
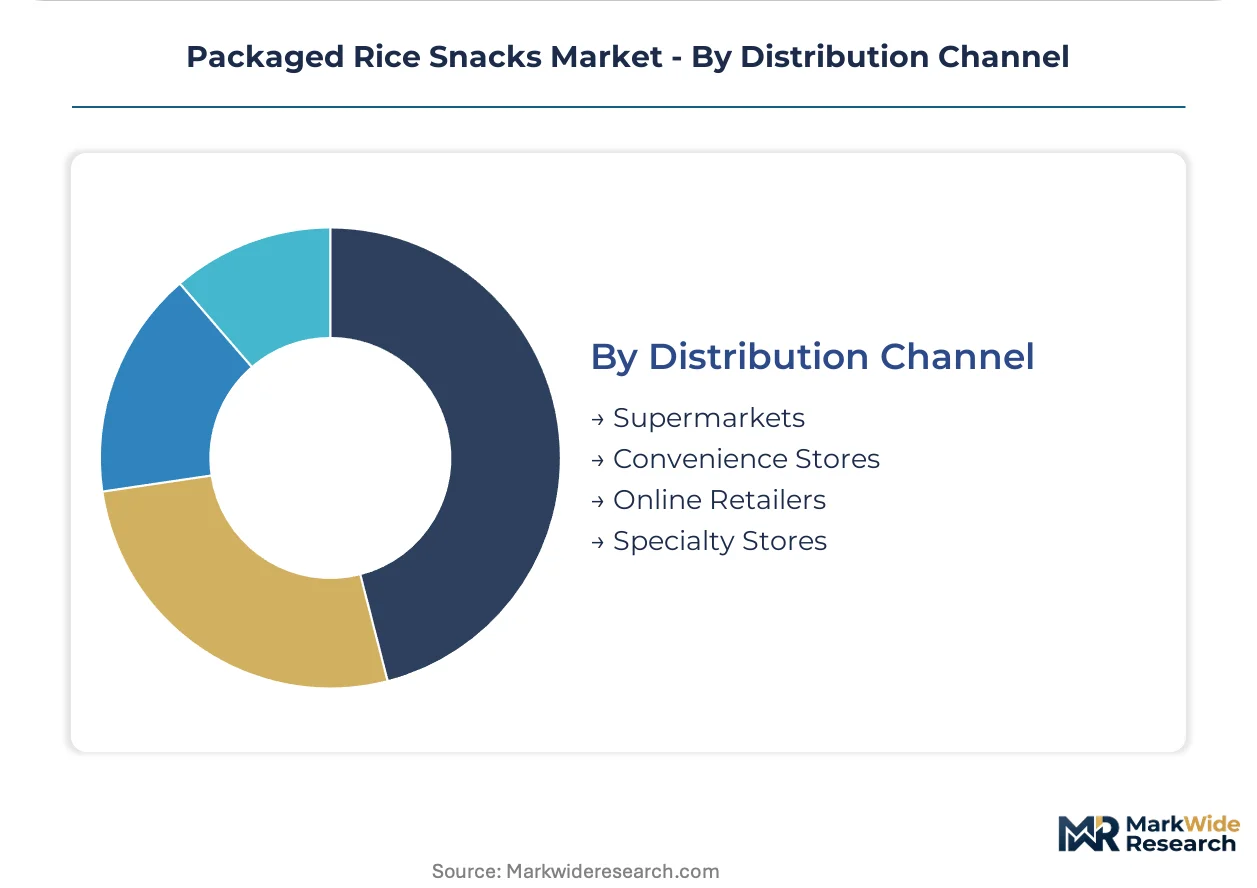
Scale economics concentrate in supermarkets. Growth velocity concentrates in online retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for packaged rice snacks concentrates in the United States, where private-label expansion and premium organic lines capture wellness-oriented millennials and working adults seeking low-sodium, whole-grain alternatives.
United States
FDA sodium-reduction guidelines and clean-label preferences drive reformulation investments across conventional grocery channels. The USDA organic certification framework governs premium positioning claims in natural retail. Sacramento Valley milling clusters supply organic brown rice base materials to California-based wellness brands.
Japan
Traditional senbei consumption persists alongside Western savory flavor adaptations in aging demographics seeking soft-texture rice puffs. METI standards on food manufacturing shape processing equipment specifications. Kanto region production facilities anchor specialized rice cracker expertise honed over decades.
Germany
Gluten-free dietary patterns and wheat-avoidance trends expand the addressable consumer base for rice-based alternatives. EFSA health claim evaluations and EU Regulation on food information to consumers mandate expanded ingredient origin disclosure. Bavaria-based distributors serve as entry points for European-compliant recipe standardization.
Australia
Regenerative agriculture certification commands price premiums in natural retail channels aligned with sustainability positioning. The country's national food standards regulator oversees allergen-free labeling requirements for school-lunch-compatible formats. Riverina region rice growing districts supply base materials to domestic processing facilities.
South Korea
Air-puffing technology adoption reduces fat content in rice cake production for fitness-oriented consumers. MFDS nutritional labeling requirements shape front-of-pack disclosure protocols. Seoul metropolitan area convenience retail networks drive single-serve bar format demand for commuter consumption.
Packaged Rice Snacks Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers rebuild processing lines to handle whole-grain brown rice formulations. The vendor base spans multinational conglomerates with global distribution infrastructure, regional specialists with decades of category expertise, and organic-certified family operations commanding premium placement. Three archetypes define competitive positioning: scale-driven volume leaders, heritage specialists in traditional formats, and regenerative-sourcing premium brands. M&A activity and strategic partnerships concentrate around clean-label certification capabilities and direct-to-consumer channel access.
Among multinational conglomerates, PepsiCo Inc. and Mars Incorporated occupy positions as scale-driven volume leaders leveraging global distribution networks. Within the heritage specialist tier, Kameda Seika Co., Ltd. exemplifies decades-honed rice cracker expertise, while Lundberg Family Farms represents the regenerative-sourcing archetype commanding premium shelf placement in natural retail channels.
| Leading Market Players |
|---|
| Mars Incorporated |
| General Mills Inc. |
| PepsiCo Inc. |
| Calbee, Inc. |
| SanoRice Holding BV |
| Kameda Seika Co., Ltd. |
| Ricegrowers Limited (SunRice) |
| Element Snacks Inc. |
| Lundberg Family Farms |
| Others |
Value Chain & Pricing Dynamics
Wellness-oriented procurement specifications for USDA Organic and Non-GMO Project Verified certifications are forcing manufacturers to secure brown rice supply from qualified Sacramento Valley milling clusters, compressing margin structures as input premiums widen over conventional white rice base materials.
Pricing Analysis
Volume leadership concentrates in flexible bag formats sold through supermarket private-label programs, while margin expansion accrues to pouch-packaged organic lines in direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates regenerative-certified organic products from conventional USDA Organic variants and mass-market white-rice formulations. Pricing pressure stems from brown rice harvest yield volatility in Arkansas and California growing regions. Mass-market conventional products exhibit highest price sensitivity, while regenerative-certified lines retain pricing power through scarcity positioning.
Supply Chain Analysis
USDA Organic and Certified Gluten-Free qualification requirements gate supply relationships, with certified milling capacity clustering in the Sacramento Valley, Arkansas Delta, and Riverina region of Australia. Base material sourcing draws from specialized organic brown rice cultivation, food-grade packaging laminates, and clean-label binding agents. Single-source vulnerability concentrates in California organic milling infrastructure exposed to drought-induced supply interruptions. Distribution runs through conventional grocery wholesale networks, natural food distributors, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized organic rice milling capacity constraints in the Sacramento Valley are propping pricing premiums for certified base materials, creating supply-constrained conditions that favor incumbent positioning and selective new entrant targeting.
For Market Incumbents: Deepen backward integration into certified organic rice cultivation through long-term grower contracts in Arkansas and California to secure base material access against drought-induced supply interruptions. Fortify extrusion engineering capabilities through targeted recruitment from aging specialist talent pools to accelerate whole-grain brown rice production scale-up timelines. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel entry point, bypassing conventional slotting fee barriers while capturing recurring revenue from millennial households in coastal metropolitan areas. Target protein-fortified rice cake formulations for fitness-oriented consumers seeking macronutrient-balanced snacking alternatives. For Investors and Strategic Acquirers: The window for entry favors regenerative-sourcing premium brands with established Whole Foods Market and Sprouts Farmers Market shelf placement and direct-to-consumer subscription infrastructure. Monitor FDA sodium-reduction guideline enforcement intensity as the inflection signal for conventional grocery channel access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | USDA Organic plus regenerative credentials unlock premium placement with Whole Foods Market and Sprouts Farmers Market. |
| Direct-to-Consumer Subscription Launch | Monthly snack box services bypass slotting fees and capture recurring revenue from millennial households. |
| Protein-Fortified Formulation Development | Pea protein and brown rice protein integration targets fitness-oriented consumers seeking balanced macronutrients. |
| Air-Puffing Equipment Retrofit | Modified atmospheric processing capabilities reduce fat content while meeting wellness retailer procurement specifications. |
| European Recipe Standardization | EFSA-compliant sodium thresholds and front-of-pack labeling enable distribution access across German and French retail banners. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with extrusion equipment specialists, organic rice mill procurement managers, natural grocery category buyers, and clean-label ingredient suppliers. Secondary validation drew from FDA sodium-reduction guidance documents, USDA organic certification databases, EFSA health claim evaluations, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Granularity-level modeling operated at product type, packaging format, end-user demographic, and distribution channel dimensions across the projection horizon. CAGRs derived from segmented growth trajectory analysis incorporating FDA regulatory timeline assumptions, organic brown rice supply elasticity estimates, and channel shift velocity parameters. Industry-specific forecast inputs included extrusion capacity expansion pipelines and regenerative agriculture adoption curves.
Caveats apply where FDA sodium-threshold enforcement intensity, drought-induced organic rice harvest disruptions, or clean-label preservative shelf-life limitations could materially shift the outlook. A model refresh is warranted upon material change in certified organic milling capacity utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Spain Snack Bar Market
Snacks
US Potato Chips Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Meat Snacks Market
Snacks
Low-Fat Tortillas Market
Snacks
Allergy-Free Snacks Market
Snacks
Australia Snack Bar Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
North America Potato Chips Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
United Kingdom Snack Bar Market
Snacks
Snack Products Market
Snacks
Global Snack Food Market
Snacks
Austria Snack Bar Market