
 Potato Chips Market | 2026-2036
Potato Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Chips Market Intelligence
Convenience store channel procurement is consolidating as the fastest-growing end-use vertical within salty snack distribution. PepsiCo leverages its direct-store-delivery infrastructure to dominate shelf placement in this channel. Kellanova anchors its position through branded portfolio depth across multiple price tiers. Calbee competes with localized flavor development tailored to regional palate preferences in Asian markets.
Potato chips are thin-sliced tuber pieces fried or baked in edible oils at temperatures between 175°C and 190°C, then seasoned to achieve a moisture content below 2% for shelf stability and crisp texture; their commercial purpose is to deliver convenient, ready-to-eat snacking occasions across retail and foodservice environments. Flavored varieties command the widest margin pools as consumers trade up from plain salted offerings. Kettle-cooked formats occupy a premium niche where texture differentiation supports higher price realization. Single-serve packaging sustains the highest velocity in vending and convenience channels despite higher per-ounce cost to consumers.
FDA nutrition labeling requirements and EU Green Deal packaging directives shape reformulation priorities and material substitution timelines across multinational supply chains. BIS standards in India and FSSAI additive regulations further fragment compliance burdens for exporters entering emerging consumption markets. Stakeholders must monitor biodegradable film cost curves and acrylamide threshold developments to anticipate capital reallocation needs.
Market Dynamics
Convenience store channel consolidation is compressing shelf access for mid-tier producers while EU Green Deal packaging mandates force simultaneous reformulation and material substitution across multinational supply chains. This dual pressure restructures competitive economics.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable film requirements accelerate capital deployment into compostable barrier technologies, creating first-mover advantages for compliant producers.
- Sun Belt metropolitan corridor:Population concentration in Texas, Florida, and Arizona metro areas sustains per-capita salty snack consumption above national baselines.
- Kettle-cooked texture differentiation:Premium positioning through batch-frying methods captures margin expansion as consumers trade up from commodity flat chips.
Market Restraints
- Edible oil price volatility:Sunflower and palm oil input costs fluctuate with commodity markets, compressing gross margins for producers lacking long-term supply contracts.
- Acrylamide threshold uncertainty:Pending FDA guidance on Maillard reaction byproducts forces defensive reformulation investments without clear regulatory endpoints.
- Single-serve packaging cost structure:Higher per-unit material and labor costs in portion-control formats limit profitability despite velocity advantages.
Strategic Opportunities
- India FSSAI additive harmonization:Alignment of Indian flavor regulations with Codex standards reduces export compliance burden for multinational portfolios.
- Vending channel digitization:Cashless payment integration and real-time inventory monitoring expand addressable occasions in workplace and transit locations.
- Localized flavor development:Regional palate mapping in Southeast Asian markets enables premium pricing through authenticity positioning against standardized global offerings.
Industry Challenges
- Acrylamide mitigation chemistry:Enzymatic asparagine reduction requires specialized food science talent scarce in conventional snack manufacturing operations.
- Biodegradable film line integration:Retrofitting existing form-fill-seal equipment for compostable materials demands capital outlays with unproven throughput rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Chips Market |
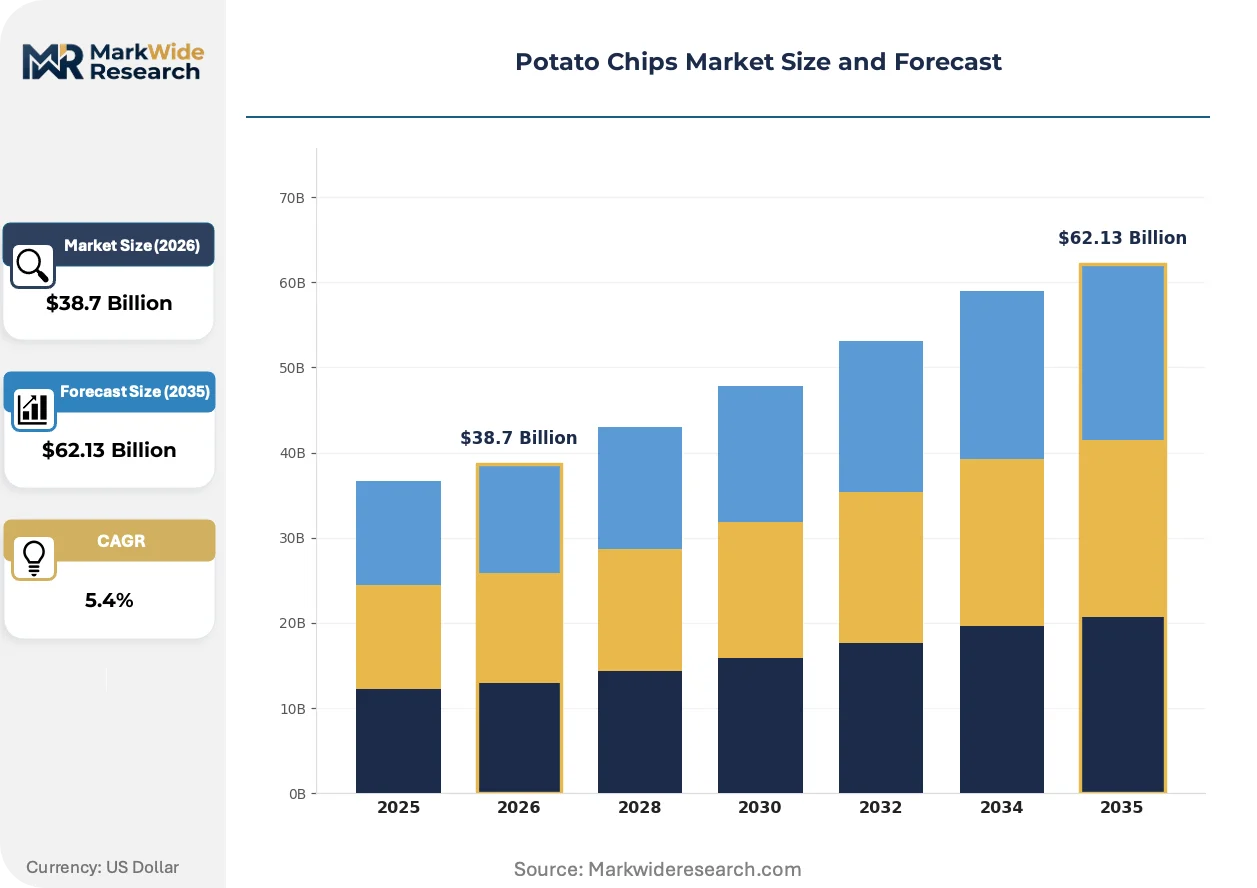
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Baked, Kettle-Cooked, Flavored Ingredient Type: Natural, Organic, Non-GMO, Gluten-Free Packaging Type: Single-Serve, Family Size, Bulk, Resealable Sales Channel: Supermarket, Online, Convenience Store, Vending Machine |
| Companies Covered | PepsiCo, Calbee, Kellanova, Utz Brands, The Campbell's Company, Herr Foods, Intersnack, Mondelez International, Burts Snacks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Chips Market Strategic Shifts & Innovations
Processing automation and regulatory compliance technology are converging to reshape production economics. Material science advances and channel-specific format innovation create parallel transformation tracks.
Hyperspectral sorting systems are automating defect detection in raw potato intake, replacing manual inspection stations with real-time bruise and greening identification. Large-scale processors in the United States deploy these systems to reduce fryer oil degradation and finished-product rejection rates. This compression of quality variability is automating yield optimization across high-volume lines.
EU Green Deal packaging directives mandate biodegradable or recyclable materials by specified timelines, forcing substitution of multi-layer metallized films with mono-material or compostable alternatives. The industrial consequence is accelerated R&D spending on barrier properties and seal integrity in novel substrates. Single-serve and multipack formats face the steepest compliance curves due to complex material lamination requirements.
Direct-store-delivery consolidation among convenience store operators concentrates buyer power and compresses supplier negotiation cycles. National convenience chains now demand category management services and promotional funding commitments that smaller producers cannot match. This pattern is most visible in the United States Sun Belt corridor where chain consolidation has outpaced independent store retention.
Potato Chips Market Segmentation
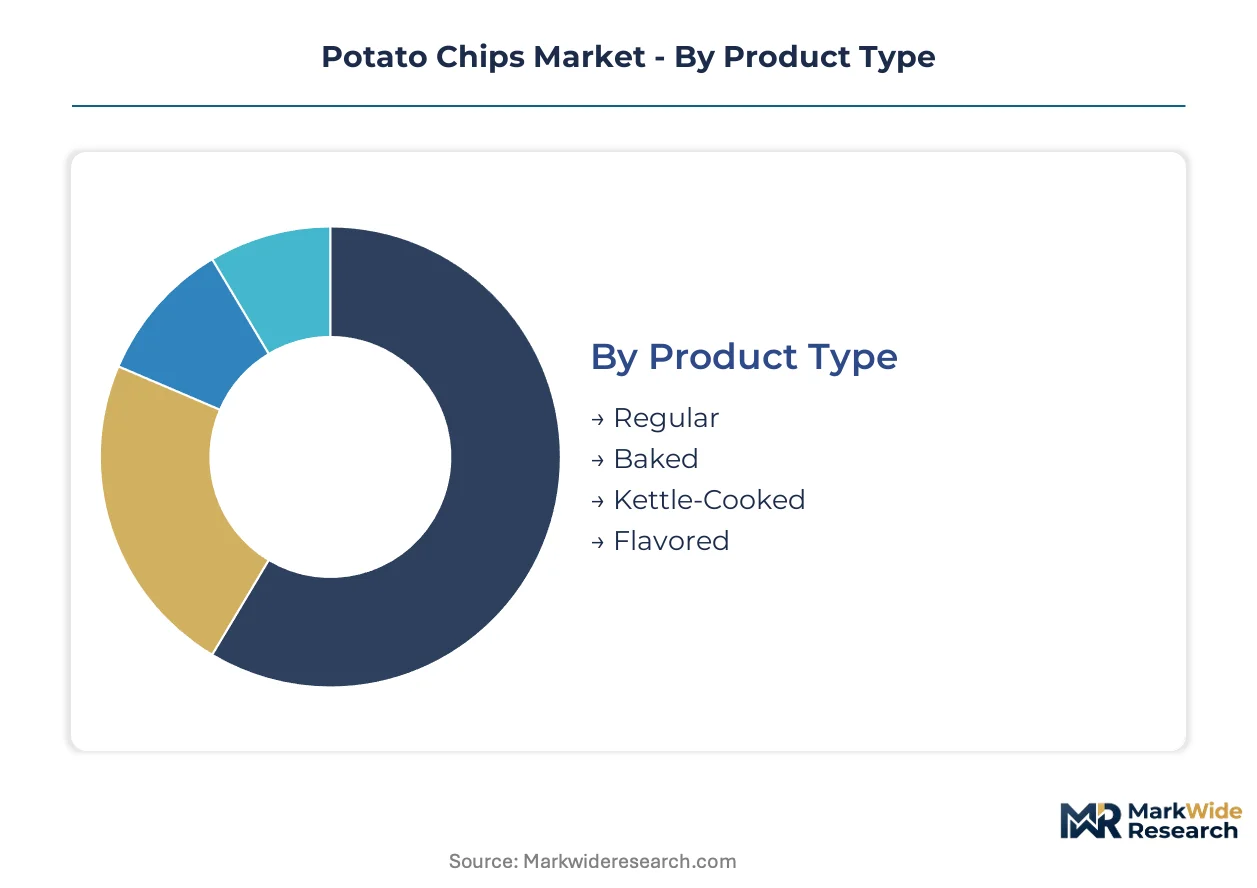
Segmentation in potato chips reveals how texture, ingredient positioning, and channel format drive margin architecture. Each dimension carries distinct capital requirements and regulatory exposure that reshape competitive economics across production scales.
Product Type:
Standardization dominates at commodity volumes while kettle-cooked and flavored variants capture customization premiums through differentiated processing intensity.
- Regular:Thin-sliced tubers fried in continuous oil baths at standardized temperatures achieve sub-2% moisture content for maximum shelf stability. Demand concentrates in mass-market retail across the United States Sun Belt corridor where household penetration sustains volume throughput despite thinner margins.
- Kettle-Cooked:Batch-frying in smaller oil volumes at lower temperatures produces irregular texture and denser bite profile that supports 20-40% price premiums over flat chips. Texas and Florida metropolitan markets show strongest per-capita consumption of this format as consumers trade up from commodity offerings.
- Baked:Hot-air circulation replaces oil immersion, reducing fat content by 60-70% but requiring modified starch coatings to achieve comparable crispness. FDA nutrition labeling thresholds for "low fat" claims drive formulation investment.
- Flavored:Post-fry seasoning application spans powder, liquid, and slurry deposition methods with flavor loadings from 4-12% by weight. Regional palate mapping in Asian markets enables localized SKU proliferation.
Leading the category by volume: Regular. Growing fastest: Kettle-Cooked.
Ingredient Type:
Certification tiering separates premium positioning from commodity supply, with organic and non-GMO segments commanding dedicated sourcing infrastructure and audit trails.
- Natural:Minimal processing claims rely on ingredient lists without artificial colors, flavors, or preservatives. Clean-label demand in US coastal metropolitan markets pressures reformulation timelines.
- Organic:USDA or equivalent certification requires three-year transition periods for potato cultivation and segregated handling through fryer oil and seasoning supply chains. Premium pricing reflects input cost premiums of 30-50% over conventional tubers.
- Non-GMO:Project Verified or equivalent third-party certification addresses consumer skepticism toward biotechnology in food crops without full organic compliance burden.
- Gluten-Free:Dedicated production lines and testing protocols prevent cross-contamination from wheat-based seasonings, capturing celiac and discretionary avoidance demand in specialty retail.
Dominant by revenue concentration: Natural. Steepest expansion trajectory: Organic.
Packaging Type:
Format selection trades material cost against consumption occasion control, with single-serve and resealable variants capturing divergent channel economics.
- Single-Serve:Portion-controlled bags of 1-2 ounces target vending and convenience channels with highest velocity per square foot despite 40-60% higher per-ounce material cost. EU Green Deal biodegradable film mandates impose steepest compliance curves here due to complex barrier requirements.
- Family Size:8-16 ounce formats balance consumption frequency against pantry storage constraints, dominating supermarket promotional cycles and volume-based price architecture.
- Bulk:Foodservice poly-lined cases of 3-5 pounds supply institutional channels with minimal retail branding and shelf-appeal investment.
- Resealable:Zipper or adhesive strip integration extends consumption windows and reduces stalage claims, justifying 15-25% price premiums in club and mass retail.
Highest velocity format: Single-Serve. Gaining share fastest: Resealable.
Sales Channel:
Channel concentration determines service model intensity, from direct-store-delivery logistics to automated replenishment systems.
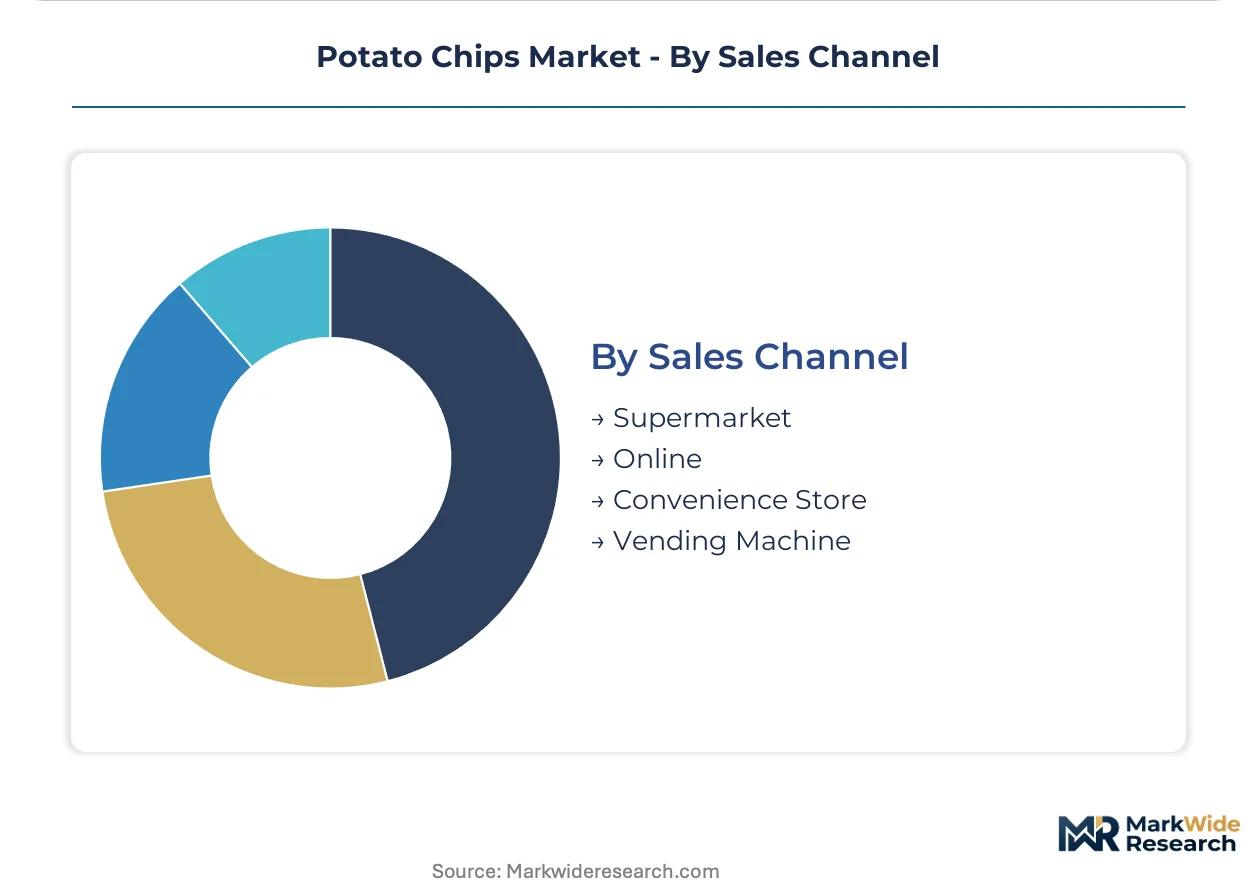
- Convenience Store:Consolidating buyer power among national chains compresses supplier negotiation cycles and demands category management services. PepsiCo's direct-store-delivery infrastructure dominates shelf placement in this channel across the Sun Belt corridor.
- Supermarket:Center-store placement and promotional funding requirements sustain highest absolute volumes but with margin compression from trade spending and slotting fees.
- Online:E-commerce fulfillment requires modified packaging for parcel shipping durability and multi-pack bundling economics, with Amazon and direct-to-consumer platforms capturing urban household replenishment.
- Vending Machine:Cashless payment integration and real-time inventory monitoring expand addressable occasions in workplace and transit locations, though single-serve cost structures limit profitability.
Volume leader: Supermarket. Expanding most quickly: Convenience Store.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in North American and European processing clusters while consumption growth accelerates across Asian metropolitan corridors. The United States retains the largest absolute consumption base. Regulatory divergence across jurisdictions fragments compliance architectures for multinational operators.
United States
Sun Belt metropolitan expansion in Texas, Florida, and Arizona sustains per-capita salty snack consumption above national baselines. FDA nutrition labeling requirements and pending acrylamide threshold guidance force defensive reformulation investments. PepsiCo's direct-store-delivery infrastructure dominates shelf placement in Dallas-Fort Worth and Houston convenience store networks.
Germany
Private-label penetration in discount retail channels compresses branded margin pools while sustaining volume throughput. EU Green Deal packaging mandates accelerate capital deployment into compostable barrier technologies. Intersnack operates processing facilities in North Rhine-Westphalia serving Central European distribution networks.
Japan
Premium texture formats capture trading-up demand in Tokyo and Osaka metropolitan markets. METI standards on food additive usage shape seasoning formulation constraints. Calbee anchors localized flavor development through regional palate mapping in Kansai and Chubu consumption clusters.
India
Rapid urbanization in Maharashtra and Karnataka metro corridors expands addressable middle-class snacking occasions. FSSAI additive regulations and BIS packaging standards fragment compliance burdens for multinational entrants. Domestic processors in Gujarat and Tamil Nadu scale regional distribution networks.
Brazil
Flavor localization in São Paulo and Rio de Janeiro metropolitan areas enables premium positioning against standardized global offerings. ANVISA food safety protocols govern imported seasoning additive approvals. Mondelez International leverages manufacturing infrastructure in Minas Gerais for Mercosur regional supply.
Potato Chips Market Key Industry Players
Top-tier vendors anchor mass-market shelf placement through direct-store-delivery infrastructure, while mid-tier producers compete on regional flavor specialization and price-tier segmentation. The vendor base stratifies across three functional archetypes: multinational portfolio conglomerates with integrated distribution, regional specialists with localized taste expertise, and private-label manufacturers serving discount retail channels. Dominant competitive moves include convenience store channel consolidation through category management services and accelerated R&D spending on biodegradable packaging compliance.
Within the multinational conglomerate tier, PepsiCo and Kellanova occupy positions defined by branded portfolio depth and North American distribution density. Calbee exemplifies the regional specialization archetype through Asia-Pacific flavor localization capabilities. These three entities represent distinct strategic postures: scale-driven supply chain integration, multi-price-tier portfolio architecture, and geographic taste adaptation expertise.
| Leading Market Players |
|---|
| PepsiCo |
| Calbee |
| Kellanova |
| Utz Brands |
| The Campbell's Company |
| Herr Foods |
| Intersnack |
| Mondelez International |
| Burts Snacks |
| Others |
Cost & Logistics Intelligence
Backward integration into edible oil refining and potato cultivation anchors supply position and pricing power for multinational processors, while fragmented domestic operators in India and Brazil absorb margin compression from commodity input volatility. This integration choice separates shelf-stable pricing from spot-market exposure.
Pricing Analysis
Short lead-time premiums attach to kettle-cooked and flavored SKUs where batch processing limits inventory depth, while spot discounts concentrate in regular flat chips with continuous production. Three-tier pricing structure across premium, standard, and economy levels stratifies by texture intensity and certification grade, with organic and non-GMO tiers capturing 30-50% markups over conventional inputs. Pricing pressure stems from edible oil cost volatility, particularly sunflower and palm oil contracts without long-term hedging. Convenience store buyers exhibit highest price sensitivity due to per-square-foot velocity metrics, while club channel purchasers trade volume for lower per-unit costs.
Supply Chain Analysis
Edible oil supply rests on Malaysian and Indonesian palm plantations, Ukrainian and Russian sunflower fields, and North American soybean processing clusters. Potato sourcing draws from Idaho and Washington state processing contracts, Maharashtra and Karnataka farm-gate purchases, and Hokkaido cultivation agreements. Single-source vulnerability concentrates in biodegradable film substrates where EU Green Deal mandates outpace supplier scaling. Distribution runs through direct-store-delivery networks in the United States Sun Belt, wholesale pallet consolidation in European discount retail, and third-party logistics in Asian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around convenience store channel control, with EU Green Deal compliance costs forcing sub-scale producers toward exit or acquisition.
For Market Incumbents: Anticipate biodegradable packaging mandates by securing compostable film supply agreements before capacity constraints tighten. Lock in long-term edible oil contracts to insulate margins from commodity volatility. Expand direct-store-delivery infrastructure in Texas and Florida metro corridors where chain consolidation concentrates buyer power. For New Entrants and Emerging Players: Hyperspectral sorting automation offers a technology-first wedge into quality-sensitive contract manufacturing for private-label retailers. Target India's Maharashtra and Karnataka corridors where FSSAI harmonization gaps create compliance arbitrage for localized flavor development. Pursue vending channel digitization partnerships with cashless payment platforms to bypass shelf-access barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational conglomerates seeking regional flavor capabilities or biodegradable packaging compliance. Five-to-ten year viability favors processors with captive oil refining and established convenience store relationships. Watch acrylamide threshold guidance from FDA as the signal for defensive reformulation capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Transition | EU Green Deal mandates force material substitution ahead of competitor compliance curves. |
| Direct-Store-Delivery Expansion | PepsiCo's infrastructure dominance in Sun Belt metros demonstrates channel control value. |
| Localized Flavor Development | Calbee's Kansai and Chubu mapping captures premium pricing through authenticity positioning. |
| Edible Oil Backward Integration | Captive refining insulates margins from sunflower and palm commodity volatility. |
| Vending Channel Digitization | Cashless payment integration expands addressable occasions in workplace transit nodes. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with snack food brand managers, convenience store category buyers, supply chain planners at retail distributors, and food science directors at processing facilities. FDA guidance documents, EU Green Deal implementation timelines, FSSAI additive regulations, and BIS packaging standards provided regulatory boundary conditions. Nielsen retail audit data, customs import records, and SEC 10-K disclosures from publicly traded processors furnished volume and value triangulation. Bottom-up SKU-level modeling and top-down category spend analysis were reconciled across approaches.
Data-stream reconciliation across shipment volumes, retail velocity, and input cost indices shaped the analytical framework over the projection horizon. Segmentation dimensions included product type, ingredient certification tier, packaging format, and sales channel, with regional regulatory clusters and metropolitan consumption density as cross-cutting variables. CAGRs were derived from trend extrapolation of historical volume-price relationships, adjusted for edible oil cost curve projections and packaging material substitution timelines. Kettle-cooked premium realization and single-serve velocity differentials were modeled as industry-specific demand drivers.
Several conditions sit outside the modeled scope, including abrupt FDA acrylamide threshold changes, palm oil trade restriction escalations, and biodegradable film cost curve inflections. Forecasts reflect documented assumptions about regulatory timeline adherence and commodity price continuity. A small set of named triggers warrants ongoing watch: EU Green Deal enforcement intensity, convenience store chain consolidation pace, and enzymatic asparagine reduction technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
India Energy Bar Market
Snacks
Fruit Jerky Market
Snacks
Extruded Cereals Market
Snacks
Snack Food Packaging Market
Snacks
Italy Snack Bar Market
Snacks
Seaweed Snacks Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Granola Bars Market
Snacks
Germany Energy Bar Market
Snacks
No-Fat Peanut Butter Market
Snacks
South Africa Savory Snacks Market
Snacks
Australia Snack Bar Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Saudi Arabia French Fries Market
Snacks
United Kingdom Energy Bar Market
Snacks
Trail Mix Market