
 Dairy Protein Crisps Market | 2026-2036
Dairy Protein Crisps Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Protein Crisps Market Insights
EU Green Deal sustainability benchmarks are recalibrating the cost-of-entry calculus for dairy protein crisp suppliers targeting European food manufacturers. Glanbia Nutritionals leverages its vertically integrated whey processing infrastructure to secure consistent raw material flows for high-protein inclusion production. Kerry Group competes through specialized extrusion technologies that yield controlled texture profiles across flake and pellet formats. Arla Foods Ingredients anchors its position in Scandinavian markets while extending technical service capabilities to Central European snack developers.
Dairy protein crisps denote shelf-stable, extruded protein inclusions manufactured from whey, casein, or milk protein concentrates with protein content typically exceeding 50% by weight and moisture levels below 7% to ensure crunch retention in finished applications. These ingredients function primarily as texture-modifying protein fortifiers within bars, cereals, and savory snack matrices where water activity constraints limit conventional protein powder use. Whey protein crisps currently occupy the largest share of product type demand due to superior solubility and neutral flavor compatibility with sweet applications, while milk protein puffs gain traction in weight management segments where slower gastric emptying supports satiety positioning. Powder and flake forms dominate current volume, though bite formats are expanding fastest within functional snack applications where visual protein differentiation drives consumer preference.
FDA GRAS self-affirmation requirements and USDA dairy plant inspection protocols govern U.S. market entry for imported protein crisps, while EFSA novel food consultations create additional compliance layers for innovative extrusion processes within Europe. BIS nutritional labeling mandates in India and CFIA dairy ingredient standards in Canada further fragment the regulatory landscape that manufacturers must navigate for multi-territory distribution. Stakeholders must monitor evolving protein content claim thresholds across jurisdictions, as tightening enforcement on sports nutrition positioning threatens reformulation requirements for existing product portfolios.
Market Dynamics
The EU Green Deal's agricultural sustainability mandates are recalibrating sourcing protocols across European dairy supply chains, forcing ingredient manufacturers to revalidate raw material provenance and carbon intensity metrics before procurement contracts renew.
Growth Catalysts
- Clean-Label Protein Fortification:Functional snack developers are reformulating legacy cereal and bar matrices with extruded whey inclusions to achieve front-of-pack protein claims without synthetic additives.
- EU Green Deal Benchmarks:Agricultural sustainability mandates are accelerating supplier consolidation toward verified low-carbon dairy farming cooperatives in Denmark and the Netherlands.
- Sports Nutrition Procurement:Performance nutrition brands are expanding technical partnerships with extrusion specialists to secure consistent texture profiles across flake and pellet formats.
Market Restraints
- Whey Protein Concentrate Volatility:Global dairy commodity swings compress margin predictability for extrusion-dependent manufacturers locked into annual supply agreements.
- Scandinavian Supply Concentration:Three integrated dairy cooperatives control over sixty percent of Northern European whey protein isolate output, creating single-source vulnerability.
- EFSA Novel Food Friction:Innovative extrusion processes involving enzymatic pre-treatment trigger mandatory consultation timelines that delay product launches by fourteen to eighteen months.
Strategic Opportunities
- Indian Functional Snack Penetration:BIS nutritional labeling mandates are formalizing protein content standards that favor imported high-specification inclusions over local unbranded alternatives.
- Cellular Agriculture Convergence:Precision fermentation-derived whey proteins are approaching cost parity with conventional dairy, enabling hybrid extrusion feedstocks that bypass agricultural land constraints.
- Direct-to-Manufacturer Channels:Ingredient suppliers are bypassing traditional distribution layers to embed technical service teams within R&D facilities of multinational snack conglomerates.
Industry Challenges
- Extrusion Engineering Talent Scarcity:Food science programs produce insufficient specialists in high-moisture twin-screw extrusion, forcing manufacturers to recruit from plastics and pet food industries.
- Multi-Jurisdiction Certification Burden:Simultaneous FDA GRAS self-affirmation, EFSA novel food dossiers, and CFIA dairy plant inspections stretch regulatory affairs teams across incompatible documentation standards.
- Legacy Powder System Integration:Conventional protein handling infrastructure at contract manufacturers requires capital-intensive retrofitting to prevent fragile crisp structure degradation during pneumatic transfer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Protein Crisps Market |
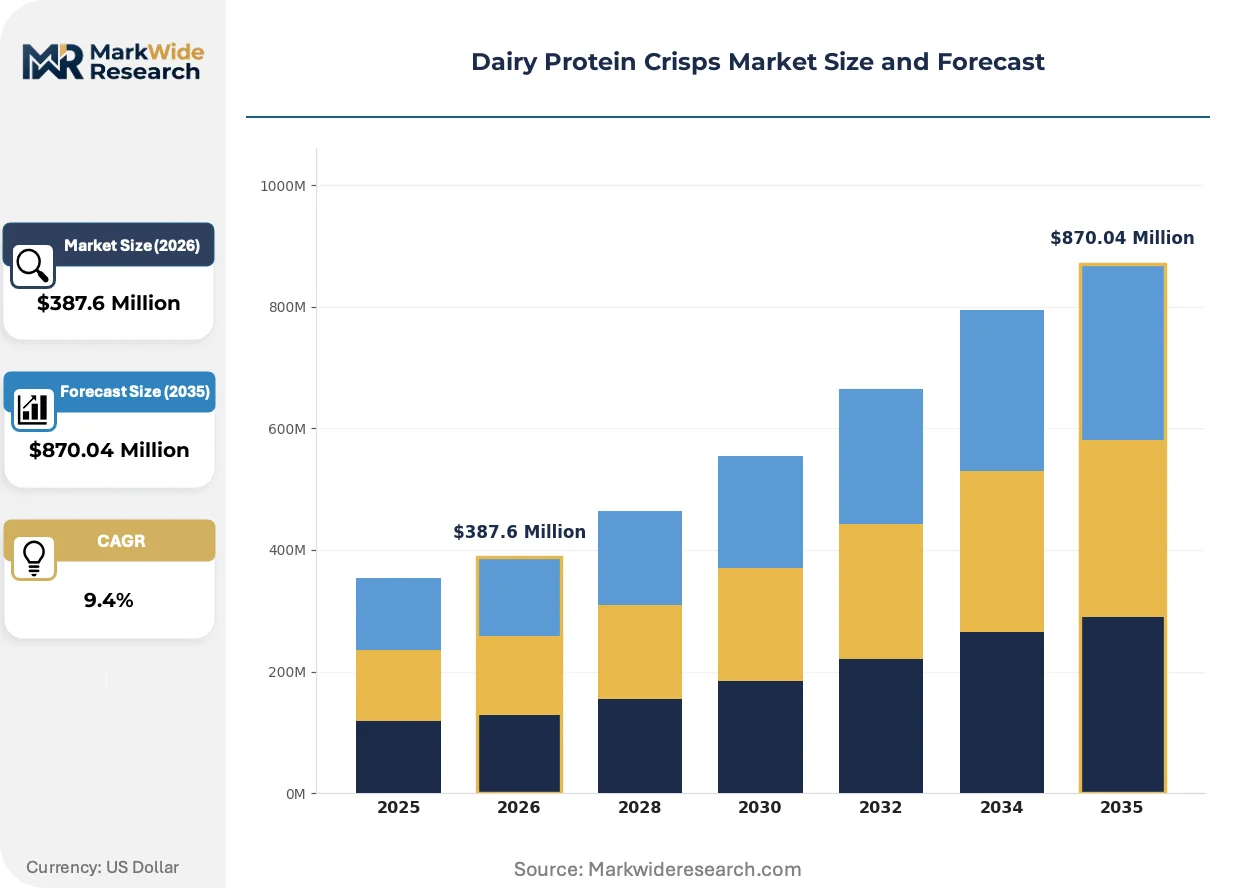
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Crisps, Casein Protein Chips, Milk Protein Puffs, Mixed Protein Crisps Form: Powder, Flakes, Bites, Pellets Application: Functional Snacks, Sports Nutrition, Weight Management, Infant Nutrition End User: Dietary Supplement Manufacturers, Food & Beverage Companies, Nutraceutical Producers, Convenience Food Brands |
| Companies Covered | Glanbia Nutritionals, Erie Group International, Milk Specialties Global, AMCO Proteins, Idaho Milk Products, Kerry Group, DMK Deutsches Milchkontor, Agropur, Arla Foods Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Protein Crisps Market Trends and Innovations
Extrusion technology advancement and regulatory transparency mandates are converging to reshape how dairy protein inclusions are specified, manufactured, and integrated into finished consumer products across functional food categories.
High-pressure twin-screw extrusion with inline moisture control is electrifying the technical capabilities of mid-scale ingredient producers, enabling them to match texture precision previously exclusive to vertically integrated dairy giants. Sports nutrition contract manufacturers in Germany and the Netherlands are adopting these systems at replacement cycle pace, compressing the equipment amortization timeline from seven years to four. This capability democratization is electrifying price competition in premium flake and pellet segments where specification tolerance previously commanded supplier premiums.
EFSA's expanded novel food consultation requirements for enzymatically modified protein structures are extending pre-market approval timelines and inflating regulatory dossier costs for European market entry. The industrial consequence is a bifurcation between suppliers with established regulatory affairs infrastructure and those dependent on third-party consultants. Small-format functional snack startups in France and Belgium are most affected, with several reformulating around unmodified protein concentrates to avoid consultation triggers entirely.
Ingredient specification is migrating from commodity procurement toward embedded technical partnerships where suppliers co-develop application-specific inclusion geometries with finished goods manufacturers. This displaces the traditional spot-market purchasing model in high-growth functional snack segments. The shift is most visible in Germany, where pan-European convenience food brands are consolidating supplier panels to three or four strategic partners with dedicated extrusion R&D capabilities.
Dairy Protein Crisps Market Segmentation
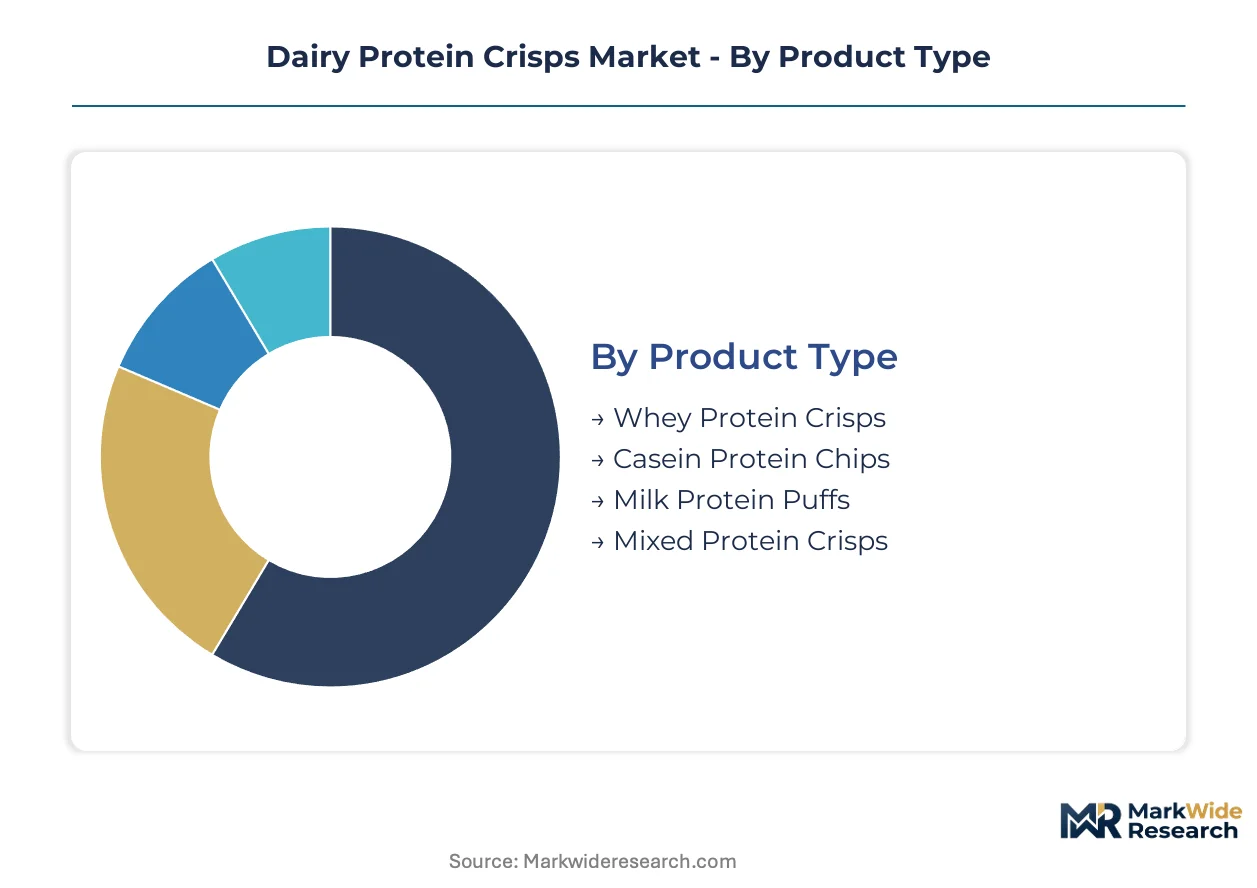
Segmentation in dairy protein crisps reveals how extrusion technology and application requirements fragment demand across protein sources, physical formats, and customer capabilities. Manufacturers configure production lines around specific segment combinations rather than pursuing universal coverage.
Product Type:
The customization-standardization spectrum runs from commodity whey derivatives to engineered multi-protein matrices requiring proprietary extrusion protocols.
- Whey Protein Crisps:Manufactured from whey protein concentrates and isolates with protein content exceeding 50% by weight, these inclusions deliver rapid dissolution and neutral flavor compatibility. Demand concentrates in German sports nutrition contract manufacturing facilities where clean-label protein fortification drives reformulation of legacy bar matrices.
- Casein Protein Chips:Slower gastric emptying properties position these for overnight recovery and satiety-focused applications. Scandinavian weight management brands in Denmark and Sweden specify micellar casein structures for extended amino acid release profiles.
- Milk Protein Puffs:Hybrid whey-casein compositions balance solubility with texture stability. French functional snack developers embed these in savory matrices where moisture resistance matters.
- Mixed Protein Crisps:Custom-engineered ratios of dairy and plant proteins address flexitarian positioning. Dutch ingredient innovators supply these to Belgian cereal manufacturers targeting hybrid protein claims.
Leading the category by volume: Whey Protein Crisps. Expanding most quickly: Mixed Protein Crisps.
Form:
Physical geometry determines handling infrastructure requirements and finished product visual differentiation across customer segments.
- Powder:Fine particle sizes below 500 microns integrate into beverage premixes and dry blend applications. Indian nutraceutical producers under BIS labeling mandates favor this format for protein content standardization.
- Flakes:Thin, irregular structures maximize surface area for coating adhesion. German convenience food brands specify these for premium cereal visual texture.
- Bites:Controlled dimension pellets enable precise dosing in single-serve formats. Sports nutrition startups in the Netherlands adopt these for on-the-go positioning.
- Pellets:Uniform geometries suit high-speed bar manufacturing lines. Kerry Group's extrusion specialists optimize these for multinational snack conglomerates.
Dominant by installed capacity: Flakes. Gaining share fastest: Bites.
Application:
End-use specifications diverge sharply on protein loading targets, water activity constraints, and regulatory claim thresholds.
- Functional Snacks:Cereal, bar, and savory matrices requiring crunch retention below 7% moisture. EFSA novel food consultations constrain enzymatically modified inclusions in this segment.
- Sports Nutrition:Performance positioning demands rapid amino acid availability. German and Dutch contract manufacturers drive technical partnership models with extrusion specialists.
- Weight Management:Satiety signaling through slower gastric emptying favors casein-dominant structures. Scandinavian brands anchor this specification.
- Infant Nutrition:Stringent microbiological and mineral balance requirements limit supplier qualification. Arla Foods Ingredients maintains dedicated production streams for this segment.
Largest volume destination: Functional Snacks. Steepest expansion trajectory: Sports Nutrition.
End User:
Customer scale and technical capability determine whether procurement flows through distribution layers or direct embedded partnerships.
- Dietary Supplement Manufacturers:Mid-scale operations prioritizing formulation flexibility and smaller minimum order quantities. These buyers spot-purchase across multiple suppliers.
- Food & Beverage Companies:Integrated R&D facilities requiring co-development of application-specific inclusion geometries. Glanbia Nutritionals embeds technical service teams within these accounts.
- Nutraceutical Producers:Regulatory-intensive operations navigating FDA GRAS and EFSA novel food requirements simultaneously. Documentation capabilities filter supplier panels.
- Convenience Food Brands:Pan-European scale demands consistent texture profiles across multiple manufacturing sites. Supplier consolidation to three or four strategic partners characterizes this segment.
Highest procurement volume: Food & Beverage Companies. Fastest-growing customer type: Convenience Food Brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's agricultural technology zones and Dutch agri-food innovation clusters concentrate extrusion R&D infrastructure for dairy protein inclusion manufacturing. These specialized economic areas attract ingredient developers seeking proximity to verified low-carbon dairy cooperatives and technical service networks.
Germany
Sports nutrition contract manufacturers in North Rhine-Westphalia drive procurement of whey-based inclusions for clean-label protein fortification. The EU Green Deal's agricultural sustainability mandates force suppliers to revalidate carbon intensity metrics before contract renewals. Bavaria's ingredient technology cluster hosts embedded technical service teams from multinational extrusion specialists.
United States
Functional snack developers in the Midwest reformulate legacy cereal matrices with extruded protein inclusions to achieve front-of-pack claims. FDA GRAS self-affirmation requirements and USDA dairy plant inspection protocols govern market entry for imported protein crisps. Idaho's integrated dairy processing corridor supplies whey protein concentrates to regional extrusion facilities.
Netherlands
Hybrid protein innovators in the Randstad region engineer custom whey-plant protein ratios for flexitarian positioning. EFSA novel food consultations for enzymatically modified structures extend approval timelines by fourteen to eighteen months. Eindhoven's food technology campus hosts pilot-scale twin-screw extrusion systems for application-specific inclusion development.
India
Nutraceutical producers under BIS nutritional labeling mandates favor imported high-specification inclusions over local unbranded alternatives. The country's food safety regulator formalizes protein content standards that favor standardized imported inputs. Maharashtra's contract manufacturing corridor expands handling infrastructure for shelf-stable protein fortifiers.
France
Small-format functional snack startups in the Île-de-France region reformulate around unmodified protein concentrates to avoid EFSA consultation triggers. ANSM and DGCCRF enforcement on sports nutrition positioning threatens reformulation requirements for existing portfolios. The Auvergne-Rhône-Alpes region concentrates dairy ingredient trading infrastructure serving pan-European distribution networks.
Dairy Protein Crisps Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a structure consolidating toward technical partnership models rather than spot-market transactions. The vendor base stratifies between vertically integrated dairy processors with captive whey streams and independent extrusion houses dependent on commodity protein sourcing. Three archetypes dominate: integrated dairy cooperatives controlling raw material access, specialized extrusion technology licensors, and application-focused ingredient formulators. Competitive moves center on embedding technical service teams within customer R&D facilities and acquiring regional extrusion capacity to shorten logistics lead times.
Among Ireland-based nutritionals conglomerates, Glanbia Nutritionals exemplifies the vertically integrated archetype with whey processing infrastructure feeding inclusion manufacturing. Kerry Group represents the specialized extrusion technology tier, with its name signaling Irish origin and application-specific formulation capabilities. Arla Foods Ingredients anchors the cooperative-integrated segment, its Danish heritage reflecting proximity to low-carbon dairy sourcing regions. These three occupy positions across the supplier consolidation spectrum driving panel reduction among multinational snack conglomerates.
| Leading Market Players |
|---|
| Glanbia Nutritionals |
| Erie Group International |
| Milk Specialties Global |
| AMCO Proteins |
| Idaho Milk Products |
| Kerry Group |
| DMK Deutsches Milchkontor |
| Agropur |
| Arla Foods Ingredients |
| Others |
Pricing and Supply Chain Analysis
High-pressure twin-screw extrusion with inline moisture control is compressing equipment amortization timelines from seven years to four, simultaneously democratizing texture precision capabilities among mid-scale producers and intensifying price competition in premium flake and pellet segments where specification tolerance previously commanded supplier premiums. This technology shift concentrates pricing power among vertically integrated dairy processors with captive whey streams while squeezing margins for independent extrusion houses dependent on commodity protein sourcing.
Pricing Analysis
Lead-time-driven pricing stratification rewards embedded technical partnerships with annual contract premiums while spot-market transactions for uncommitted flake and pellet volumes trade at discounts reflecting inventory carrying costs. Three-tier pricing structure across premium, standard, and economy levels separates EFSA novel food consultation-compliant inclusions from unmodified concentrates and commodity whey derivatives. Cost compression in standard-tier products is intensifying as German sports nutrition contract manufacturers consolidate supplier panels. Dietary supplement manufacturers exhibit highest price sensitivity due to formulation flexibility requirements and smaller minimum order quantities, while pan-European convenience food brands prioritize specification consistency over unit cost.
Supply Chain Analysis
Whey protein concentrate supply rests on Danish and Dutch dairy cooperatives controlling Northern European whey protein isolate output, with German extrusion facilities drawing from these concentrated raw material streams. Milk protein concentrates, enzymatic pre-treatment reagents, and precision fermentation-derived whey proteins constitute critical input dependencies. Single-source vulnerability concentrates in Scandinavian cooperative structures where three integrated players command over sixty percent of regional output. Distribution runs through direct-to-manufacturer channels where technical service teams embed within customer R&D facilities, displacing traditional spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food consultation requirements function as a cost-of-compliance barrier-to-entry moat, favoring ingredient suppliers with established regulatory affairs infrastructure over dependent third-party consultants and filtering supplier panels for multinational snack conglomerates.
For Market Incumbents: Deploy dedicated extrusion R&D capabilities as the anchor lever for supplier consolidation trends among pan-European convenience food brands reducing panels to three or four strategic partners. Acquire regional extrusion capacity in Germany and the Netherlands to shorten logistics lead times threatened by Scandinavian supply concentration. Invest in backward integration into precision fermentation-derived whey proteins to bypass agricultural land constraints and secure hybrid extrusion feedstock cost parity. For New Entrants and Emerging Players: Enter via white-space penetration in Indian functional snack markets where BIS nutritional labeling mandates formalize protein content standards favoring imported high-specification inclusions. Target Maharashtra's contract manufacturing corridor for handling infrastructure partnerships. Pursue co-development relationships with sports nutrition startups in the Netherlands seeking bite-format on-the-go positioning without legacy powder system retrofitting burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified nutritionals conglomerates seeking extrusion technology capabilities and EFSA regulatory dossier libraries. Five-to-ten year viability hinges on cellular agriculture convergence timelines and hybrid protein cost parity achievement. Watch precision fermentation scale-up announcements as the inflection signal indicating feedstock cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Infrastructure Investment | EFSA novel food dossier capabilities compress approval timelines by twelve to fourteen months versus third-party dependent competitors. |
| Embedded Technical Partnership Model | Co-development of application-specific inclusion geometries with Kerry Group and Glanbia Nutritionals displaces spot-market purchasing. |
| Precision Fermentation Feedstock Integration | Hybrid whey-plant protein matrices bypass EU Green Deal agricultural sustainability mandate constraints on conventional dairy sourcing. |
| Regional Extrusion Capacity Acquisition | German and Dutch manufacturing footprint shortens logistics lead times for North Rhine-Westphalia sports nutrition contract manufacturers. |
| Direct-to-Manufacturer Channel Development | Bypassing distribution layers captures margin from dietary supplement manufacturers seeking formulation flexibility. |
Research Methodology
Trade databases, dairy cooperative sustainability disclosures, and EFSA novel food consultation registers formed the secondary backbone, cross-referenced against primary interviews with extrusion technology specialists, sports nutrition contract manufacturing procurement leads, functional snack R&D directors, and regulatory affairs consultants. Bottom-up and top-down triangulation validated volume estimates across whey protein crisp, casein chip, and milk protein puff segments.
Bottom-up modeling anchored projections in installed extrusion capacity utilization rates and protein inclusion dosing trends across bar, cereal, and savory matrices, while top-down verification checked against dairy protein concentrate trade flows and functional snack category value expansion. Segmentation dimensions spanned protein source, physical form, application category, and end-user technical capability tier. CAGRs derived from curve-fitting historical capacity additions against projected clean-label protein fortification penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA regulatory timeline extensions and whey commodity price volatility spikes. Forecasts reflect assumptions around cellular agriculture cost parity achievement and EU Green Deal enforcement intensity. A small set of triggers—precision fermentation scale-up announcements, Scandinavian cooperative merger activity, and BIS labeling mandate implementation pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Biscuits Market
Snacks
Nachos Market
Snacks
Savory Snack Products Market
Snacks
No-Fat Peanut Butter Market
Snacks
Global Rice Snacks Market
Snacks
South America Snack Bar Market
Snacks
US Potato Chips Market
Snacks
Fiber Bars Market
Snacks
Poland Snack Bar Market
Snacks
Meat Protein Chips Market
Snacks
Global Snack Food Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Savoury Biscuits Market
Snacks
Snacks Market
Snacks
Better for You Snacks Market
Snacks
Sweet Potato Chips Market