
 Vegetable Puree Market | 2026-2036
Vegetable Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Puree Market Analysis
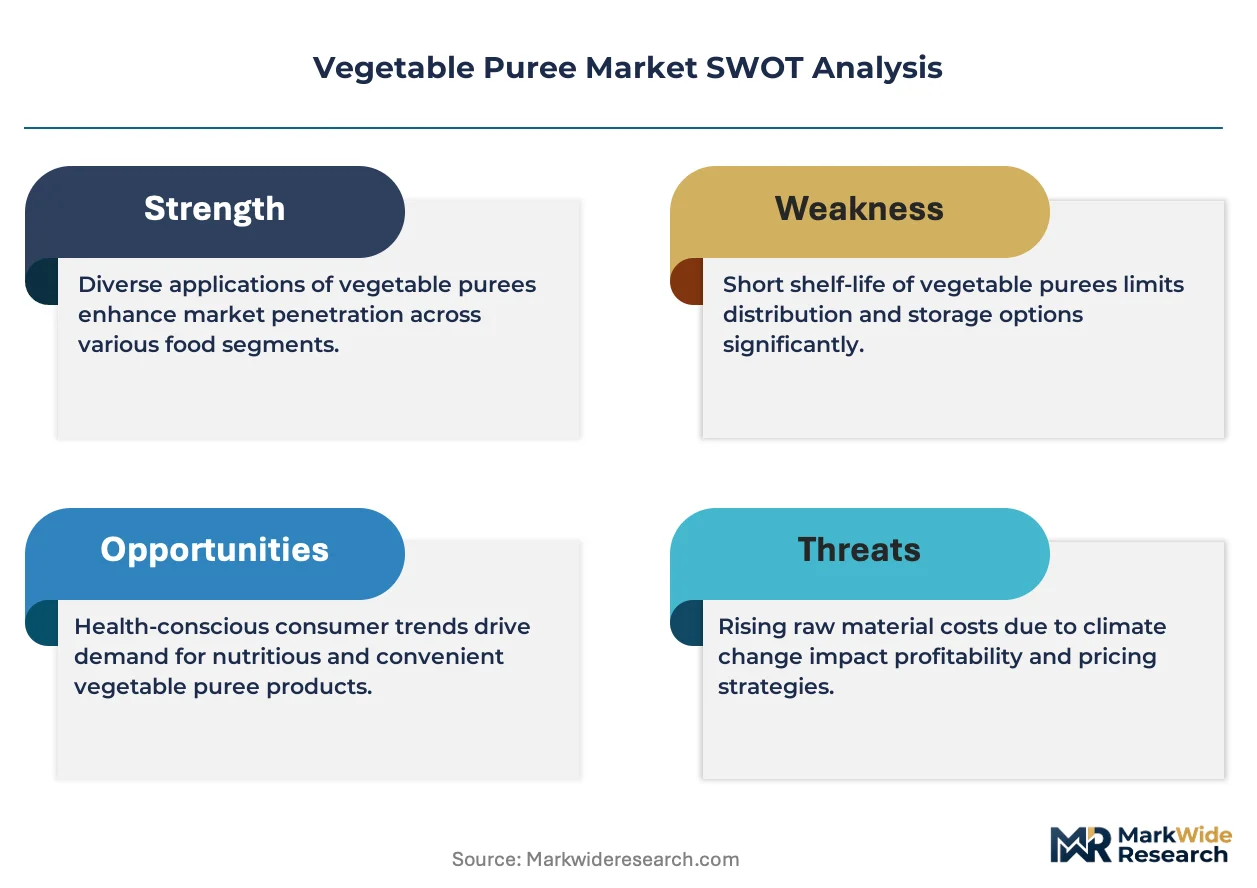
The gap between premium single-origin purees and bulk commodity blends is realigning procurement strategies across the value chain. Bonduelle S.A. leverages its European agricultural base to secure consistent raw material flows for high-specification products. Döhler anchors its position through deep formulation expertise in beverage and dairy applications. SVZ Industrial Fruit & Vegetable Ingredients dominates industrial-scale supply to European and North American food processors.
Vegetable puree consists of mechanically processed, sieved plant tissue with controlled moisture content, particle size, and Brix levels, produced through washing, blanching, milling, and pasteurization steps for use as a functional ingredient or finished food product. Frozen puree commands the largest volume share due to extended shelf stability and minimal additive requirements in industrial settings. Dehydrated puree is gaining traction in dry soup and seasoning applications where freight cost reduction matters. Chilled puree serves premium retail and foodservice channels where fresh taste positioning supports margin capture.
The EU Green Deal and REACH chemical frameworks govern pesticide thresholds and processing aid approvals across European supply chains, while FDA regulations in the United States set standards for acidified foods and low-acid canned products. These overlapping compliance requirements push processors toward dual-certified facilities and traceable farm-level documentation. Stakeholders must weigh organic certification premiums against the operational complexity of segregated supply chains as buyer specifications tighten.
Market Dynamics
Clean-label mandates from the EU Green Deal are forcing processors to restructure sourcing relationships and invest in certified organic supply chains, compressing margins for conventional puree operations while rewarding traceable farm-level documentation.
Growth Catalysts
- EU Farm to Fork Strategy:Tightening pesticide residue limits accelerates demand for certified organic vegetable puree across European infant food and ready-meal manufacturing.
- Industrial Bakery Sector:German bakers are integrating vegetable puree into premium product lines as natural moisture retention and color agents replace synthetic additives.
- High-Pressure Processing:Cold pasteurization technology extends chilled puree shelf life without thermal degradation, unlocking fresh-positioned retail channels.
Market Restraints
- Input Cost Volatility:Weather-driven fluctuations in root vegetable and squash harvests destabilize raw material pricing for processors lacking long-term grower contracts.
- Supply Concentration Risk:Bulk frozen puree production clusters in northwestern European processing hubs, creating vulnerability to regional energy price spikes.
- Substitution Threat:Vegetable fiber powders and concentrated juices compete for formulation share in dry soup and seasoning applications where freight cost reduction matters.
Strategic Opportunities
- Underpenetrated Foodservice:Premium chilled puree remains underdeveloped in Mediterranean European markets outside France and Italy, offering white space for cold-chain logistics investors.
- Regulatory Tailwind:EU CSRD reporting requirements push food manufacturers toward documented sustainable sourcing, favoring puree suppliers with blockchain-enabled farm traceability.
- Technology Convergence:Combination of aseptic filling and modified atmosphere packaging enables ambient-stable clean-label products previously requiring frozen distribution.
Industry Challenges
- Organic Certification Timeline:Three-year conversion periods for conventional farmland block rapid supply scaling to meet surging clean-label demand.
- Segregated Supply Chain Complexity:Maintaining identity-preserved organic streams through washing, milling, and pasteurization requires parallel processing lines and dedicated storage infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Puree Market |
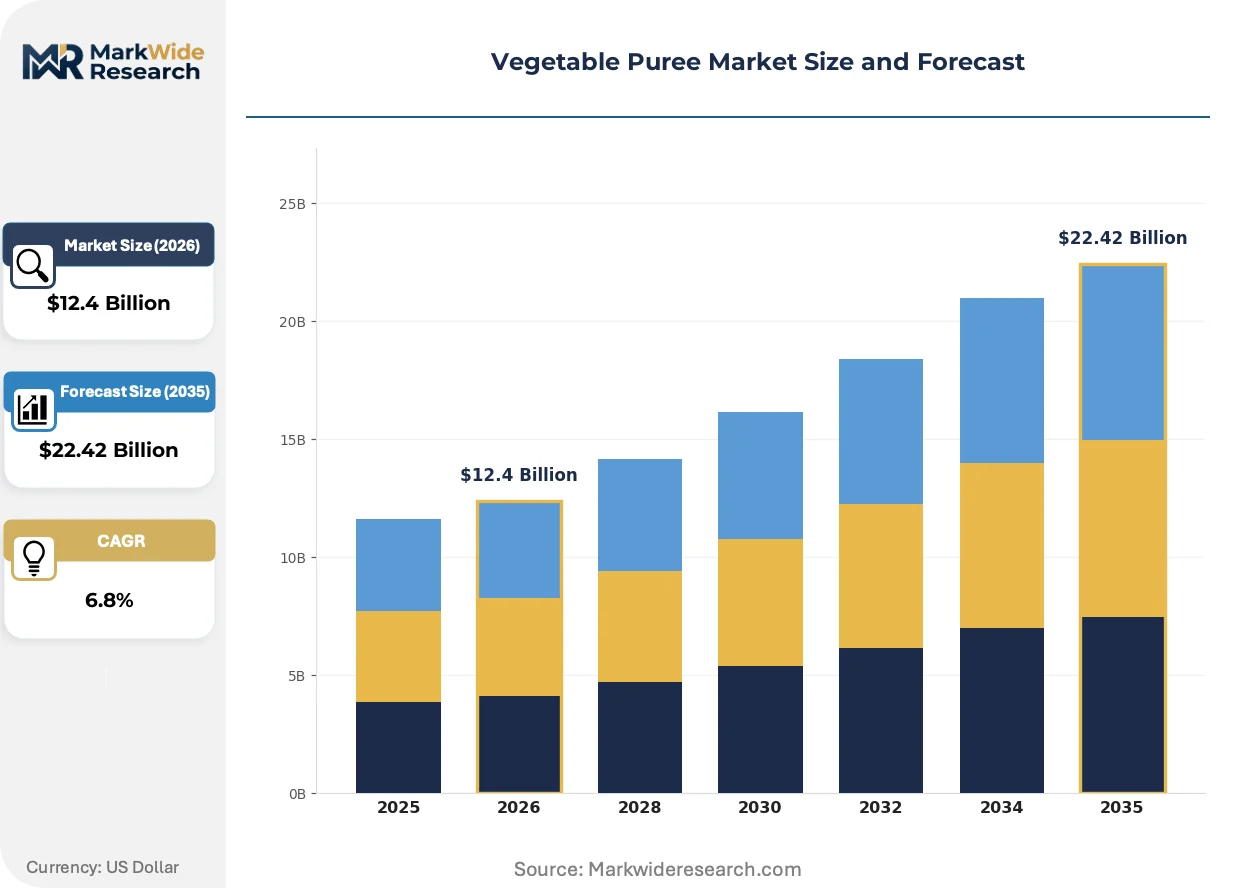
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Puree, Dehydrated Puree, Chilled Puree, Canned Puree End User: Food Processing, Restaurant Chains, Retail Grocery, Child Nutrition Packaging Type: Pouches, Tetra Packs, Glass Jars, Cans Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales |
| Companies Covered | Bonduelle S.A., Ingredion Incorporated, Döhler, Les vergers Boiron, Grünewald International, SVZ Industrial Fruit & Vegetable Ingredients, Greenyard N.V., McCain Foods Limited, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Puree Market Emerging Trajectories
Processing technology and regulatory compliance frameworks are actively restructuring competitive advantage in vegetable puree, with differentiation shifting from commodity scale to specification precision and provenance verification.
High-pressure processing equipment is absorbing capital investment from thermal pasteurization systems across European chilled puree operations. Premium retail brands and foodservice distributors are adopting HPP-treated carrot and beet purees to support extended shelf claims without additive labels. This technology is absorbing margin pressure from energy-intensive frozen distribution by enabling ambient or refrigerated logistics for previously frozen-dependent products.
EU REACH chemical frameworks are tightening scrutiny of processing aids and equipment lubricants in contact with food matrices. Processors must now validate compliance documentation for every substance used in washing, blanching, and milling stages. Infant food and organic-certified product lines face the steepest compliance burden, with some manufacturers relocating finishing operations to dual-certified facilities in Germany and the Netherlands.
Specification-driven procurement now dominates industrial buyer behavior, with detailed particle size distribution and Brix consistency requirements replacing commodity-grade spot purchasing. Large ready-meal manufacturers in Germany and France are consolidating supplier relationships around processors capable of certificate-of-analysis batch documentation. This pattern is most visible in the industrial bakery segment, where automated depositing equipment demands puree viscosity tolerances unavailable from commodity blenders.
Vegetable Puree Market Segmentation
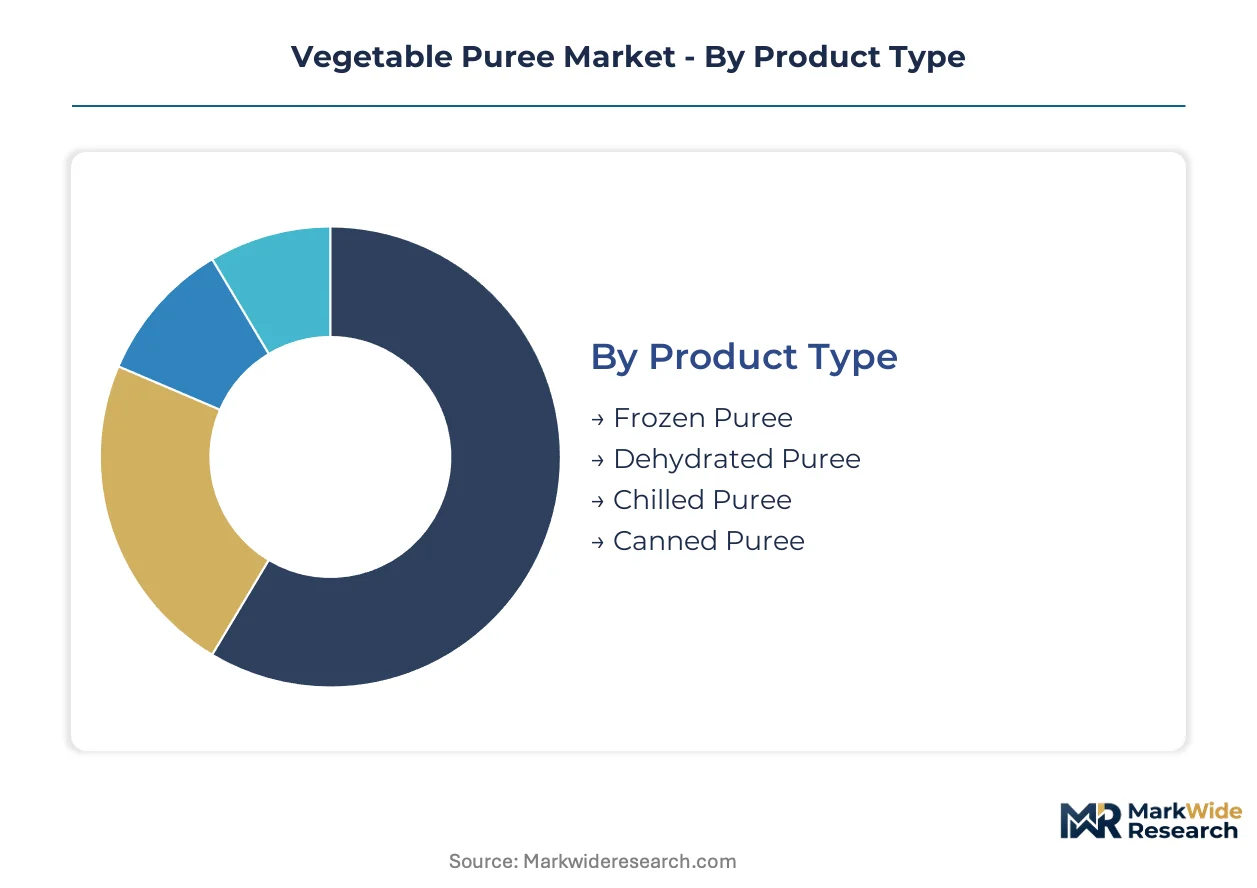
Segmentation in vegetable puree markets determines capital allocation, margin structure, and regulatory exposure. Product format dictates processing technology investment, while end-user concentration shapes contract terms and traceability requirements.
Product Type:
Frozen puree demands the heaviest upfront capital, requiring blast freezing tunnels and cold storage infrastructure at scale.
- Frozen Puree:Mechanically processed vegetable tissue flash-frozen to preserve cellular structure and nutrient density. German industrial bakeries and ready-meal manufacturers anchor demand, driven by extended shelf stability and minimal additive requirements under EU clean-label mandates.
- Chilled Puree:High-pressure processed or mildly pasteurized product distributed under refrigerated conditions. Premium retail channels in France and Italy concentrate procurement here, as fresh taste positioning supports margin capture despite shorter shelf life and cold-chain dependency.
- Dehydrated Puree:Moisture-reduced powder form for dry soup and seasoning applications where freight cost reduction matters.
- Canned Puree:Thermally processed and hermetically sealed for ambient distribution, serving institutional buyers with limited cold-chain access.
Frozen puree absorbs the bulk of installed capacity; chilled puree is expanding most quickly.
End User:
Customer type determines specification stringency and certification burden, with infant food and organic lines facing the steepest compliance requirements.
- Food Processing:Industrial-scale buyers of bulk puree for bakery, dairy, and ready-meal manufacturing. German processors dominate procurement volumes, consolidating supplier relationships around processors capable of certificate-of-analysis batch documentation for automated depositing equipment.
- Child Nutrition:Infant food manufacturers with zero-tolerance pesticide residue standards. EU Green Deal Farm to Fork strategy tightens sourcing requirements, pushing processors toward certified organic supply chains with blockchain-enabled farm traceability.
- Restaurant Chains:Foodservice operators seeking consistent viscosity for menu standardization across locations.
- Retail Grocery:Packaged consumer brands competing on clean-label positioning and convenience formats.
Food processing commands the largest contract volumes; child nutrition shows the steepest specification escalation.
Packaging Type:
Format selection balances shelf life extension against sustainability credentials and retail channel requirements.
- Pouches:Flexible laminated structures for single-serve and family-size retail formats, favored by parents for child nutrition products.
- Tetra Packs:Aseptic carton systems enabling ambient distribution of premium chilled-equivalent products.
- Glass Jars:Traditional format retaining share in organic and premium positioning where visibility and recyclability matter.
- Cans:Metal containers for industrial-scale food processing and institutional foodservice procurement.
Tetra Packs are gaining share fastest in retail; cans retain dominance in industrial channels.
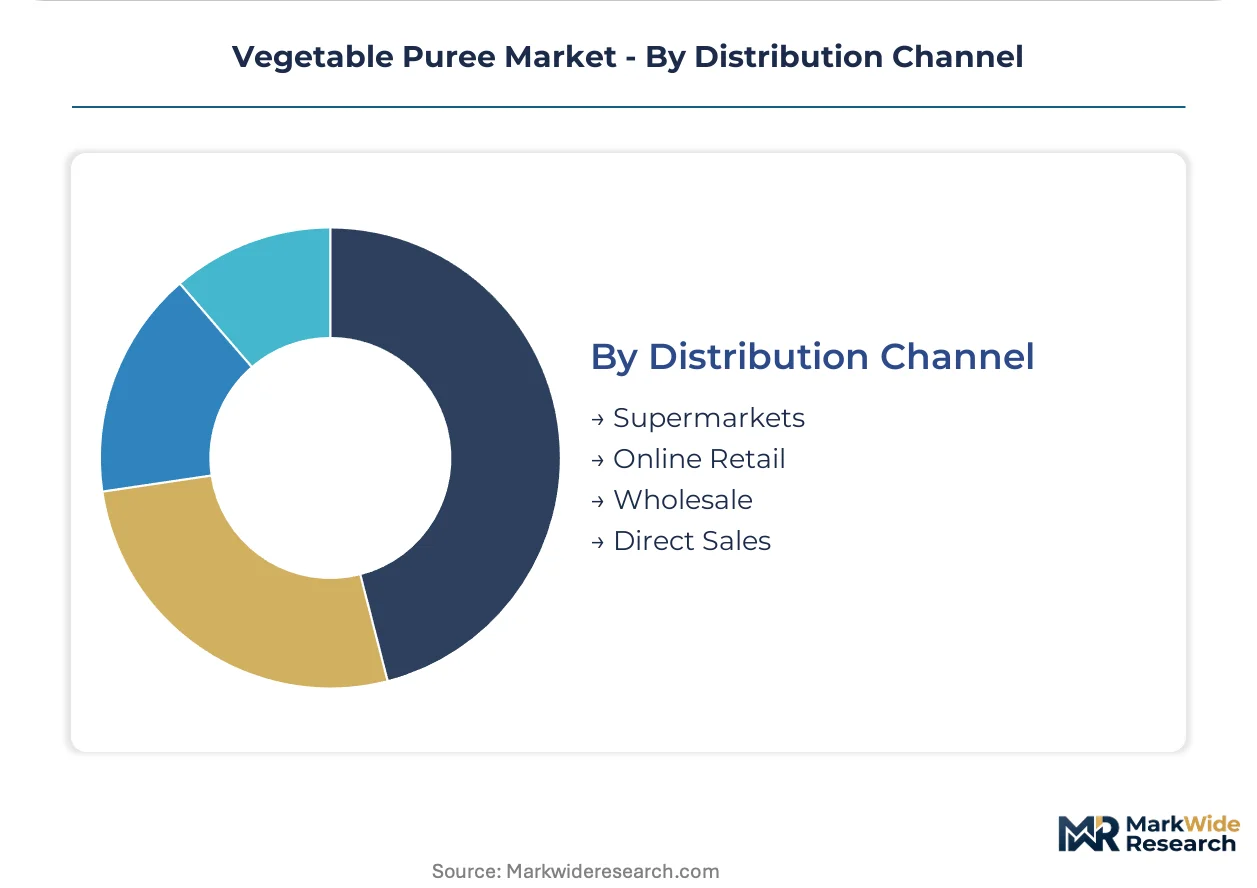
Distribution Channel:
Channel structure reflects buyer scale, specification complexity, and the economics of frozen versus ambient logistics.
- Wholesale:Bulk frozen puree distribution to industrial food processors and restaurant chains. Concentrated in northwestern European processing hubs, creating vulnerability to regional energy price spikes.
- Supermarkets:Retail grocery placement for branded chilled and shelf-stable puree lines, with slotting fees favoring established suppliers.
- Online Retail:Direct-to-consumer and subscription models for premium organic and single-origin positioning.
- Direct Sales:Contract manufacturing relationships with large ready-meal and infant food manufacturers requiring identity-preserved supply chains.
Wholesale handles the greatest tonnage; online retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northwestern European processing hubs around Hamburg and Rotterdam dominate frozen puree capacity, while Mediterranean markets concentrate chilled and premium retail distribution.
Germany
Industrial bakeries in Lower Saxony and ready-meal manufacturers in Bavaria anchor frozen puree procurement volumes. The EU Farm to Fork strategy tightens pesticide residue limits through EFSA enforcement, pushing processors toward certified organic supply chains. Hamburg's port infrastructure supports bulk frozen distribution to Central European food processors.
France
Premium retail channels in Paris and Lyon concentrate demand for high-pressure processed chilled purees with clean-label positioning. ANSM oversees food contact material compliance for processing equipment lubricants. The Auvergne-Rhône-Alpes corridor hosts specialized infant food manufacturers requiring blockchain-enabled farm traceability.
Netherlands
Rotterdam's cold-chain logistics hub distributes bulk frozen puree to British and Scandinavian markets. REACH frameworks through ECHA govern processing aid approvals across washing and blanching stages. Food processing clusters in Gelderland consolidate supplier relationships around certificate-of-analysis batch documentation.
United States
Midwest agricultural processors supply conventional and organic vegetable feedstock to infant food manufacturers. FDA acidified food regulations and low-acid canned product standards shape thermal processing requirements. California's Central Valley hosts dehydration facilities serving dry soup and seasoning applications.
United Kingdom
Ready-meal manufacturers in the Midlands source specification-grade purees for automated depositing equipment. Post-Brexit UK REACH maintains chemical framework alignment with EU standards. London-based foodservice distributors are expanding chilled puree portfolios for premium restaurant chains.
Vegetable Puree Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers and specification precision. The vendor base clusters around three strategic archetypes: diversified European agricultural conglomerates with captive farming operations, specialized industrial ingredient processors with formulation expertise, and frozen food specialists with scale-driven cost positions. Competitive moves concentrate on backward integration into organic farmland and technology licensing for high-pressure processing systems.
Within the diversified agricultural tier, Bonduelle S.A. and Greenyard N.V. represent European operators with integrated supply chain control. Döhler exemplifies the formulation-specialist archetype through its positioning in beverage and dairy applications. SVZ Industrial Fruit & Vegetable Ingredients occupies a scale-driven position in industrial-scale supply to food processors.
| Leading Market Players |
|---|
| Bonduelle S.A. |
| Ingredion Incorporated |
| Döhler |
| Les vergers Boiron |
| Grünewald International |
| SVZ Industrial Fruit & Vegetable Ingredients |
| Greenyard N.V. |
| McCain Foods Limited |
| Conagra Brands |
| Others |
Supply Flow & Price Mechanics
Skilled blanching and milling technicians concentrated in Lower Saxony and Gelderland drive labor-cost spreads between premium organic and conventional puree tiers, with certification-grade wage premiums widening price differentials across the value chain.
Pricing Analysis
Yield-based pricing anchors contract negotiations, with industrial bakeries paying premiums for viscosity-tolerant purees that reduce waste in automated depositing equipment. Three-tier pricing structure across premium organic, standard industrial, and economy commodity levels separates infant food manufacturers from ready-meal producers from institutional buyers. Cost compression in the conventional tier is intensifying because energy price spikes in northwestern European processing hubs erode processor margins. Food processing procurement teams show highest price sensitivity due to volume scale and substitution options, while child nutrition manufacturers accept steep premiums for traceable supply chains.
Supply Chain Analysis
EU Green Deal domestic-content requirements for organic certification documentation are reshaping sourcing patterns toward EU-registered farmland with verifiable pesticide histories. Supply concentrates in Germany, the Netherlands, and France, with raw material dependencies on root vegetables from Lower Saxony, squash from Provence, and beet varieties from Flevoland. Single-source vulnerability runs through Rotterdam's cold-chain logistics hub, where regional energy disruptions cascade into frozen puree distribution delays. Distribution runs through wholesale bulk channels to industrial processors, with direct sales contracts capturing premium-margin child nutrition and organic lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, with EU Farm to Fork strategy pesticide residue limits creating a barrier-to-entry moat that rewards processors with certified organic supply chains and punishes conventional operators.
For Market Incumbents: Cement backward integration into organic farmland in Lower Saxony and Auvergne-Rhône-Alpes to lock in raw material security ahead of three-year conversion timelines. Expand high-pressure processing capacity in Germany and the Netherlands to capture margin expansion from chilled puree substitution of frozen distribution. Defend against concentrated juice and vegetable fiber powder substitutes by deepening formulation partnerships with industrial bakery equipment manufacturers.
For New Entrants and Emerging Players: EU CSRD reporting requirements in Germany open a window for blockchain-enabled farm traceability platforms that command premium pricing from ready-meal manufacturers. Target Mediterranean foodservice markets outside France and Italy where chilled puree penetration remains shallow and cold-chain logistics investment is nascent. Lead with direct sales contracts to mid-sized organic infant food brands seeking identity-preserved supply chains without incumbent volume minimums.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized industrial ingredient processors given specification-driven procurement consolidation around certificate-of-analysis batch documentation capabilities. Long-term viability favors operators with dual-certified facilities in Germany or the Netherlands capable of serving both EU and export markets under diverging regulatory frameworks. Watch for inflection when EU REACH enforcement tightens processing aid scrutiny, forcing facility relocations and acquisition opportunities among compliance-constrained mid-cap players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farmland | Captures raw material security ahead of EU Farm to Fork tightening and three-year conversion timelines. |
| High-Pressure Processing Capacity Expansion | Enables margin capture from chilled puree substitution of energy-intensive frozen distribution channels. |
| Blockchain-Enabled Farm Traceability Platform | Meets EU CSRD documentation requirements and commands premium pricing from ready-meal manufacturers. |
| Dual-Certified Facility Investment | Serves both EU and FDA-regulated export markets without redundant processing infrastructure. |
| Specification-Grade Formulation Partnerships | Locks in industrial bakery demand through viscosity-tolerant purees for automated depositing equipment. |
Methodological Framework
Trade databases, EU regulatory filings through EFSA and ECHA, and industry association reports formed the secondary backbone, supplemented by primary interviews with plant managers at northwestern European processing facilities, procurement leads at German industrial bakeries, infant food regulatory affairs directors, and cold-chain logistics operators. Bottom-up and top-down triangulation validated volume estimates across product format tiers.
Analytical lens combined bottom-up capacity modeling of blast freezing and high-pressure processing installations with top-down demand segmentation across the projection horizon. Segmentation dimensions spanned product format, end-user specification tier, certification grade, and regional regulatory cluster. CAGRs derived from production capacity expansion schedules and buyer procurement pattern analysis, with forecast inputs including EU Green Deal implementation pacing and energy price volatility assumptions.
The model assumes a particular technology adoption path; alternative pathways for aseptic filling and modified atmosphere packaging would alter the outlook if ambient-stable clean-label products displace frozen distribution faster than projected. Forecasts reflect assumptions on organic farmland conversion rates, REACH enforcement intensity, and substitution elasticities between puree formats. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Grapes Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market