
 Freeze Dried Fruits and Vegetables Market | 2026-2036
Freeze Dried Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Fruits and Vegetables Market Intelligence
Advanced vacuum-microwave hybrid drying is narrowing the quality gap between freeze-dried and fresh produce textures while cutting energy inputs by half. Van Drunen Farms leverages its Illinois-based vertical integration to dominate North American berry supply contracts for foodservice. European Freeze Dry anchors its position through pharmaceutical-grade cleanroom certifications that extend into nutraceutical applications. SouthAm Freeze Dry specializes in tropical fruit portfolios sourced from its Chilean and Argentine processing sites.
Freeze dried fruits and vegetables undergo sublimation dehydration at temperatures below −40°C and pressures below 600 Pa, preserving cellular structure, native color, and water-soluble vitamin content for shelf lives exceeding two years without preservatives. The primary commercial purpose centers on lightweight, shelf-stable ingredients for ready meals, confectionery inclusions, and emergency rations where refrigeration is unavailable. Fruits command the largest value share within product type segmentation due to strawberry and raspberry demand from breakfast cereal and snack bar manufacturers, while vacuum sealed packaging captures premium margin pools by extending shelf stability for outdoor enthusiast channels. Pouches compete aggressively in online stores where single-serve portability drives repeat purchase frequency among remote workers.
The FDA enforces Hazard Analysis and Risk-Based Preventive Controls for Human Foods, requiring validated kill-step documentation that elevates capital barriers for new freeze-dry entrants. USDA Organic certification shapes ingredient sourcing decisions as major buyers mandate certified supply chains for clean-label product lines. The EPA's energy efficiency standards for industrial refrigeration equipment influence lyophilizer capital expenditure planning across processing facilities. Stakeholders must monitor evolving state-level extended producer responsibility legislation for flexible packaging, as pouch format dominance creates downstream recycling compliance exposure.
Market Dynamics
Clean-label formulation mandates from breakfast cereal and snack bar manufacturers are compressing supply timelines and forcing freeze-dry processors to validate organic-certified sourcing chains at unprecedented scale.
Growth Catalysts
- FSMA Traceability Rules:The FDA's updated Food Safety Modernization Act requirements are compelling processors to upgrade dehydration documentation systems, creating competitive moats for compliant operators.
- Backpacking Culture:United States outdoor enthusiast channels sustain premium consumption patterns for lightweight, shelf-stable nutrition where refrigeration is unavailable.
- Vacuum-Microwave Hybrid Drying:This technology is narrowing quality gaps between freeze-dried and fresh produce textures while halving energy inputs, expanding addressable applications.
Market Restraints
- Lyophilizer Capital Intensity:Industrial-scale freeze-drying equipment requires substantial upfront investment, elevating barriers for new entrants seeking validated kill-step documentation.
- Energy Input Volatility:EPA energy efficiency standards for industrial refrigeration equipment influence capital expenditure planning and operating cost structures across processing facilities.
- Flexible Packaging Compliance Exposure:State-level extended producer responsibility legislation for pouch formats creates downstream recycling compliance risks that concentrate with format-dominant processors.
Strategic Opportunities
- Nutraceutical Grade Certification:Pharmaceutical-grade cleanroom certifications extend into functional food applications, opening margin pools beyond conventional foodservice channels.
- Tropical Fruit Portfolio Expansion:Chilean and Argentine processing sites offer captive supply of mango, pineapple, and papaya varieties underrepresented in North American retail.
- Emergency Preparedness Stockpiling:Civil defense and institutional preparedness programs represent underpenetrated demand verticals for multi-year shelf-stable rations.
Industry Challenges
- Organic Certification Timelines:USDA Organic supply chain validation creates procurement bottlenecks as major buyers mandate certified sourcing for clean-label product lines.
- Sublimation Process Control:Maintaining temperatures below minus 40 degrees Celsius and pressures below 600 Pa requires specialized operational expertise that concentrates among established processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Fruits and Vegetables Market |
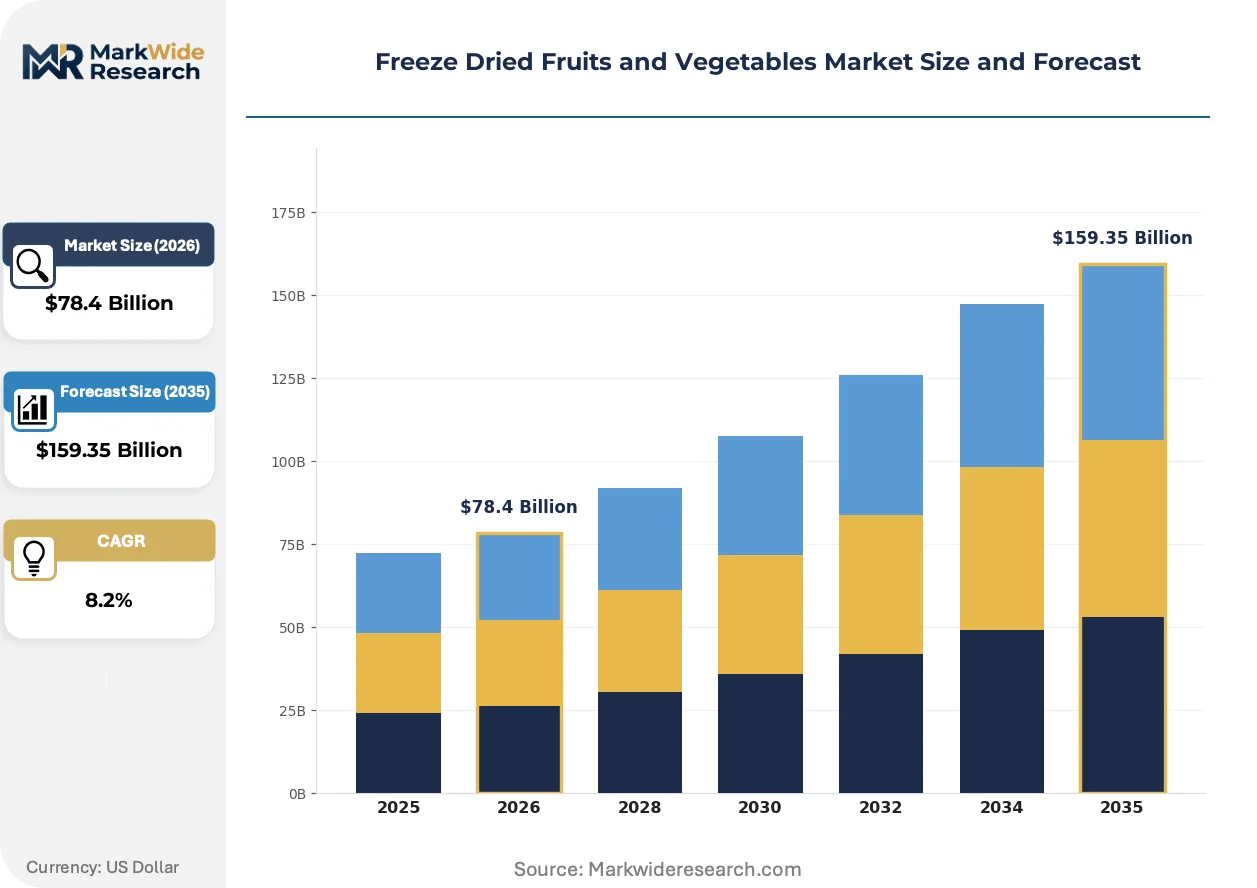
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $159.35 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Mixes, Snacks Packaging Type: Bulk, Pouches, Jars, Vacuum Sealed End User: Households, Restaurants, Food Manufacturers, Outdoor Enthusiasts Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Van Drunen Farms, Döhler, Nestlé, SouthAm Freeze Dry, European Freeze Dry, Kerry Group, Mercer Foods, Mondelez International, OFD Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Fruits and Vegetables Market Strategic Shifts & Innovations
Technology convergence and regulatory documentation requirements are reconfiguring competitive advantage around energy efficiency, supply chain transparency, and format-specific packaging compliance.
Advanced vacuum-microwave hybrid drying systems are collapsing the historical quality gap between freeze-dried and fresh produce textures. Ready-to-eat breakfast cereal manufacturers are adopting these systems at accelerating pace to meet clean-label formulation deadlines. The technology is collapsing energy consumption benchmarks that previously constrained processor margins and geographic expansion feasibility.
REACH chemical safety frameworks in Europe and EPA industrial refrigeration standards in the United States are tightening in parallel. These regulations are forcing capital retooling toward lower-global-warming-potential refrigerants and closed-loop energy recovery systems. Pharmaceutical and nutraceutical applications face the steepest compliance curves, driving consolidation toward processors with existing cleanroom infrastructure.
Single-serve pouch formats are displacing bulk canister distribution in direct-to-consumer channels. Online stores and remote worker consumption patterns favor portability and portion control over traditional volume packaging. This shift concentrates margin capture with processors capable of flexible packaging line reconfiguration and extended shelf stability validation.
Freeze Dried Fruits and Vegetables Market Segmentation
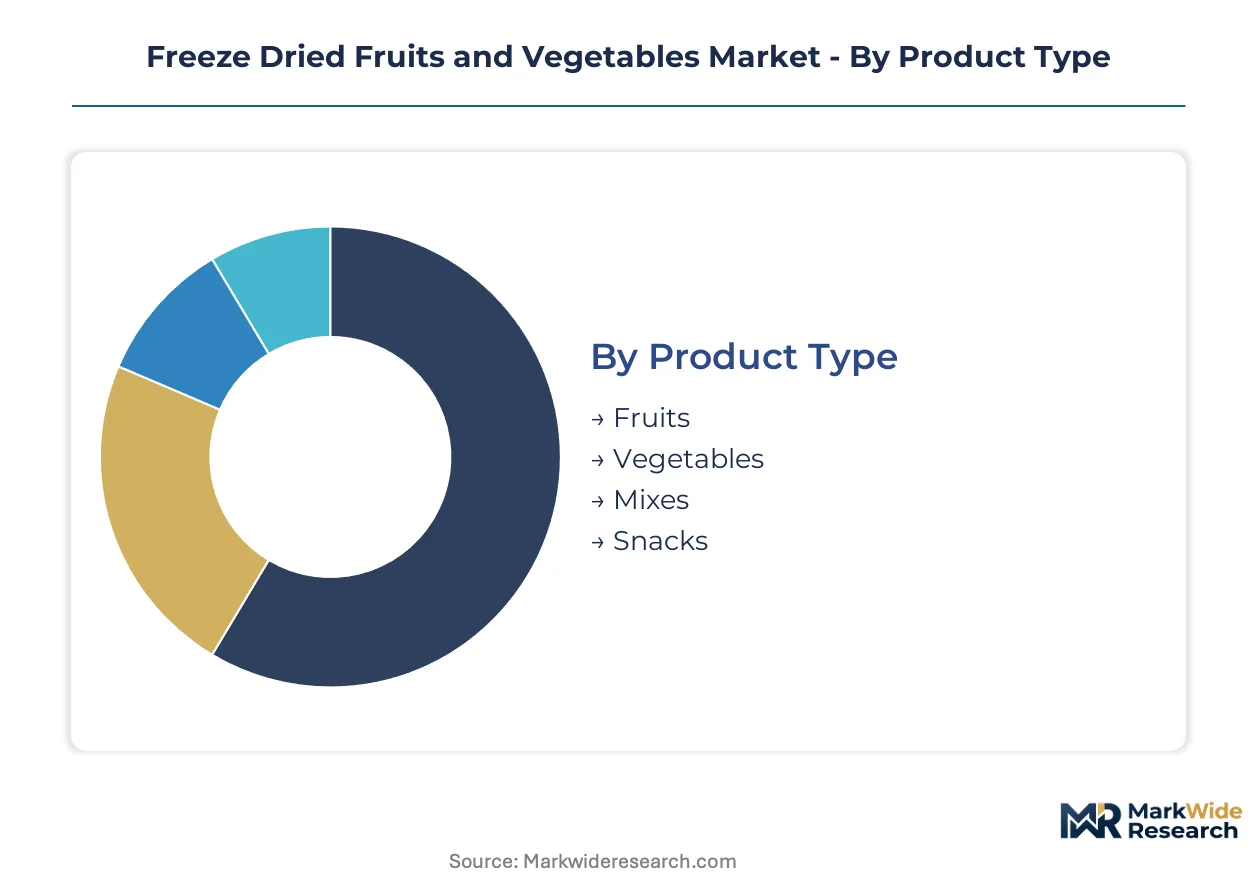
Freeze dried produce processors configure production lines around specific segment requirements, with packaging format and end-use application dictating shelf stability protocols, portion sizing, and moisture specification tolerances. Segmentation discipline separates commodity bulk supply from premium direct-to-consumer channels with divergent margin structures.
Product Type:
After-sales service intensity varies sharply across product types, with fruit processors fielding formulation support calls from cereal manufacturers while vegetable suppliers manage institutional procurement audits.
- Fruits:Strawberry, raspberry, and blueberry segments dominate breakfast cereal and snack bar inclusion contracts. Clean-label mandates from ready-to-eat cereal manufacturers in the United States compress supply timelines and force organic-certified sourcing validation at scale.
- Vegetables:Peas, corn, and bell pepper varieties supply ready meal manufacturers and emergency ration packers. Slower moisture rehydration curves limit penetration in quick-service restaurant applications where speed-of-prep dictates supplier selection.
- Mixes:Blended fruit-vegetable combinations target smoothie kit producers and camping meal suppliers seeking single-SKU solutions.
- Snacks:Standalone freeze dried apple chips and banana crisps compete in direct-to-consumer channels against conventional dried fruit alternatives.
Fruits holds the largest share; momentum sits with Snacks as portable format innovation accelerates.
Packaging Type:
Cost tier separation runs from economy bulk formats through premium vacuum-sealed configurations, with capital equipment requirements and shelf stability validation costs determining processor participation.
- Bulk:Industrial totes and fiber drums supply food manufacturers with high-volume, low-margin ingredient streams. Restaurant chains and ready meal producers in the United States anchor demand for unbranded bulk supply with minimal packaging overhead.
- Pouches:Single-serve and multi-serve flexible formats dominate online stores and remote worker consumption patterns. Portion control and portability drive repeat purchase frequency, though state-level extended producer responsibility legislation creates downstream recycling compliance exposure for format-dominant processors.
- Jars:Rigid container formats retain shelf visibility in specialty retail and gift channels where premium positioning justifies higher unit economics.
- Vacuum Sealed:Extended shelf stability validation supports outdoor enthusiast and emergency preparedness channels where multi-year storage specifications are mandatory.
Bulk commands volume leadership; Vacuum Sealed is expanding most quickly as preparedness stockpiling accelerates.
End User:
Application-specific moisture specifications and kill-step documentation requirements segment processor capabilities across household, institutional, and industrial buyers.
- Households:Direct-to-consumer purchases concentrate in online stores and specialty retailers. Single-serve pouch formats and snack-oriented SKUs dominate as portable convenience overrides bulk economy considerations.
- Restaurants:Foodservice demand centers on garnish applications and premium salad inclusions where texture differentiation commands menu price premiums. Rehydration speed and color retention specifications filter supplier qualification.
- Food Manufacturers:Breakfast cereal, snack bar, and ready meal producers represent the largest contract volume pool. USDA Organic certification and FSMA traceability documentation are non-negotiable entry requirements for supplier status.
- Outdoor Enthusiasts:Backpacking and emergency preparedness cultures in the United States sustain premium consumption for lightweight, shelf-stable nutrition where refrigeration is unavailable.
Food Manufacturers holds the largest share; Outdoor Enthusiasts shows the steepest expansion trajectory as preparedness categories broaden.
Distribution Channel:
Customer type and purchase occasion separate digital-native remote workers from traditional retail shoppers, with channel selection determining packaging format and margin capture.
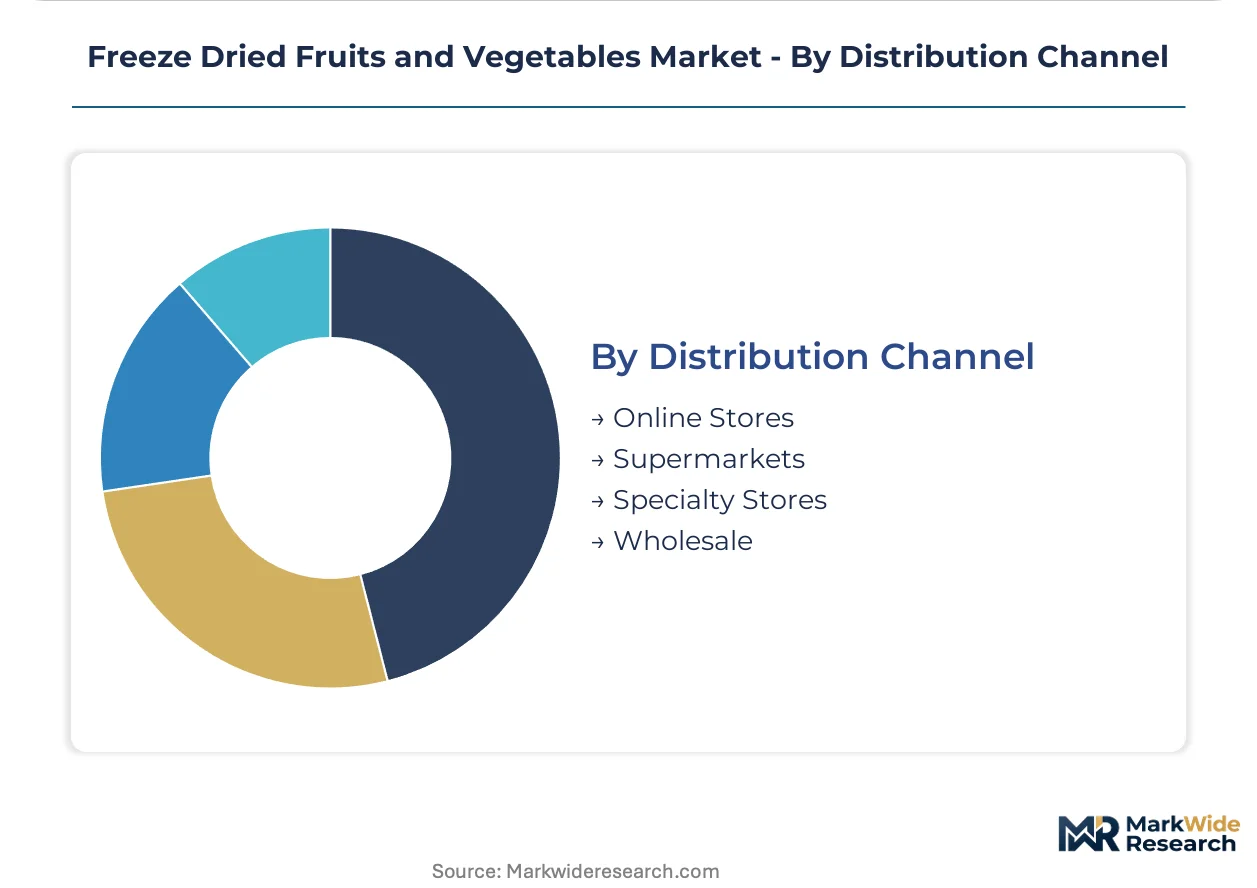
- Online Stores:Direct-to-consumer platforms and third-party marketplaces favor single-serve pouch formats with subscription replenishment mechanics. Remote worker consumption patterns and portability requirements drive repeat purchase frequency in this channel.
- Supermarkets:Mass retail placement demands case-ready packaging and promotional slotting fee structures that favor established processors with trade marketing budgets.
- Specialty Stores:Outdoor retailers and natural food boutiques stock premium vacuum-sealed formats targeting enthusiast demographics with higher willingness-to-pay for extended shelf stability.
- Wholesale:Foodservice distributors and institutional supply houses move bulk and jar formats to restaurants, catering operations, and preparedness contractors with volume pricing structures.
Online Stores holds the largest share; Specialty Stores is gaining share fastest as premium format differentiation concentrates margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile and Argentina export tropical fruit portfolios to North American breakfast cereal manufacturers, while European processors supply pharmaceutical-grade ingredients to nutraceutical formulators across the Atlantic corridor.
United States
Backpacking culture and emergency preparedness stockpiling sustain premium consumption for lightweight, shelf-stable nutrition. The FDA enforces Hazard Analysis and Risk-Based Preventive Controls documentation requirements that elevate capital barriers for new entrants. Illinois-based vertical integration dominates North American berry supply contracts for foodservice channels.
Germany
REACH chemical safety frameworks and industrial refrigeration standards tighten compliance curves for pharmaceutical-grade cleanroom certifications. The ECHA registration requirements concentrate margin capture with processors possessing existing validation infrastructure. Bavarian processing clusters anchor supply relationships with functional food manufacturers seeking extended shelf stability.
China
Domestic demand for ready-to-eat breakfast cereal inclusions accelerates clean-label procurement from freeze-dry processors. The country's national food safety regulator enforces traceability documentation that mirrors FSMA-equivalent standards. Yangtze River Delta manufacturing zones concentrate vacuum-microwave hybrid drying technology adoption.
India
Urban remote worker consumption patterns drive repeat purchase frequency for single-serve pouch formats through online stores. FSSAI mandates on food safety documentation create procurement bottlenecks as major buyers mandate certified sourcing chains. Maharashtra-based processors expand tropical fruit portfolio capabilities to serve export markets.
Freeze Dried Fruits and Vegetables Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent margin structures. The vendor base fragments between vertically integrated agricultural operators and technology-focused dehydration specialists. Three archetypes dominate: captive-supply processors controlling upstream fruit sourcing, equipment-integrated technology licensors, and cleanroom-certified pharmaceutical-grade suppliers. Competitive moves concentrate on strategic partnerships for organic certification scale and capacity expansion for vacuum-microwave hybrid drying adoption.
Among North American agricultural processors, Van Drunen Farms exemplifies captive-supply vertical integration, while SouthAm Freeze Dry occupies a position within tropical fruit specialization. European Freeze Dry represents the pharmaceutical-grade certification tier, anchoring nutraceutical applications through cleanroom infrastructure. These three players illustrate how geographic sourcing control, technology differentiation, and regulatory compliance stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Van Drunen Farms |
| Döhler |
| Nestlé |
| SouthAm Freeze Dry |
| European Freeze Dry |
| Kerry Group |
| Mercer Foods |
| Mondelez International |
| OFD Foods |
| Others |
Cost & Logistics Intelligence
The Pacific maritime corridor linking Chilean fruit processors to Los Angeles and Long Beach ports channels freight volatility directly into margin compression for tropical fruit suppliers and downstream price tiering for breakfast cereal manufacturers.
Pricing Analysis
Conventional lyophilizer technology, vacuum-microwave hybrid systems, and pilot-scale atmospheric drying create three distinct pricing strata across the freeze-dried produce landscape. Pricing stratifies across pharmaceutical-grade certification, organic certification, and conventional commodity tiers, with USDA Organic validation commanding substantial premia from clean-label cereal manufacturers. Cost compression in conventional bulk supply is intensifying because vacuum-microwave adopters are collapsing energy benchmarks and expanding addressable volume. Food manufacturers represent the most price-sensitive buyer segment due to formulation cost targets, while outdoor enthusiast channels show least sensitivity given multi-year shelf stability requirements.
Supply Chain Analysis
Export-control restrictions on advanced lyophilizer vacuum pumps and sublimation chamber technologies limit equipment flows into emerging processing markets, concentrating production capability among established operators. Supply concentrates in the United States, Chile, and Germany, with Argentine sites expanding tropical fruit sourcing. Raw material flows draw from California strawberry cooperatives, Chilean mango orchards, and Bavarian berry cultivation. Single-source vulnerability runs through Illinois-based berry processors dominating North American foodservice contracts. Distribution runs through foodservice distributors, direct-to-consumer platforms, and institutional preparedness contractors with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as clean-label procurement mandates splinter demand across organic-certified, pharmaceutical-grade, and conventional supply tiers, creating specialist niches for differentiated processors.
For Market Incumbents: Harden organic certification pipelines against procurement bottlenecks by securing multi-year berry supply contracts with California and Pacific Northwest cooperatives. Expand vacuum-microwave hybrid capacity to defend margin position against energy efficiency mandates from the EPA. Channel control through exclusive breakfast cereal manufacturer relationships represents the critical defensive lever against SouthAm Freeze Dry's tropical fruit expansion. For New Entrants and Emerging Players: Emergency preparedness stockpiling in the United States represents the most penetrable white-space target, with civil defense and institutional programs currently underserved by incumbent processors. Nutraceutical-grade cleanroom certification offers second-entry pathway given European Freeze Dry's concentration in pharmaceutical applications. Go-to-market execution should anchor on direct-to-consumer subscription mechanics for single-serve pouch formats targeting remote worker consumption patterns. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underutilized freeze-dry assets lacking organic certification scale or pharmaceutical-grade infrastructure. Long-term viability hinges on energy transition positioning and regulatory compliance depth rather than commodity volume scale. Signal to monitor: acceleration of state-level extended producer responsibility legislation for flexible packaging, which would force capital retooling and concentrate margin capture with compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Scale-Up | USDA Organic validation unlocks clean-label cereal manufacturer contracts requiring validated supply chains. |
| Vacuum-Microwave Hybrid Adoption | Energy consumption benchmarks from EPA standards force retooling toward halved-input sublimation systems. |
| Pharmaceutical-Grade Cleanroom Investment | ECHA registration requirements concentrate nutraceutical margin pools with existing validation infrastructure. |
| Flexible Packaging Line Reconfiguration | Single-serve pouch dominance in online stores demands shelf stability validation for remote worker channels. |
| Captive Tropical Fruit Sourcing | Chilean and Argentine processing sites secure mango and papaya supply underrepresented in North American retail. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with freeze-dry processing executives, organic certification auditors, breakfast cereal procurement managers, and outdoor retailer category buyers; alongside secondary validation from USDA organic certification databases, FDA FSMA guidance documents, EPA industrial refrigeration standards, and customs trade flow records. Bottom-up capacity modeling triangulated against top-down demand segmentation across product type, packaging format, and end-use application dimensions.
Forecast inputs considered vacuum-microwave technology diffusion curves, organic certification timeline compression, and extended producer responsibility legislation progression across the analysis window. Segmentation dimensions modeled include product type stratification, packaging tier economics, end-use moisture specifications, and distribution channel margin structures. CAGRs derived from installed lyophilizer capacity expansion trajectories and clean-label procurement mandate penetration rates.
Practitioners should monitor regulatory acceleration in extended producer responsibility frameworks and energy efficiency standard tightening for early signals of margin restructuring. Forecasts reflect assumptions on technology adoption curves and certification timeline stability. Material shifts in EPA refrigerant phase-down schedules or state-level packaging compliance deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Butterfly Pea Flowers Market