
 US Vegetable Puree Market | 2026-2036
US Vegetable Puree Market Size, Share, and Industry Trends Forecast 2026-2036
US Vegetable Puree Market Intelligence
Single-serve pouch packaging is expanding across retail and foodservice channels, unbundling traditional bulk formats into portion-controlled units that reduce waste and extend shelf stability. Döhler leverages its ingredient technology platform to supply customized vegetable bases for infant nutrition brands. SVZ Industrial Fruit & Vegetable Ingredients anchors North American supply through its Washington-state processing facilities. F&S Produce Co. differentiates via vertical integration from farm sourcing to aseptic filling.
US vegetable puree consists of mechanically processed, heat-treated vegetable matter milled to a uniform consistency, typically with soluble solids between 8 and 30 degrees Brix depending on end-use application, and serves as a functional ingredient in formulated foods requiring standardized flavor, color, and nutritional profiles. Organic product type commands premium positioning through USDA certification requirements and constrained raw material availability. Baby food end use leads value contribution due to stringent purity standards and parental willingness to pay for clean-label positioning. Pouch packaging type is displacing glass jars in retail channels due to convenience and reduced shipping weight.
FDA enforcement of Food Safety Modernization Act preventive controls shapes facility design and hazard analysis requirements for domestic puree processors. USDA National Organic Program standards govern ingredient traceability and prohibited substance lists for certified organic lines. California Department of Public Health processing regulations add state-level compliance layers for Central Valley manufacturers. Stakeholders must monitor evolving FDA traceability rules for high-risk foods and assess whether cold-pressed minimal-processing claims can withstand regulatory scrutiny as consumer preference for raw-adjacent products intensifies.
Market Dynamics
California's Central Valley agricultural corridor concentrates vegetable processing infrastructure, creating supply advantages for puree producers while FDA Food Safety Modernization Act enforcement compresses facility design timelines and elevates hazard analysis requirements across domestic operations.
Growth Catalysts
- USDA Organic Certification:Parental willingness to pay premium prices for clean-label baby food drives processors to secure National Organic Program accreditation, tightening ingredient traceability protocols.
- Single-serve pouch packaging:Retail and foodservice channels unbundle bulk formats into portion-controlled units that reduce waste and extend shelf stability through aseptic filling technology.
- Baby food end-use concentration:Stringent purity standards and parental demand for transparent sourcing accelerate adoption of mechanically processed vegetable bases in infant nutrition formulations.
Market Restraints
- Raw material availability constraints:Organic vegetable acreage limitations in California's Central Valley restrict certified ingredient supply and inflate procurement costs for puree processors.
- Cold chain logistics intensity:Temperature-controlled distribution requirements from processing facilities to aseptic filling operations concentrate operational risk in refrigerated transport networks.
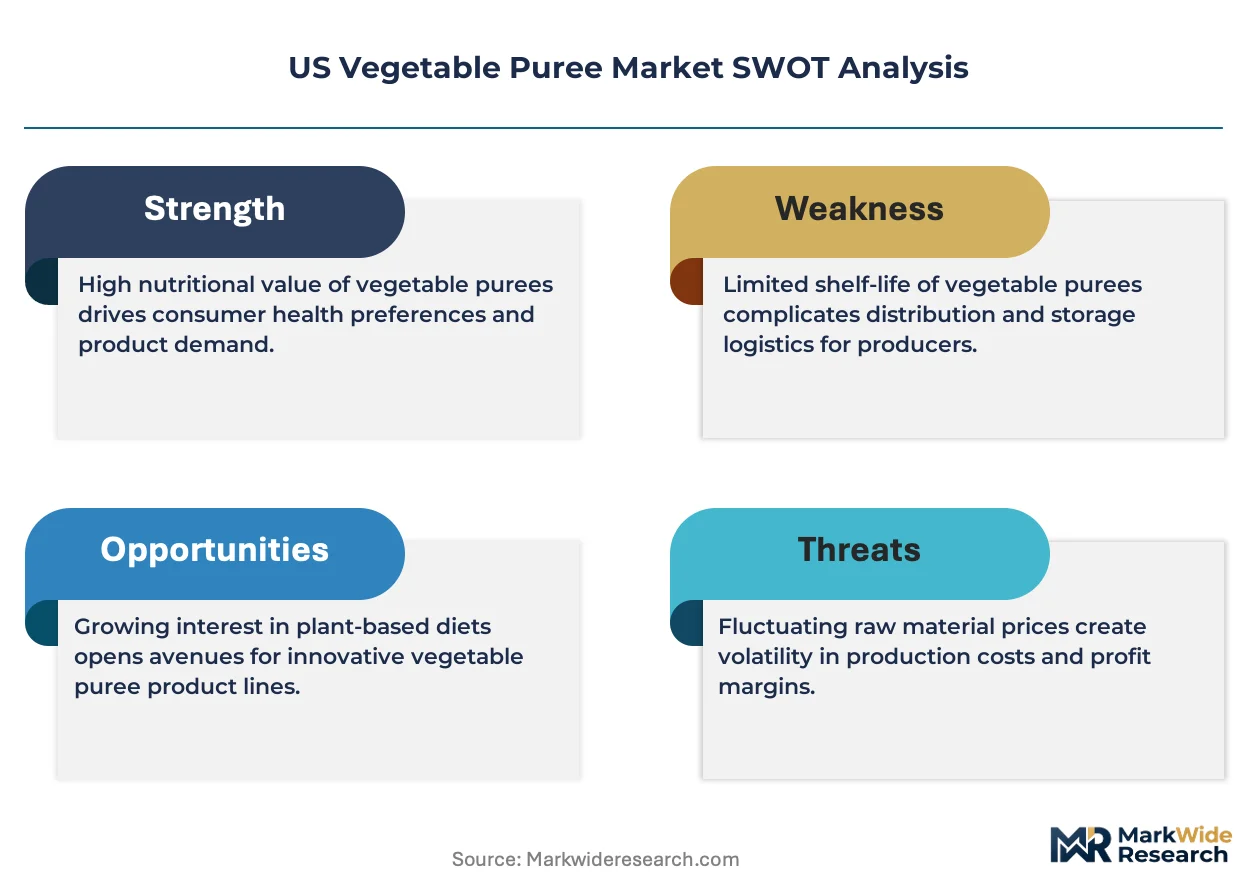
- Substitution by fresh vegetable alternatives:Consumer preference for minimally processed whole foods in adult nutrition segments threatens shelf-stable puree demand outside infant applications.
Strategic Opportunities
- Foodservice channel expansion:Institutional kitchens and restaurant chains seek standardized vegetable bases for sauce and soup formulations, opening volume contracts beyond retail.
- Cold-pressed minimal processing claims:Raw-adjacent product positioning targets health-conscious consumers willing to pay premium prices for reduced heat treatment.
- IRA clean energy incentives:Renewable energy tax credits support processor investment in solar-powered refrigeration and electrified processing equipment.
Industry Challenges
- FDA traceability rule compliance:Evolving record-keeping requirements for high-risk foods demand upgraded digital tracking systems across supplier networks.
- Aseptic filling capex intensity:Specialized equipment for extended-shelf-life packaging requires substantial capital deployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vegetable Puree Market |
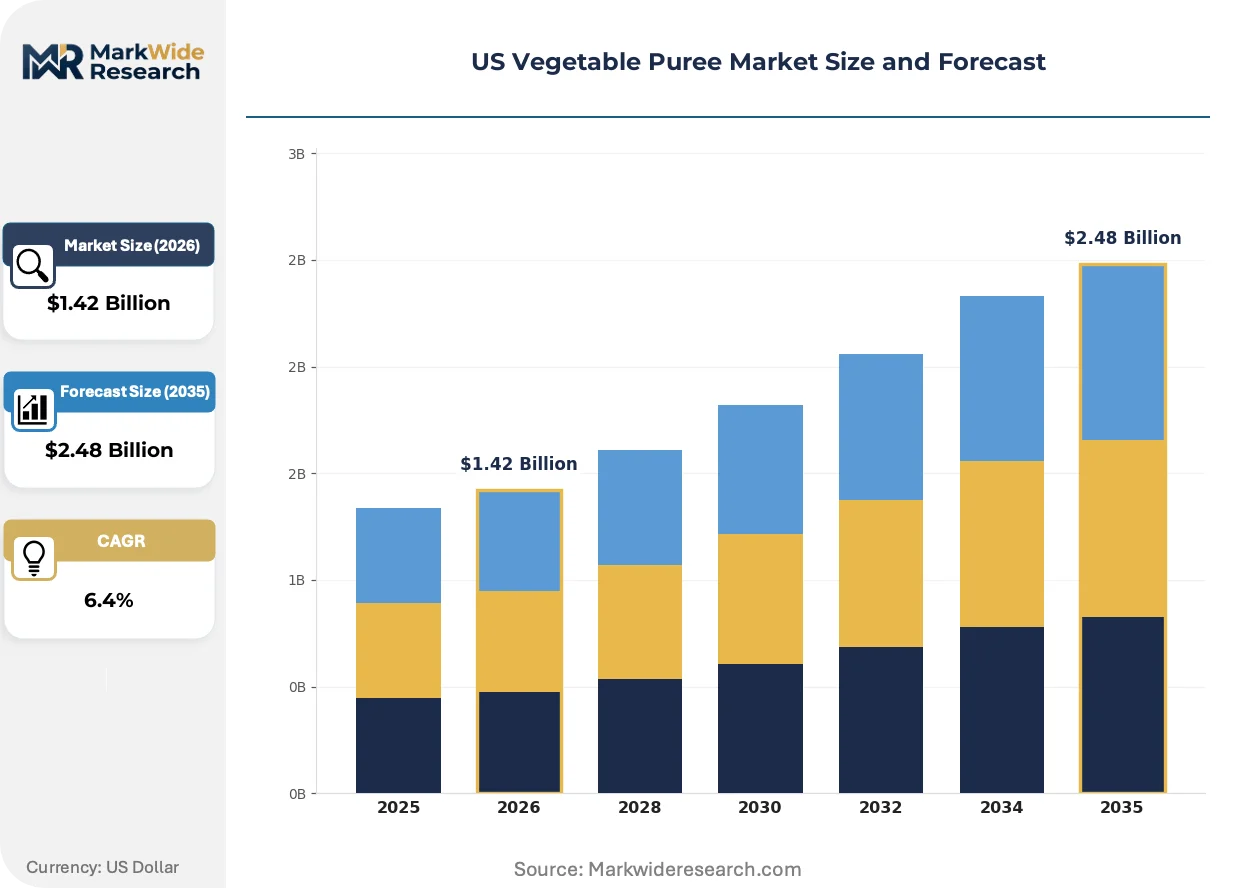
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Frozen, Dehydrated End Use: Food Industry, Baby Food, Snacks, Beverage Packaging Type: Glass Jar, Tetra Pack, Pouch, Canned Distribution Channel: Supermarkets, Online, Specialty Stores, Food Service |
| Companies Covered | Grünewald International, Dennick FruitSource, Döhler, Encore Fruit Marketing, F&S Produce Co., SVZ Industrial Fruit & Vegetable Ingredients, Les vergers Boiron, foodguys, Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vegetable Puree Market Strategic Shifts & Innovations
Technology convergence between high-pressure processing and aseptic filling systems is compressing traditional thermal treatment cycles while regulatory pressure on traceability accelerates digital infrastructure investment across supplier networks.
High-pressure processing technology preserves nutrient density and flavor profiles in vegetable purees without traditional heat degradation. Baby food manufacturers adopt this method at accelerating pace to support clean-label claims. Cold-pressed minimal processing is overtaking conventional retort sterilization in premium product tiers, enabling processors to command price premiums through raw-adjacent positioning.
FDA enforcement of Food Safety Modernization Act preventive controls mandates hazard analysis and risk-based preventive controls for human food facilities. Domestic puree processors redesign facility layouts and supplier qualification protocols to satisfy inspection readiness requirements. California Department of Public Health processing regulations add state-level compliance layers that concentrate compliance investment among Central Valley manufacturers.
Parental purchasing behavior shifts toward subscription-based direct-to-channel models for infant nutrition products. Traditional retail shelf placement faces displacement from auto-replenishment services targeting time-constrained households. This channel migration concentrates in urban coastal markets where delivery infrastructure density supports cold chain reliability for temperature-sensitive shipments.
US Vegetable Puree Market Segmentation
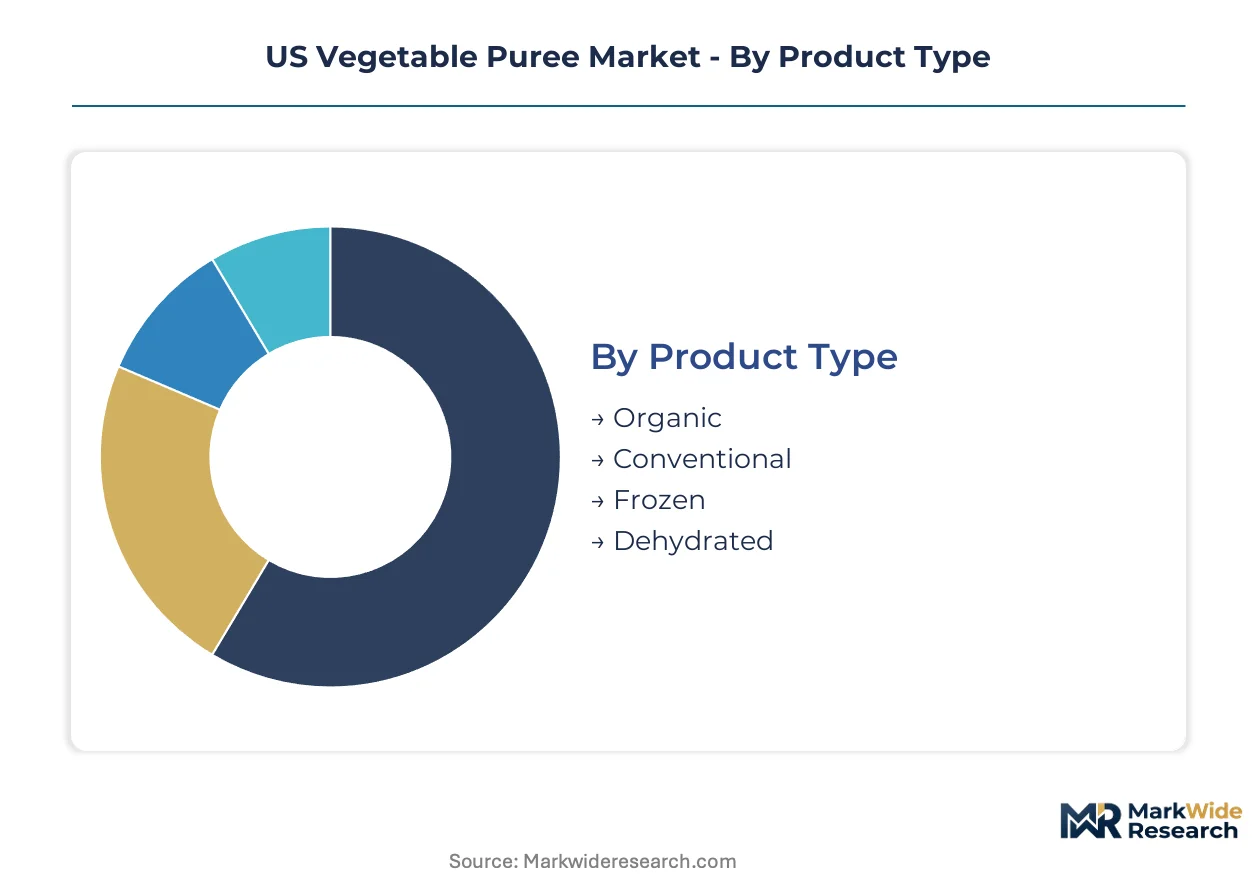
US vegetable puree demand fragments across four structural dimensions that determine procurement economics and margin capture. Product type and end-use specifications dictate processing intensity and certification requirements. Packaging and channel choices separate commodity volume plays from premium positioning strategies.
Product Type:
Integration depth varies sharply: organic and conventional purees embed into formulated foods as invisible ingredients, while frozen and dehydrated formats function as standalone inputs requiring reconstitution.
- Organic:USDA National Organic Program certification mandates ingredient traceability and prohibits synthetic inputs throughout cultivation and processing. Baby food manufacturers in California's Central Valley corridor absorb premium pricing to satisfy parental demand for clean-label positioning. Organic acreage constraints tighten raw material availability and inflate procurement costs relative to conventional alternatives.
- Conventional:Mechanically processed vegetable matter without organic certification carries lower input costs and broader supply availability. Food industry formulators in sauce and soup applications prioritize cost efficiency over certification premiums. Conventional sourcing dominates volume contracts with institutional foodservice operators.
- Frozen:Blast-frozen puree blocks preserve cellular structure and flavor intensity through -18°C storage chains. Cold chain logistics intensity concentrates operational risk in refrigerated transport networks serving food manufacturers.
- Dehydrated:Low-moisture powder formats reduce shipping weight and eliminate frozen distribution requirements. Snack and beverage formulators value extended shelf stability and reconstitution flexibility.
Conventional leads volumes today; organic is gaining share fastest.
End Use:
Cost tier separation determines specification stringency: infant nutrition commands purity premiums while industrial food manufacturing prioritizes unit economics.
- Food Industry:Sauce, soup, and prepared meal manufacturers specify standardized Brix levels and color consistency for batch uniformity. Foodservice channel expansion opens volume contracts beyond retail as institutional kitchens seek reliable vegetable bases.
- Baby Food:Stringent FDA preventive controls and parental willingness to pay for transparent sourcing accelerate adoption of mechanically processed vegetable bases. Pouch packaging displacement of glass jars concentrates in this segment due to convenience and reduced shipping weight.
- Snacks:Vegetable-infused chip and cracker formulations utilize dehydrated purees for flavor integration and moisture management. Clean-label positioning drives specification upgrades toward organic and cold-pressed inputs.
- Beverage:Smoothie and juice blenders incorporate vegetable purees for nutritional density and color standardization. High-pressure processing adoption preserves nutrient profiles without thermal degradation.
Baby food commands highest margins; food industry delivers largest absolute volumes.
Packaging Type:
Application context dictates format selection: retail-facing units emphasize shelf appeal and handling convenience while industrial bulk formats minimize per-unit logistics cost.
- Glass Jar:Traditional container format retains premium positioning in organic baby food tiers where transparency signals quality. Higher shipping weight and breakage rates disadvantage glass against flexible alternatives in e-commerce channels.
- Tetra Pack:Aseptic carton technology extends shelf stability without refrigeration for ambient distribution. Beverage and soup applications favor this format for rectangular stacking efficiency in retail and foodservice storage.
- Pouch:Single-serve flexible packaging reduces material weight and enables portion-controlled consumption. Baby food segment adoption accelerates through convenience and reduced shipping cost.
- Canned:Metal container format persists in industrial food manufacturing for bulk ingredient storage. Retort sterilization compatibility suits conventional processing lines with established thermal treatment protocols.
Pouch formats are expanding most quickly; glass retains premium tier positioning.
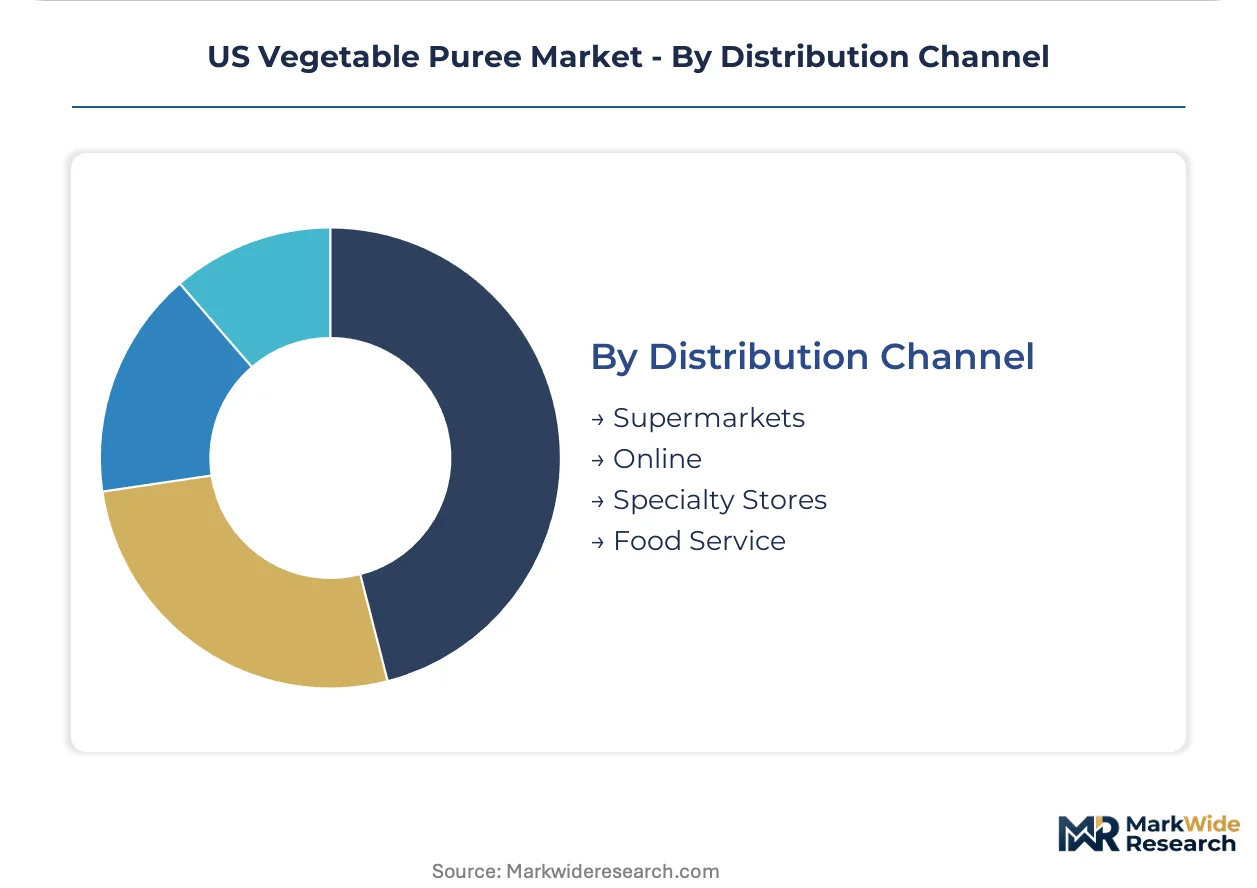
Distribution Channel:
Customer type separation structures go-to-market economics: household purchasers prioritize convenience and discovery while institutional buyers negotiate specification-driven contracts.
- Supermarkets:Mass retail placement demands slotting fees and promotional support for shelf visibility. Baby food and snack segments concentrate in conventional and natural grocery banners.
- Online:Direct-to-consumer and third-party marketplace sales enable subscription-based auto-replenishment for infant nutrition. Urban coastal markets with dense delivery infrastructure support cold chain reliability for temperature-sensitive shipments.
- Specialty Stores:Natural and organic retailers curate premium product assortments with transparent sourcing claims. Organic certification and minimal-processing positioning command price premiums in this channel.
- Food Service:Restaurant chains and institutional kitchens procure standardized vegetable bases through broadline distributors. Volume contracts emphasize consistency and food safety documentation over brand recognition.
Supermarkets anchor current volume; online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vegetable puree production in the United States traces its industrial roots to post-World War II food processing expansion in California's Central Valley, where tomato and carrot processing infrastructure established the foundation for modern puree manufacturing. Cold chain logistics networks and aseptic filling technology subsequently enabled national distribution of shelf-stable vegetable bases.
California
California's Central Valley agricultural corridor hosts the densest concentration of vegetable processing infrastructure, with Fresno and Modesto metropolitan areas anchoring tomato, carrot, and squash puree operations. FDA Food Safety Modernization Act preventive controls and California Department of Public Health processing regulations impose dual compliance layers on Central Valley manufacturers. Cold chain logistics from processing facilities through the Port of Oakland support West Coast distribution and export positioning.
Washington
Washington State's Columbia Basin irrigation district supplies potato, pea, and beet raw materials to puree processors serving Pacific Northwest food manufacturers. State Department of Agriculture inspection protocols and FDA cooperative agreements govern facility compliance for processors operating in the Yakima Valley cluster. Rail connectivity through BNSF and Union Pacific corridors enables eastward shipment of frozen puree blocks to Midwest food industry customers.
Midwest
Illinois and Ohio food manufacturing corridors absorb substantial vegetable puree volumes for sauce, soup, and prepared meal production. USDA National Organic Program certification requirements shape procurement patterns for Chicago-area baby food formulators. Interstate highway density and refrigerated distribution centers in Gary and Columbus support just-in-time delivery to industrial food processors.
Texas
Texas Gulf Coast logistics hubs facilitate import receipt of tropical vegetable purees for blending with domestic production. State health department food manufacturing regulations and FDA import inspection protocols govern border-adjacent processing operations. Houston and Dallas-Fort Worth distribution centers serve expanding foodservice channel demand from restaurant chain headquarters.
Northeast
New York and New Jersey metropolitan markets concentrate premium organic puree consumption through natural and specialty retail channels. State-level organic certification reciprocity with USDA National Organic Program streamlines interstate commerce for New England baby food brands. Port of Newark cold storage infrastructure supports import of European specialty purees for high-end foodservice applications.
US Vegetable Puree Market Key Industry Players
The competitive structure tilts toward ingredient technology specialists and vertically integrated processors. Market concentration remains moderate, with multinational ingredient suppliers occupying premium tiers alongside regional processors serving foodservice volume contracts. Two archetypes dominate: technology-led ingredient platforms supplying customized bases, and farm-to-filling integrated operators controlling raw material sourcing. Capacity expansion and aseptic packaging partnerships represent the primary competitive moves, with processors securing filling line access through equipment alliances rather than capital deployment.
Within the ingredient technology tier, Döhler and SVZ Industrial Fruit & Vegetable Ingredients exemplify platform-based supply models, while F&S Produce Co. occupies a position among vertically integrated processors. Grünewald International and Dennick FruitSource represent North American regional specialists. Les vergers Boiron and Encore Fruit Marketing sit within the premium import-dependent segment. foodguys and Ingredion Incorporated anchor commodity-scale distribution capabilities.
| Leading Market Players |
|---|
| Grünewald International |
| Dennick FruitSource |
| Döhler |
| Encore Fruit Marketing |
| F&S Produce Co. |
| SVZ Industrial Fruit & Vegetable Ingredients |
| Les vergers Boiron |
| foodguys |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Organic-conventional certification divergence splits procurement economics and logistics configurations across California's Central Valley corridor, with USDA National Organic Program compliance commanding premium positioning through constrained acreage and segregated handling protocols that inflate both input costs and cold chain complexity relative to conventional bulk operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic purees from conventional mechanically processed bases and dehydrated commodity powders. Price differentiation rests on certification grade and volume scale, with baby food manufacturers absorbing the steepest premiums for traceable sourcing. Cost compression in conventional tiers is intensifying because foodservice buyers consolidate volume contracts. Institutional kitchens exhibit highest price sensitivity; infant nutrition brands show least.
Supply Chain Analysis
Single-source vulnerability sits with California's Central Valley tomato and carrot processing cluster, where Fresno and Modesto metropolitan areas anchor over half of domestic puree production. Raw material supply draws from irrigated acreage in the Columbia Basin and Central Valley, with aseptic filling equipment and refrigerated transport fleets as critical downstream dependencies. Tariff exposure on imported tropical vegetable inputs threatens blending operations in Texas Gulf Coast hubs. Distribution runs through cold storage networks at Oakland, Newark, and Houston ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US vegetable puree hinges on cold-pressed minimal processing premiums offsetting organic acreage constraints, as parental willingness to pay for clean-label positioning outpaces input cost inflation across the forecast horizon.
For Market Incumbents: Deploy aseptic filling partnerships to defray capital intensity while securing extended-shelf-life packaging capacity. Deepen backward integration into Central Valley organic acreage through contract farming arrangements to defend against raw material availability constraints. FDA traceability rule compliance investments create defensive moats against smaller processors lacking digital infrastructure scale. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting urban coastal households with auto-replenishment infant nutrition. Foodservice channel white space offers penetrable volume contracts for standardized vegetable bases in institutional kitchens. Cold-pressed minimal processing claims command premium positioning with health-conscious adult consumers outside baby food saturation. For Investors and Strategic Acquirers: Consolidation pressure builds where aseptic filling capex requirements and FDA preventive control compliance costs outstrip regional processor balance sheet capacity. Long-term viability favors vertically integrated operators with captive organic supply and West Coast processing infrastructure. Watch cold chain logistics reliability as inflection indicator for subscription channel expansion sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Partnership | Reduces capital deployment burden while securing shelf-stable packaging technology for pouch formats. |
| Backward Integration into Organic Acreage | Captive supply of USDA-certified raw materials insulates against Central Valley land constraints. |
| Cold-Pressed Processing Investment | High-pressure processing technology commands premium positioning through nutrient-preservation claims. |
| Foodservice Channel Expansion | Institutional volume contracts diversify revenue beyond retail baby food saturation. |
| Digital Traceability Infrastructure | FDA Food Safety Modernization Act compliance creates inspection-readiness advantage. |
Research Approach
Multiple input streams — primary interviews with baby food formulators and Central Valley processing executives, secondary validation through USDA National Organic Program filings and FDA enforcement data, and trade flow analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included procurement leads at infant nutrition brands, plant managers at aseptic filling facilities, and category buyers at natural grocery banners. Secondary sources encompassed California Department of Public Health processing regulations, cold chain logistics operator disclosures, and agricultural acreage reports from the Central Valley.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled included product type tier, end-use application, packaging format, and distribution channel, with organic certification status as an industry-specific cross-cutting variable. CAGRs were derived from trend extrapolation of historical volume movements adjusted for regulatory phase-in effects and channel migration patterns. Forecast inputs incorporated parental purchasing behavior shifts and foodservice contract velocity as demand-side drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under organic acreage expansion delays or FDA traceability rule acceleration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Global Pickle Market