
 Bahrain Fruits and Vegetables Market | 2026-2036
Bahrain Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Fruits and Vegetables Market Outlook
Asset-light leasing models for cold-chain logistics is rewriting competitive entry barriers for produce distributors in Bahrain. Lulu Hypermarket leverages its Gulf-wide procurement network to sustain lower sourcing costs on imported tropical fruits. Al Ghadeer Agricultural Company anchors domestic supply through controlled-environment greenhouse operations across the Northern Governorate. Gulf Produce Company competes on last-mile delivery velocity to hotels and catering clients in Manama.
Bahrain fruits and vegetables encompass fresh and minimally processed edible plant products with moisture content typically exceeding 80 percent, harvested for direct human consumption or light processing into salads, juices, and prepared meals. These products require continuous temperature control between zero and four degrees Celsius through the supply chain to preserve organoleptic quality and prevent microbial degradation. Leafy Greens command premium shelf positioning in supermarket chilled sections due to perishability-driven replenishment cycles and higher margin capture. Citrus Fruits dominate import volumes through the Port of Khalifa Bin Salman, reflecting Bahrain's climatic constraints on local cultivation of subtropical varieties. The Wholesale channel occupies substantial throughput share, though Online Retail is accelerating as delivery platforms consolidate grocery and restaurant supply orders.
Bahrain's national food safety authority enforces pesticide Maximum Residue Limits aligned with Gulf Standardization Organization frameworks, compelling importers to maintain batch-level laboratory certification. The Ministry of Municipalities Affairs and Agriculture oversees irrigation water quality standards for domestic farms, directly constraining allowable cultivation acreage in groundwater-dependent regions. Stakeholders must monitor evolving biodegradable packaging mandates from Bahrain's Supreme Council for Environment, as single-use plastic restrictions reshape produce presentation requirements across all distribution channels.
Market Dynamics
Hotel procurement consolidation across Manama and Riffa is compressing distributor margins while amplifying volume concentration among certified cold-chain operators. The national food safety authority's pesticide residue enforcement is simultaneously elevating compliance costs and rewarding integrated greenhouse producers with laboratory certification capabilities.
Growth Catalysts
- Gulf Standardization Organization alignment:Bahrain's Maximum Residue Limits framework creates competitive moats for importers maintaining batch-level laboratory documentation, accelerating certified supplier consolidation.
- Controlled-environment greenhouse expansion:Domestic hydroponic and vertical farming installations in the Northern Governorate reduce import dependency for leafy greens and premium herbs.
- Hospitality sector procurement centralization:Hotel chains and catering operators in Manama are consolidating produce purchasing through contracted distributors, favoring scale-capable logistics providers.
Market Restraints
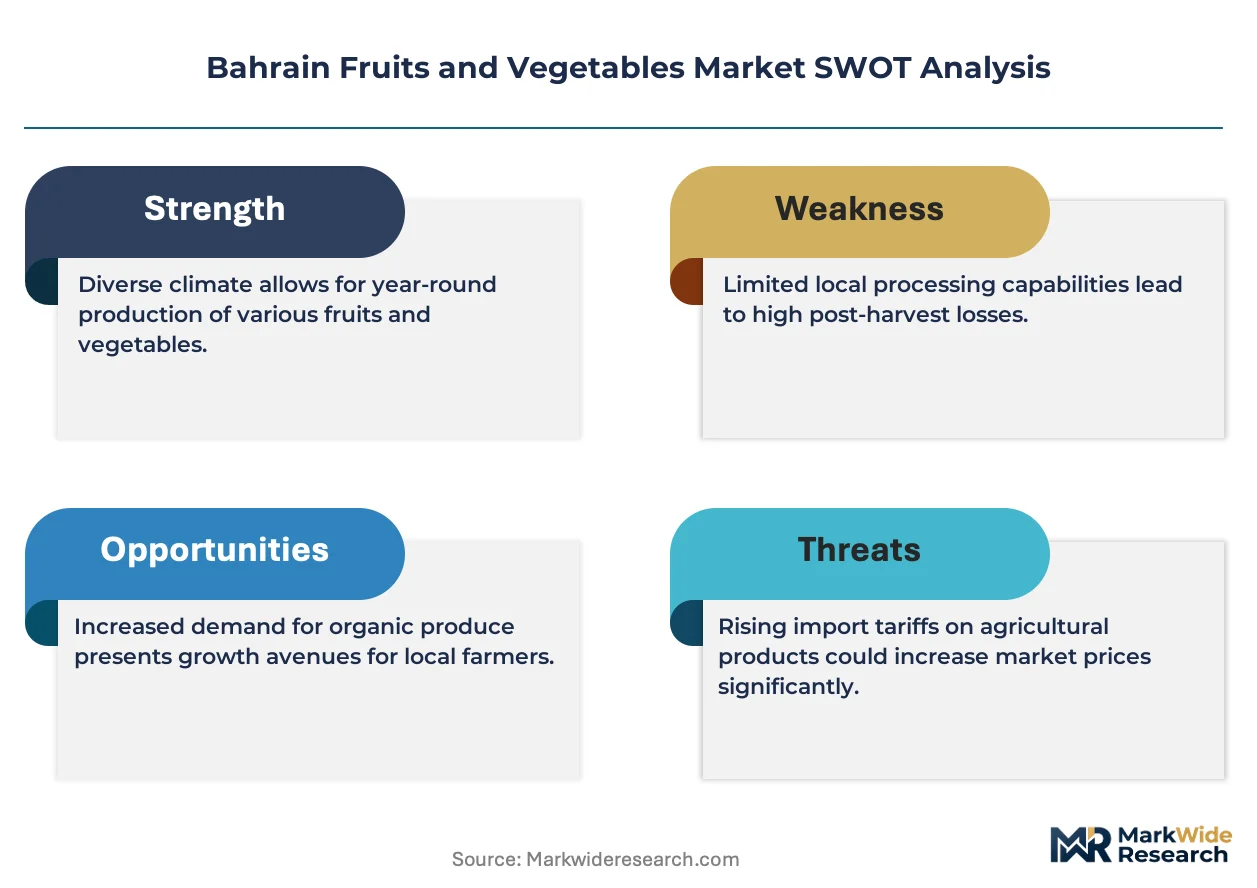
- Groundwater irrigation constraints:Ministry of Municipalities Affairs and Agriculture water quality standards restrict allowable cultivation acreage in aquifer-dependent regions, capping domestic production expansion.
- Single-source import concentration:Citrus Fruits and tropical varieties flow predominantly through Port of Khalifa Bin Salman, creating vulnerability to shipping disruptions and customs processing delays.
- Biodegradable packaging cost premium:Supreme Council for Environment mandates on single-use plastic elimination impose material cost escalations that squeeze distributor margins without full pass-through pricing power.
Strategic Opportunities
- Asset-light cold-chain leasing:Refrigerated transport and warehousing rental models lower capital barriers for new entrants seeking hotel and restaurant supply contracts.
- Online Retail platform consolidation:Grocery delivery platforms aggregating consumer and restaurant orders present channel expansion paths for mid-size distributors lacking direct retail relationships.
- Hotel chain backward integration:Hospitality operators exploring captive greenhouse investments for high-turnover items create partnership opportunities with established agricultural technology providers.
Industry Challenges
- Certified agronomist scarcity:Controlled-environment farming expansion outpaces technical training pipeline, forcing operators to import greenhouse management expertise at elevated compensation.
- Laboratory testing capacity bottlenecks:Batch-level pesticide residue verification requirements exceed domestic certified facility throughput during seasonal import surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Fruits and Vegetables Market |
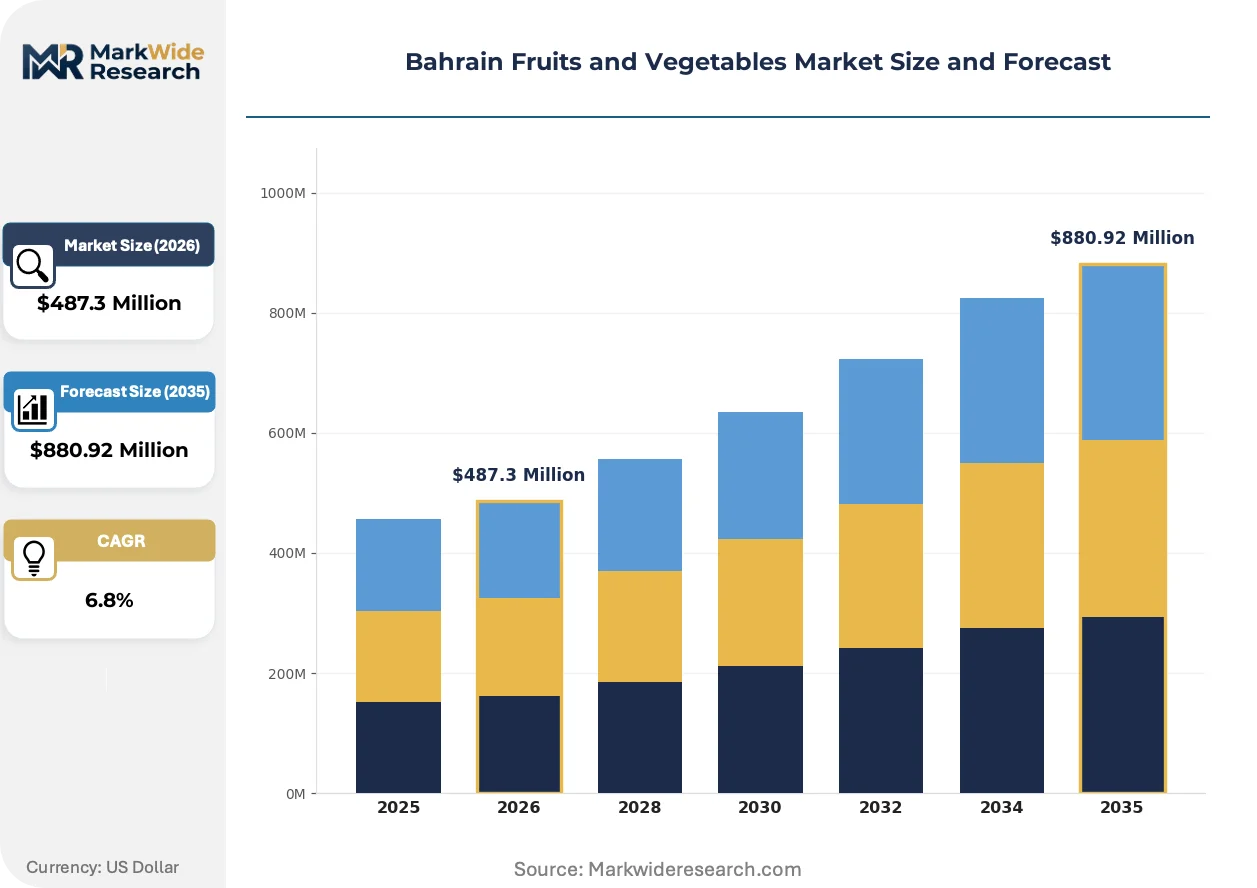
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Fruits, Leafy Greens, Root Vegetables, Stone Fruits End User: Retail Consumers, Restaurants, Hotels, Wholesalers Packaging Type: Bulk Bins, Plastic Containers, Cardboard Boxes, Styrofoam Trays Distribution Channel: Supermarkets, Local Markets, Online Retail, Export |
| Companies Covered | Lulu Hypermarket (Lulu Group International), Carrefour (Majid Al Futtaim Group), Alosra Supermarket, Geant Hypermarket, Al Baraka Dates, Al Ghadeer Agricultural Company, MBT Fruits and Vegetables, Gulf Produce Company, Bahrain Vegetables and Fruits Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Fruits and Vegetables Market Strategic Shifts
Digital traceability platforms and climate-controlled logistics are converging to reshape how produce quality is verified and preserved across Bahrain's import-dependent supply chain. These shifts are elevating transparency requirements while compressing acceptable delivery windows.
Blockchain-enabled provenance tracking is virtualizing quality assurance documentation for imported produce shipments. Supermarket chains and hotel procurement departments are mandating digital ledger integration for premium-tier suppliers. This technology is virtualizing the traditional paper-based certification chain, compressing dispute resolution timelines and reducing fraud exposure in cross-border transactions.
Bahrain's Supreme Council for Environment is advancing biodegradable packaging mandates that will eliminate conventional plastic produce containers within the retail channel. The regulation forces importers and domestic growers to redesign presentation formats and absorb material cost transitions. Leafy Greens and prepared salad segments face the most acute compliance pressure due to high packaging-to-product ratios and chilled display requirements.
Consolidated platform ordering is displacing fragmented wholesale purchasing patterns among restaurants and smaller hotels. Manama-based catering operators are migrating toward integrated procurement applications that aggregate produce with protein and dry goods. This behavioral shift concentrates purchasing power among technology-enabled distributors while marginalizing traditional cash-and-carry wholesale operations in the capital region.
Bahrain Fruits and Vegetables Market Segmentation
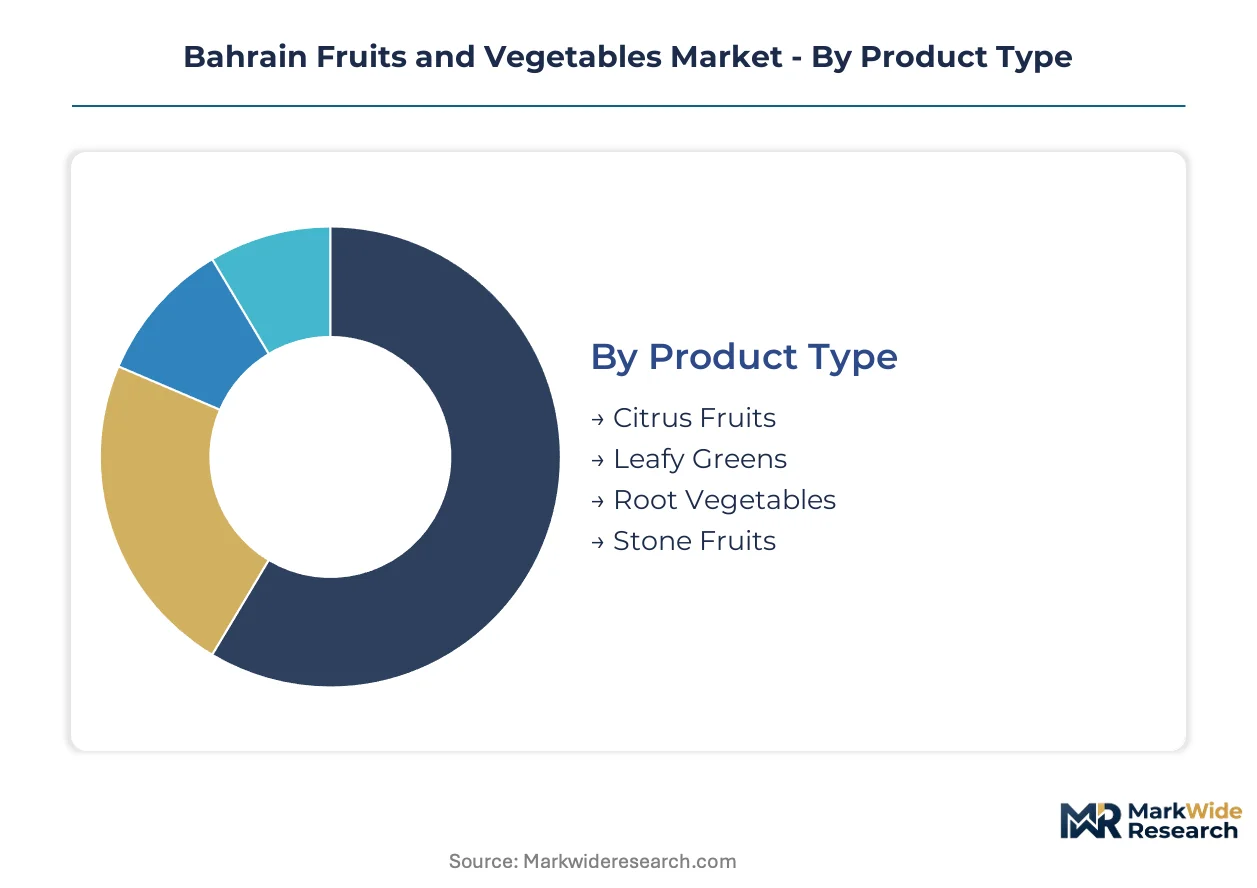
Segmentation in Bahrain's produce market reveals how import dependency, perishability profiles, and channel concentration create distinct competitive arenas. Each dimension exposes different margin pressures and certification requirements that shape supplier positioning.
Product Type:
Mature categories dominate import volumes while emerging segments drive domestic greenhouse investment.
- Citrus Fruits:Oranges, lemons, and grapefruits imported primarily through Port of Khalifa Bin Salman face strict Gulf Standardization Organization residue testing. Hotel procurement in Manama concentrates demand for premium-grade varieties with full batch documentation.
- Leafy Greens:Spinach, lettuce, and herbs with moisture content exceeding 90 percent require continuous zero-to-four-degree Celsius cold chains. Northern Governorate hydroponic operations are capturing share from imports as Al Ghadeer Agricultural Company expands controlled-environment acreage.
- Root Vegetables:Carrots, potatoes, and beets tolerate longer storage cycles and simpler logistics.
- Stone Fruits:Peaches, plums, and cherries face seasonal availability constraints and elevated air-freight costs.
Citrus Fruits retains volume leadership; Leafy Greens holds the steepest expansion curve.
End User:
Customer type determines certification depth, delivery velocity requirements, and pricing power distribution across the supply chain.
- Retail Consumers:Supermarket chains now dominate purchasing patterns, demanding digital traceability and biodegradable packaging compliance per Supreme Council for Environment mandates. Chilled section positioning drives premium placement fees for perishable categories.
- Hotels:Procurement consolidation across Manama and Riffa compresses distributor margins while amplifying volume concentration. Contracted supply agreements favor certified cold-chain operators with laboratory certification capabilities.
- Restaurants:Platform ordering through consolidated procurement applications is displacing cash-and-carry wholesale patterns.
- Wholesalers:Traditional throughput intermediaries face margin erosion from direct-to-hotel distributor relationships.
Retail Consumers anchors absolute volume; Hotels demonstrates the most rapid procurement centralization.
Packaging Type:
Material cost structures and regulatory compliance timelines differentiate competitive positioning across presentation formats.
- Plastic Containers:Conventional clamshells and punnits face phase-out pressure under single-use plastic elimination mandates. Importers and domestic growers absorb material cost transitions while redesigning presentation formats for Leafy Greens segments.
- Cardboard Boxes:Corrugated fiberboard dominates bulk transport for Root Vegetables and Citrus Fruits with lower packaging-to-product ratios. Wet-strength grades handle condensation from chilled distribution without structural degradation.
- Bulk Bins:Reusable plastic totes serve high-volume restaurant and hotel procurement with return logistics requirements.
- Styrofoam Trays:Expanded polystyrene faces complete prohibition under environmental mandates with limited replacement alternatives for moisture-sensitive presentations.
Cardboard Boxes maintains cost leadership; Plastic Containers confronts the most urgent compliance transition.
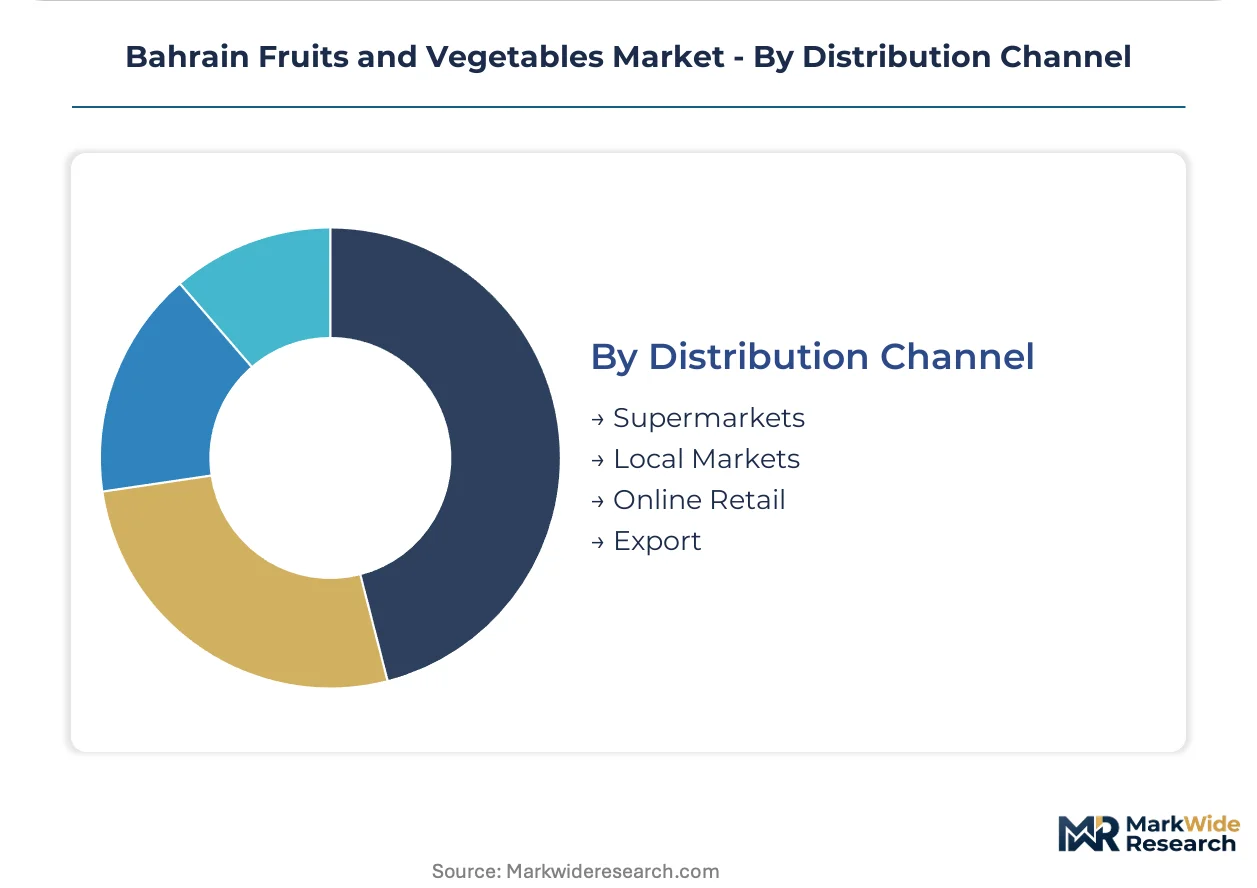
Distribution Channel:
Channel selection dictates capital intensity, customer relationship structures, and technology integration requirements for produce suppliers.
- Supermarkets:Lulu Hypermarket and competing chains leverage Gulf-wide procurement networks to sustain lower sourcing costs on imported tropical fruits. Blockchain-enabled provenance tracking is becoming mandatory for premium-tier supplier status.
- Online Retail:Grocery delivery platforms aggregating consumer and restaurant orders present channel expansion paths for mid-size distributors. Last-mile delivery velocity requirements compress acceptable fulfillment windows.
- Local Markets:Traditional souk operations in Manama retain price-sensitive consumer segments with minimal certification documentation.
- Export:Limited re-export activity focuses on premium greenhouse products to neighboring Gulf Cooperation Council markets.
Supermarkets commands throughput dominance; Online Retail exhibits the most rapid behavioral shift acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hotel procurement teams in Manama and Riffa concentrate purchasing power among certified cold-chain operators, while retail consumers drive volume through supermarket chains. Groundwater irrigation constraints and port logistics shape supply patterns across Bahrain's governorates.
Capital Governorate
Manama's hotel and restaurant clusters generate concentrated demand for premium-grade produce with full batch documentation. The Supreme Council for Environment enforces biodegradable packaging mandates that eliminate single-use plastic containers across retail channels. Seef Mall and City Centre Bahrain anchor supermarket expansion with blockchain-enabled provenance tracking requirements.
Northern Governorate
Controlled-environment greenhouse operations supply leafy greens and premium herbs to domestic buyers seeking reduced import dependency. Ministry of Municipalities Affairs and Agriculture irrigation water quality standards cap allowable cultivation acreage in groundwater-dependent zones. Al Ghadeer Agricultural Company anchors hydroponic production across this sub-region.
Southern Governorate
Traditional wholesale throughput retains price-sensitive segments with minimal certification documentation. The national food safety authority's pesticide Maximum Residue Limits enforcement elevates compliance costs for importers serving this area. Riffa's emerging hospitality corridor is consolidating procurement through contracted distributors with laboratory certification capabilities.
Muharraq Governorate
Port of Khalifa Bin Salman logistics infrastructure channels citrus fruits and tropical varieties into domestic distribution networks. Gulf Standardization Organization alignment creates competitive moats for importers maintaining batch-level laboratory documentation. Muharraq Island's retail density supports supermarket chain expansion with chilled section premium positioning.
Bahrain Fruits and Vegetables Market Competitive Environment
Channel-controlling players compete with product-specialist players across Bahrain's produce supply chain. Supermarket chains with Gulf-wide procurement networks dominate retail throughput, while agricultural operators with controlled-environment capabilities anchor domestic supply. Three archetypes define competitive positioning: Gulf-integrated retailers leveraging regional sourcing scale, domestic greenhouse specialists with certification advantages, and logistics-focused distributors competing on last-mile velocity. Capacity expansion in cold-chain infrastructure and strategic partnerships with hospitality procurement departments represent the dominant competitive moves.
Among Gulf-integrated retailers, Lulu Hypermarket and Carrefour exemplify channel-controlling archetypes that sustain sourcing cost advantages through regional procurement networks. Al Ghadeer Agricultural Company occupies a position within the domestic greenhouse specialist tier, representing controlled-environment production capabilities that reduce import dependency for perishable categories. Gulf Produce Company sits within the logistics-focused distributor archetype, anchoring competitive positioning around delivery velocity to hospitality clients in Manama.
| Leading Market Players |
|---|
| Lulu Hypermarket (Lulu Group International) |
| Carrefour (Majid Al Futtaim Group) |
| Alosra Supermarket |
| Geant Hypermarket |
| Al Baraka Dates |
| Al Ghadeer Agricultural Company |
| MBT Fruits and Vegetables |
| Gulf Produce Company |
| Bahrain Vegetables and Fruits Co. |
| Others |
Value Chain & Pricing Dynamics
Port of Khalifa Bin Salman import concentration for citrus and tropical varieties funnels margin capture toward certified cold-chain operators with laboratory documentation capabilities. Hotel procurement consolidation across Manama and Riffa amplifies volume concentration among these operators while compressing distributor margins in the wholesale tier.
Pricing Analysis
Certification level creates the primary spread between Gulf Standardization Organization-compliant suppliers and undocumented importers. Three-tier pricing structure across premium certified, standard commercial, and economy cash-and-carry levels segments the market by traceability depth and residue testing rigor. Cost compression in the wholesale tier intensifies as supermarket chains and hotel procurement departments extract volume discounts from mid-size distributors. Retail consumers through supermarket channels demonstrate lowest price sensitivity due to chilled-section premium positioning, while traditional souk buyers in the Southern Governorate anchor the economy tier.
Supply Chain Analysis
Extended payment terms from hotel procurement departments and supply-chain finance facilities from regional banks are restructuring working capital requirements for produce distributors. Geographic supply concentration draws from India, Egypt, and Jordan for leafy greens and herbs, with citrus varieties sourcing from Spain, South Africa, and Egypt. Cold-chain equipment, greenhouse technology, and laboratory testing capacity constitute critical input dependencies. Single-source import vulnerability through Port of Khalifa Bin Salman creates exposure to customs processing delays and shipping disruptions. Distribution runs through contracted logistics providers serving hospitality clusters, supermarket distribution centers, and consolidated online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's produce market fragments across certification tiers, channel structures, and geographic supply sources, creating entry niches for specialists who capture demand-side shifts toward digital traceability and controlled-environment domestic production.
For Market Incumbents: Insulate margin pools by deepening backward integration into Northern Governorate greenhouse capacity and securing exclusive procurement contracts with expanding hotel chains in Riffa's emerging hospitality corridor. The threat of asset-light cold-chain leasing models lowering entry barriers for new distributors demands preemptive channel control investments. Certification infrastructure expansion at batch level will defend positioning against supermarket chains mandating blockchain-enabled provenance tracking. For New Entrants and Emerging Players: Build out online retail platform partnerships aggregating restaurant and consumer orders, as this channel exhibits the most rapid behavioral shift acceleration with compressed fulfillment windows creating service differentiation opportunities. The most penetrable segment sits among mid-size hotel operators in Manama lacking direct relationships with Gulf-integrated retailers. A go-to-market angle anchored in biodegradable packaging compliance ahead of Supreme Council for Environment mandates will capture regulatory-driven switching demand. For Investors and Strategic Acquirers: Capital is best deployed toward domestic greenhouse specialists with controlled-environment capabilities and existing laboratory certification infrastructure, as these assets compound in value under tightening pesticide residue enforcement. Long-term viability over a five-to-ten year window hinges on import substitution potential for perishable categories and hospitality sector procurement centralization trends. The signal to watch is Ministry of Municipalities Affairs and Agriculture irrigation water quality standard revisions, which would either expand or contract allowable cultivation acreage in groundwater-dependent regions.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Greenhouse Expansion | Al Ghadeer Agricultural Company demonstrates how hydroponic capacity reduces import dependency for leafy greens. |
| Blockchain-Enabled Provenance Tracking | Lulu Hypermarket mandates digital ledger integration for premium-tier supplier status across its Gulf-wide network. |
| Biodegradable Packaging Transition | Supreme Council for Environment mandates eliminate single-use plastic containers, forcing material cost absorption. |
| Cold-Chain Logistics Partnership | Gulf Produce Company competes on last-mile delivery velocity to hotels and catering clients in Manama. |
| Hotel Procurement Consolidation | Contracted supply agreements favor certified operators with laboratory capabilities across Manama and Riffa. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supermarket category buyers, hotel procurement managers, greenhouse operations directors, cold-chain logistics providers, and national food safety authority officials. Secondary validation drew from Gulf Standardization Organization regulatory filings, Ministry of Municipalities Affairs and Agriculture irrigation standards, Supreme Council for Environment packaging mandates, customs import records through Port of Khalifa Bin Salman, and hospitality sector procurement databases. Bottom-up volume triangulation across product segments, end-user channels, and regional governorates was cross-checked against top-down market sizing from trade flow analysis.
Calibration against historical trade volumes and known production capacities anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, packaging format, and distribution channel, with additional granularity on certification tier and cold-chain compliance level. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and infrastructure investment pipelines. Industry-specific forecast inputs incorporated groundwater irrigation constraint scenarios and biodegradable packaging mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Gulf-integrated retailers or accelerated hotel backward integration into captive greenhouse operations would shift outcomes beyond modeled ranges. Macroeconomic deviation affecting hospitality sector investment, regulatory tightening on pesticide residue limits, or technological breakthroughs in vertical farming economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market