
 United Arab Emirates Fruits and Vegetables Market | 2026-2036
United Arab Emirates Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Fruits and Vegetables Market Analytics
Hotel and restaurant procurement is rotating toward domestically grown premium produce, displacing traditional reliance on re-exported goods. Kibsons International LLC leverages its direct farm-to-door logistics platform to capture this shift. Pure Harvest Smart Farms anchors supply with its controlled-environment agriculture facility in Nahel. Elite Agro LLC competes through its integrated desert farming and packing operations across multiple emirates.
Fresh fruits and vegetables encompass edible plant materials harvested for direct consumption, comprising structures ranging from citrus hesperidia with specialized oil-gland rind tissues to leafy brassicas with high post-harvest respiration rates requiring cold-chain maintenance within hours of picking. The category serves nutritional, culinary, and food-service processing functions across commercial and institutional channels. Leafy Greens command premium positioning due to perishability constraints and local vertical farm output limitations. Supermarkets dominate volume throughput while Online Retail captures the fastest expansion as delivery infrastructure matures across Abu Dhabi and Dubai.
MOHAP enforces Hazard Analysis Critical Control Point standards across all fresh produce handling facilities, elevating compliance costs for smaller traders. FSSAI-aligned import inspection protocols at Dubai's logistics hubs govern entry for Indian and Pakistani consignments. Emirates Authority for Standardization and Metrology mandates pesticide residue thresholds that shape domestic cultivation practices. Stakeholders must monitor water tariff reforms and desalination energy pricing as these inputs determine the economic viability of local greenhouse expansion against imported alternatives.
Market Dynamics
UAE hospitality procurement is rotating toward domestically grown premium produce, displacing traditional reliance on re-exported goods through MOHAP-certified channels and controlled-environment agriculture investments.
Growth Catalysts
- MOHAP Food Safety Protocols:Mandatory Hazard Analysis Critical Control Point standards across all fresh produce handling facilities elevate compliance barriers that favor capitalized local operators over informal traders.
- Vertical Farming Technology:Controlled-environment agriculture facilities in Nahel and Dubai's hospitality corridor supply year-round leafy greens to luxury hotel groups, compressing import dependency.
- Hotel Procurement Consolidation:Expanding luxury hotel chains in Dubai and Abu Dhabi are expanding direct farm partnerships, creating captive demand for premium-grade local output.
Market Restraints
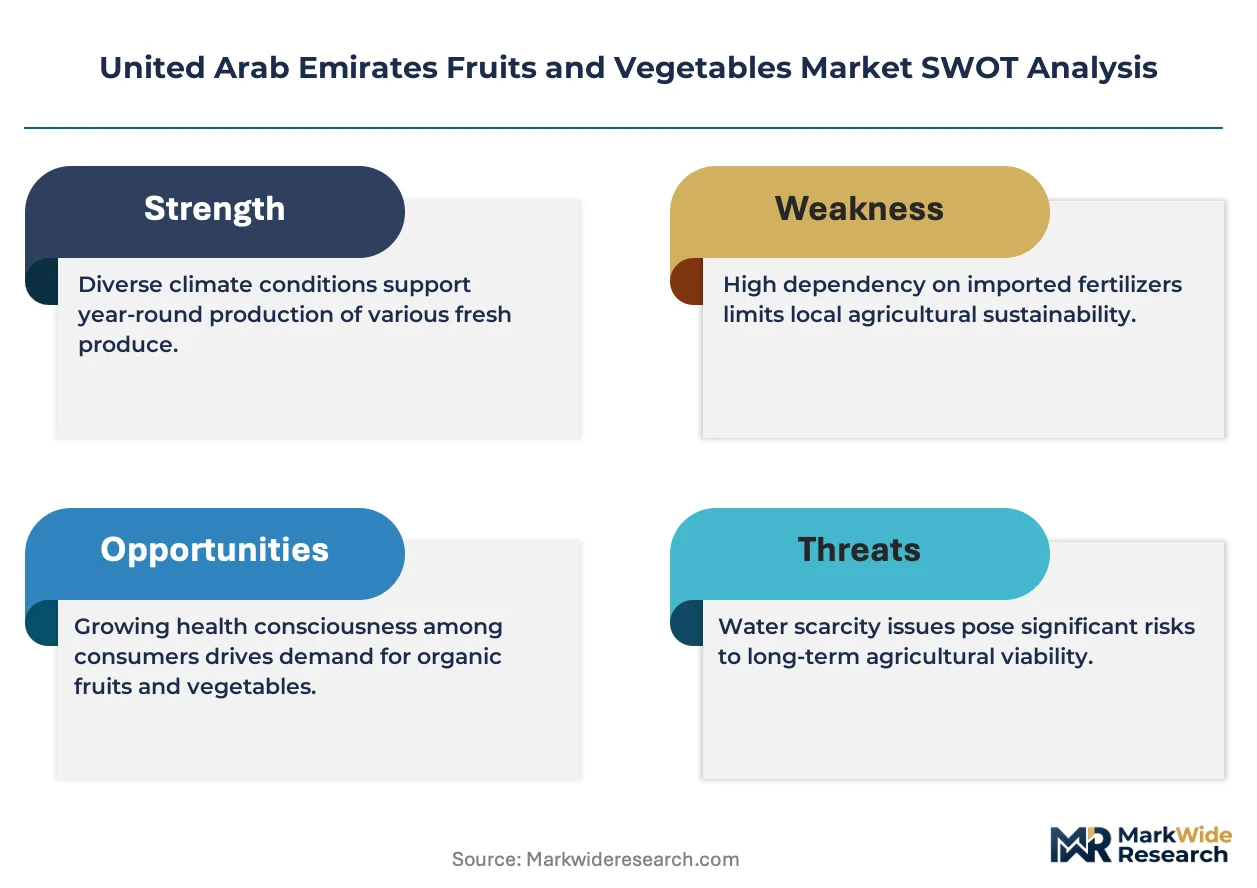
- Desalination Energy Pricing:Greenhouse operations depend on desalinated water inputs where tariff reforms threaten margin structures against lower-cost imported alternatives.
- Import Concentration at Dubai Logistics Hubs:FSSAI-aligned inspection protocols for Indian and Pakistani consignments create single-point bottlenecks that amplify supply risk during peak seasonal demand.
- Leafy Greens Output Limitations:Local vertical farm capacity constraints cap premium domestic supply, forcing continued reliance on air-freighted imports for perishable brassicas.
Strategic Opportunities
- Abu Dhabi Online Retail Infrastructure:Delivery platform maturation across the emirate creates channel expansion potential for direct-to-consumer fresh produce models beyond supermarket dominance.
- Emirates Authority for Standardization and Metrology Incentives:Pesticide residue threshold mandates shape cultivation practices that certified local operators can leverage for export positioning into Gulf Cooperation Council markets.
- Hydroponics-AI Convergence:Integration of sensor networks with nutrient film technique systems enables predictive harvest scheduling that aligns supply with hospitality procurement calendars.
Industry Challenges
- Agritech Engineering Talent Scarcity:Controlled-environment agriculture operations face recruitment gaps for climate systems engineers capable of optimizing desert greenhouse energy efficiency.
- MOHAP Certification Timelines:New facility approval processes extend operational commissioning periods, delaying revenue realization for greenhouse expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Fruits and Vegetables Market |
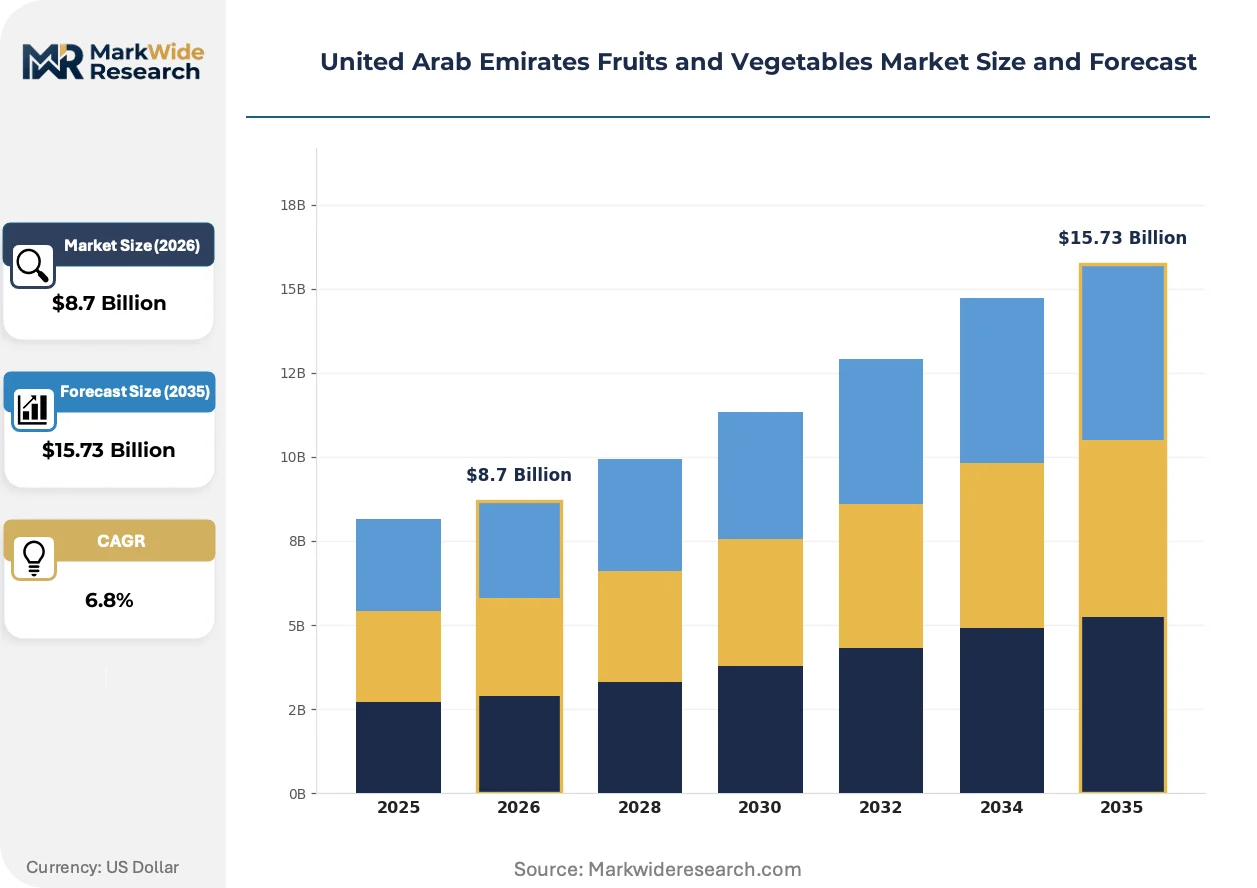
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Fruits, Leafy Greens, Root Vegetables, Berries Distribution Channel: Supermarkets, Farmers Markets, Online Retail, Wholesale End User: Hospitals, Restaurants, Households, Food Service Packaging Type: Bags, Boxes, Clamshells, Bulk |
| Companies Covered | Al Dahra Agriculture, Kibsons International LLC, Greenheart Organic Farms, Elite Agro LLC, Emirates Bio Farm, Al Ain Farms, Pure Harvest Smart Farms, Spinneys Dubai LLC, Carrefour UAE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Fruits and Vegetables Market Evolving Landscape
Technology deployment and regulatory tightening are compressing traditional supply chain layers while procurement patterns fragment across institutional and digital channels.
Containerized vertical farming units are miniaturizing controlled-environment agriculture into modular formats deployable within hotel properties and retail parking structures. Luxury hospitality groups in Dubai are piloting on-site herb production that eliminates last-mile logistics entirely. This distributed model is miniaturizing the geographic footprint of fresh produce supply, compressing the role of centralized distribution centers.
MOHAP enforcement of Hazard Analysis Critical Control Point standards across all fresh produce handling facilities is elevating capital requirements for market participation. Smaller traders face facility upgrade costs that accelerate consolidation toward integrated operators with captive cold-chain infrastructure. Dubai's hospitality corridor exhibits the most pronounced compliance response, with hotel groups now requiring supplier certification documentation as a procurement prerequisite.
Direct farm-to-door logistics platforms are capturing buyer relationships previously held by wholesale market intermediaries. Kibsons International LLC and similar operators connect desert farming facilities with household consumers through subscription models that bypass traditional retail markup structures. Abu Dhabi and Dubai urban corridors display the fastest platform adoption, where delivery infrastructure maturity enables same-day harvest-to-delivery service guarantees.
United Arab Emirates Fruits and Vegetables Market Segmentation
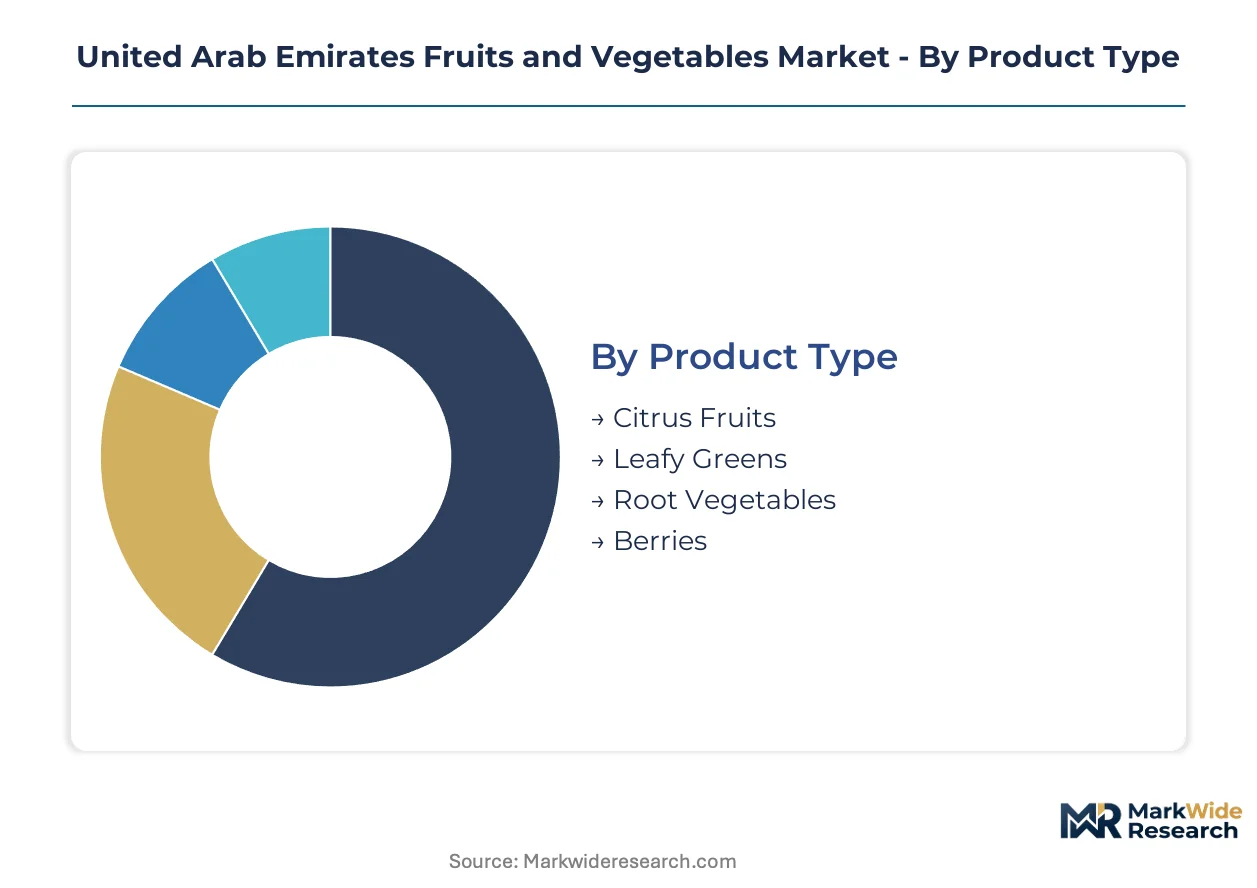
Segmentation reveals how MOHAP certification requirements and hospitality procurement standards reshape channel economics across product categories. Each dimension exposes distinct margin structures and compliance burdens that determine operator viability in the UAE's controlled-environment agriculture expansion.
Product Type:
MOHAP pesticide residue thresholds apply differential stringency across product categories, elevating compliance costs for import-dependent segments while favoring certified domestic cultivation.
- Citrus Fruits:Hesperidia with specialized oil-gland rind tissues require extended cold-chain protocols. Hotels and restaurant chains in Dubai's hospitality corridor source these primarily from re-exported Egyptian and Spanish consignments due to domestic cultivation constraints.
- Leafy Greens:High post-harvest respiration rates demand cold-chain maintenance within hours of picking. Vertical farming operators in Nahel supply year-round output to luxury hotel groups under direct farm partnerships, compressing air-freight dependency for perishable brassicas.
- Root Vegetables:Lower perishability extends shelf life, enabling desert greenhouse cultivation across multiple emirates with reduced energy inputs compared to leafy categories.
- Berries:Extreme climate sensitivity limits domestic production; UAE relies on air-freighted imports from Europe and North Africa with premium pricing at supermarket channels.
Leafy Greens handles the majority of throughput; Online Retail is the fastest mover on share.
Distribution Channel:
Channel economics diverge sharply based on last-mile infrastructure maturity and MOHAP handling facility certification requirements.
- Supermarkets:Dominant volume throughput with established cold-chain infrastructure. Carrefour UAE and Lulu Group International anchor procurement through centralized distribution centers requiring full HACCP documentation.
- Online Retail:Same-day delivery platforms capture household demand through subscription models. Kibsons International LLC leverages direct farm-to-door logistics to bypass traditional retail markups in Abu Dhabi and Dubai urban corridors.
- Farmers Markets:Limited scale due to climate constraints; seasonal operations concentrate in Dubai's indoor retail concepts with curated local producer participation.
- Wholesale:Dubai's logistics hubs consolidate re-export flows from Indian and Pakistani origins under FSSAI-aligned inspection protocols, creating single-point bottlenecks during peak demand periods.
Supermarkets handles the majority of throughput; Online Retail is expanding most quickly.
End User:
End-use concentration determines pricing power and contract structures, with institutional buyers driving standardization.
- Restaurants:Luxury hotel groups mandate MOHAP-certified supplier documentation as procurement prerequisite, consolidating demand toward integrated operators with captive cold-chain infrastructure.
- Households:Fragmented demand captured through supermarket dominance and emerging platform delivery, with price sensitivity highest in this segment.
- Food Service:Catering and institutional kitchens require volume consistency that favors wholesale channel relationships with documented traceability.
- Hospitals:MOHAP food safety protocols elevate compliance requirements; nutrition departments prioritize certified local produce for patient meal programs.
Restaurants handles the majority of throughput; Food Service is climbing the fastest.
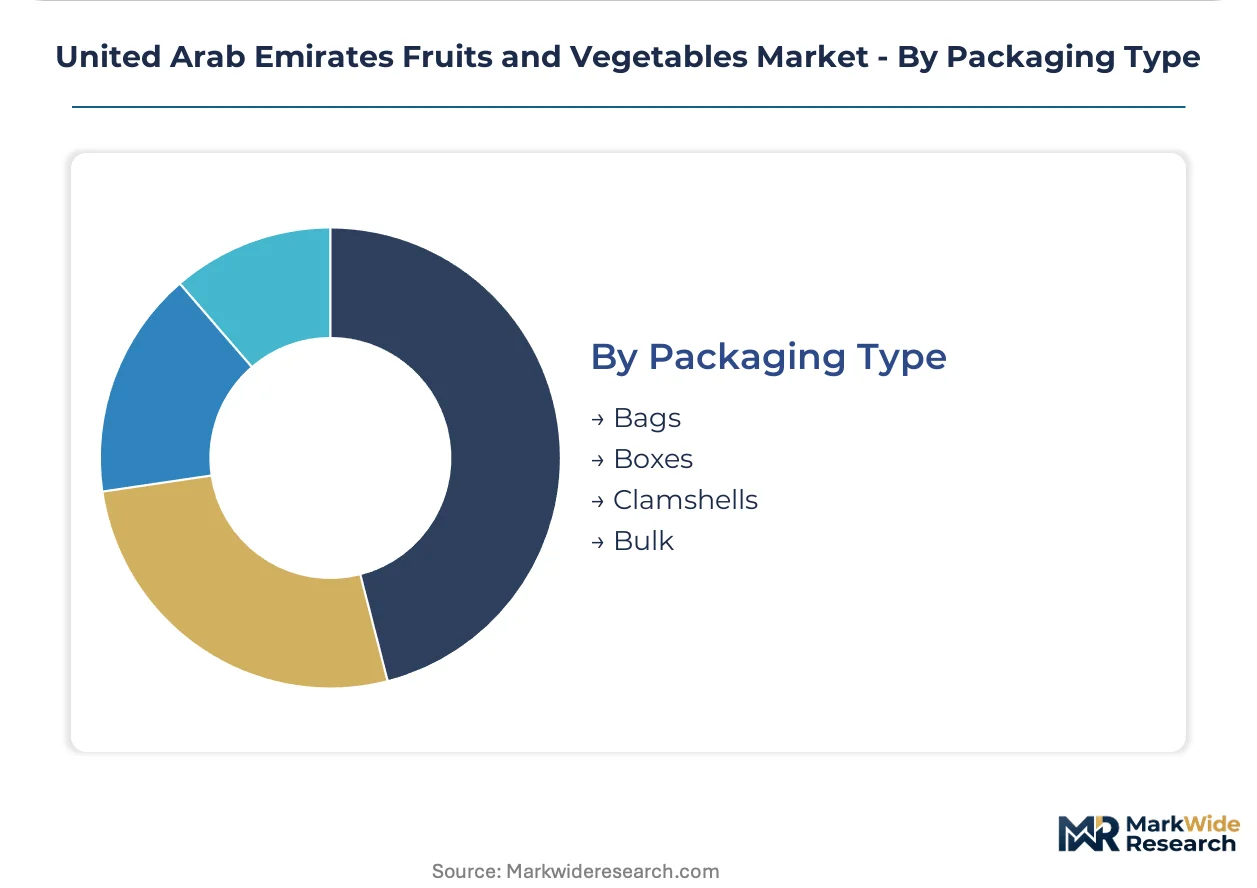
Packaging Type:
Packaging selection reflects shelf-life extension requirements and retail channel presentation standards.
- Clamshells:Rigid containers protect delicate berries and leafy greens through distribution; premium retail positioning aligns with supermarket produce section standards.
- Bulk:Hotels and restaurant chains reduce per-unit packaging costs through direct farm partnerships with reusable container programs.
- Bags:Lightweight format suits root vegetables and citrus with lower bruising risk; dominates discount retail positioning.
- Boxes:Standardized corrugated format enables palletized logistics for wholesale and food service volume procurement.
Bulk handles the majority of throughput; Clamshells is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port anchors the UAE's agricultural trade infrastructure, processing re-export flows from Indian subcontinent origins while supporting domestic controlled-environment agriculture output destined for hospitality and retail channels.
Dubai
Luxury hotel procurement drives demand for MOHAP-certified leafy greens from Nahel-based vertical farms. The Dubai Municipality enforces Hazard Analysis Critical Control Point standards across all fresh produce handling facilities. Dubai's hospitality corridor concentrates year-round supply contracts with controlled-environment agriculture operators serving five-star hotel groups.
Abu Dhabi
Desert greenhouse expansion targets root vegetable cultivation with lower energy inputs than leafy categories. The Abu Dhabi Agriculture and Food Safety Authority administers pesticide residue thresholds aligned with Emirates Authority for Standardization and Metrology mandates. Al Ain anchors integrated farming and packing operations across multiple crop categories for institutional buyers.
Sharjah
Wholesale market consolidation serves northern emirate retail and food service channels through Dubai logistics hub spillover. The Sharjah Chamber of Commerce coordinates with federal MOHAP protocols for cross-emirate distribution compliance. Industrial zones near the Dubai border host cold-chain facilities bridging re-export and domestic supply streams.
Northern Emirates
Ras Al Khaimah and Fujairah concentrate date palm cultivation and seasonal vegetable production for local consumption. Federal water tariff reforms threaten margin structures for open-field operations dependent on desalinated irrigation. Mountain wadi farming in Fujairah supplies limited volumes of traditional crops to ethnic retail segments in Dubai.
United Arab Emirates Fruits and Vegetables Market Competitive Landscape
Listed retail chains compete with private agricultural specialists across procurement channel access and cold-chain infrastructure ownership. Market structure tilts toward integrated operators with captive farming, packing, and distribution assets. Three archetypes dominate: vertically integrated desert farming enterprises, direct-to-consumer logistics platforms, and supermarket chains with centralized HACCP-certified distribution. Capacity expansion and strategic farm partnerships constitute the primary competitive moves.
Within the integrated farming tier, Elite Agro LLC and Pure Harvest Smart Farms exemplify operators combining controlled-environment agriculture with direct hospitality supply relationships. Kibsons International LLC anchors the direct-to-consumer logistics archetype through its farm-to-door subscription platform. These three entities represent distinct strategic positions: captive production for institutional buyers, technology-intensive vertical farming, and digital channel disruption of traditional retail markups.
| Leading Market Players |
|---|
| Al Dahra Agriculture |
| Kibsons International LLC |
| Greenheart Organic Farms |
| Elite Agro LLC |
| Emirates Bio Farm |
| Al Ain Farms |
| Pure Harvest Smart Farms |
| Spinneys Dubai LLC |
| Carrefour UAE |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Nahel vertical farms and Dubai luxury hotel groups lock in supply access while insulating both parties from spot-market volatility in air-freighted leafy greens. These contracts embed MOHAP certification requirements as non-negotiable quality tiers, binding price visibility to compliance investment timelines and desalination energy input costs.
Pricing Analysis
Volume-discount tiering structures separate premium-grade MOHAP-certified produce from standard import-reliant supply and economy-grade wholesale lots. Price differentiation rests on certification grade and cold-chain integrity rather than brand heritage. Pricing pressure stems from desalination tariff reforms that compress greenhouse margins against lower-cost Indian and Pakistani re-exports. Household consumers through online platforms exhibit highest price sensitivity; luxury hotel procurement departments show least.
Supply Chain Analysis
Inventory lead times compress from weeks to hours for leafy greens as Nahel vertical farms synchronize harvest schedules with Dubai hospitality corridor demand calendars. Geographic supply concentrates in India, Pakistan, and Spain for citrus and berries that desert climate cannot support. Raw material dependencies include desalinated water, specialized nutrient formulations, and climate-control equipment. Single-source vulnerability sits at Dubai logistics hubs where FSSAI-aligned inspection protocols create bottlenecks. Distribution runs through direct farm partnerships for institutional buyers and supermarket centralized distribution for household volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as controlled-environment agriculture penetration remains below ten percent of hospitality procurement despite MOHAP regulatory tailwinds accelerating certification requirements.
For Market Incumbents: Compound advantage through backward integration into captive desalination infrastructure and nutrient formulation capabilities that new entrants cannot replicate. Defend against direct-to-consumer platform disruption by locking exclusive variety development partnerships with Emirates Authority for Standardization and Metrology-certified seed suppliers. Priority lever: cold-chain infrastructure ownership across multiple emirates. For New Entrants and Emerging Players: Lead with containerized vertical farming units deployable in Sharjah industrial zones near Dubai border logistics. Target Abu Dhabi online retail corridor where delivery platform maturation outpaces incumbent supermarket response. Go-to-market angle: subscription-based herb and microgreen boxes bypassing traditional retail markup structures entirely. For Investors and Strategic Acquirers: Technology-intensive mid-scale operators with proven hospitality supply relationships and MOHAP certification history represent the highest-conviction acquisition archetype. Long-term viability frames around water-energy nexus efficiency gains and GCC export positioning under Emirates Authority for Standardization and Metrology pesticide residue protocols. Signal to watch: MOHAP facility approval timeline compression as regulatory capacity expands.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Capacity Expansion | Nahel facility scale-up captures year-round leafy greens demand from Dubai five-star hotel groups. |
| Direct Farm Partnership Consolidation | Luxury hospitality procurement departments now require MOHAP certification documentation as mandatory prerequisite. |
| Desalination Infrastructure Backward Integration | Greenhouse operators hedge energy tariff exposure through captive solar-desalination hybrid installations. |
| Online Retail Channel Development | Abu Dhabi and Dubai delivery platform maturity enables same-day harvest-to-delivery service guarantees. |
| GCC Export Certification Investment | Emirates Authority for Standardization and Metrology alignment opens Saudi and Kuwait hospitality procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with vertical farm operations directors, MOHAP compliance officers, luxury hotel procurement managers, and cold-chain logistics specialists; and secondary validation through UAE customs trade records, Emirates Authority for Standardization and Metrology pesticide residue filings, MOHAP facility certification databases, and hospitality industry procurement surveys. Bottom-up cultivation capacity modeling triangulated against top-down hospitality spend allocation estimates.
Across the projection horizon, the analytical framework modeled volume and value outputs through product type, distribution channel, end-user segment, and packaging format dimensions. CAGRs derived from regression analysis against hospitality construction pipelines, desalination energy pricing trajectories, and MOHAP regulatory enforcement intensity. Industry-specific forecast inputs incorporated vertical farm yield curves per square meter and hotel guest-night projections for Dubai and Abu Dhabi corridors.
The analysis sits within stated boundaries; outcomes outside sustained MOHAP certification timeline compression and stable desalination tariff regimes would require recalibration. Forecasts reflect documented assumptions around hospitality sector expansion and controlled-environment agriculture technology cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Global Papaya Puree Market