
 US Fruit and Vegetables Market | 2026-2036
US Fruit and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
US Fruit and Vegetables Market Intelligence
The increasing reliance on venture capital and project finance for controlled environment agriculture is rewriting the competitive landscape for specialty produce. Established players like Taylor Farms leverage large-scale field operations and extensive distribution networks to maintain market leadership. Meanwhile, Driscoll's specializes in the berry category through a proprietary genetics program and a network of independent growers. Grimmway Farms dominates the carrot segment with significant in-house production of its core vegetable products.
The US fruit and vegetables sector encompasses edible plant products intended for human consumption, either fresh or processed. This includes a vast range of botanical items, from pomes and berries to leafy greens and root vegetables, managed under specific post-harvest cold chain protocols to preserve quality. Fresh vegetables constitute the largest product type by volume, although frozen fruits represent a high-growth category. Distribution is shifting as online retailers gain share from traditional supermarkets, particularly for packaged and value-added items.
The US Department of Agriculture (USDA) sets quality grades and standards for produce, which directly influence pricing and procurement contracts. Concurrently, the Food and Drug Administration (FDA) enforces food safety through the Food Safety Modernization Act (FSMA). EPA regulations on pesticide residues further dictate cultivation practices and impact market access for both domestic and imported goods. Producers must now decide whether to invest in automation and water-saving technologies or risk margin erosion from rising labor and input costs.
Market Dynamics
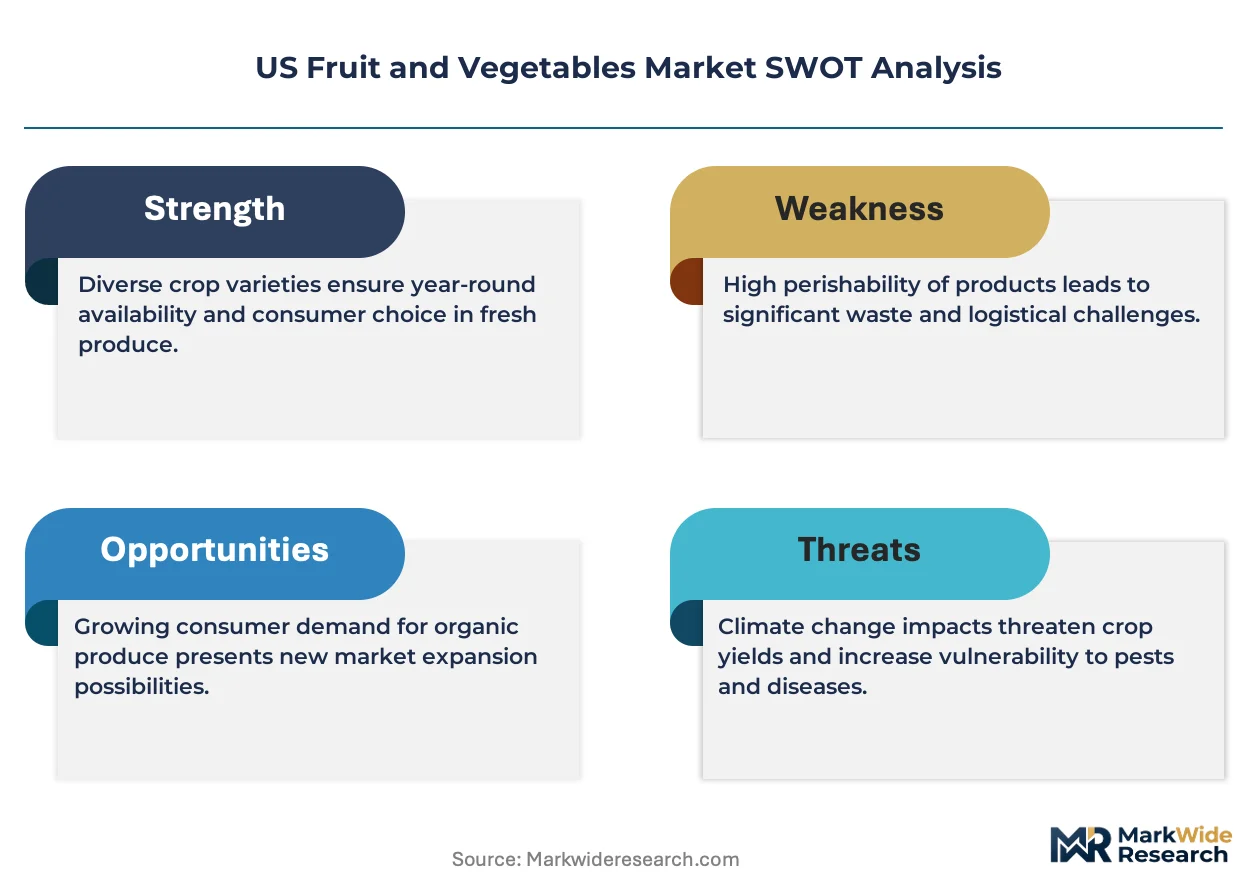
The US fruit and vegetables market is shaped by the tension between rising operational costs, particularly for labor and water, and the necessity of capital investment in automation and controlled environment agriculture to maintain competitiveness and supply consistency.
Growth Catalysts
- Health-Conscious Diets:Consumer emphasis on fresh, nutrient-dense foods continues to expand demand within the food service and retail sectors, especially for organic and minimally processed options that align with wellness trends.
- FDA FSMA Implementation:The Food Safety Modernization Act's stringent requirements for traceability and preventative controls are driving investment in digital platforms and sensor technologies to ensure supply chain transparency and compliance.
- Controlled Environment Agriculture:Advancements in hydroponics, aeroponics, and vertical farming enable year-round production of high-value crops like leafy greens and herbs closer to major urban consumption centers, reducing transportation costs.
Market Restraints
- Labor Scarcity:A persistent shortage of agricultural labor, especially for harvesting, in key production states like California and Florida increases operating costs and creates significant bottlenecks during peak seasons.
- Water Resource Constraints:Increasing competition for water and drought conditions in the Western US, governed by complex state and federal allocations, restrict acreage and raise irrigation costs for growers.
- Import Price Pressure:A steady flow of lower-cost produce from international sources, particularly Mexico for items like tomatoes and avocados, puts downward pressure on domestic pricing and margins.
Strategic Opportunities
- Value-Added Processing:Significant opportunity exists in expanding offerings of pre-cut, pre-washed, and packaged produce kits that cater to consumer demand for convenience and reduced meal preparation time.
- Direct-to-Consumer Channels:Leveraging e-commerce and subscription models allows producers of specialty, organic, or heirloom varieties to bypass traditional retail and build direct relationships with consumers.
- Upcycled Food Products:Utilizing cosmetically imperfect or surplus produce to create new products like juices, powders, and snacks offers a new revenue stream while addressing food waste concerns.
Industry Challenges
- Cold Chain Management:Maintaining an unbroken and precise temperature-controlled supply chain from farm to retailer remains a major operational challenge, with failures leading to spoilage and significant financial loss.
- Automation Capital Investment:The high upfront cost of acquiring and integrating robotic harvesting, sorting, and packing systems is a substantial barrier for many small and medium-sized farming operations.
- Pesticide Regulation Complexity:Growers must continuously adapt cultivation practices to comply with evolving EPA regulations on pesticide residues and application methods, which can impact crop yields and market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fruit and Vegetables Market |
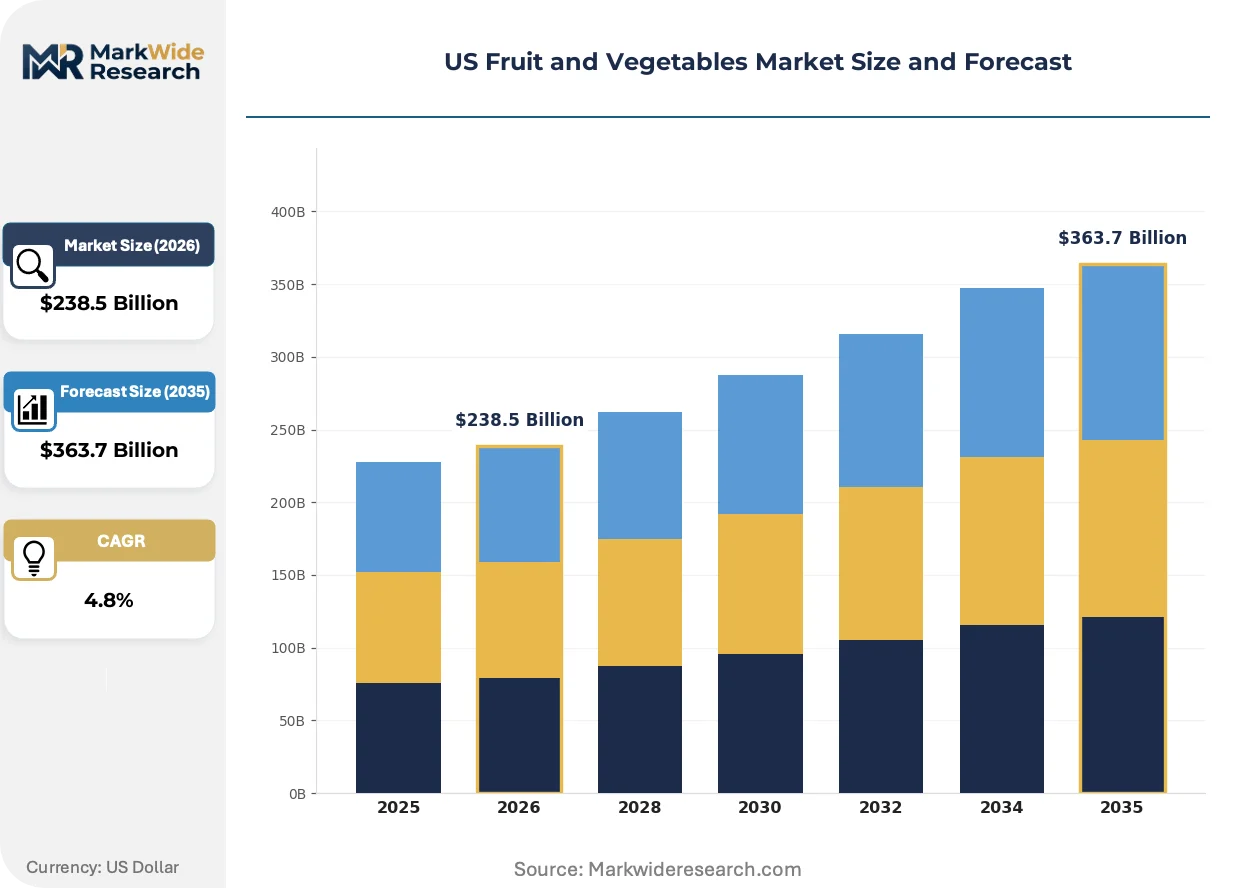
| Market Size in 2026 | $238.5 Billion |
| Market Size in 2035 | $363.7 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fruits, Fresh Vegetables, Frozen Fruits, Frozen Vegetables Distribution Channel: Supermarkets, Farmers Markets, Online Retailers, Wholesale Distributors End User: Households, Restaurants, Food Service, Retailers Packaging Type: Plastic Bags, Boxes, Bulk Containers, Reusable Crates |
| Companies Covered | Driscoll's, Taylor Farms, Dole Food Company, Bolthouse Farms, Grimmway Farms, Fresh Del Monte Produce Inc., Calavo Growers, Inc., Sunkist Growers, Incorporated, Chiquita Brands International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fruit and Vegetables Market Strategic Shifts & Innovations
Technological advancement and sustainability pressures are fundamentally altering production economics and distribution pathways. Innovations in agriculture technology and evolving consumer purchasing habits are forcing a re-evaluation of long-standing supply chain models from the farm to the end consumer.
Precision agriculture technologies, including sensor-based irrigation and drone monitoring, provide granular, real-time data on crop health and resource needs. Large-scale growers in California's Central Valley and Florida are rapidly adopting these systems to optimize water and fertilizer inputs. This technology is collapsing the information lag between field-level conditions and management decisions, enabling more efficient and responsive resource allocation.
The EPA's tightening rules on pesticide use and water quality, particularly concerning nutrient runoff into watersheds, are impacting cultivation methods. These regulations compel growers to invest in integrated pest management (IPM) strategies and advanced water recycling systems. Producers in environmentally sensitive regions are most affected, leading the shift toward more sustainable farming practices to maintain regulatory compliance.
Consumers are increasingly purchasing fresh and packaged produce through online grocery platforms, subscription boxes, and meal-kit delivery services. This trend is disrupting the traditional supermarket channel, which has historically relied on the produce department to drive store traffic. The shift is most visible in dense urban and suburban markets where last-mile refrigerated logistics infrastructure is well-established.
US Fruit and Vegetables Market Segmentation
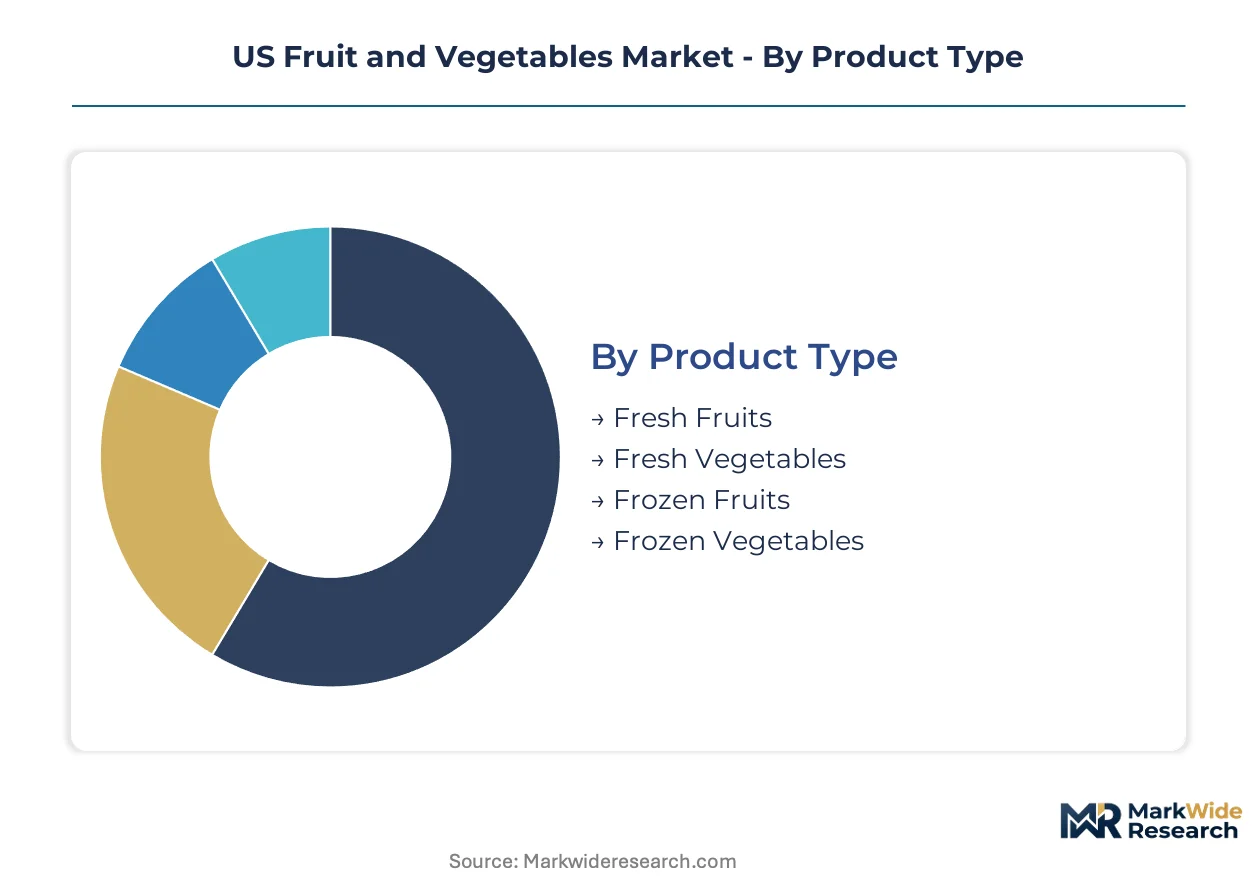
Understanding the distinct segments within the US fruit and vegetables market provides critical insight into consumer preferences, supply chain dynamics, and growth opportunities. This detailed classification helps stakeholders tailor strategies to specific product characteristics, distribution pathways, and end-user demands across the nation.
Product Type:
The intensity of post-harvest care and cold chain management varies significantly across product types, directly influencing their market reach and shelf life.
- Fresh Fruits:These are perishable botanical items, including pomes, berries, and citrus, typically consumed raw or minimally processed. Demand concentrates in retail channels and households seeking seasonal, natural produce.
- Fresh Vegetables:This category encompasses a diverse range of botanicals like leafy greens, root vegetables, and cruciferous items, characterized by high water content and short shelf life. Food service and retail sectors drive demand for nutrient-dense, unprocessed options.
- Frozen Fruits:Products are typically processed and blast-frozen immediately after harvest to preserve nutritional value and extend shelf life significantly. Demand is strong among households and food manufacturers for convenience and year-round availability in the US.
- Frozen Vegetables:These items are often blanched and flash-frozen, retaining nutrients and offering extended storage and ease of preparation. US consumers utilize these for meal preparation and as convenient side dishes.
Fresh Vegetables holds the largest share; momentum sits with Frozen Fruits.
Distribution Channel:
The diverse needs of end consumers and commercial buyers shape the strategic importance of each distribution channel.
- Supermarkets:Large-format grocery stores with extensive produce sections and established cold chain infrastructure serve a mass consumer base across the US. Consumers rely on these for one-stop shopping convenience and variety.
- Farmers Markets:These venues facilitate direct producer-to-consumer sales, emphasizing local, seasonal, and often organic produce. Consumers in many US communities seek fresh, regionally sourced items here.
- Online Retailers:E-commerce platforms leverage refrigerated last-mile delivery and subscription models to provide convenience to consumers. Urban and suburban households increasingly use these services for packaged and value-added items.
- Wholesale Distributors:These entities procure produce in bulk from growers and supply it to food service establishments, larger retailers, and institutional buyers. They form a critical link in the commercial supply chain.
Supermarkets retain significant volume, while online channels are expanding most quickly.
End User:
Consumption patterns and scale of demand define the critical role of distinct end-user segments.
- Households:Individual and family consumption for at-home meal preparation represents a primary demand driver for fresh and processed produce. Health-conscious diets influence purchasing decisions within US households.
- Restaurants:Commercial culinary establishments utilize fresh fruits and vegetables as core ingredients for prepared dishes. Demand here is often for specific varieties and consistent quality.
- Food Service:This broad segment includes institutional catering, cafeterias, and prepared meal services, with a growing emphasis on healthier menu options. The US food service sector demands consistent supply and adherence to safety standards.
- Retailers:Supermarkets, specialty grocers, and convenience stores purchase produce for resale to end consumers. They focus on product presentation, shelf life, and variety to attract shoppers.
Households represent the largest consumption base, with food service demonstrating strong growth.
Packaging Type:
The selection of packaging directly impacts logistics efficiency and product preservation across different cost tiers.
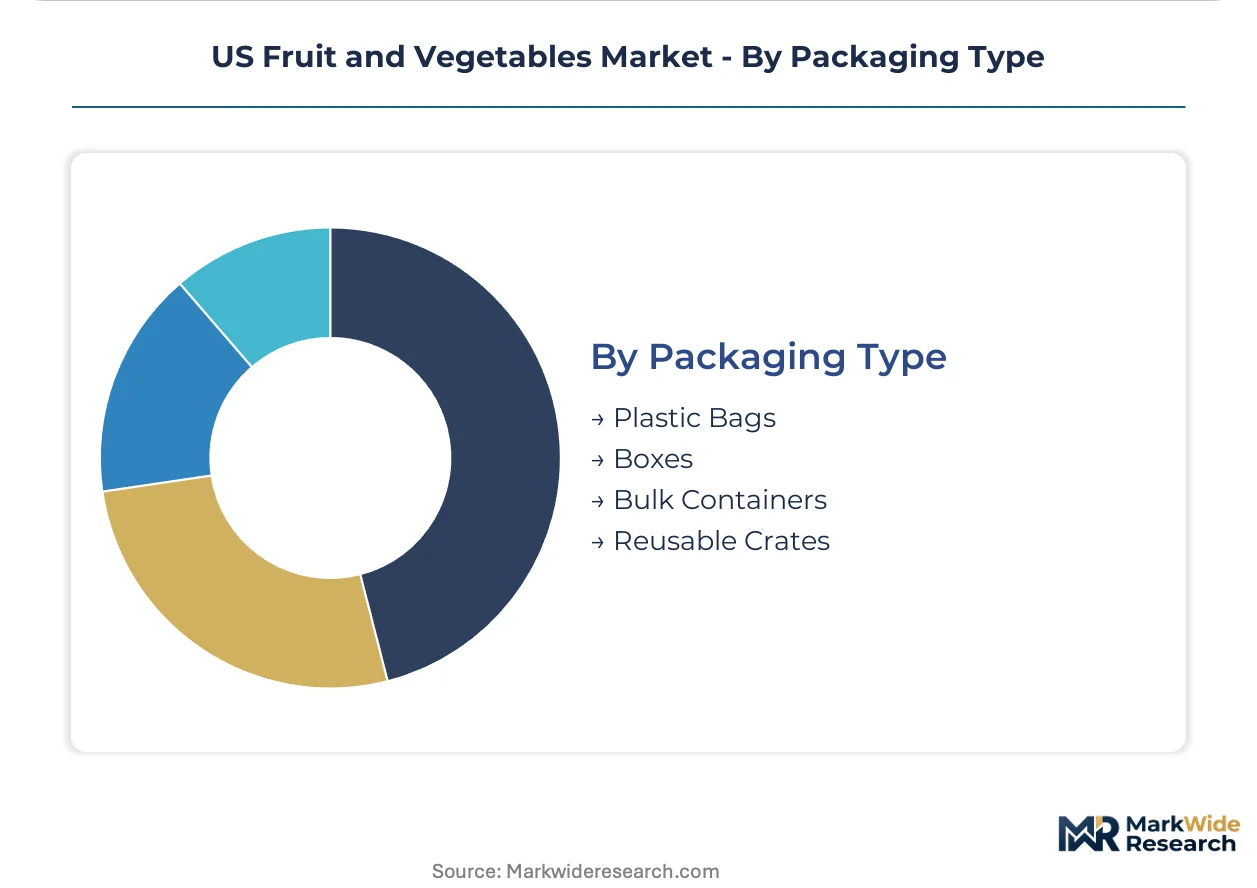
- Plastic Bags:Lightweight and transparent polyethylene or polypropylene film bags are widely used for retail consumer packaging. These offer convenience and product visibility for individual purchases in the US.
- Boxes:Corrugated cardboard or fiberboard containers provide structural integrity and protection during transport and storage. These are standard for wholesale distribution and retail display.
- Bulk Containers:Large bins, crates, or totes are designed for high-volume transport of raw, unprocessed produce from farms to processing facilities or distribution centers. These optimize large-scale logistics.
- Reusable Crates:Durable, returnable plastic containers offer an environmentally friendly option for supply chain logistics. These reduce waste and support circular economy initiatives among US growers and distributors.
Traditional packaging like boxes and plastic bags dominate, while reusable options are gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US fruit and vegetables market demonstrates a complex interplay between domestic production and substantial imports, particularly from Mexico and Canada. While domestic growers supply a significant portion of fresh produce, imports fill seasonal gaps and provide cost-effective options for consumers. This dynamic balance influences regional production strategies and market pricing across US states.
California
California's vast agricultural lands fuel high demand for specialty crops and organic produce across the nation. The state's Sustainable Groundwater Management Act (SGMA) significantly impacts water allocation for agricultural operations. In the Central Valley, growers are rapidly adopting precision irrigation systems to optimize water use and maintain yields.
Florida
Florida experiences strong demand for its citrus fruits and winter vegetables, serving both fresh markets and processing facilities. The Florida Department of Agriculture and Consumer Services enforces strict pesticide application rules to protect water quality. The Everglades Agricultural Area focuses on large-scale vegetable production, utilizing advanced drainage and irrigation systems.
Pacific Northwest
Growing consumer preference drives demand for diverse berry crops, apples, and organic produce across the Pacific Northwest. State environmental agencies in Washington and Oregon strictly regulate water rights and nutrient runoff from agricultural lands. Washington's Yakima Valley maintains its dominance in apple production, expanding its controlled atmosphere storage capabilities.
Texas
Texas maintains consistent demand for its onions, watermelons, and citrus, often supplying regional and national markets. The Texas Department of Agriculture manages agricultural marketing programs and enforces pest management protocols. The Rio Grande Valley serves as a primary hub for citrus and vegetable production, benefiting from its extended growing season.
US Fruit and Vegetables Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical inputs and specialized varieties. The US fruit and vegetables market exhibits a tiered structure, with large-scale growers and distributors coexisting with specialized producers. Strategic archetypes include diversified fresh produce giants, berry specialists, and segment-dominant vegetable growers. Companies frequently engage in geographic expansion and strategic partnerships to secure consistent supply and broaden market reach for their offerings.
Specialists in specific produce categories, like Driscoll's, exemplify a focus on proprietary genetics and independent grower networks to maintain dominance in the berry sector. Meanwhile, diversified fresh produce giants such as Taylor Farms represent the archetype of large-scale field operations and extensive distribution capabilities, crucial for broad market penetration. Grimmway Farms anchors the market's segment-dominant vegetable growers, particularly within the carrot sector through significant in-house production and brand recognition.
| Leading Market Players |
|---|
| Driscoll's |
| Taylor Farms |
| Dole Food Company |
| Bolthouse Farms |
| Grimmway Farms |
| Fresh Del Monte Produce Inc. |
| Calavo Growers, Inc. |
| Sunkist Growers, Incorporated |
| Chiquita Brands International |
| Others |
Cost & Logistics Intelligence
Mexican and Californian agricultural production concentrates the upstream supply, directly influencing pricing power and margin distribution across the US fruit and vegetables market. This concentration impacts negotiation leverage for downstream retailers.
Pricing Analysis
Industrial food service buyers anchor contract-based long-term offtake pricing for bulk produce. Price differentiation stems from quality grade, such as USDA Fancy vs. No. 1, and volume scale, favoring large purchasers. Pricing pressure stems from import competition, particularly from Mexico, which drives cost compression for commodity items. Households, especially for organic and specialty items, exhibit lower price sensitivity compared to mass-market retail.
Supply Chain Analysis
Large-scale growers in California and Florida hold significant primary production and packing capacity for fresh produce. The supply chain draws from key production regions like California, Florida, and Mexico, with raw material dependencies on water resources and agricultural labor. Single-source vulnerability during extreme weather events presents a structural risk. Distribution runs through a hub-and-spoke model, with wholesale distributors serving as critical intermediaries to retailers and food service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US fruit and vegetables market is entering a cyclical recovery, driven by a renewed consumer focus on health-conscious diets following economic shifts. This rebound supports strategic investments across the value chain.
For Market Incumbents: Harden existing distribution networks and cold chain infrastructure against disruptions from climate change and labor scarcity. Invest in automation for harvesting and packing to mitigate rising operational costs and maintain competitiveness against import price pressure. Leverage proprietary genetics programs to differentiate product offerings and secure premium pricing for specialty produce.
For New Entrants and Emerging Players: Urban and suburban food deserts represent a significant underpenetration opportunity for new entrants in the US fruit and vegetables market. Target direct-to-consumer channels and subscription models for high-value crops like leafy greens and herbs. Focus on controlled environment agriculture near consumption centers to reduce transportation costs and offer year-round fresh produce.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture capital-backed controlled environment agriculture startups seeking scale-up capital. The long-term viability of the sector remains strong over the next five to ten years, driven by health trends and technological advancements. Identify vertically integrated specialty produce growers with strong brand equity and established distribution as prime acquisition targets. The signal to watch is successful commercialization of automation solutions in harvesting.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation Integration | Mitigates labor scarcity and reduces operational costs in key production regions. |
| Controlled Environment Expansion | Ensures year-round supply of high-value crops closer to urban markets. |
| Value-Added Product Development | Captures consumer demand for convenience and expands revenue streams beyond raw produce. |
| Supply Chain Digitization | Enhances traceability and compliance with FDA FSMA requirements, reducing spoilage. |
| Proprietary Genetics Investment | Strengthens market position in specialty categories like berries and organic varieties. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings of this study. Interviews included agricultural producers, food service procurement managers, retail category buyers, and logistics specialists. Secondary data utilized USDA reports, FDA enforcement records, EPA regulatory updates, and trade association publications. This approach enabled comprehensive bottom-up and top-down market triangulation.
The quantitative model was calibrated using historical market data and projected economic indicators over the analysis window. Segmentation dimensions modeled include product type, distribution channel, end user, and packaging format. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included consumer spending patterns and agricultural yield projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large-scale retailers or food service giants would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and climate conditions. Cross-checking against USDA economic outlooks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market