
 Morocco Fruits and Vegetables Market | 2026-2036
Morocco Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Fruits and Vegetables Market Foresight
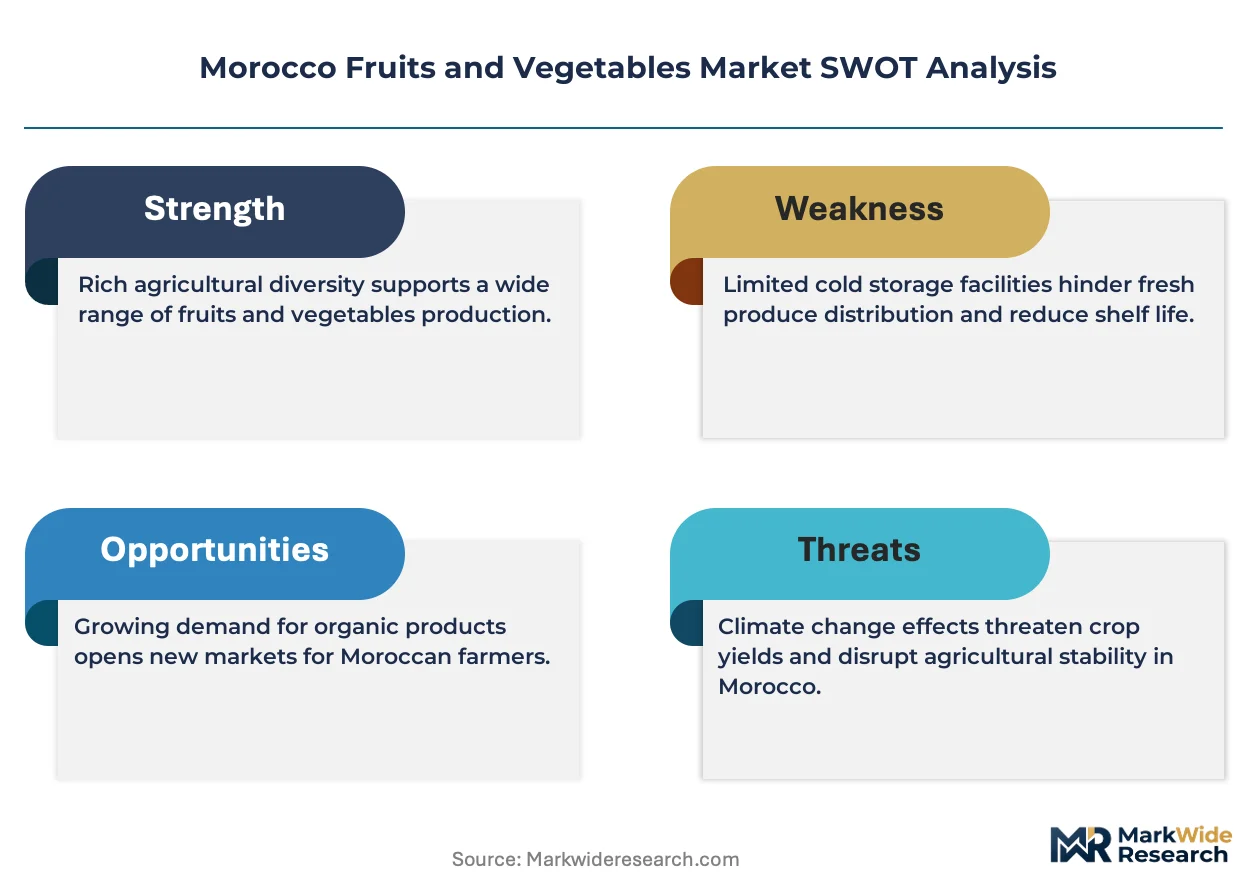
Plastic packaging is expanding as a cost-efficient alternative to traditional wooden crates in Moroccan export logistics, though biodegradable substitutes are gaining traction among EU-bound shippers. Les Domaines Brahim Zniber anchors premium citrus volumes through integrated orchard-to-port operations. Azura Group competes on berry specialization with year-round greenhouse production in Agadir. Delassus Group leverages its tomato and citrus diversification to sustain contract reliability across volatile growing seasons.
Morocco fruits and vegetables encompass fresh and minimally processed horticultural products cultivated across irrigated perimeters, greenhouse complexes, and rain-fed orchards, with harvest standards typically grading by caliber, Brix content, and visual defect thresholds for export eligibility. The primary commercial purpose centers on supplying European retail chains, domestic fresh consumption, and regional food manufacturing with consistent, traceable produce volumes. Citrus dominates export value through established varietal programs serving juice processors and fresh-fruit importers, while berries represent the fastest-growing product type as Moroccan growers install substrate-based hydroponic systems to extend counter-seasonal supply windows. Wholesale channels retain structural control over farmer-to-exporter price discovery, though direct sales to European supermarkets are capturing margin pools previously absorbed by intermediary traders.
Morocco's national food safety regulator enforces pesticide maximum residue limits that mirror EU standards, compelling growers to adopt certified integrated pest management protocols or risk export exclusion. The country's conformity assessment framework under BIS-aligned technical regulations mandates traceability documentation for all EU-bound shipments, elevating compliance costs for smallholder cooperatives. COPAG Cooperative and M'Brouka Citrus Cooperative navigate these requirements through shared packinghouse investments and group certification schemes. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their potential extension to horticultural products, as compliance scope expansion could reshape sourcing requirements for Moroccan exporters serving Northern European markets.
Market Dynamics
EU pesticide residue alignment through Morocco's national food safety authority is compressing smallholder participation while concentrating export volumes among integrated greenhouse operators with certified integrated pest management protocols.
Growth Catalysts
- Substrate-based hydroponics:Moroccan berry growers deploy soilless cultivation systems to extend counter-seasonal supply windows for European retail contracts. This technology enables year-round production cycles previously impossible in open-field conditions.
- EU deforestation-free supply chain regulations:Anticipated extension to horticultural products creates first-mover advantages for Moroccan exporters with documented traceability systems. Early compliance investments secure preferential sourcing relationships with Northern European supermarkets.
- Souss-Massa infrastructure clustering:Concentrated greenhouse development around Agadir reduces per-unit logistics costs through shared packinghouses and direct port access. Regional specialization strengthens contract reliability for juice processors and frozen food manufacturers.
Market Restraints
- Water scarcity in Drâa-Tafilalet:Irrigation-dependent citrus orchards face allocation restrictions during drought cycles. Groundwater depletion limits expansion of rain-fed cultivation into marginal lands.
- Smallholder cooperative fragmentation:Dispersed production across uncoordinated farms elevates traceability documentation costs. Group certification schemes struggle to maintain uniform integrated pest management compliance across member plots.
- Plastic packaging substitution limits:Biodegradable crate alternatives remain cost-prohibitive for price-sensitive EU-bound shippers. Wooden crate traditions persist among established export channels despite handling inefficiencies.
Strategic Opportunities
- Beni Mellal-Khénifra citrus processing:Underdeveloped juice concentrate infrastructure in central Morocco offers backward integration potential for exporters seeking captive supply. Regional water availability supports processing scale expansion.
- Organic certification premiums:EFSA-aligned organic standards command price differentiation in German and Dutch retail channels. Conversion timelines of 24-36 months create competitive moats for early adopters.
- Direct supermarket contracting:Disintermediation of wholesale channels captures margin pools previously absorbed by Agadir-based traders. Retail traceability requirements favor vertically integrated operators with in-house logistics.
Industry Challenges
- Integrated pest management technician shortage:Certified crop protection specialists are concentrated in Souss-Massa, leaving Gharb-Chrarda-Béni Hssen growers dependent on external consultants. Training program expansion lags behind regulatory compliance deadlines.
- Greenhouse capex recovery cycles:Substrate-based berry installations require 5-7 year payback periods under current EU price volatility. Financing access constrains smallholder participation in protected cultivation expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Fruits and Vegetables Market |
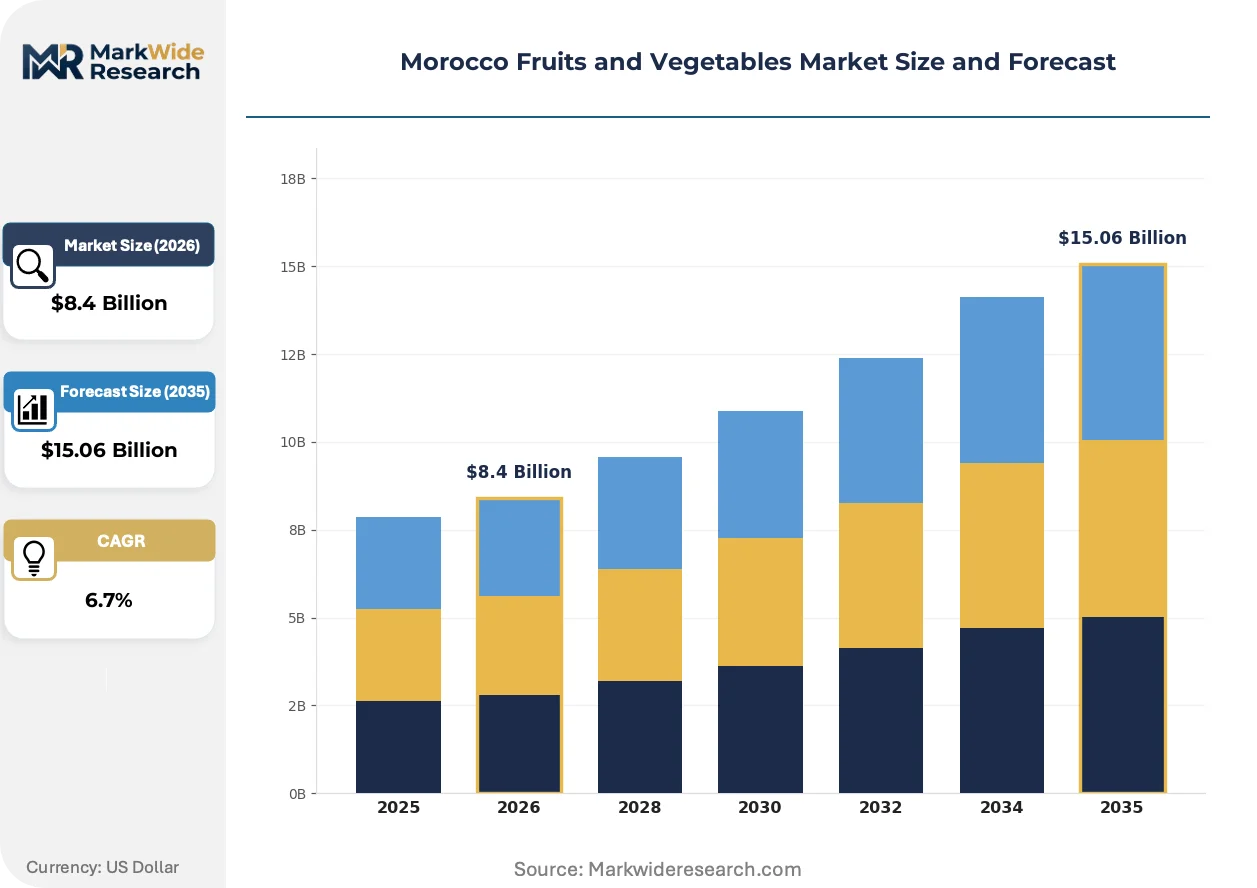
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Leafy Greens, Root Vegetables Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Food Processors, Restaurants, Households, Exporters Packaging Type: Plastic Crates, Cartons, Bags, Bulk |
| Companies Covered | Les Domaines Brahim Zniber (Diana Holding), BH Holding, Azura Group, M'Brouka Citrus Cooperative, Delight Co., Delassus Group, COPAG Cooperative, Safa-mush, Domaines Agricoles (SIGER), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Fruits and Vegetables Market Shifts & Advancements
Active reshaping in Moroccan horticulture centers on automation convergence with biocontrol protocols, regulatory anticipation of EU supply chain due diligence, and procurement compression that eliminates traditional trader intermediaries.
Sensor-driven climate control is integrating into Souss-Massa greenhouse operations to optimize water-use efficiency and Brix accumulation in berry varieties. Large-scale operators deploy these systems to meet stringent EU supermarket visual defect thresholds. The technology is integrating orchard management with real-time harvest timing decisions that reduce post-harvest losses.
REACH-aligned chemical authorization reviews through ECHA are restricting active ingredient availability for Moroccan exporters serving Northern European markets. Growers substitute biological control agents and pheromone disruption systems to maintain residue compliance. Berry and tomato segments absorb the highest compliance costs due to intensive pesticide application histories.
Retail procurement consolidation across German and Dutch supermarket chains is compressing supplier rosters to traceability-verified direct sources. Moroccan exporters with in-house packing and port logistics displace traditional Agadir trader networks. This concentration is most visible in citrus and berry categories where single-source contracts now span multi-year volumes.
Morocco Fruits and Vegetables Market Segmentation
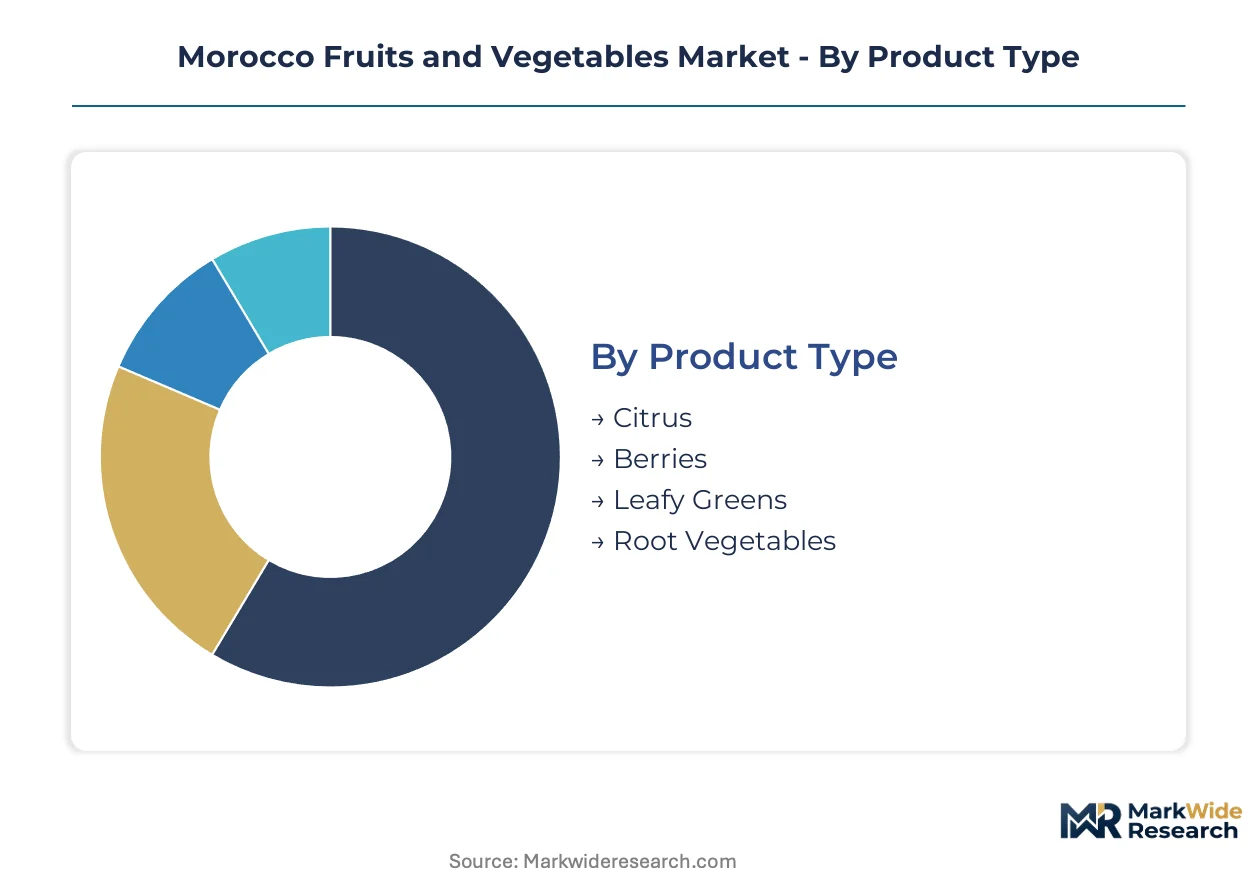
Segmentation in Moroccan horticulture reveals where capital deployment concentrates and which channels capture margin pools. Each dimension exposes structural advantages for integrated operators versus fragmented competitors.
Product Type:
Capital intensity varies sharply across cultivation systems, with protected infrastructure requirements determining barrier heights for new entrants.
- Citrus:Perennial orchard systems demand 8-12 year establishment timelines before commercial yields. Souss-Massa grapefruit and Clementine programs serve established EU juice processor contracts with volume reliability that open-field alternatives cannot match.
- Berries:Substrate-based hydroponic installations require $3-5 million per hectare for climate-controlled greenhouses with automated irrigation. Agadir-based operators extend counter-seasonal windows for Northern European retail chains through these capital-intensive systems.
- Leafy Greens:Shorter rotation cycles and lower infrastructure thresholds enable smallholder participation in regional supply.
- Root Vegetables:Rain-fed cultivation in Gharb-Chrarda-Béni Hssen keeps entry barriers minimal for domestic market suppliers.
Most installed capacity flows through Citrus. Expansion is steepest in Berries.
Distribution Channel:
Channel selection determines traceability burden and margin retention, with direct routes rewarding compliance investments that intermediaries cannot replicate.
- Wholesale:Traditional Agadir trader networks retain price discovery control for uncoordinated smallholder volumes. EFSA-aligned residue documentation requirements are compressing participation as EU-bound shipments demand batch-level traceability.
- Direct Sales:Vertically integrated operators with in-house packinghouses and port logistics capture margin pools previously absorbed by intermediary layers. German and Dutch supermarket consolidation favors these arrangements for multi-year citrus and berry contracts.
- Retail:Domestic supermarket chains source through centralized procurement with standardized caliber requirements.
- Online:Emerging channel for urban household delivery with limited penetration in fresh produce categories.
Volume concentrates in Wholesale. Value capture is shifting fastest toward Direct Sales.
End User:
Customer type dictates specification stringency, with export-facing segments imposing certification and documentation burdens that domestic channels tolerate.
- Exporters:EU-bound shipments require BIS-aligned conformity assessment with full traceability documentation. Les Domaines Brahim Zniber and Azura Group maintain dedicated compliance teams for REACH-aligned chemical authorization reviews through ECHA.
- Food Processors:Juice concentrate and frozen lines demand consistent Brix specifications and defect thresholds that integrated orchard-to-port operations deliver. Beni Mellal-Khénifra processing infrastructure remains underdeveloped relative to raw material availability.
- Restaurants:Domestic hospitality channels prioritize visual presentation and shelf stability over certification documentation.
- Households:Price-sensitive fresh consumption through souk networks with minimal quality standardization.
Contract reliability matters most to Exporters. Processing demand is climbing fastest in Food Processors.
Packaging Type:
Material selection reflects cost-positioning against sustainability pressures, with EU-bound channels facing earlier substitution deadlines than domestic routes.
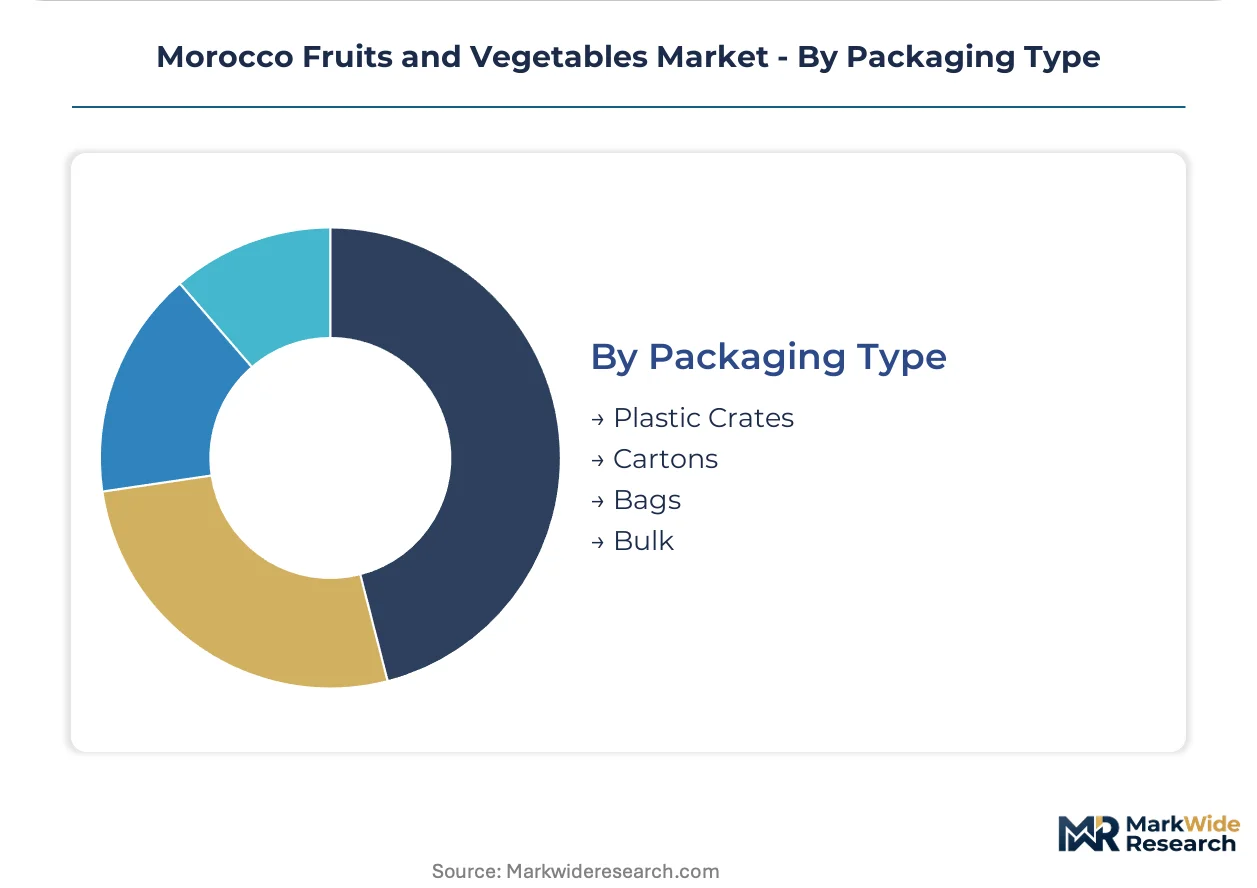
- Plastic Crates:Polypropylene injection-molded systems dominate export logistics for handling efficiency and stackability. Biodegradable alternatives remain cost-prohibitive for price-sensitive shippers despite retailer sustainability commitments.
- Cartons:Corrugated fiberboard serves premium citrus and berry lines with printed branding for supermarket shelf presentation. COPAG Cooperative investments in automated carton erecting equipment reduce per-unit labor costs.
- Bags:Polyethylene mesh dominates root vegetable and onion categories for ventilation and weight efficiency.
- Bulk:Unpackaged volumes flow to juice processors and canneries with immediate processing timelines.
Plastic Crates handle the greatest tonnage. Carton adoption is expanding most quickly in premium export tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Souss-Massa anchors Morocco's horticultural output through concentrated greenhouse infrastructure and direct Agadir port access serving European retail contracts. Regional specialization varies sharply across irrigation availability and EU compliance proximity.
Souss-Massa
Agadir-based greenhouse clusters dominate berry and tomato exports through substrate-based hydroponic systems. The region's national food safety authority enforcement aligns pesticide residue limits with EFSA standards. Packinghouse concentration around Inezgane-Aït Melloul reduces per-unit logistics costs for EU-bound shipments.
Gharb-Chrarda-Béni Hssen
Rain-fed citrus orchards and cereal rotations serve domestic processors with lower capital thresholds than protected cultivation. Groundwater access restrictions under national irrigation allocation frameworks limit expansion. Kenitra logistics corridors channel root vegetable volumes toward Casablanca export terminals.
Béni Mellal-Khénifra
Central plateau citrus groves supply underdeveloped juice concentrate infrastructure with raw material availability exceeding processing capacity. Ouled Ayad cooperative networks aggregate smallholder volumes for bulk shipment. Regional water reservoir access supports potential backward integration by exporters seeking captive supply.
Drâa-Tafilalet
Date palm oases and marginal citrus cultivation face severe groundwater depletion under climate stress. Errachidia agricultural extension services promote deficit irrigation techniques. Smallholder fragmentation persists without greenhouse clustering or shared packing infrastructure.
Marrakech-Safi
High-value table grape and citrus operations serve Gulf export channels through Marrakech-Menara air freight connectivity. El Badi cooperative investments target organic certification for German retail premiums. Urban demand from Marrakech hospitality sectors absorbs premium-grade domestic supply.
Morocco Fruits and Vegetables Market Competitive Landscape
Global majors compete with regional champions across integrated orchard-to-port operations versus cooperative-based aggregation models. The vendor base arranges into tiered structures where capital-intensive greenhouse operators capture direct supermarket contracts while smallholder cooperatives serve wholesale channels. Three archetypes dominate: vertically integrated agro-industrial holdings, specialized berry or citrus cooperatives, and diversified food conglomerates with horticultural divisions. Competitive moves center on backward integration into processing infrastructure and multi-year direct contracting with Northern European retail consolidators.
Among integrated holding companies, Les Domaines Brahim Zniber exemplifies premium citrus specialization through captive orchard management and port logistics control. Azura Group occupies a position within protected-cultivation berry segments through year-round greenhouse operations. The cooperative tier includes COPAG Cooperative and M'Brouka Citrus Cooperative, representing smallholder aggregation models navigating group certification requirements for EU market access.
| Leading Market Players |
|---|
| Les Domaines Brahim Zniber (Diana Holding) |
| BH Holding |
| Azura Group |
| M'Brouka Citrus Cooperative |
| Delight Co. |
| Delassus Group |
| COPAG Cooperative |
| Safa-mush |
| Domaines Agricoles (SIGER) |
| Others |
Supply & Pricing Matrix
Agadir port freight benchmarks cascade through Moroccan horticultural supply chains, compressing margins at smallholder cooperatives while concentrating pricing power among integrated greenhouse operators with direct supermarket contracts. EU-bound berry and citrus shipments stratify across premium organic tiers, certified conventional grades, and bulk processing lines based on traceability documentation completeness and residue compliance proximity.
Pricing Analysis
Input-cost pass-through from polypropylene packaging and certified biocontrol agents flows unevenly across Moroccan export tiers. Three-tier pricing structure separates EFSA-aligned organic premiums for German retail from standard integrated pest management grades and economy bulk lines for juice processors. Pricing pressure stems from REACH-aligned chemical authorization reviews restricting active ingredient availability, with berry and tomato segments absorbing the highest compliance burden. Smallholder cooperatives exhibit greatest price sensitivity due to fragmented certification costs, while vertically integrated operators with captive packinghouses retain margin flexibility.
Supply Chain Analysis
Agadir port congestion surcharges and refrigerated container availability swings drive logistics cost volatility for EU-bound Moroccan shipments. Production concentrates in Souss-Massa greenhouse clusters, Béni Mellal-Khénifra citrus groves, and Gharb-Chrarda-Béni Hssen rain-fed operations. Raw material dependencies include substrate materials for hydroponic systems, polypropylene packaging resins, and biological control agent formulations. Single-source vulnerability runs through concentrated Agadir port access for perishable exports. Distribution runs through vertically integrated operator direct contracts, wholesale trader networks, and emerging cooperative aggregation models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's fruits and vegetables market compounds steadily through persistent European retail demand for counter-seasonal supply and regulatory alignment that rewards early compliance investments.
For Market Incumbents: Extend substrate-based hydroponic capacity in Souss-Massa to capture multi-year direct supermarket contracts before EU deforestation-free regulations extend to horticultural products. Defend against emerging integrated pest management technician shortages by anchoring certified crop protection specialists through captive training programs. Prioritize backward integration into Beni Mellal-Khénifra juice concentrate infrastructure to secure captive supply for processing demand growth. For New Entrants and Emerging Players: Direct-to-retail digital procurement platforms offer white-space entry around traceability documentation services for fragmented smallholder cooperatives struggling with EFSA-aligned batch-level compliance. Target organic certification conversion in Béni Mellal-Khénifra and Marrakech-Safi regions where 24-36 month timelines create competitive moats against late adopters. Deploy group certification scheme management as a service layer to capture margin pools from cooperative aggregation without greenhouse capital deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with protected-cultivation specialists with established EU retail relationships and residue compliance infrastructure already operational. Long-term viability centers on water-secure greenhouse assets with direct port logistics control across multi-year contract horizons. Watch EU deforestation-free supply chain regulation extension timing as the inflection signal for compliance-premium capture versus exclusion risk.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate-Based Hydroponic Expansion | Agadir-based operators extend counter-seasonal windows through climate-controlled greenhouse investments serving German retail contracts. |
| Organic Certification Conversion | Early adopters in Béni Mellal-Khénifra secure EFSA-aligned premiums before 24-36 month conversion timelines saturate competitive positioning. |
| Direct Supermarket Contracting | Vertically integrated operators displace Agadir trader networks through in-house packinghouse and port logistics control. |
| Backward Integration into Processing | Exporters capture captive supply value from underdeveloped Beni Mellal-Khénifra juice concentrate infrastructure. |
| Group Certification Scheme Investment | Cooperative aggregation models navigate BIS-aligned traceability requirements through shared packinghouse infrastructure. |
Research Methodology
Direct dialogue with greenhouse operations managers, cooperative board representatives, EU supermarket procurement leads, and Morocco's national food safety authority officials grounded qualitative findings in operational reality. Secondary validation drew from EFSA pesticide residue databases, ECHA REACH authorization registers, EU trade flow statistics, and Moroccan agricultural extension service reports. Bottom-up orchard and greenhouse capacity estimates triangulated against top-down export value flows through Agadir port customs records.
Bottom-up modeling of installed greenhouse hectarage and orchard maturity profiles fed into volume projections across the analysis window. Segmentation dimensions included cultivation system type, distribution channel structure, end-user specification tier, and regional production cluster. CAGRs derived from historical export value trajectories adjusted for infrastructure buildout timelines and regulatory compliance phase-ins. Forecast inputs incorporated irrigation allocation frameworks, EU deforestation-free regulation anticipation effects, and biocontrol substitution cost curves.
The model assumes a particular technology adoption path for substrate-based hydroponic systems; alternative pathways for open-field deficit irrigation would alter the outlook for Drâa-Tafilalet and Gharb-Chrarda-Béni Hssen expansion potential. Forecasts reflect assumptions around EU regulatory timeline adherence and water reservoir availability in central plateau regions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
North America Organic Fruits Market