
 Jackfruit Market | 2026-2036
Jackfruit Market Size, Share, and Industry Trends Forecast 2026-2036
Jackfruit Market Analysis
Contract farming arrangements with built-in processing offtake is narrowing the capital barrier for small-scale processors entering the jackfruit value chain. The Jackfruit Company leverages direct farmer partnerships to secure raw material consistency across seasons. Artocarpus Foods Pvt. Ltd. anchors its position through specialized dried and canned product lines targeting export markets. Anna Food Product competes on regional brand recognition in South Indian retail channels.
Jackfruit comprises the compound fruit of Artocarpus heterophyllus, with mature specimens reaching 15-25 kg and delivering 2.5-3.0 g protein per 100 g alongside substantial dietary fiber; processors exploit its fibrous texture as a meat analog in vegan and vegetarian formulations. Fresh jackfruit dominates volume trade but carries perishability constraints that compress margins, while dried jackfruit commands premium positioning in health stores and export markets due to extended shelf stability. Canned jackfruit occupies the middle tier, serving food service and manufacturers seeking standardized inputs for plant-based product development.
FDA food safety standards govern U.S. import pathways for processed jackfruit, while India's FSSAI mandates labeling and hygiene protocols for domestic packaged products. The EU Green Deal's sustainable sourcing requirements are reshaping export compliance costs for Indian and Southeast Asian suppliers. Stakeholders must monitor evolving carbon-footprint disclosure rules under CSRD and emerging allergen-labeling harmonization across major import jurisdictions.
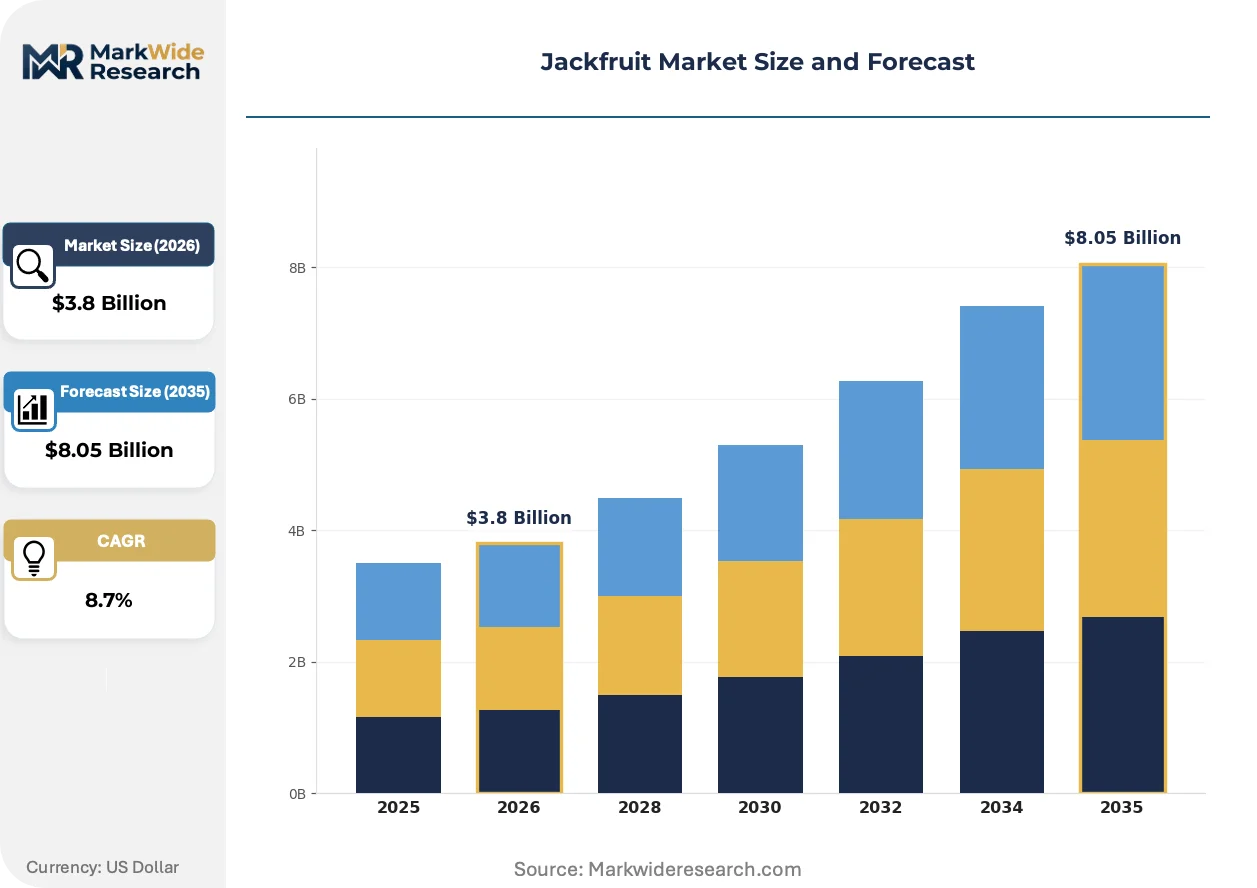
Market Dynamics
India's PLI scheme for food processing infrastructure is concentrating capital around jackfruit value chains, while the EU Green Deal's carbon-footprint disclosure mandates are forcing export-oriented processors to reconfigure sourcing and certification protocols.
Growth Catalysts
- EU Green Deal sustainable sourcing requirements:Carbon-footprint disclosure rules under CSRD are creating compliance-driven demand for traceable jackfruit supply chains, favoring processors with integrated farm-to-facility documentation systems.
- Plant-based meat analogs:Food manufacturers in North America and Europe are substituting jackfruit for soy and wheat gluten in vegan product lines, exploiting its neutral flavor profile and fibrous texture.
- Kerala-Tamil Nadu cultivation clusters:Concentrated production zones with established processing infrastructure reduce per-unit logistics costs and enable year-round raw material availability for exporters.
Market Restraints
- Fresh fruit perishability:Unprocessed jackfruit degrades within 3-5 days post-harvest, compressing margins for traders lacking cold-chain infrastructure or immediate processing offtake.
- Seasonal supply volatility:South India's monsoon-dependent harvest cycles create raw material gluts and shortages that destabilize pricing for dried and canned product lines.
- Substitute protein fibers:Cultivated mycelium and extruded pea-soy blends from precision fermentation facilities are capturing shelf space in vegan retail channels.
Strategic Opportunities
- India's PLI scheme for food processing:Capital subsidies for cold storage and dehydration equipment lower entry barriers for regional processors seeking export certification.
- Direct-to-foodservice distribution:Bypassing traditional commodity traders, processors are contracting with restaurant chains and meal-kit providers for standardized canned and IQF jackfruit.
- FDA import pathway standardization:Harmonized food safety documentation requirements are enabling Indian and Southeast Asian suppliers to consolidate multiple regional certifications into single U.S. market entry protocols.
Industry Challenges
- HACCP and FSSC 22000 certification timelines:Small-scale processors face 12-18 month compliance periods to meet EU and North American retail buyer requirements, delaying revenue from export contracts.
- Post-harvest handling skill gaps:Proper latex management, ripeness grading, and enzymatic browning prevention require trained labor that remains scarce outside established Kerala processing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jackfruit Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Jackfruit, Dried Jackfruit, Canned Jackfruit, Jackfruit Chips Application: Food Processing, Snacks, Beverages, Confectionery End User: Retailers, Food Service, Manufacturers, Health Stores Packaging Type: Bags, Boxes, Cans, Pouches |
| Companies Covered | Anna Food Product, Jackfruit365, The Jackfruit Company, Frubites, Natureloc, Artocarpus Foods Pvt. Ltd., Island Valley Delights, Cabefruit Produce LLC, Mother Dairy Fruit Vegetable Pvt. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jackfruit Market Emerging Trajectories
Digital traceability platforms and precision dehydration technologies are compressing quality variance in export supply chains, while regulatory disclosure mandates are reshaping competitive positioning around carbon accounting transparency.
Blockchain-enabled farm-to-retail tracking is digitizing provenance documentation for EU and North American buyers. Large-format retailers and foodservice distributors are mandating lot-level traceability to satisfy CSRD supply-chain disclosure requirements. This technology is digitizing compliance workflows that previously required manual audit trails, reducing verification costs for processors serving multiple export jurisdictions.
REACH and F-Gas Regulation amendments are tightening residual solvent limits for dried fruit processing equipment. European importers are rejecting batches exceeding updated ethylene oxide and sulfite thresholds, forcing Asian suppliers to retrofit dehydration lines with closed-loop systems. Canned jackfruit processors in India and Thailand are accelerating migration to steam-based sterilization to preempt regulatory exclusion from premium retail channels.
Buyers are consolidating procurement around processors offering integrated farm-certification and carbon-footprint data. Food manufacturers and retail chains are displacing spot-market purchasing with multi-year supply agreements that bundle traceability guarantees and volume commitments. This pattern is most pronounced in German and Dutch markets, where supermarket sustainability scorecards directly influence supplier selection for private-label plant-based product lines.
Jackfruit Market Segmentation
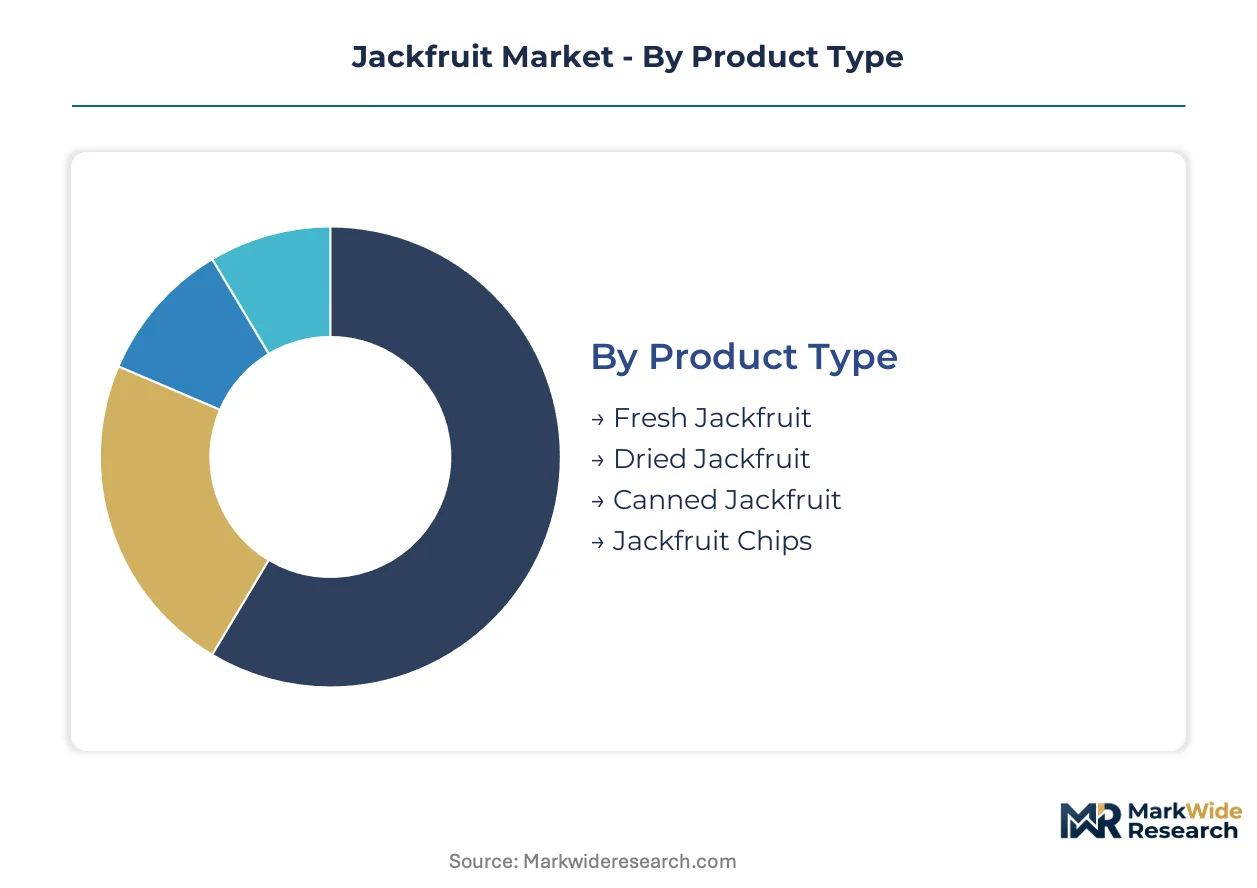
Jackfruit processors navigate divergent margin profiles across product formats, with perishability cycles and export certification requirements fragmenting competitive specialization. Segmentation reveals how capital intensity and shelf-stability trade-offs concentrate supply chain investments.
Product Type:
Inventory velocity varies dramatically across formats, with fresh product clearing in days while dried and canned variants sit for months.
- Fresh Jackfruit:Whole and segment-cut fruit weighing 15-25 kg per specimen delivers 2.5-3.0 g protein per 100 g alongside substantial dietary fiber. South Indian wet markets and urban retail chains in Kerala and Tamil Nadu absorb the bulk of volume, though 3-5 day spoilage windows compress margins for traders lacking immediate processing offtake or cold-chain infrastructure.
- Dried Jackfruit:Dehydrated slices and chunks achieve 12-18 month shelf stability through precision moisture reduction, commanding premium positioning in German and Dutch health stores. EU Green Deal carbon-footprint disclosure mandates favor processors with integrated farm-to-facility documentation systems, displacing spot-market suppliers lacking traceability infrastructure.
- Canned Jackfruit:Brined or syrup-packed segments in standardized containers serve North American and European food manufacturers seeking meat analog inputs. Steam-based sterilization retrofits are accelerating among Indian and Thai processors to preempt REACH and F-Gas Regulation residual solvent exclusions.
- Jackfruit Chips:Vacuum-fried or kettle-cooked snack formats target Southeast Asian retail and duty-free channels. FSSAI labeling compliance and India's PLI scheme capital subsidies are lowering equipment barriers for regional processors entering export certification pipelines.
Fresh jackfruit anchors the volume base while dried jackfruit gains share at the steepest rate.
Application:
End-use economics stratify sharply, with ingredient supply to food manufacturers outpacing direct-to-consumer velocity.
- Food Processing:Raw and semi-processed jackfruit supplies plant-based meat analog production lines across North America and Europe. FDA food safety standardization enables Indian and Southeast Asian suppliers to consolidate multiple regional certifications into single U.S. market entry protocols.
- Snacks:Chips, puffs, and extruded formats target impulse purchase occasions in Indian metropolitan retail and Middle Eastern convenience channels. Health positioning around fiber and natural sweetness competes with established tropical fruit snack incumbents.
- Beverages:Nectar, juice, and functional drink formulations exploit jackfruit's neutral flavor profile for blending applications. Thai and Vietnamese processors dominate this niche with established tropical fruit beverage supply chains.
- Confectionery:Jams, preserves, and candied segments serve premium gifting markets in East Asia and Gulf Cooperation Council countries. Extended processing cycles and sugar content regulation compliance elevate entry barriers relative to other applications.
Food processing commands the dominant revenue share while snacks expand most quickly among consumer-facing categories.
End User:
Procurement sophistication diverges, with manufacturers and food service operators demanding specification-grade consistency that retailers rarely require.
- Retailers:Supermarket chains and independent grocers stock fresh, dried, and canned formats for direct consumer purchase. Kerala and Tamil Nadu cultivation clusters with established processing infrastructure reduce per-unit logistics costs for domestic Indian distribution.
- Food Service:Restaurant chains, cloud kitchens, and meal-kit providers contract for IQF and standardized canned inputs. Direct-to-foodservice distribution bypasses traditional commodity traders, compressing margin extraction layers.
- Manufacturers:Plant-based meat companies and packaged food producers specify fiber content, ripeness grade, and microbial load tolerances. HACCP and FSSC 22000 certification timelines of 12-18 months delay revenue for small-scale processors seeking export contracts.
- Health Stores:Organic and specialty retailers in Germany, Netherlands, and North American coastal metros prioritize carbon-accounting transparency and blockchain-enabled provenance. CSRD supply-chain disclosure requirements are consolidating procurement around processors offering integrated farm-certification data.
Manufacturers drive specification innovation while health stores represent the fastest-climbing customer tier.
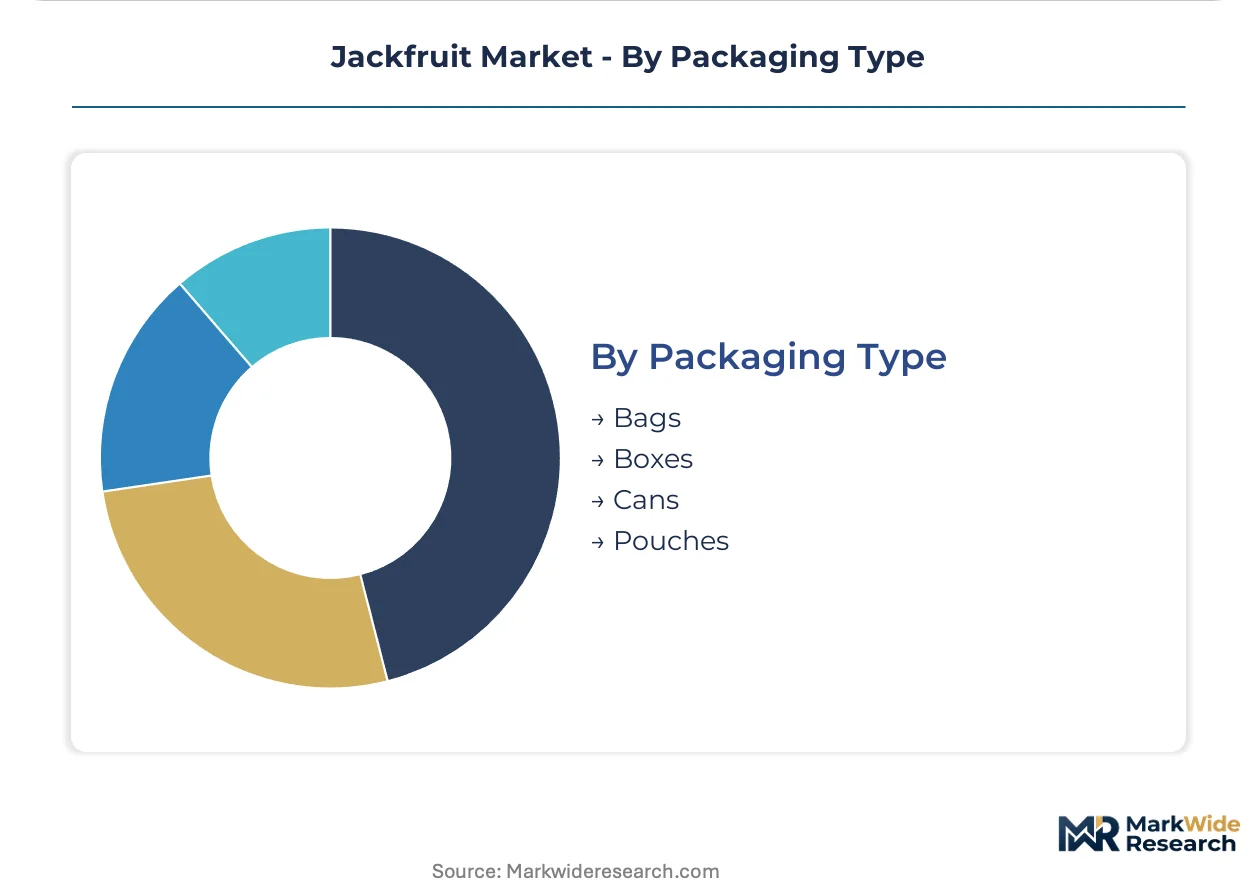
Packaging Type:
Unit economics and regulatory compliance costs concentrate investment around format-specific equipment lines.
- Bags:Flexible pouches and stand-up bags dominate dried jackfruit and chip formats for retail shelf presence. REACH amendments tightening residual solvent limits are forcing Asian suppliers to retrofit dehydration and packaging lines with closed-loop systems.
- Boxes:Corrugated and rigid packaging serves bulk food service shipments and premium gift confectionery. German and Dutch supermarket sustainability scorecards directly influence supplier selection for private-label plant-based product lines.
- Cans:Metal containers remain the standard for brined jackfruit targeting food manufacturers and institutional food service. Steam-based sterilization migration is preempting regulatory exclusion from premium European retail channels.
- Pouches:Retort and aseptic flexible formats are gaining traction for single-serve beverage and ready-to-eat segments. India's PLI scheme capital subsidies for cold storage and dehydration equipment lower entry barriers for regional processors pursuing pouch-format export certification.
Cans anchor existing infrastructure investment while pouches demonstrate the steepest technology adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for food processing infrastructure is concentrating capital around jackfruit value chains, while the EU Green Deal's carbon-footprint disclosure mandates are forcing export-oriented processors to reconfigure sourcing and certification protocols.
India
Kerala and Tamil Nadu cultivation clusters anchor domestic supply, with contract farming arrangements narrowing capital barriers for small-scale processors. The FSSAI mandates labeling and hygiene protocols for domestic packaged products. Processing infrastructure concentrates in Kochi, Thiruvananthapuram, and Coimbatore, where established dehydration and canning facilities enable year-round raw material availability for exporters.
United States
Plant-based meat manufacturers in North America are substituting jackfruit for soy and wheat gluten in vegan product lines. The FDA food safety standards govern import pathways for processed jackfruit, requiring HACCP documentation. Distribution runs through specialty food distributors in California and New York Metro, serving restaurant chains and meal-kit providers seeking standardized canned and IQF inputs.
Germany
Organic and specialty retailers in German metropolitan areas prioritize carbon-accounting transparency and blockchain-enabled provenance. The EU Green Deal's CSRD supply-chain disclosure requirements are consolidating procurement around processors offering integrated farm-certification data. Supermarket sustainability scorecards in Berlin, Munich, and Hamburg directly influence supplier selection for private-label plant-based product lines.
Netherlands
Dutch food manufacturers specify fiber content, ripeness grade, and microbial load tolerances for jackfruit meat analog inputs. REACH and F-Gas Regulation amendments are tightening residual solvent limits for dried fruit processing equipment. Rotterdam and Amsterdam serve as consolidation points for Asian suppliers retrofitting dehydration lines with closed-loop systems to preempt regulatory exclusion.
Thailand
Thai processors dominate jackfruit beverage formulations with established tropical fruit supply chains. The country's national food safety regulator enforces export certification protocols aligned with EU and North American retail buyer requirements. Processing activity clusters in Bangkok and surrounding provinces, where steam-based sterilization migration is accelerating to maintain premium European retail channel access.
Jackfruit Market Vendor Landscape
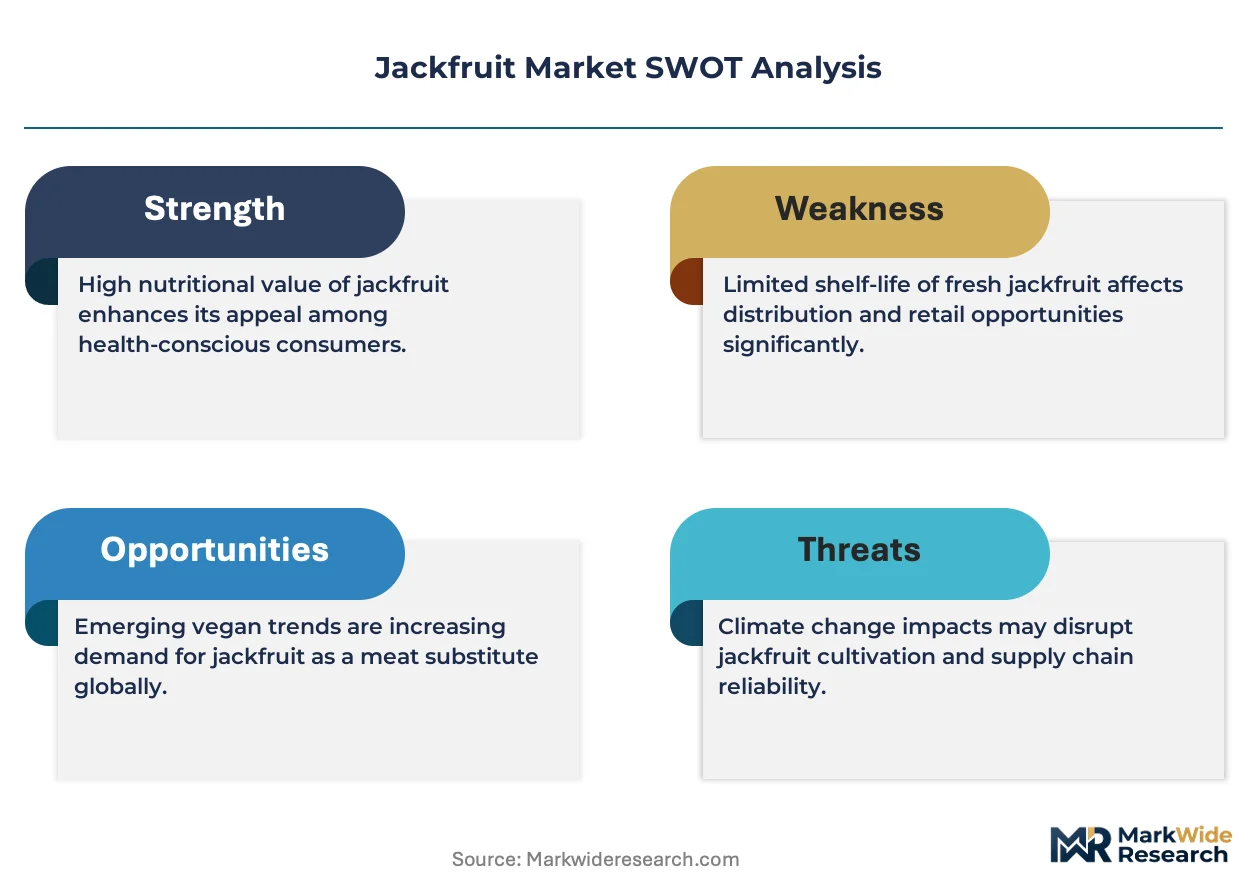
On the supply side, the industry is fragmented across regional specialists and emerging integrated processors, with concentration varying by product format and export certification level. Tiered competitive positioning separates established exporters with multi-jurisdiction compliance from domestic-focused operators lacking cold-chain infrastructure. Three archetypes dominate: direct farmer partnership models, specialized dried and canned product exporters, and regional retail brand builders. Capacity expansion and certification-driven M&A represent the dominant competitive moves, as processors seek to compress 12-18 month HACCP and FSSC 22000 compliance timelines.
Among India-based specialists, The Jackfruit Company, Artocarpus Foods Pvt. Ltd., and Anna Food Product exemplify distinct strategic archetypes. The Jackfruit Company occupies a position within the direct farmer partnership tier, securing raw material consistency across seasons through captive supply arrangements. Artocarpus Foods Pvt. Ltd. anchors the export-specialist segment, targeting premium positioning in health stores and international markets. Anna Food Product represents the regional brand recognition model, competing through established retail channel presence in South Indian domestic markets. These three entities collectively illustrate how geographic focus, certification depth, and farmer integration levels stratify competitive positioning within the broader industry structure.
| Leading Market Players |
|---|
| Anna Food Product |
| Jackfruit365 |
| The Jackfruit Company |
| Frubites |
| Natureloc |
| Artocarpus Foods Pvt. Ltd. |
| Island Valley Delights |
| Cabefruit Produce LLC |
| Mother Dairy Fruit Vegetable Pvt. Ltd |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-footprint disclosure mandates compress both pricing tier spreads and supply chain architecture, forcing processors with integrated farm-certification systems to capture premium positioning while spot-market suppliers face margin erosion from compliance exclusion.
Pricing Analysis
Certification level (HACCP/FSSC 22000/FDA-grade) creates the primary spread between export-ready processors and domestic-only operators. Contract-based long-term offtake agreements dominate food manufacturer procurement, with volume scale and carbon-accounting transparency as secondary differentiation drivers. Cost compression in fresh fruit trading intensifies because perishability constraints compress margins for cold-chain-deficient traders. Food service operators exhibit highest price sensitivity due to standardized input specifications, while health stores accept substantial premiums for blockchain-enabled provenance documentation.
Supply Chain Analysis
Raw jackfruit feedstock draws from concentrated cultivation belts in India, Thailand, and Vietnam, with Kerala-Tamil Nadu clusters anchoring premium export supply. Processing inputs hinge on dehydration equipment, sterilization systems, and cold storage infrastructure. Single-source vulnerability runs through monsoon-dependent harvest cycles that destabilize year-round raw material availability. Distribution runs through specialty food distributors in California and New York Metro for North American penetration, with Rotterdam and Amsterdam serving European consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates entry niches for specialists capable of bridging farm-level traceability with food manufacturer specification requirements.
For Market Incumbents: Entrench market position through backward integration into Kerala-Tamil Nadu contract farming networks and accelerated HACCP/FSSC 22000 certification pipelines. Cultivated mycelium substitutes threaten vegan channel shelf space; preemptive carbon-accounting transparency investments defend premium positioning against precision fermentation entrants. For New Entrants and Emerging Players: German and Dutch health store underpenetration offers white-space expansion for processors with integrated farm-to-facility documentation. Direct-to-foodservice distribution bypasses entrenched commodity trader margins. Target IQF and standardized canned format supply agreements with meal-kit providers as the most penetrable entry vector. For Investors and Strategic Acquirers: Regional processors with dormant export certification pipelines represent the most actionable acquisition archetype. Long-term viability hinges on CSRD compliance infrastructure and multi-jurisdiction certification depth. Watch for EU Green Deal enforcement acceleration as inflection signal for traceability-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Farm-Level Certification Integration | CSRD disclosure requirements favor processors with captive farm-audit documentation systems. |
| Steam-Based Sterilization Retrofit | REACH amendments are excluding ethylene oxide-dependent processors from premium European retail. |
| Direct-to-Foodservice Distribution | Bypassing commodity traders compresses margin extraction layers for IQF and canned formats. |
| Blockchain Traceability Deployment | German supermarket sustainability scorecards now mandate lot-level provenance verification. |
| Cold Storage Capacity Expansion | India's PLI scheme capital subsidies lower equipment barriers for export-certification pipelines. |
Methodological Framework
Desk research of FSSAI regulatory filings, EU Green Deal implementation documents, and FDA import pathway standards preceded structured interviews with jackfruit processing plant managers, food manufacturer procurement leads, specialty food distributors, and Kerala-Tamil Nadu agricultural extension officers. Secondary validation drew from customs trade data, agricultural ministry harvest statistics, and food safety certification body records. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand projections from plant-based meat manufacturer ingredient sourcing disclosures.
Assumptions held India's PLI scheme subsidy rates and EU carbon-footprint disclosure timelines fixed across the analysis window, with monsoon variability and substitute protein fiber adoption rates as modeled sensitivities. Segmentation modeling incorporated product format, application end-use, and export certification tier as primary dimensions. CAGRs derived from trend extrapolation of contract farming expansion rates and food service channel penetration patterns, with dehydration technology cost curves and steam sterilization retrofit adoption as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by precision fermentation specialists or accelerated EU enforcement timelines would shift outcomes. Cross-checking against FAO agricultural trade statistics and alternative protein investment flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Global Maqui Berries Market