
 Grapes Market | 2026-2036
Grapes Market Size, Share, and Industry Trends Forecast 2026-2036
Grapes Market Outlook
Multi-source procurement from both Northern and Southern Hemisphere suppliers is rebalancing inventory risk across the grape trade. Chile leverages counter-seasonal harvest windows to supply North American and Asian markets during winter months. Italy sustains dominance in premium wine grape varietals through controlled-designation-of-origin frameworks. China anchors volume growth in table grape production, competing on scale while upgrading cold-chain infrastructure.
Grapes are fleshy, berry-type fruits of the Vitis genus, containing 15-25% sugars, organic acids, and polyphenolic compounds, cultivated on perennial woody vines trained to trellis systems for optimal sun exposure and air circulation. The fruit serves as raw material for fresh consumption, wine fermentation, raisin drying, and juice extraction across commercial food systems. Table grapes occupy the largest revenue pool in the product type dimension, though wine grapes command higher per-tonne value through processing premiums. Red and green color segments split retail shelf space, with black varieties gaining traction in antioxidant-positioned product lines. Supermarkets control the dominant distribution channel, while online retailers are capturing urban convenience-driven purchases through same-day delivery models.
The EU Green Deal and REACH frameworks govern pesticide maximum residue levels and sustainable cultivation certification for grapes entering European markets. The FDA and USDA enforce grading standards and import phytosanitary requirements for table grapes distributed in the United States. China's SAMR and GB standards regulate domestic quality benchmarks while the country's dual carbon goals pressure growers to reduce energy-intensive cold storage emissions. Stakeholders must monitor how tightening residue standards in multiple jurisdictions reshape sourcing territories and varietal planting decisions.
Market Dynamics
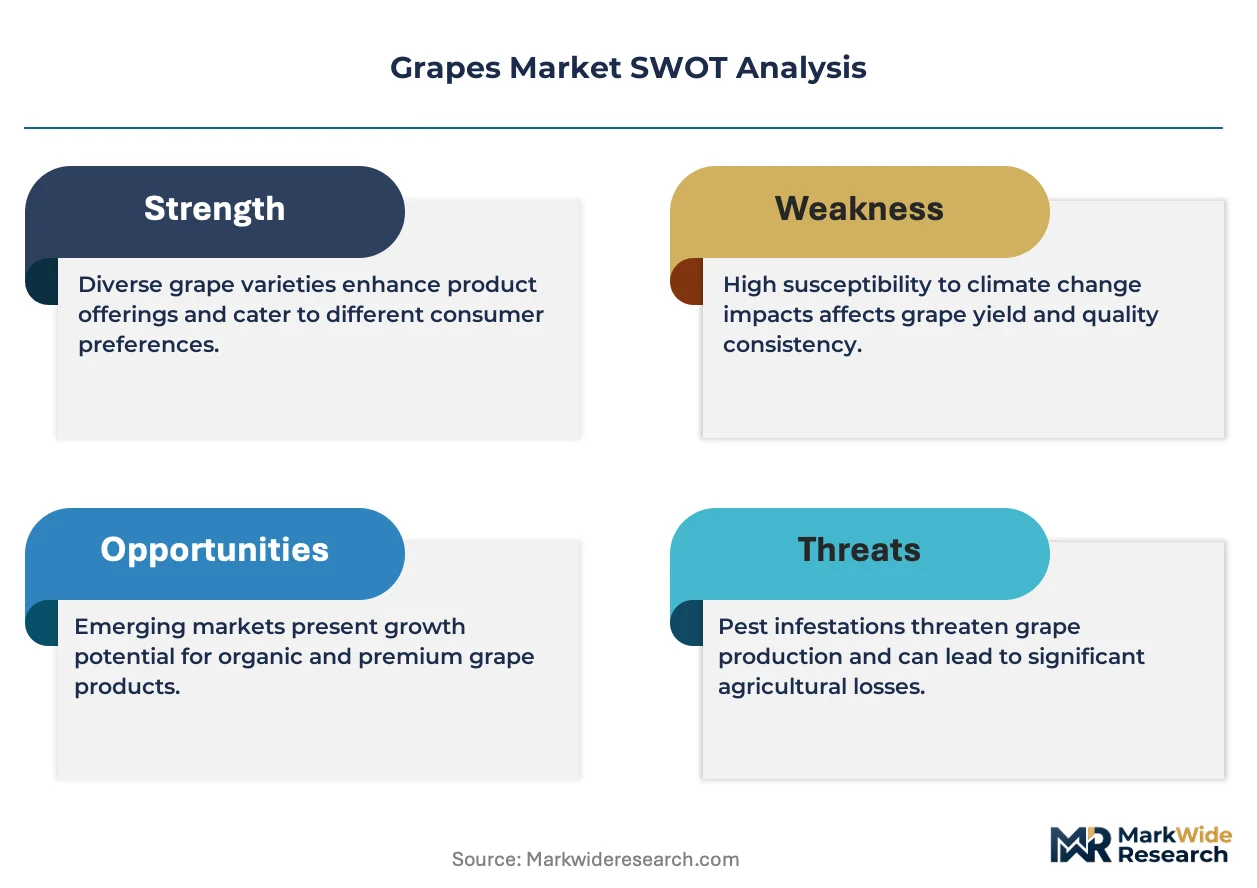
The EU Green Deal is compressing pesticide tolerance windows and forcing vineyard operators toward integrated pest management systems, reshaping input sourcing and certification costs across the value chain.
Growth Catalysts
- EU Green Deal residue limits:Tightening maximum residue levels under EFSA frameworks are accelerating adoption of biological pest control and precision spraying technologies among European growers seeking market access.
- China urban fresh demand:Rising disposable incomes in tier-one cities are expanding cold-chain procurement of premium table grape varieties through supermarket and e-commerce channels.
- Counter-seasonal supply windows:Chilean and Peruvian harvest cycles are enabling year-round North American retail shelf presence, reducing inventory risk for importers and distributors.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings are compressing margins for smallholder vineyard operations dependent on diesel-powered mechanized harvesting.
- Water access concentration:California's Central Valley and Australia's Murray-Darling Basin face allocation restrictions that constrain expansion of irrigated acreage.
- Climate-induced yield variance:Unpredictable frost and heat spike patterns are increasing crop insurance premiums and destabilizing forward contracting.
Strategic Opportunities
- India organized retail penetration:Reliance Retail and BigBasket are building cold-chain networks for imported table grapes in Mumbai, Delhi, and Bangalore metro corridors.
- Carbon-neutral certification:EU CSRD disclosure requirements are creating price premiums for vineyards with verified emissions reductions and renewable energy integration.
- Controlled-environment viticulture:Vertical farming and greenhouse systems are enabling premium grape production in non-traditional Nordic and Gulf climates.
Industry Challenges
- Skilled labor scarcity:Experienced viticulturists and certified sommelier-trained quality graders command wage premiums that strain operational budgets.
- Multi-jurisdiction compliance timelines:Simultaneous USDA organic, EU organic, and China green food certification processes extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grapes Market |
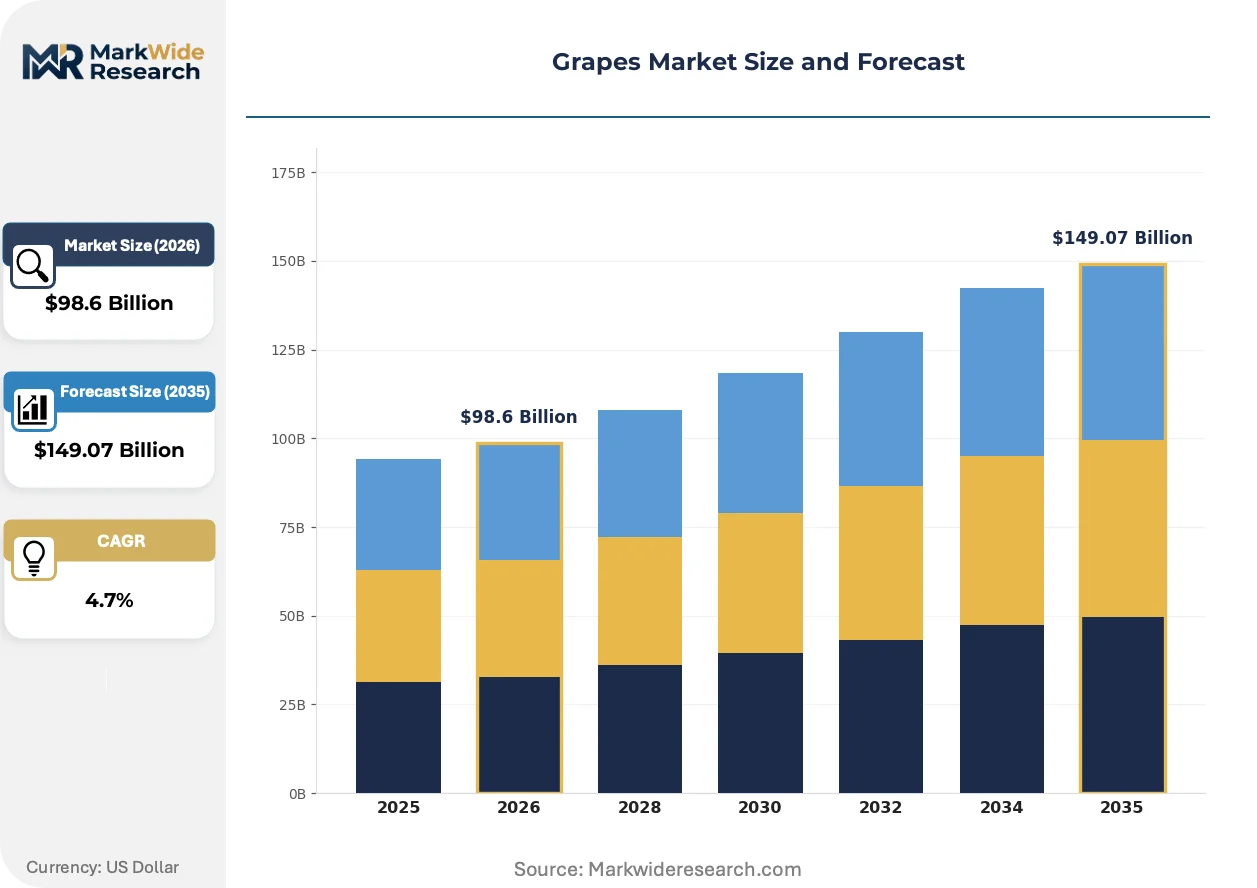
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $149.07 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Grapes, Wine Grapes, Dried Grapes, Juice Grapes Color: Red, Green, Black, Yellow Distribution Channel: Supermarkets, Online Retailers, Farmers' Markets, Specialty Stores End User: Food Industry, Beverage Industry, Retail Consumers, Food Processors |
| Companies Covered | Spain, Turkey, China, Chile, India, Italy, France, South Africa, United States, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grapes Market Strategic Shifts
Digital vineyard management and climate-adaptive cultivation systems are compressing decision cycles and enabling precision agriculture at scale across traditional and emerging production zones.
Sensor networks and drone-based multispectral imaging are electrifying canopy management and irrigation scheduling. Large-scale Chilean and Australian operators are deploying these systems across ten-thousand-hectare estates, compressing water use intensity while improving sugar-acid balance predictability.
REACH framework amendments and EU F-Gas Regulation phase-down schedules are mandating cold-chain refrigerant transitions. European grape importers and storage operators are retrofitting facilities with CO2 and ammonia systems, with German and Dutch port terminals leading capital deployment to maintain phytosanitary compliance.
Same-day delivery platforms are fragmenting traditional wholesale procurement patterns for fresh table grapes. Chinese urban consumers through Meituan and Dingdong Maicai are bypassing wet markets, forcing import distributors to reconfigure lot sizes and ripening protocols for direct-to-consumer fulfillment in Shanghai and Shenzhen.
Grapes Market Segmentation
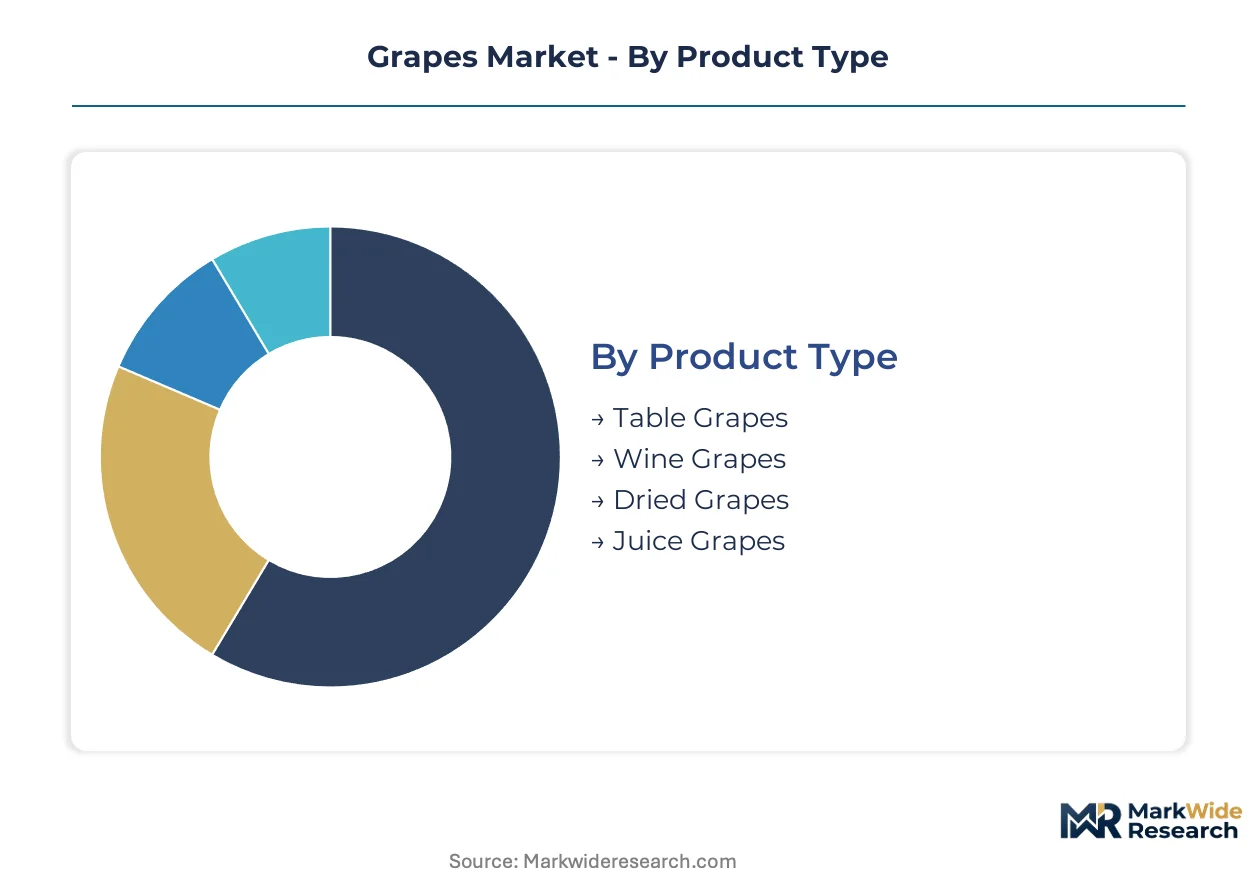
Grape segmentation reveals distinct value capture patterns across consumption formats and buyer sophistication levels. Product type and distribution channel choices determine margin structures, while color and end-user targeting shape procurement specifications and shelf positioning strategies.
Product Type:
Buyers in this category separate by processing intent versus direct consumption needs, with cold-chain requirements and perishability windows driving fundamentally different sourcing economics.
- Table Grapes:Fresh consumption varieties with firm skin, seedless profiles, and 15-25% sugar content dominate retail procurement. Chinese tier-one cities and Indian metro corridors are expanding cold-chain procurement of premium seedless varieties through supermarket and quick-commerce channels as disposable incomes rise.
- Wine Grapes:Vitis vinifera cultivars selected for sugar-acid balance, tannin structure, and terroir expression command processing premiums through fermentation value-add. Italian controlled-designation-of-origin frameworks sustain dominance in premium varietals, while Chilean and Australian estates scale mechanized harvesting for volume wine production.
- Dried Grapes:Thompson Seedless and Sultana varieties with high sugar concentration and thin skins optimize for dehydration efficiency and extended shelf stability.
- Juice Grapes:Concord and Niagara varieties selected for intense color extraction and balanced acidity serve industrial concentrate and single-strength beverage production.
Table grapes lead volumes today; wine grapes command the highest per-tonne value through processing premiums.
Color:
Retail shelf positioning and antioxidant marketing claims differentiate buyer preferences in this visually-driven category.
- Red:Anthocyanin-rich skins deliver polyphenolic compounds positioned for cardiovascular health claims. North American and European supermarkets allocate dominant shelf space to Crimson Seedless and Red Globe varieties, with Chinese e-commerce platforms expanding same-day delivery of premium red seedless clusters.
- Green:Lower tannin profiles and crisp texture appeal to fresh snacking occasions. Peruvian and Chilean counter-seasonal exports supply North American winter demand, with per-berry sizing specifications tightening for club store procurement.
- Black:Highest anthocyanin concentration supports premium antioxidant positioning in functional food lines.
- Yellow:Distinctive hue differentiation captures specialty retail and gift segment premiums.
Red and green varieties split mainstream retail presence; black grapes are climbing the fastest on health-positioned product lines.
Distribution Channel:
Channel selection determines lot sizing, ripening protocols, and margin distribution between grower and final buyer.
- Supermarkets:Controlled-atmosphere storage and centralized procurement drive volume consolidation. German and Dutch retail chains enforce EFSA residue compliance through approved supplier lists, while Chinese supermarket operators invest in direct sourcing relationships with Chilean and Australian exporters.
- Online Retailers:Same-day and next-day fulfillment models fragment traditional wholesale patterns. Meituan and Dingdong Maicai in Shanghai and Shenzhen are forcing import distributors to reconfigure ripening protocols and packaging formats for direct-to-consumer delivery.
- Farmers' Markets:Direct producer-consumer relationships capture local provenance premiums with minimal cold-chain overhead.
- Specialty Stores:Curated varietal selection and sommelier-guided purchasing serve connoisseur segments.
Supermarkets anchor volume throughput today; online retailers are expanding most quickly in Chinese and Indian urban corridors.
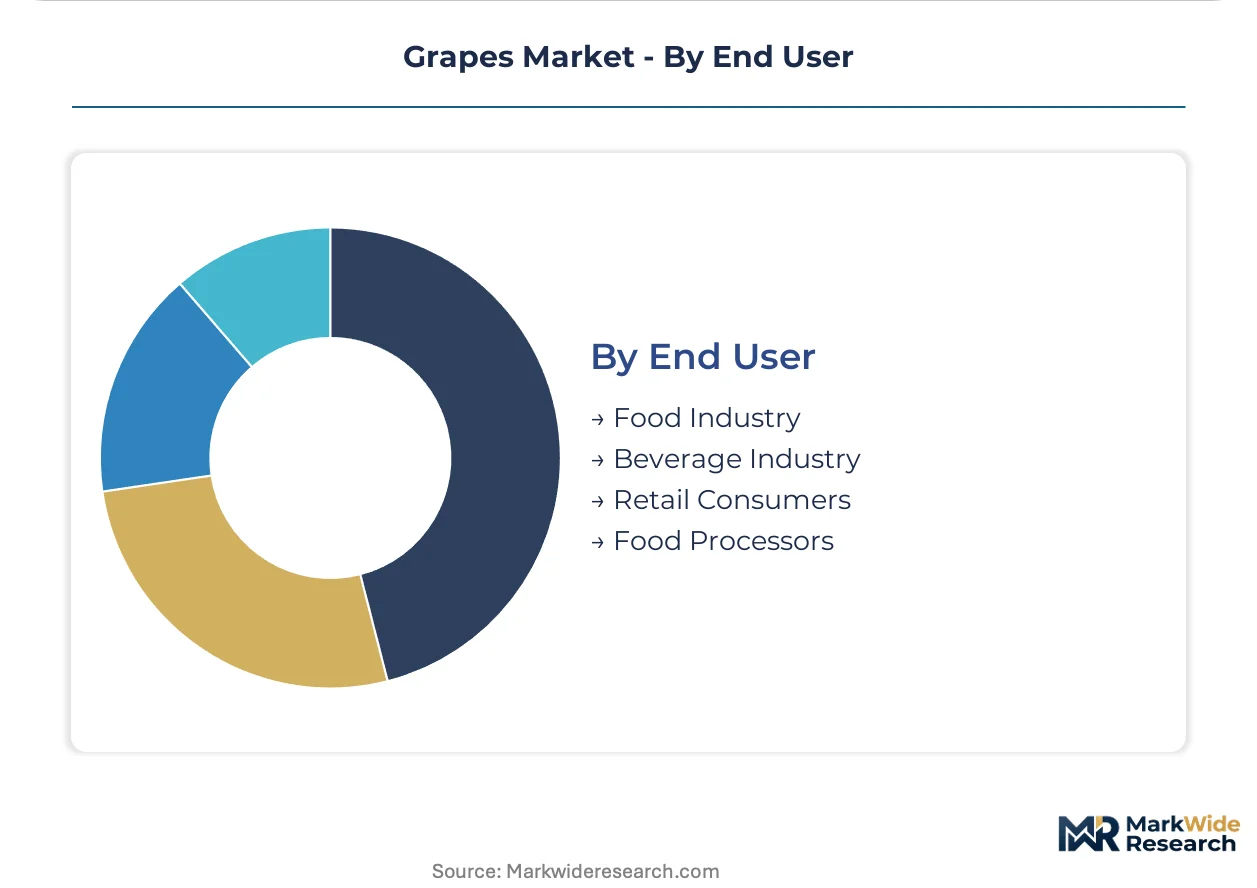
End User:
End-user segmentation separates commodity volume buyers from specification-driven processors with certified quality requirements.
- Food Industry:Bakeries, confectionery manufacturers, and prepared food operators procure standardized fruit specifications for ingredient applications. EU Green Deal residue limits are forcing ingredient buyers toward integrated pest management-certified supply chains.
- Beverage Industry:Wineries and juice processors demand sugar-acid ratios, pH specifications, and traceable vineyard documentation. California and Australian beverage producers are contracting forward for climate-resilient varietals as frost and heat spike patterns intensify.
- Retail Consumers:Fresh table grape purchases prioritize visual appeal, convenience packaging, and snacking occasion suitability.
- Food Processors:Raisin drying, concentrate production, and extract manufacturing require uniform ripeness and minimized defect thresholds.
The food industry moves the largest absolute volumes today; beverage industry buyers are gaining share fastest on premiumization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Central Valley anchors counter-seasonal supply chains that replenish North American and Asian retail shelves during winter months. Production clusters across Mendoza, Tuscany, and California's Central Valley compete on terroir differentiation and mechanization scale.
China
Urban households in Shanghai, Beijing, and Shenzhen are expanding cold-chain procurement of premium seedless varieties through supermarket and quick-commerce channels. SAMR's GB standards regulate domestic quality benchmarks while dual carbon goals pressure growers to reduce energy-intensive cold storage emissions. Xinjiang's Turpan Basin and Shandong Peninsula dominate domestic table grape production, with producers upgrading greenhouse infrastructure for year-round harvests.
United States
California's table grape shipments serve domestic retail and export markets, with Peruvian and Chilean imports filling winter demand gaps. FDA and USDA enforce grading standards and phytosanitary requirements that shape import sourcing territories. The Central Valley's Fresno and Kern counties concentrate irrigated acreage, though water allocation restrictions from the State Water Resources Control Board constrain expansion.
Italy
Premium wine grape varietals from Piedmont and Tuscany command processing premiums through controlled-designation-of-origin frameworks. EU Green Deal residue limits under EFSA frameworks accelerate biological pest control adoption among vineyard operators seeking market access. The Veneto and Apulia regions scale mechanized harvesting for volume wine production while maintaining DOC certification compliance.
India
Organized retail penetration by Reliance Retail and BigBasket builds cold-chain networks for imported table grapes in Mumbai, Delhi, and Bangalore metro corridors. FSSAI regulations govern pesticide residue thresholds and food safety certification for domestic and imported fruit. Maharashtra's Nashik district and Karnataka's Bengaluru hinterland anchor domestic production, with growers adopting integrated pest management to meet export eligibility.
Chile
Counter-seasonal harvest windows from the Atacama to Maule regions supply North American and Asian markets during Northern Hemisphere winter months. EU REACH framework amendments and F-Gas Regulation phase-down schedules mandate cold-chain refrigerant transitions for export-bound fruit. The Colchagua and Maipo valleys concentrate premium wine grape production, with estates deploying sensor networks across ten-thousand-hectare operations.
Grapes Market Competitive Environment
Global majors compete with regional champions across varietal specialization and terroir certification dimensions. The vendor base stratifies into three tiers: integrated agribusiness conglomerates with multi-hemisphere estates, family-owned controlled-designation-of-origin estates, and contract-growing cooperatives serving processor offtake agreements. Dominant competitive moves include backward integration into nursery propagation and climate-adaptive rootstock development, plus strategic partnerships with quick-commerce platforms for direct-to-consumer fulfillment.
Within the terroir-specialist tier, Italy and France exemplify controlled-designation-of-origin dominance through regional consortium structures. Spain and Turkey anchor volume production for raisin drying and table grape export markets. South Africa occupies a position between premium wine export and counter-seasonal table grape supply, with estates in the Western Cape balancing EU phytosanitary compliance with Asian market expansion.
| Leading Market Players |
|---|
| Spain |
| Turkey |
| China |
| Chile |
| India |
| Italy |
| France |
| South Africa |
| United States |
| Others |
Value Chain & Pricing Dynamics
Experienced viticulturists and certified quality graders concentrated in Italy's Piedmont and France's Champagne regions command wage premiums that widen spreads between premium DOC-tier and economy table grape pricing tiers.
Pricing Analysis
Input-cost pass-through from fertilizer and diesel fuel volatility is compressing margins for smallholder operators while reinforcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade—EU organic, China green food, or conventional—and volume scale with club store procurement. Pricing pressure stems from water allocation restrictions in California's Central Valley that constrain irrigated acreage expansion. Retail consumers through quick-commerce channels show lowest price sensitivity; food processors buying standardized raisin inputs exhibit highest.
Supply Chain Analysis
Logistics and freight costs from Chilean and Peruvian ports to Shanghai and Los Angeles container terminals represent 12-18% of landed cost for counter-seasonal table grapes. Supply concentrates in China, Chile, and Italy as dominant sourcing territories. Production draws from fertilizer inputs, diesel fuel for mechanized harvesting, and cold-chain refrigerants transitioning under EU F-Gas Regulation phase-down schedules. Single-source vulnerability runs through California's Central Valley water allocation dependence. Distribution runs through supermarket centralized procurement with ripening protocols adapted for online retailer same-day fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grapes market functions as a stable compounder anchored by perennial urbanization in Chinese tier-one cities that sustains cold-chain procurement growth regardless of cyclical volatility.
For Market Incumbents: Deploy integrated pest management certification as a defensive moat against EU Green Deal residue limit tightening. Lock in backward integration into nursery propagation and climate-adaptive rootstock development to secure varietal supply. Capture channel control through direct sourcing relationships with BigBasket and Reliance Retail in Indian metro corridors before import distributors consolidate shelf access. For New Entrants and Emerging Players: Launch via controlled-environment viticulture in Nordic and Gulf non-traditional climates where land costs undercut established terroir premiums. Target India's organized retail penetration white space where cold-chain infrastructure gaps delay incumbent reach. Pursue carbon-neutral certification positioning to capture EU CSRD disclosure-driven price premiums before scale players retrofit estates. For Investors and Strategic Acquirers: Agribusiness conglomerates with multi-hemisphere estate portfolios are the most active acquirer in this space, consolidating family-owned DOC estates for terroir diversification. Five-to-ten year viability rests on climate-resilient varietal positioning as frost and heat spike patterns intensify. Acquire contract-growing cooperatives serving processor offtake agreements for stable cash flow anchoring. Monitor Chinese dual carbon goal enforcement timelines as inflection signal for cold-chain infrastructure retrofit capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Certification Program | EU CSRD disclosure requirements create verified emissions reduction price premiums for vineyard operators. |
| Backward Integration into Rootstock Development | Climate-adaptive nursery propagation secures varietal supply against heat spike and frost pattern intensification. |
| Quick-Commerce Platform Partnership | Meituan and Dingdong Maicai same-day delivery models fragment traditional wholesale procurement patterns. |
| Integrated Pest Management Adoption | EFSA residue limit tightening under EU Green Deal mandates biological pest control for market access. |
| Counter-Seasonal Supply Window Expansion | Chilean and Peruvian harvest cycles enable year-round North American retail shelf presence reducing inventory risk. |
Study Parameters
Coverage spans China, Italy, Chile, and the United States, with primary inputs from each territory combining interviews with vineyard operators, cold-chain logistics managers, supermarket category buyers, and wine industry procurement directors with secondary validation. Secondary sources include customs and trade data from each jurisdiction, EU EFSA pesticide residue monitoring reports, SAMR GB standards documentation, and USDA grading standards filings. Bottom-up acreage and yield estimates triangulate against top-down consumption demand modeling.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, color segment, distribution channel, and end-user category with regional regulatory cluster overlays. CAGRs derive from historical trend extrapolation adjusted for policy intervention impacts. Forecast inputs incorporate water allocation restriction scenarios in California's Central Valley and EU F-Gas Regulation refrigerant transition timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-induced yield variance scenarios and multi-jurisdiction certification timeline extensions. Forecasts reflect documented assumptions on urbanization rates, disposable income trajectories, and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Vaccinium Myrtillus Market