
 North America Canned Fruits Market | 2026-2036
North America Canned Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
North America Canned Fruits Market Analytics
Grocery wholesale distribution is narrowing as club retailers and e-commerce direct-to-pantry channels capture larger volume flows in the North America canned fruits category. Del Monte Foods sustains broad shelf presence through backward integration into tropical fruit sourcing networks. Dole Food Company competes on brand recognition in the pineapple segment. Seneca Foods Corporation dominates private-label contracts with regional supermarket banners.
Canned fruits are thermally processed fruit products sealed in airtight metal containers, typically preserved in syrup, juice, or water to achieve shelf stability exceeding twenty-four months without refrigeration; the process inactivates enzymes and microbial loads through retort sterilization at temperatures above 100°C. The category serves commercial food manufacturing, institutional food service, and household pantry stocking applications where perishable alternatives face logistics constraints. Peaches and pineapples anchor the product type mix, with mixed fruit blends capturing expanded food service demand. Cans retain the majority packaging share, though pouches are gaining traction in convenience-oriented retail formats. Households represent the largest end user segment, while food manufacturers concentrate procurement for ingredient applications.
The FDA enforces standards of identity and good manufacturing practices for low-acid canned foods under 21 CFR Part 113, with the USDA Agricultural Marketing Service grading product quality for federal procurement eligibility. Health Canada and the Canadian Food Inspection Agency administer parallel safety and labeling requirements for cross-border trade. The EPA regulates wastewater discharge from fruit processing facilities under Clean Water Act permits. Stakeholders must monitor evolving sodium and added-sugar disclosure rules across U.S. and Canadian jurisdictions, as reformulation requirements could reshape syrup formulations and labeling investments.
Market Dynamics
The FDA's updated Food Safety Modernization Act preventive controls are forcing processors to reconfigure traceability systems across peach and pear supply chains concentrated in the southeastern United States.
Growth Catalysts
- Food Service Menu Expansion:Shelf-stable fruit ingredients are penetrating quick-service and institutional kitchens as operators seek labor-saving preparation alternatives. Commercial kitchens value the twenty-four-month ambient shelf stability for inventory flexibility.
- 21 CFR Part 113 Compliance Infrastructure:Retort sterilization investments by established processors create barriers to entry that protect incumbent capacity utilization. The regulation's thermal processing standards validate product safety for federal procurement eligibility.
- Southeastern Processing Clusters:Georgia and South Carolina peach processing infrastructure concentrates specialized equipment and seasonal labor pools. Proximity to Atlantic port facilities reduces inbound tropical fruit logistics costs.
Market Restraints
- Steel Input Cost Volatility:Tinplate and aluminum can sheet prices fluctuate with global metal commodity markets. Three-piece can manufacturing depends on integrated steel mill supply concentrated in domestic and Canadian production.
- Syrup Formulation Constraints:Added-sugar disclosure rules across U.S. and Canadian jurisdictions threaten traditional heavy syrup pack standards. Reformulation to juice or water packs alters texture profiles and consumer acceptance.
- Fresh and Frozen Substitution:Refrigerated logistics improvements and blast freezing technology enable year-round fresh fruit availability. Food manufacturers increasingly specify IQF fruit for ingredient applications requiring intact cell structure.
Strategic Opportunities
- Mexican Market Access:Underpenetrated distribution in northern Mexican retail channels offers volume expansion for U.S. processors with bilingual labeling capabilities. Cross-border refrigerated trucking infrastructure supports just-in-time replenishment.
- Pouch Format Conversion:Retort pouch technology reduces shipping cube and opens convenience-oriented retail formats. Flexible packaging lines require lower capital investment than traditional can-making equipment.
- USDA Grade A Procurement Contracts:Federal nutrition programs specify graded product for school lunch and military commissary eligibility. Certification investments unlock institutional volume commitments with multi-year terms.
Industry Challenges
- Retort Operator Skill Shortage:Thermal processing certification requires specialized training in time-temperature monitoring and deviation response. Aging workforce demographics constrain plant-level technical capacity expansion.
- Legacy ERP Traceability Integration:Lot tracking systems must interface with FDA's enhanced record-keeping requirements for supply chain transparency. Software upgrades strain mid-processor IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Canned Fruits Market |
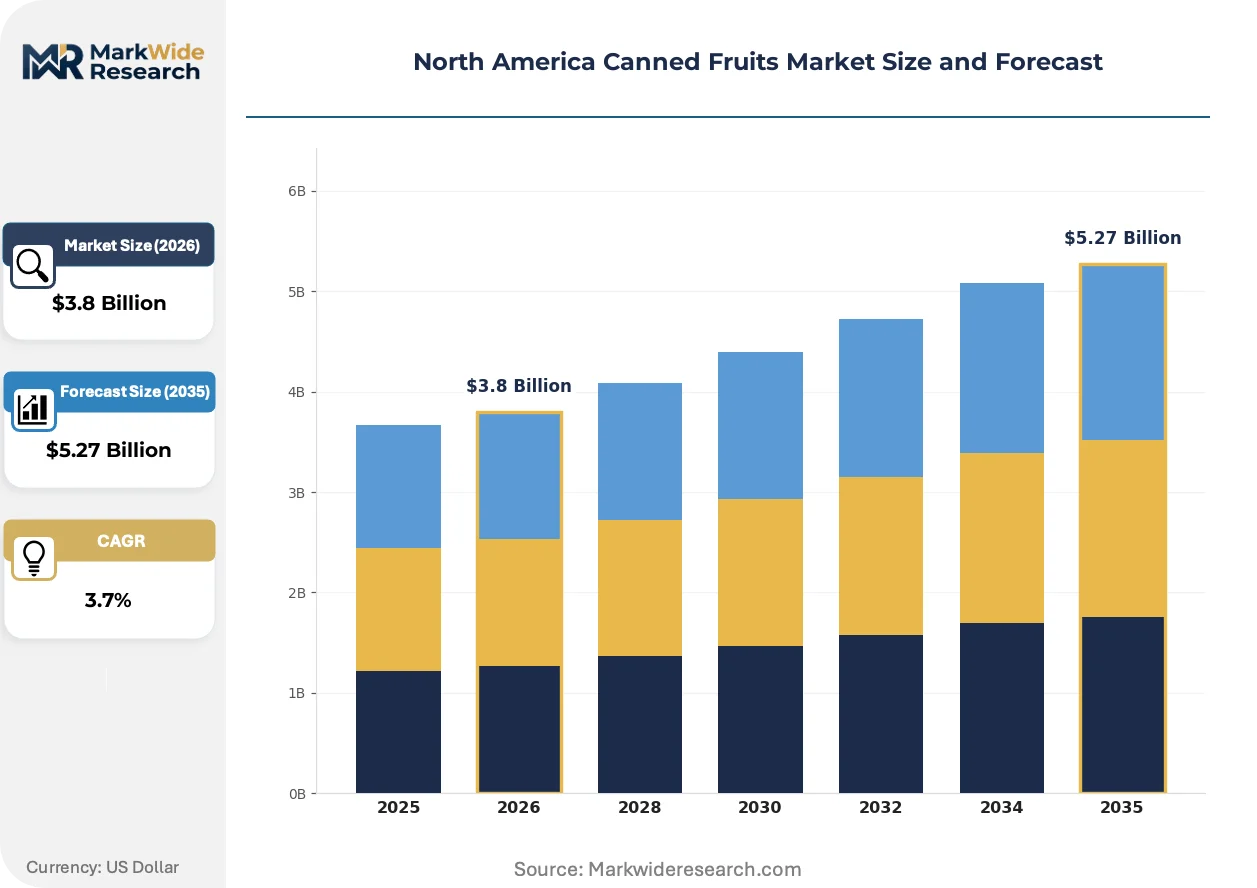
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peaches, Pears, Pineapples, Mixed Fruits End User: Households, Food Service, Retailers, Food Manufacturers Packaging Type: Cans, Tetra Paks, Glass Jars, Pouches Flavor Profile: Sweet, Tart, Spicy, Savory |
| Companies Covered | Del Monte Foods, Inc., Dole Food Company, Inc., The Kraft Heinz Company, Seneca Foods Corporation, Fresh Del Monte Produce Inc., Hormel Foods Corporation, Conagra Brands, Inc., Bonduelle, Dole Packaged Foods, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Canned Fruits Market Evolving Landscape
Digital traceability platforms and packaging format diversification are compressing traditional supply chain configurations while regulatory disclosure requirements reshape formulation strategies.
Blockchain-enabled lot tracking is digitizing pedigree documentation from orchard through retail shelf. Major food manufacturers now require granular harvest-to-can provenance data for ingredient sourcing contracts. The technology is digitizing audit trails that previously relied on paper-based chain-of-custody records, compressing recall response timelines from days to hours.
Health Canada's front-of-package nutrition symbol regulations are tightening added-sugar disclosure thresholds for cross-border trade compliance. Processors face reformulation investments or label redesign to maintain dual-market eligibility. The Canadian Food Inspection Agency's parallel enforcement is accelerating juice-pack and no-sugar-added line extensions for products distributed in both countries.
Club retailers and e-commerce direct-to-pantry channels are capturing volume flows previously routed through grocery wholesale distribution. Bulk multipack formats and subscription replenishment models displace single-unit supermarket purchases. The southeastern United States shows the most pronounced channel shift, where Amazon Fresh and Costco expansion concentrates household procurement.
North America Canned Fruits Market Segmentation
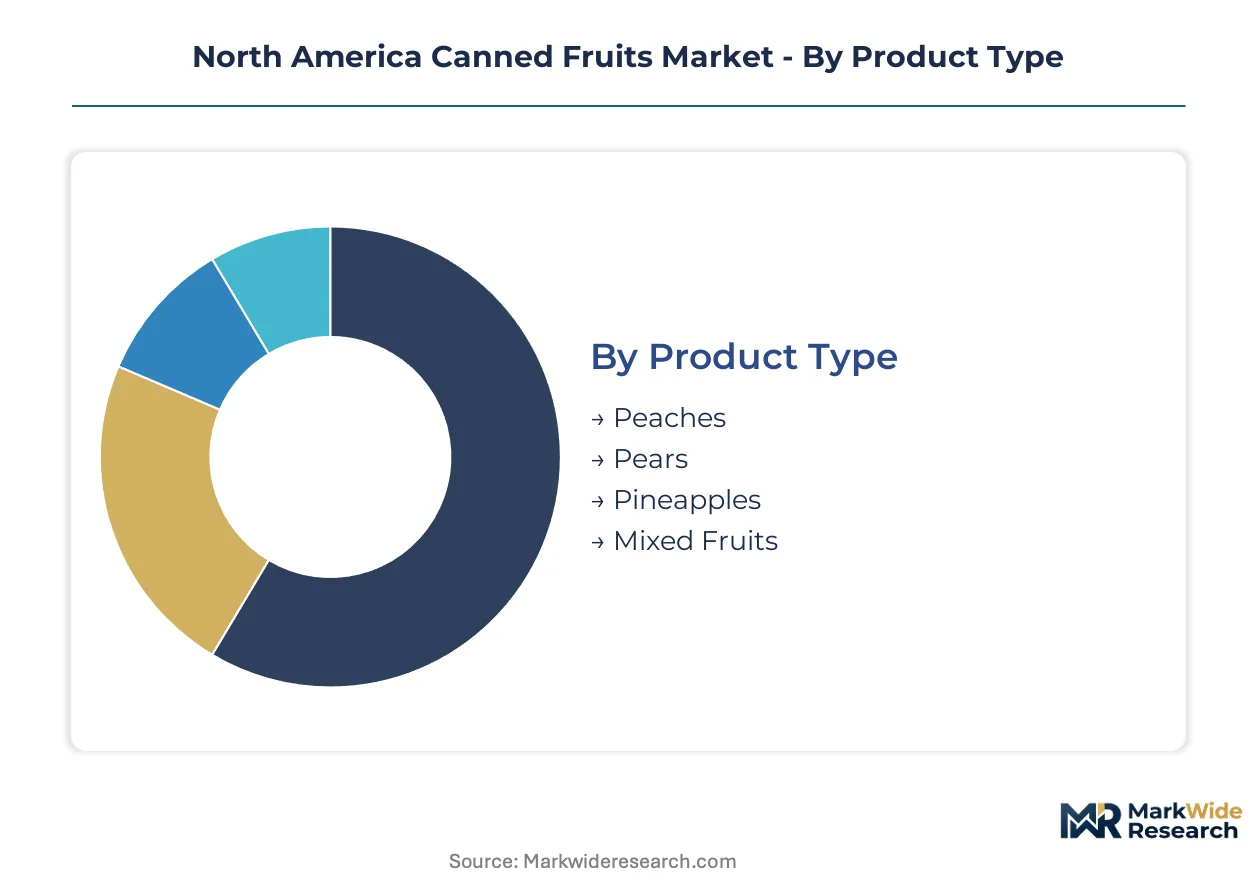
Segmentation in the North America canned fruits market reveals how thermal processing requirements, shelf stability demands, and channel economics concentrate procurement patterns across distinct buyer groups. Understanding these divides exposes where reformulation investments and packaging conversions unlock margin expansion.
Product Type:
Cost tier stratification in fruit sourcing determines which varieties anchor private-label contracts versus branded premium positioning.
- Peaches:Freestone and clingstone cultivars undergo lye peeling and steam blanching before syrup packing. Georgia and South Carolina processing clusters concentrate seasonal supply contracts with institutional buyers seeking USDA Grade A certification for federal nutrition programs.
- Pineapples:Tropical sourcing from Costa Rica and Mexico requires backward integration into grower networks to secure year-round supply. Del Monte Foods and Dole Food Company compete on plantation-controlled quality consistency for retail shelf placement.
- Pears:Bartlett varieties dominate Pacific Northwest processing with Bartlett-specific retort schedules preserving texture integrity.
- Mixed Fruits:Five-fruit and cocktail blends optimize processor utilization of sub-grade pieces from primary lines.
Peaches hold installed capacity. Pineapples is rotating up the share rankings.
End User:
Application requirements vary dramatically between inventory-flexibility-focused commercial kitchens and household pantry stocking patterns.
- Households:Pantry replenishment through club retailers and e-commerce direct-to-pantry channels is displacing single-unit supermarket purchases. Amazon Fresh and Costco expansion in the southeastern United States concentrates volume flows.
- Food Manufacturers:Ingredient applications demand intact cell structure specifications that IQF frozen alternatives increasingly satisfy for pie filling and yogurt mix-in formulations.
- Food Service:Quick-service and institutional kitchens value twenty-four-month ambient shelf stability for labor-saving preparation alternatives.
- Retailers:Private-label procurement concentrates with Seneca Foods Corporation for regional supermarket banner contracts.
Households hold installed capacity. Food Manufacturers is climbing the fastest.
Packaging Type:
Volume-to-weight ratios and capital investment thresholds separate incumbent metal formats from emerging flexible alternatives.
- Cans:Three-piece tinplate and two-piece aluminum construction dominates with retort sterilization compatibility validated under 21 CFR Part 113. Steel input cost volatility from domestic and Canadian mill supply constrains margin stability.
- Pouches:Retort pouch technology reduces shipping cube and opens convenience-oriented retail formats with lower capital investment requirements than traditional can-making equipment.
- Tetra Paks:Aseptic carton filling lines serve institutional food service bulk formats with extended shelf stability.
- Glass Jars:Premium positioning in specialty retail channels leverages visual product appeal for gift and gourmet segments.
Cans hold installed capacity. Pouches is gaining share fastest.
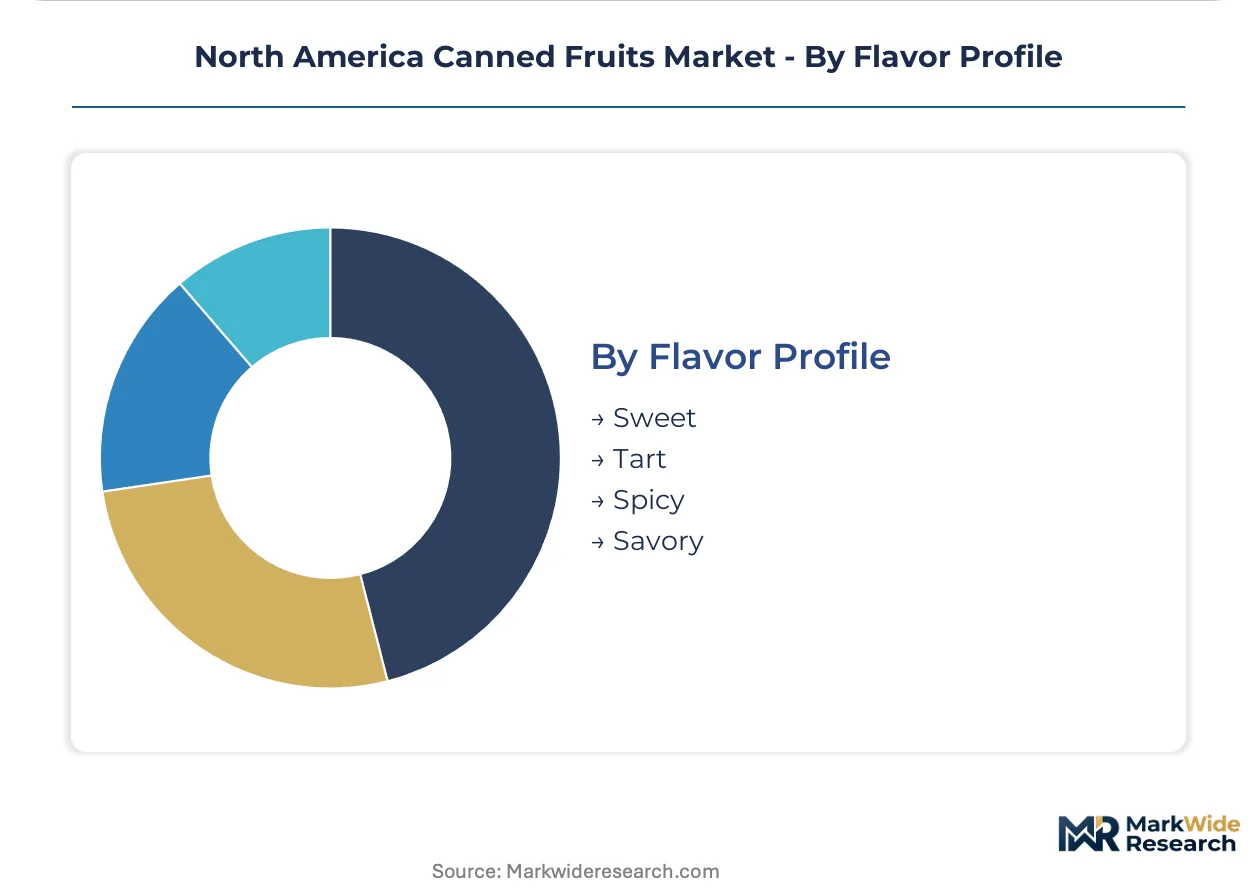
Flavor Profile:
Customer type preferences in syrup formulation expose regulatory pressure points from added-sugar disclosure rules.
- Sweet:Heavy and light syrup packs face reformulation pressure from Health Canada front-of-package nutrition symbol regulations and parallel U.S. disclosure requirements.
- Tart:Juice-packed and water-packed alternatives align with no-sugar-added line extensions for dual-market eligibility.
- Spicy:Niche positioning in ethnic food service channels leverages jalapeño and chili-infused brines.
- Savory:Crossover applications in salad and protein bowl formulations expand beyond traditional dessert positioning.
Sweet holds installed capacity. Tart is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA preventive controls and FSMA traceability mandates anchor regulatory dynamics across North America. Demand concentrates in processing clusters where thermal sterilization infrastructure meets seasonal fruit supply.
United States
Peach and pear processing concentrates in Georgia and South Carolina where specialized retort equipment and seasonal labor pools support institutional procurement. The FDA's updated Food Safety Modernization Act rules tighten supply chain documentation requirements for low-acid canned foods. Atlantic port access reduces inbound logistics costs for tropical fruit sourcing networks.
Canada
Cross-border trade flows concentrate in Ontario and Quebec where bilingual labeling capabilities serve dual-market distribution. Health Canada's front-of-package nutrition symbol regulations drive reformulation toward juice-packed and no-sugar-added line extensions. The Canadian Food Inspection Agency enforces parallel safety standards that maintain eligibility for U.S. federal nutrition programs.
Mexico
Northern Mexican retail channels remain underpenetrated for shelf-stable fruit distribution despite growing household demand. Cross-border refrigerated trucking infrastructure from Texas and Arizona supports just-in-time replenishment for club retailer expansion. Mexican processors face compliance alignment with FDA preventive controls for exported products.
North America Canned Fruits Market Competitive Landscape
Vertically integrated plantation operators and contract-based private-label specialists split the market into distinct competitive spheres. Three structural archetypes dominate: backward-integrated tropical fruit controllers, regional processing cooperatives, and private-label manufacturing platforms. Capacity consolidation and format diversification represent the dominant competitive moves as incumbents defend shelf position.
Within the integrated plantation tier, Del Monte Foods and Dole Food Company exemplify backward-controlled sourcing strategies that secure year-round supply consistency. Seneca Foods Corporation anchors the private-label manufacturing segment through regional supermarket banner relationships. These three entities represent divergent paths to market presence: captive agricultural assets versus contract manufacturing scale versus brand equity accumulation.
| Leading Market Players |
|---|
| Del Monte Foods, Inc. |
| Dole Food Company, Inc. |
| The Kraft Heinz Company |
| Seneca Foods Corporation |
| Fresh Del Monte Produce Inc. |
| Hormel Foods Corporation |
| Conagra Brands, Inc. |
| Bonduelle |
| Dole Packaged Foods, LLC |
| Others |
Value Network & Pricing Analysis
Steel input cost volatility from domestic and Canadian mill supply determines both the spread between branded premium and private-label economy tiers and the geographic clustering of three-piece can manufacturing capacity. Processors pass through metal commodity swings via quarterly contract adjustments while maintaining syrup formulation standards that anchor federal procurement eligibility.
Pricing Analysis
The customization-premium spread separates USDA Grade A certified product for institutional nutrition programs from sub-grade economy packs for club retail multipacks. Price differentiation hinges on certification tier and volume scale, with federal eligibility commanding measurable premiums over ungraded alternatives. Pricing pressure stems from added-sugar disclosure rules forcing reformulation investments in heavy syrup lines. Food manufacturers exhibit highest price sensitivity due to IQF frozen substitution, while military commissary procurement demonstrates lowest sensitivity given multi-year contract structures.
Supply Chain Analysis
Upstream feedstock flows concentrate on Costa Rica and Mexico for tropical pineapple supply, Georgia and South Carolina for peach cultivars, and the Pacific Northwest for Bartlett pear varieties. Raw material dependencies include tinplate and aluminum can sheet from integrated North American steel mills, seasonal labor pools for harvest windows, and retort sterilization chemicals for thermal processing compliance. Supply chain risk centers on single-source vulnerability for three-piece can manufacturing equipment. Distribution runs through club retailer direct-to-pantry channels and e-commerce subscription models displacing traditional grocery wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as channel bifurcation splits procurement between institutional grade-certification buyers and convenience-oriented household replenishment, creating distinct competitive arenas with divergent capability requirements.
For Market Incumbents: Harden traceability infrastructure to satisfy FDA's enhanced record-keeping mandates before compliance deadlines tighten. Deepen backward integration into tropical fruit grower networks to secure year-round supply consistency against Costa Rican weather volatility. Expand retort pouch capacity in lower-capital flexible packaging lines to capture format conversion demand from convenience retailers.
For New Entrants and Emerging Players: Build out bilingual labeling capabilities for northern Mexican retail channels where club retailer expansion outpaces local processor capacity. Target juice-packed and no-sugar-added line extensions for dual U.S.-Canada market eligibility as Health Canada's front-of-package regulations accelerate reformulation cycles. Pursue USDA Grade A certification as the go-to-market anchor for federal nutrition program contracts with multi-year volume commitments.
For Investors and Strategic Acquirers: FDA's updated preventive controls reshape the acquisition landscape toward processors with legacy ERP traceability integration already deployed. Long-term viability favors mid-cap specialists with regional processing clusters and existing institutional relationships over pure-brand plays without captive supply. Watch for retort operator skill shortage indicators as the inflection signal constraining capacity expansion regardless of capital availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Format Conversion | Reduces shipping cube and opens convenience retail channels with lower capital thresholds than can-making equipment. |
| USDA Grade A Certification Investment | Unlocks federal nutrition program eligibility for school lunch and military commissary procurement with multi-year terms. |
| Blockchain Traceability Platform Deployment | Digitizes orchard-to-can provenance for ingredient sourcing contracts requiring granular harvest documentation. |
| Backward Integration into Tropical Grower Networks | Secures year-round pineapple supply consistency against weather volatility in Costa Rica and Mexico. |
| Bilingual Labeling Capability Expansion | Enables northern Mexican retail penetration as club retailers expand cross-border distribution infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from fruit processing plant managers, retail category buyers at club and e-commerce channels, food service procurement directors, and regulatory compliance officers at FDA-registered facilities and refined through secondary validation. Trade data from U.S. Census Bureau import records, USDA Agricultural Marketing Service grading reports, FDA 21 CFR Part 113 inspection databases, and Health Canada front-of-package regulation filings anchored quantitative triangulation. Bottom-up volume modeling from processor capacity utilization and top-down demand aggregation from channel shipment data were reconciled to produce final estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type, end user application, packaging format, and flavor profile. CAGRs were derived from trend extrapolation of historical volume flows adjusted for channel shift acceleration and regulatory reformulation impacts. Forecast inputs incorporated steel commodity price trajectory assumptions and labor availability projections for seasonal processing clusters.
Sensitivities concentrate around tariff exposure for tinplate imports, retort operator workforce availability, and frozen fruit substitution rates in food manufacturing applications. Cross-checking against USDA National Agricultural Statistics Service crop production estimates and FDA low-acid canned food registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Global Avocado Market