
 Frozen Fruits and Vegetables Market | 2026-2036
Frozen Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Fruits and Vegetables Market Intelligence
IQF processing is consolidating around nitrogen-based flash-freezing as blast freezing yields to superior texture retention and lower dehydration losses. McCain Foods Limited leverages its potato-processing infrastructure to anchor frozen vegetable capacity across North American plains states. Greenyard NV sustains European retail dominance through backward integration into Belgian and Polish growing cooperatives. Bonduelle S.A. differentiates via organic certification density that commands shelf-space premiums in French and Italian hypermarkets.
Frozen fruits and vegetables denote plant matter preserved at sub-zero temperatures immediately post-harvest to arrest enzymatic degradation and microbial proliferation; individual quick freezing at minus forty degrees Celsius preserves cellular structure, enabling year-round supply of seasonal produce to retail and food-service channels. Frozen berries occupy the fastest-growing product slot as smoothie chains and plant-based dairy alternatives drive procurement volumes. Bulk packaging dominates industrial and catering end-use channels where portion-control economics outweigh consumer-facing convenience. Premium and organic quality grades capture disproportionate margin pools in household segments where clean-label positioning supports price elasticity.
The FDA enforces Hazard Analysis Critical Control Point protocols and FSMA traceability mandates that elevate compliance costs for frozen produce importers and domestic processors. The USDA Organic seal and EU REACH chemical-residue frameworks shape permissible pesticide thresholds and labeling claims across Atlantic trade corridors. Stakeholders must monitor cold-chain energy cost trajectories and refrigerant phase-down schedules as regulatory and operational variables that will determine facility location and technology refresh decisions.
Market Dynamics
Cold-chain infrastructure investments across tier-two Indian cities are redistributing frozen produce consumption patterns, forcing processors to reconfigure distribution networks around emerging urban clusters rather than traditional metro anchors.
Growth Catalysts
- FSMA Traceability Mandates:FDA digital lot-tracking requirements are accelerating supplier consolidation toward enterprise-grade ERP systems, advantaging scaled processors with capital reserves for compliance infrastructure.
- Quick-Service Restaurant Chains:Menu standardization drives frozen vegetable procurement volumes as operators seek year-round supply consistency across multi-state footprints.
- Nitrogen Flash-Freezing:IQF technology adoption preserves cellular structure at minus forty degrees Celsius, enabling texture parity with fresh produce in smoothie and plant-based dairy applications.
Market Restraints
- Refrigerant Phase-Down Schedules:F-Gas Regulation compliance in Europe and EPA SNAP restrictions in the US elevate cold-storage facility retrofit costs, compressing margins for aging plant infrastructure.
- Input Cost Volatility:Natural gas price swings directly impact blast-freezing operational economics, particularly for commodity vegetable processors lacking long-term supply contracts.
- Fresh Produce Substitution:Shortened harvest-to-retail windows for domestic fresh vegetables in temperate climates erode frozen category penetration in household segments.
Strategic Opportunities
- Indian Tier-Two Cold-Chain Expansion:Accelerating investments in refrigerated warehousing and last-mile logistics in cities like Indore and Lucknow unlock frozen food penetration in underdeveloped retail corridors.
- EU Organic Certification Density:REACH chemical-residue frameworks and EU Organic seal requirements create shelf-space premiums for certified processors serving French and Italian hypermarket channels.
- Industrial Bulk Packaging:Catering and food-manufacturing procurement shifts toward portion-control economics favor high-volume bag-in-box formats over consumer-facing retail SKUs.
Industry Challenges
- HACCP Talent Scarcity:Qualified food-safety auditors capable of managing multi-site frozen produce operations command premium compensation, constraining mid-cap processor expansion timelines.
- Legacy System Integration:Digital traceability upgrades require interoperability with existing warehouse management platforms, generating implementation friction and data-migration risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Fruits and Vegetables Market |
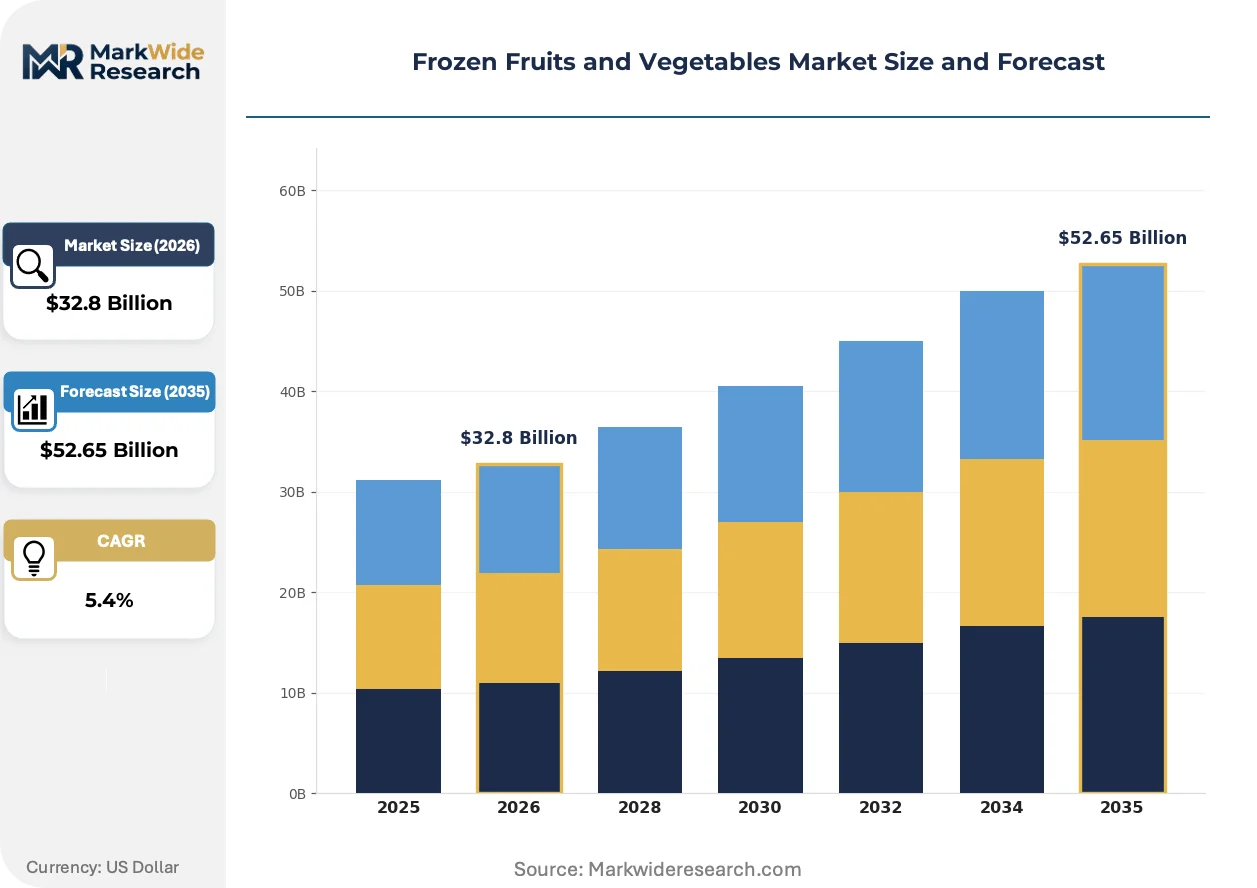
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Berries, Frozen Peas, Frozen Carrots, Frozen Spinach Packaging Type: Retail Bags, Bulk Packaging, Pouches, Cans End Use: Household, Food Service, Industrial, Catering Quality Grade: Premium, Standard, Organic, Others |
| Companies Covered | Conagra Brands Inc., General Mills Inc., Ardo Group, Nomad Foods, J.R. Simplot Co., McCain Foods Limited, Greenyard NV, Birds Eye Foods, Bonduelle S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Fruits and Vegetables Market Strategic Shifts & Innovations
Processing technology and regulatory compliance frameworks are converging to reshape competitive economics, with nitrogen-based systems and digital traceability emerging as the twin axes of differentiation.
Cryogenic freezing infrastructure is decentralizing production geography by enabling smaller-scale facilities to achieve IQF quality parity with legacy centralized plants. Regional processors in Poland and Belgium are deploying modular nitrogen tunnel freezers to serve nearby growing cooperatives without capital-intensive blast-freezing construction. This compression of optimal facility scale is fragmenting supply concentration and enabling backward integration by agricultural collectives.
The FDA's updated Food Safety Modernization Act traceability rules impose granular lot-record requirements on frozen produce importers and domestic handlers. Compliance costs favor enterprise-scale processors with integrated ERP systems, pressuring smaller operators toward third-party logistics partnerships or exit. Frozen berry suppliers face the steepest documentation burden due to multi-source blending practices and extended supply chains.
Smoothie chains and plant-based dairy manufacturers are consolidating procurement around frozen berry specifications that prioritize brix levels and texture retention over price minimization. This specification-driven purchasing compresses supplier margins for commodity-grade fruit while rewarding processors with calibrated IQF protocols and varietal segmentation capabilities. The shift is most visible in North American food-service channels where chain operators specify cultivar and origin in master supply agreements.
Frozen Fruits and Vegetables Market Segmentation
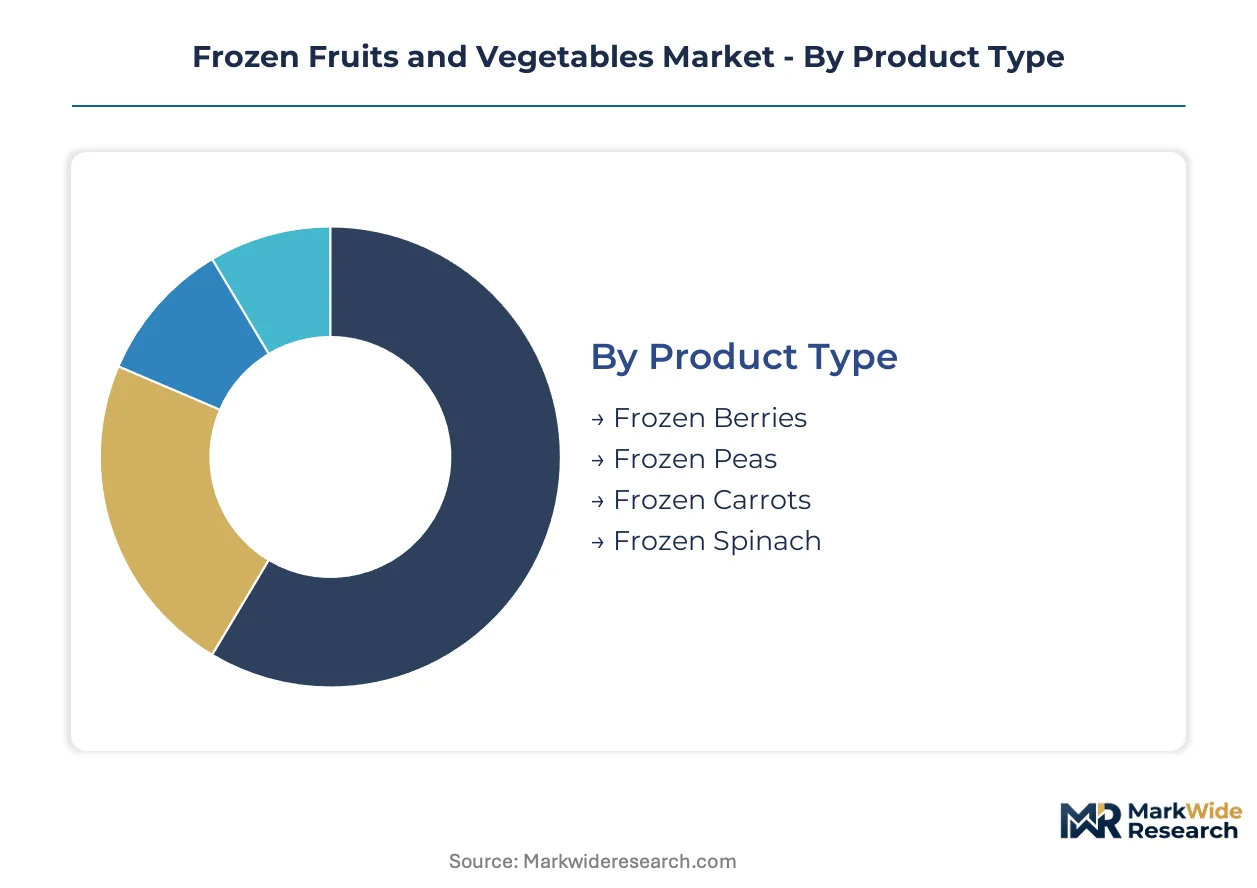
Frozen produce segmentation reflects divergent supply chain economics between embedded industrial inputs and standalone retail formats. Each dimension shapes procurement specifications, cold-chain requirements, and margin structures differently.
Product Type:
Integration depth varies sharply: berries embed into beverage manufacturing while peas and carrots serve dual retail and food-service channels.
- Frozen Berries:IQF-processed strawberries, blueberries, and raspberries retain cellular integrity at minus forty degrees Celsius for smoothie chains and plant-based dairy manufacturers. Procurement concentrates in North American food-service channels where chains specify brix levels and cultivar origin in master supply agreements.
- Frozen Peas:Blast-frozen garden and petit pois varieties anchor commodity vegetable procurement for quick-service restaurant chains seeking menu standardization across multi-state footprints. Demand clusters in institutional catering where portion-control economics outweigh texture premiums.
- Frozen Carrots:Diced, sliced, and crinkle-cut formats serve industrial soup and ready-meal manufacturing.
- Frozen Spinach:Leaf and chopped grades supply retail private-label and food-service channels.
Frozen peas lead volumes today; frozen berries are gaining share fastest.
Packaging Type:
Cost tiers separate consumer-facing convenience from industrial portion-control economics.
- Retail Bags:Printed polypropylene and polyethylene laminates with resealable closures dominate supermarket frozen vegetable aisles. Household penetration depends on clean-label positioning and organic certification density in French and Italian hypermarkets.
- Bulk Packaging:Ten-kilogram to twenty-kilogram bag-in-box formats serve catering and food-manufacturing procurement where scale economics compress per-unit logistics costs. Demand concentrates in Indian tier-two cities as cold-chain infrastructure investments accelerate.
- Pouches:Stand-up and flat retort-compatible formats target microwave-ready meal kits.
- Cans:Metal and composite containers preserve ambient-stable processed vegetables for emergency stockpiling segments.
Bulk packaging dominates industrial channels; retail bags capture the steepest margin premiums.
End Use:
Customer type determines specification stringency and contract structure.
- Household:Supermarket and e-commerce procurement of branded and private-label frozen vegetables. Quality grade stratification creates pricing tiers across premium, standard, and organic levels in European retail.
- Food Service:Quick-service restaurant chains and institutional cafeterias procure frozen vegetables for menu consistency. FDA FSMA traceability mandates pressure suppliers toward digital lot-tracking systems.
- Industrial:Food manufacturers blend frozen produce into soups, sauces, and ready meals.
- Catering:Event and contract catering operations source bulk formats for volume feeding.
Food service leads procurement volumes; industrial use is expanding most quickly.
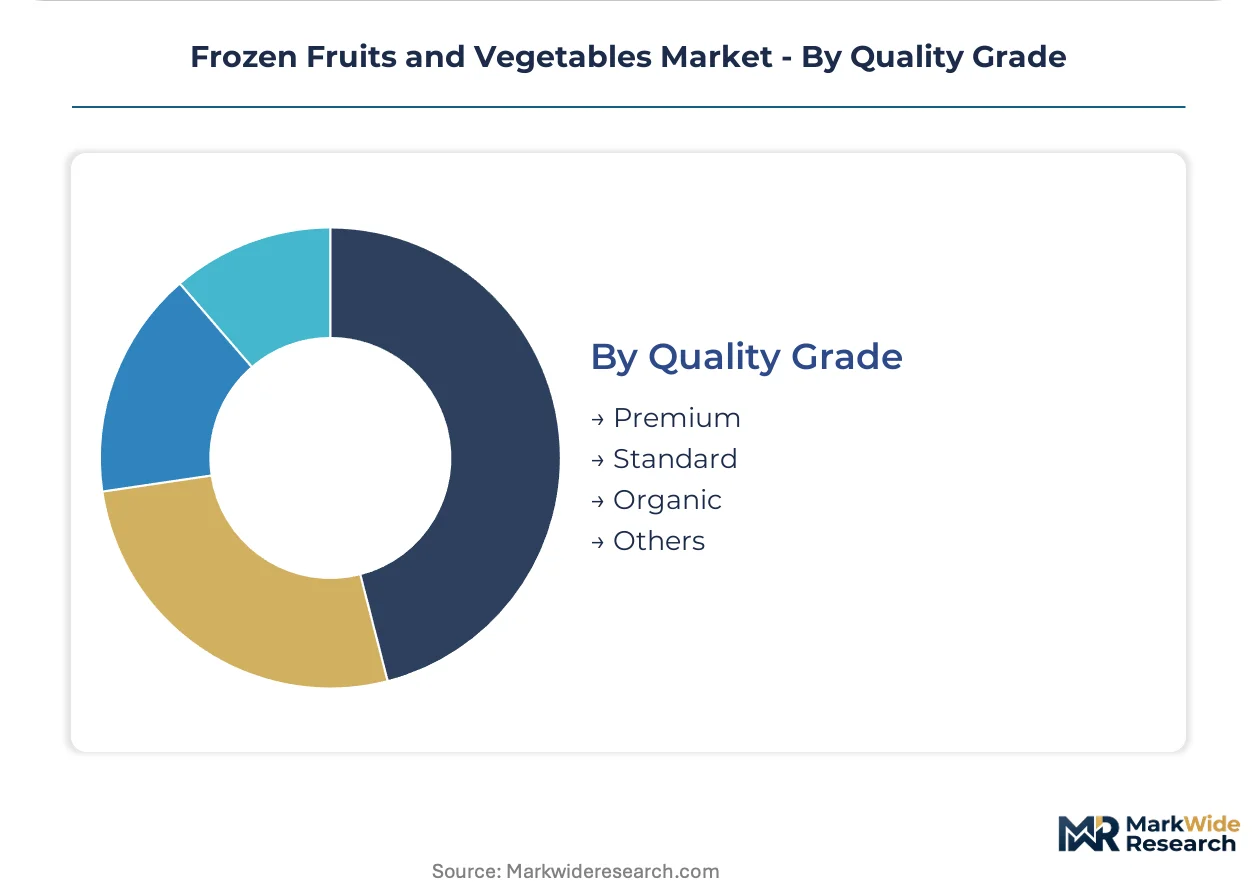
Quality Grade:
Certification density shapes permissible pesticide thresholds and shelf-space allocation.
- Premium:Cultivar-specific, origin-designated produce with calibrated IQF protocols commanding texture parity with fresh. Bonduelle S.A. and Greenyard NV anchor European retail dominance through backward integration into growing cooperatives.
- Organic:USDA Organic seal and EU REACH chemical-residue compliance create entry barriers and price premiums. McCain Foods Limited leverages potato-processing infrastructure to anchor organic vegetable capacity.
- Standard:Commodity-grade produce meeting baseline FDA HACCP protocols for mass-market penetration.
- Others:Private-label and economy tiers serving price-sensitive retail segments.
Standard grade leads volumes today; organic certification is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian and Polish growing cooperatives anchor European frozen vegetable processing capacity, while nitrogen flash-freezing infrastructure expands across North American plains states and tier-two Indian cities.
United States
Quick-service restaurant chains drive frozen vegetable procurement volumes for menu standardization across multi-state footprints. FDA FSMA traceability mandates pressure suppliers toward digital lot-tracking systems and enterprise-grade ERP infrastructure. McCain Foods Limited leverages potato-processing assets across plains states to anchor frozen vegetable capacity.
India
Cold-chain infrastructure investments accelerate frozen food penetration in tier-two cities like Indore and Lucknow as refrigerated warehousing expands. FSSAI food safety protocols and PLI scheme incentives support processing facility modernization. Bulk packaging formats dominate emerging urban retail corridors where portion-control economics outweigh consumer convenience premiums.
Germany
EU REACH chemical-residue frameworks shape permissible pesticide thresholds for frozen produce entering French and Italian hypermarket channels. F-Gas Regulation compliance elevates cold-storage facility retrofit costs across industrial zones. Greenyard NV sustains retail dominance through backward integration into regional growing cooperatives.
France
Organic certification density commands shelf-space premiums in hypermarket channels where clean-label positioning supports price elasticity. EU Organic seal requirements create entry barriers for imported frozen produce. Bonduelle S.A. differentiates via certified organic vegetable grades serving household segments.
Belgium
Modular nitrogen tunnel freezers enable smaller-scale facilities to achieve IQF quality parity with legacy centralized plants. ECHA chemical safety protocols govern processing facility emissions and refrigerant phase-down schedules. Regional processors deploy decentralized production to serve nearby Polish and domestic growing cooperatives.
Frozen Fruits and Vegetables Market Key Industry Players
Global majors compete with regional champions across processing technology and cold-chain infrastructure dimensions. The vendor base stratifies into three tiers: scale-driven conglomerates with multi-category portfolios, mid-cap specialists with backward integration into growing cooperatives, and niche organic certifiers commanding premium shelf-space allocations. Consolidation pressures intensify as FDA traceability mandates and refrigerant phase-down schedules elevate compliance costs. Dominant competitive moves include strategic partnerships for cold-chain expansion and technology licensing for nitrogen flash-freezing systems.
Within the scale-driven tier, Conagra Brands Inc. and General Mills Inc. represent diversified food conglomerates with frozen vegetable portfolios spanning retail and food-service channels. Ardo Group and Nomad Foods occupy positions as European specialists with regional processing density. McCain Foods Limited anchors North American capacity through infrastructure originally built for potato processing. Greenyard NV and Bonduelle S.A. exemplify the backward-integrated archetype with cooperative supply relationships in Belgian and Polish growing regions.
| Leading Market Players |
|---|
| Conagra Brands Inc. |
| General Mills Inc. |
| Ardo Group |
| Nomad Foods |
| J.R. Simplot Co. |
| McCain Foods Limited |
| Greenyard NV |
| Birds Eye Foods |
| Bonduelle S.A. |
| Others |
Cost & Logistics Intelligence
Quick-service restaurant chains concentrating procurement volumes across multi-state footprints anchor contract-based long-term offtake agreements that compress spot-market exposure for frozen vegetable suppliers. This buyer consolidation shifts pricing power toward volume-tiered negotiations where specification stringency determines premium capture.
Pricing Analysis
Natural gas price swings pass through directly to blast-freezing operational economics, particularly for commodity processors lacking long-term supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified grades commanding shelf-space premiums in French and Italian hypermarkets from baseline HACCP-compliant commodities. Pricing pressure stems from refrigerant phase-down compliance costs elevating cold-storage facility retrofit burdens. Household segments exhibit highest price sensitivity in temperate climates where shortened fresh produce harvest-to-retail windows enable substitution.
Supply Chain Analysis
Dual-sourcing requirements from FDA FSMA traceability mandates force quick-service chains and food manufacturers to qualify multiple IQF processors per product category, fragmenting volume concentration. Supply concentrates in Belgian and Polish growing cooperatives for European retail, with North American plains states anchoring McCain Foods' vegetable processing capacity. Nitrogen gas, agricultural labor, and refrigerated warehousing constitute critical input dependencies. Single-source vulnerability emerges from concentrated nitrogen flash-freezing equipment suppliers. Distribution runs through temperature-controlled third-party logistics networks serving retail, food-service, and industrial channels with distinct cold-chain protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where smoothie chains and plant-based dairy manufacturers consolidating procurement around brix-level specifications reward processors with calibrated IQF protocols.
For Market Incumbents: Hedge nitrogen supply exposure through long-term gas contracts or captive on-site generation infrastructure before refrigerant phase-down schedules compress margins further. Reinforce backward integration into growing cooperatives in Poland and Belgium to secure cultivar-specific supply for premium grades. Defend against fresh produce substitution in temperate climates by emphasizing texture parity and year-round availability guarantees in master supply agreements.
For New Entrants and Emerging Players: Food-service distributors represent the most accessible channel partners for modular nitrogen tunnel freezer deployments achieving IQF quality without capital-intensive centralized plant construction. White-space targets include Indian tier-two cities where cold-chain infrastructure investments accelerate frozen food penetration, and organic-certified berry processing for North American smoothie chains. Pursue specification-driven purchasing relationships that prioritize brix levels and texture retention over commodity price minimization.
For Investors and Strategic Acquirers: Private-label retail conglomerates represent the most active acquirer in this space, seeking backward-integrated processing capacity to secure supply chain control. The five-to-ten-year viability window favors mid-cap specialists with cooperative supply relationships and modular freezing technology enabling geographic flexibility. Acquisition target archetype: regional processors in Poland or Belgium with established growing cooperative partnerships and nitrogen flash-freezing capabilities. Monitor FDA enforcement patterns on digital traceability compliance as the signal indicating consolidation acceleration versus fragmentation persistence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Growing Cooperatives | Greenyard NV and Bonduelle S.A. secure cultivar-specific supply for premium grades serving EU hypermarkets. |
| Nitrogen Flash-Freezing Technology Licensing | Regional processors in Belgium deploy modular tunnel freezers to achieve IQF parity without centralized plant investment. |
| Digital Traceability System Implementation | Enterprise-grade ERP integration satisfies FDA FSMA mandates and pressures smaller operators toward exit or partnership. |
| Cold-Chain Infrastructure Expansion | Refrigerated warehousing investments in Indian tier-two cities unlock frozen food penetration in underdeveloped retail corridors. |
| Organic Certification Density Investment | USDA Organic seal and EU REACH compliance create entry barriers and price premiums in French and Italian channels. |
Research Approach
Multiple input streams — primary interviews with frozen food processing executives, quick-service restaurant procurement directors, and cold-chain logistics operators; secondary validation through FDA FSMA guidance documents, USDA organic certification databases, and EU REACH chemical-residue frameworks; plus customs trade data and food-service distribution channel records — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across product type, packaging format, end-use channel, quality grade, and regional production hub dimensions shaped analytical framework construction over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions calibrated to nitrogen flash-freezing adoption curves and cold-chain infrastructure investment patterns. Forecast inputs incorporated refrigerant phase-down compliance cost trajectories and FSSAI protocol modernization timelines in India.
Revisions become necessary when FDA enforcement intensity on digital traceability mandates, natural gas price volatility affecting freezing economics, or fresh produce harvest-to-retail compression in temperate climates materialize differently than modeled. Deviation in nitrogen equipment supplier concentration or cooperative supply contract renewal rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Cucumber and Gherkins Market