
 United States Frozen Fruits and Vegetables Market | 2026-2036
United States Frozen Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
United States Frozen Fruits and Vegetables Market Intelligence
Supermarket freezer aisle placement is narrowing as private-label and branded suppliers battle for shelf space. Conagra Brands leverages its Birds Eye heritage to anchor premium vegetable positioning in conventional retail. Dole Packaged Foods competes through tropical fruit specialization and food-service portion control. JR Simplot Company dominates potato and vegetable processing with backward integration into Idaho farming operations.
Frozen fruits and vegetables comprise produce flash-frozen at peak ripeness, typically at temperatures below minus eighteen degrees Celsius, then packaged for extended shelf-life retention of vitamins and texture. The category serves commercial kitchens and households seeking year-round ingredient consistency without spoilage loss. Frozen vegetables sustain higher volume throughput in bags and bulk containers through institutional channels, while frozen fruits lead margin capture in individual portions sold via online retail. Mixed frozen produce occupies a growing niche as meal-kit suppliers standardize recipe inputs.
The USDA grades frozen products for quality under its Agricultural Marketing Service, while FDA enforces hazard analysis requirements across processing plants. State-level cold-chain inspections in California and Florida supplement federal oversight with facility audits. Stakeholders must monitor how FDA traceability rules reshape supplier documentation burdens and whether state energy policies raise refrigeration costs for freezing cooperatives.
Market Dynamics
California's Central Valley freezing corridor now dictates national supply rhythms, with processors clustering within fifty miles of strawberry and spinach harvest zones to compress field-to-freezer windows below four hours. This geographic lock-in shapes capital allocation, labor mobility, and cold-chain infrastructure investment across the entire domestic market.
Growth Catalysts
- Food Safety Modernization Act preventive controls:FDA's updated rules on hazard analysis and risk-based preventive controls force processors to upgrade documentation systems, creating competitive moats for compliant operators.
- Meal-kit ingredient standardization:Recipe-input consistency requirements from Blue Apron, HelloFresh, and regional competitors pull frozen mixed produce into portion-controlled formats.
- Central Valley co-location economics:Freezing facilities adjacent to Salinas spinach and Watsonville strawberry operations capture harvest-quality premiums unavailable to distant processors.
Market Restraints
- Natural gas price volatility:Blast freezing and cold storage operations face margin compression when Henry Hub spikes disrupt energy hedging strategies.
- Refrigerant phase-down constraints:EPA's AIM Act restrictions on HFCs force capital-intensive retrofits of existing freezing tunnels before 2027 compliance deadlines.
- Fresh produce substitution:Controlled-atmosphere shipping and hydroponic greenhouse expansion extend seasonal fresh availability, narrowing frozen's traditional price-quality window.
Strategic Opportunities
- Texas and Southeast distribution hubs:Underpenetrated freezing capacity in Dallas-Fort Worth and Atlanta corridors offers population-growth exposure beyond California saturation.
- USDA BioPreferred procurement mandates:Federal purchasing preference for biobased packaging materials creates first-mover advantages for compostable frozen bag suppliers.
- Smart freezer IoT convergence:Temperature-logging sensors combined with predictive maintenance algorithms enable outcome-based cold-chain service contracts for food-service distributors.
Industry Challenges
- Blast-freezer technician scarcity:Specialized ammonia refrigeration expertise concentrates among retiring union workforces in Pacific Northwest potato processing regions.
- Traceability system integration:FDA's Food Traceability Rule mandates interoperable record-keeping from farm to retail, forcing legacy ERP overhauls at mid-sized cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Frozen Fruits and Vegetables Market |
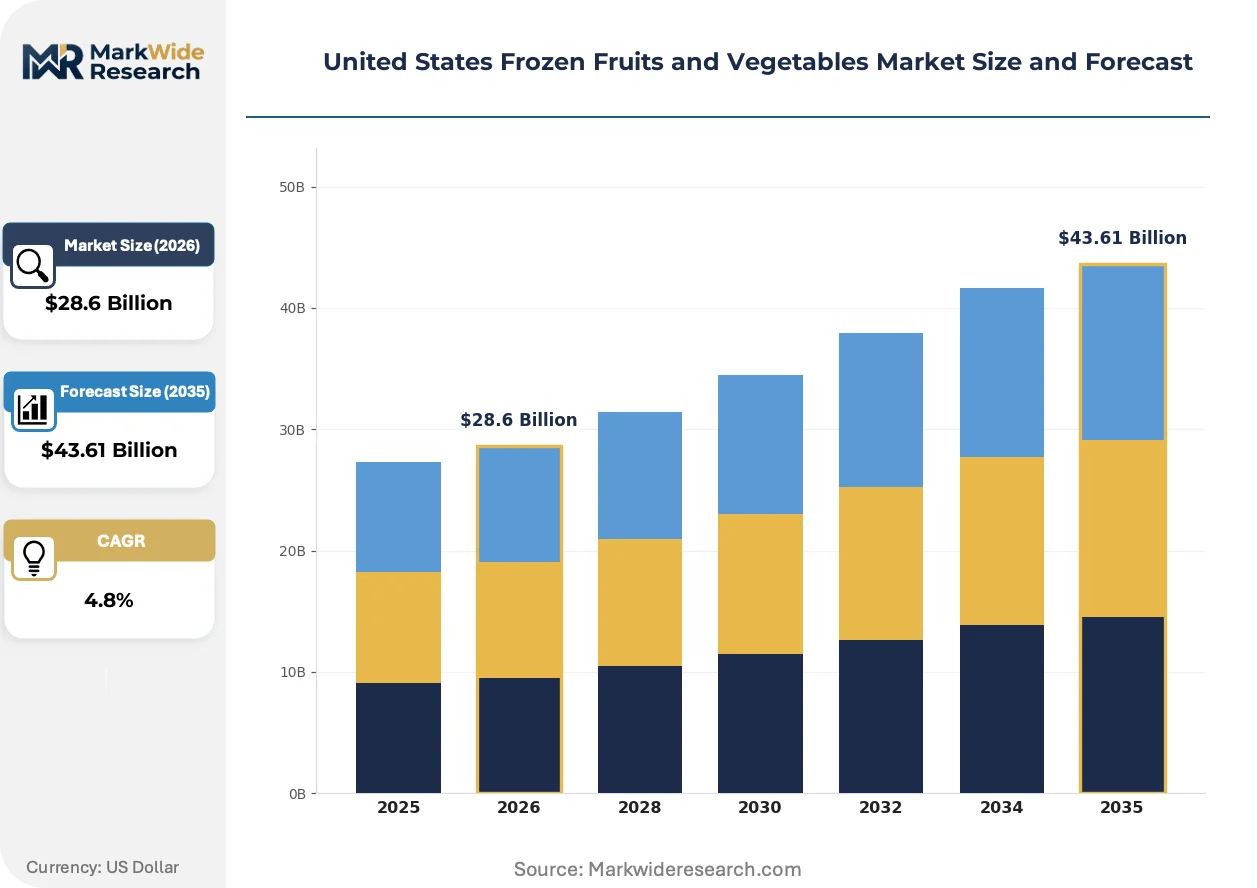
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fruits, Frozen Vegetables, Mixed Frozen Produce, Frozen Herbs End User: Households, Restaurants, Food Service, Retailers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bags, Boxes, Bulk Containers, Individual Portions |
| Companies Covered | Conagra Brands, General Mills, Dole Packaged Foods, Nestlé USA, SunOpta, Ardo NV, JR Simplot Company, Birds Eye Foods, Driscoll's, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Frozen Fruits and Vegetables Market Strategic Shifts & Innovations
Flash-freezing technology and cold-chain visibility tools are compressing quality-degradation windows while reshaping buyer-processor relationships. These shifts favor operators with capital reserves for equipment refresh cycles.
Individual quick freezing (IQF) tunnel technology with nitrogen-cooled cryogenic systems is digitizing quality-control protocols through embedded thermocouple arrays and real-time moisture-loss tracking. Large food-service distributors now mandate IQF certification for berry suppliers, rejecting traditional block-frozen alternatives. This specification pressure is digitizing procurement documentation, as buyers require batch-level temperature logs downloadable via API.
FDA's Food Traceability Rule under Section 204 of the Food Safety Modernization Act imposes electronic record-keeping requirements for twenty-two listed foods including leafy greens and berries. Processors must capture key data elements at each critical tracking event, with compliance deadlines compressing IT implementation timelines. Smaller freezing cooperatives in Florida's strawberry belt face disproportionate compliance burdens relative to integrated California operators.
Direct-to-restaurant procurement through platforms like Cheetah Technologies and Restaurant Depot's digital ordering systems is fragmenting traditional broadline distributor relationships. Independent smoothie shops and fast-casual chains now source frozen fruit blends through app-based purchasing with next-day delivery guarantees. This channel disintermediation concentrates most visibly in Austin, Nashville, and Denver metropolitan areas where operator density supports micro-fulfillment models.
United States Frozen Fruits and Vegetables Market Segmentation
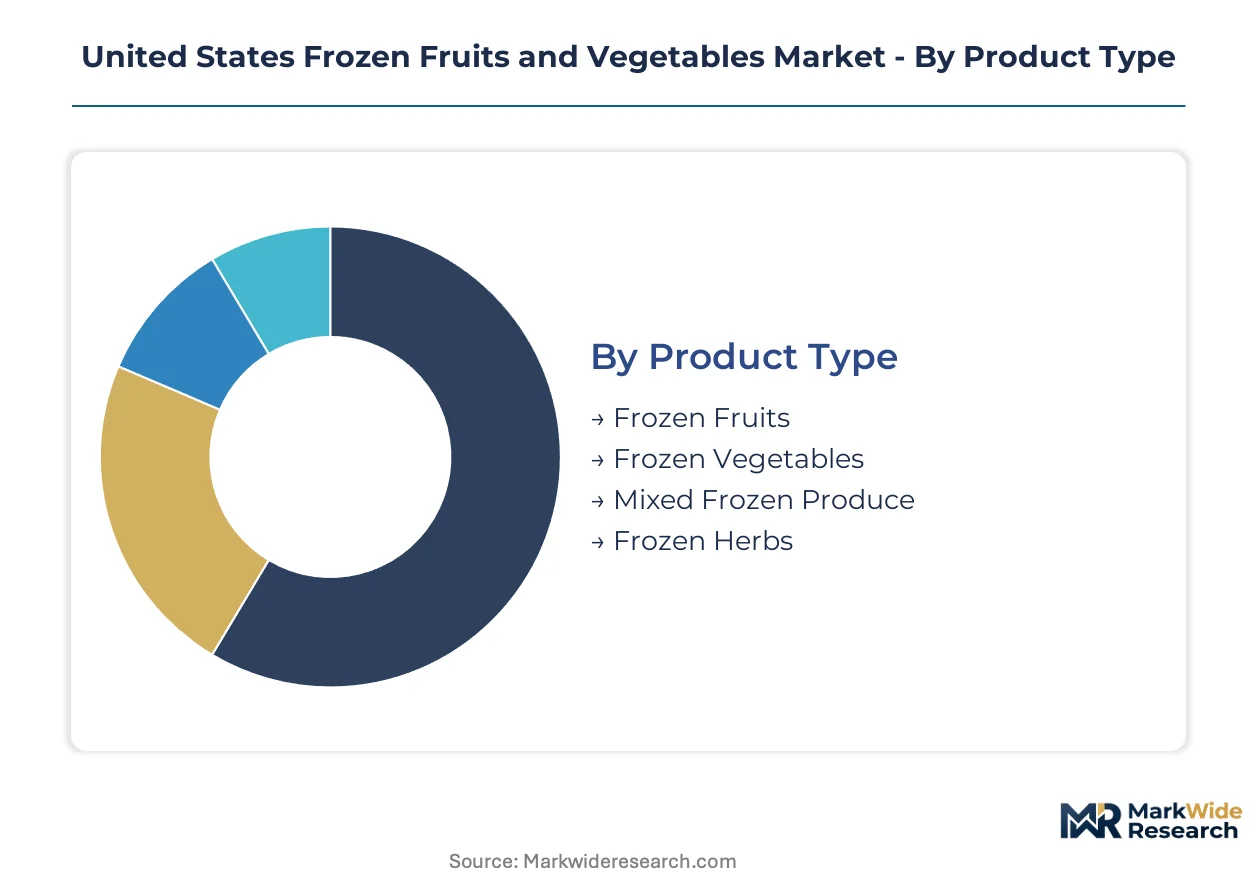
Segmentation in the United States frozen fruits and vegetables market reveals how procurement cycles, shelf-life requirements, and channel economics split demand across distinct operational profiles. Each dimension carries implications for freezing technology selection, inventory velocity, and margin structure.
Product Type:
Frozen fruits turn inventory fastest through smoothie and baking channels, while frozen vegetables move more slowly through institutional procurement with longer contract cycles. Mixed frozen produce and frozen herbs occupy intermediate velocity positions depending on meal-kit integration depth.
- Frozen Fruits:IQF-processed berries, tropical fruits, and stone fruits retain cellular integrity through cryogenic tunnel freezing. California's Central Valley strawberry processors supply quick-service smoothie chains with four-hour field-to-freezer documentation that fresh alternatives cannot match.
- Frozen Vegetables:Blanched and blast-frozen broccoli, peas, corn, and spinach deliver standardized cook times for institutional kitchens. Idaho's integrated potato processors anchor volume through backward integration into farming operations that control varietal selection for fry and flake applications.
- Mixed Frozen Produce:Pre-combined vegetable medleys and fruit blends reduce kitchen labor for food-service operators. Meal-kit suppliers standardize recipe inputs through portion-controlled mixed formats.
- Frozen Herbs:Basil, cilantro, and parsley preserved through rapid freezing maintain volatile oil profiles. Specialty food manufacturers source frozen herbs for sauce and seasoning applications.
Frozen vegetables dominate installed base. Frozen fruits is where expansion concentrates.
End User:
Cost tier stratification separates premium household buyers from price-sensitive institutional accounts, with margin compression intensifying at the food-service scale.
- Households:Convenience-seeking consumers purchase retail-format frozen produce for home cooking and smoothie preparation. Online grocery expansion has shifted household procurement toward direct-to-door frozen delivery with dry-ice packaging.
- Restaurants:Independent and chain operators source frozen produce for menu consistency across seasons. Fast-casual concepts specify IQF berries for beverage programs requiring predictable texture and brix levels.
- Food Service:K-12 schools, hospitals, and correctional facilities procure frozen vegetables in bulk through USDA commodity programs. These institutional buyers prioritize shelf stability and portion control over premium quality tiers.
- Retailers:Supermarket chains and club stores manage private-label frozen produce programs competing on price with branded alternatives. Retailer consolidation has reduced supplier counts through centralized procurement at the banner level.
Food service commands volume throughput. Households is where margin expansion concentrates.
Distribution Channel:
Geographic reach and cold-chain reliability separate channels, with proximity to freezing infrastructure determining viable service territories.
- Supermarkets:Traditional grocery freezer aisles allocate shelf space through category management negotiations with national suppliers. California-based processors leverage co-location advantages to secure preferred placement in West Coast retail chains.
- Online Retail:E-commerce platforms fulfill frozen produce orders through specialized cold-chain logistics with temperature-validated last-mile delivery. Amazon Fresh and regional competitors have built dedicated frozen distribution nodes in Texas and the Southeast.
- Specialty Stores:Organic and natural-food retailers stock premium frozen produce lines with certified sourcing claims. These channels command price premiums through storytelling around harvest timing and freezing methodology.
- Wholesale:Broadline distributors like Sysco and US Foods aggregate frozen produce volumes for multi-unit restaurant chains. Wholesale purchasing specifications increasingly mandate electronic traceability documentation under FDA compliance timelines.
Supermarkets anchor current volume. Online retail is where channel expansion concentrates.
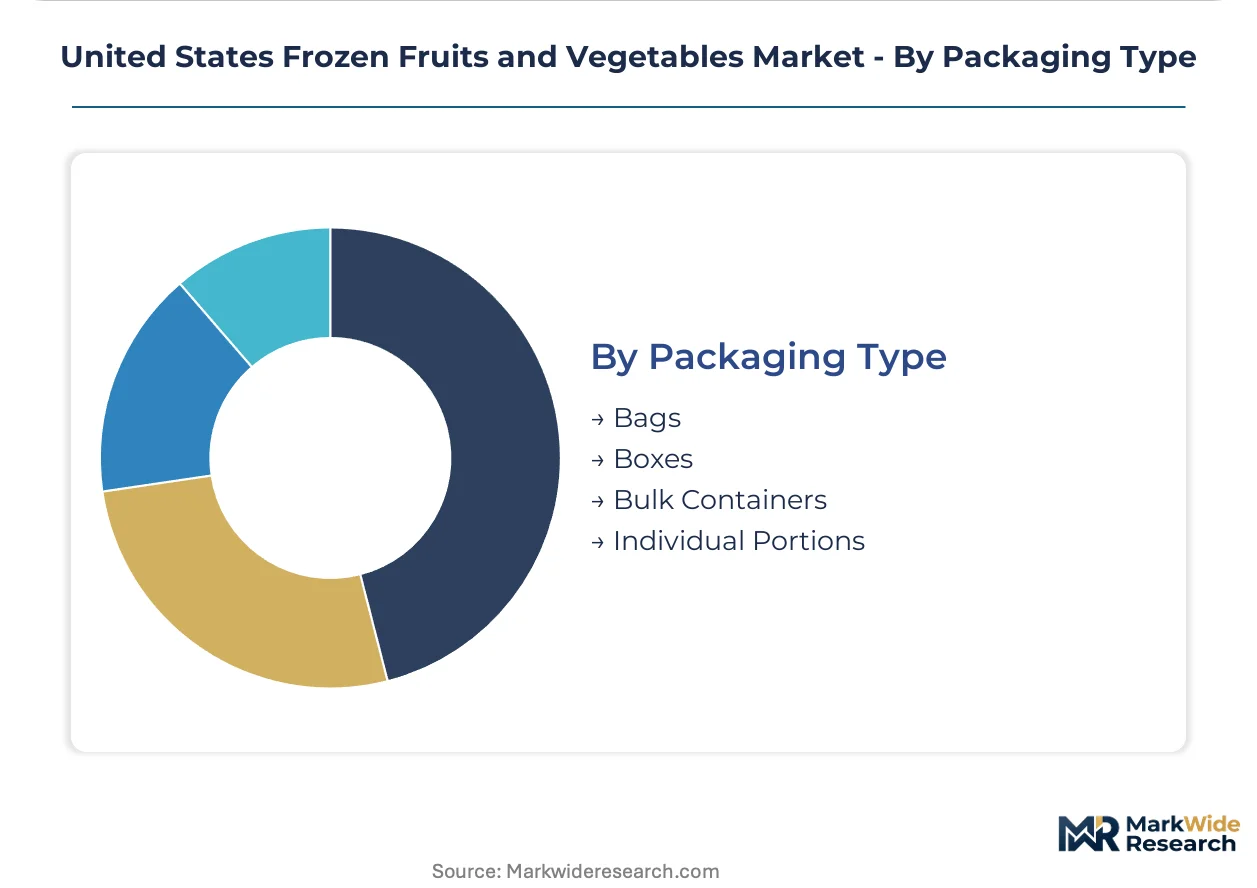
Packaging Type:
Volume scale and handling requirements differentiate formats, with automation compatibility driving specification decisions at the food-service tier.
- Bags:Flexible polyethylene and nylon laminate structures dominate retail frozen vegetables with resealable zipper features. Bagging lines at California freezing facilities run at higher speeds than rigid container alternatives.
- Boxes:Paperboard cartons with polyethylene liners support premium positioning through graphic design flexibility and stackability. Frozen fruit brands use box formats to differentiate from commodity bagged alternatives.
- Bulk Containers:Corrugated totes and poly-lined bins serve institutional food-service accounts with portion-control dispensing systems. Bulk formats minimize per-unit packaging cost for high-throughput operators.
- Individual Portions:Single-serve cups and pouches target meal-kit suppliers and convenience-oriented household segments. Portion control reduces food waste while supporting recipe standardization.
Bags dominate unit volume. Individual portions is where packaging innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley processors command price premiums through four-hour field-to-freezer windows, while Texas and Southeast operators absorb margin compression from longer supply chains and higher logistics costs.
California
Strawberry and spinach freezing facilities cluster within fifty miles of Salinas and Watsonville harvest zones. FDA's Food Traceability Rule mandates electronic documentation for leafy greens, favoring integrated operators with existing ERP systems. The Central Valley corridor anchors national supply rhythms through co-location economics that distant competitors cannot replicate.
Texas
Dallas-Fort Worth distribution hubs serve underpenetrated population growth corridors with frozen produce fulfillment centers. State energy policies raise refrigeration costs for freezing cooperatives, compressing margins relative to California benchmarks. The Interstate 35 corridor attracts cold-chain infrastructure investment from operators seeking Southeast market access.
Idaho
Integrated potato processors control varietal selection for fry and flake applications through backward integration into farming operations. USDA Agricultural Marketing Service grading standards apply to frozen potato products shipped nationwide. The Snake River Plain concentrates ammonia refrigeration expertise among specialized technician workforces nearing retirement.
Florida
Strawberry freezing cooperatives in the Plant City region face disproportionate FDA compliance burdens relative to California's integrated operators. EPA AIM Act refrigerant phase-down deadlines force capital-intensive retrofits of existing freezing tunnels before 2027. The state's strawberry belt lacks the co-location density that protects Central Valley margins.
Pacific Northwest
Specialized blast-freezer technician expertise concentrates among retiring union workforces in potato processing regions. Washington and Oregon freezing facilities supply berry and vegetable volumes to West Coast retail chains. The region's cold-chain infrastructure faces labor scarcity that threatens operational continuity.
United States Frozen Fruits and Vegetables Market Key Industry Players
Heritage-brand conglomerates and specialty produce operators split the market through divergent capital allocation strategies. Consolidation pressure intensifies as FDA compliance costs disproportionately burden mid-sized freezing cooperatives. Three archetypes dominate: integrated agricultural processors with captive supply, diversified packaged-food conglomerates with retail freezer-aisle leverage, and tropical-fruit specialists with food-service portion-control expertise. Competitive moves center on co-location expansion near harvest zones and ERP system upgrades for traceability compliance.
Within the heritage-brand tier, Conagra Brands and General Mills occupy positions shaped by decades of retail shelf-space negotiation. Dole Packaged Foods exemplifies tropical-fruit specialization with food-service distribution reach. JR Simplot Company anchors the integrated-processor archetype through upstream control over Idaho farming operations.
| Leading Market Players |
|---|
| Conagra Brands |
| General Mills |
| Dole Packaged Foods |
| Nestlé USA |
| SunOpta |
| Ardo NV |
| JR Simplot Company |
| Birds Eye Foods |
| Driscoll's |
| Others |
Cost & Logistics Intelligence
California's Central Valley freezing corridor anchors pricing power through four-hour field-to-freezer compression that distant competitors cannot replicate. Co-located processors capture harvest-quality premiums while Texas and Southeast operators absorb logistics-driven margin compression.
Pricing Analysis
Configured-to-order pricing for IQF-certified berries commands substantial premiums over standard block-frozen commodities. Three-tier pricing structure across premium, standard, and economy levels separates branded retail positioning from institutional bulk procurement. Cost compression in economy tiers is intensifying because natural gas volatility disrupts energy hedging strategies for blast-freezing operations. Food-service distributors exhibit highest price sensitivity due to contract-based volume commitments, while specialty retailers absorb premiums for traceability documentation.
Supply Chain Analysis
Upstream feedstock from Salinas spinach and Watsonville strawberry operations flows into integrated freezing facilities within fifty-mile radiuses. The domestic supply chain draws from California, Idaho, and Florida production clusters with heavy reliance on ammonia refrigeration systems, polyethylene packaging laminates, and nitrogen cryogenic inputs. Single-source vulnerability concentrates in specialized blast-freezer technician labor pools nearing retirement in Pacific Northwest potato regions. Distribution runs through broadline distributors, direct-to-restaurant platforms, and retail freezer aisles with temperature-validated last-mile logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as meal-kit ingredient standardization pulls frozen mixed produce into portion-controlled formats with accelerating penetration.
For Market Incumbents: Pre-empt FDA traceability compliance gaps by upgrading ERP systems before enforcement deadlines compress implementation timelines. Secure preferred freezer-aisle placement through category management negotiations with consolidating retail banners. Vertical integration into Idaho farming operations or Central Valley harvest zones protects margin structure against logistics-driven competitors. For New Entrants and Emerging Players: Establish a beachhead in Texas and Southeast distribution corridors where underpenetrated freezing capacity offers population-growth exposure beyond California saturation. Target individual portion packaging formats for meal-kit suppliers seeking recipe-input standardization. Pursue USDA BioPreferred certification for compostable bag materials to capture federal procurement preference. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because FDA compliance costs disproportionately burden mid-sized freezing cooperatives without integrated ERP infrastructure. Acquisition targets include Florida strawberry belt operators facing 2027 refrigerant retrofit deadlines and traceability system overhauls. Watch EPA enforcement intensity on AIM Act HFC phase-downs as inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Texas and Southeast hubs capture population growth beyond California saturation zones. |
| ERP System Modernization | FDA Food Traceability Rule mandates interoperable record-keeping from farm to retail. |
| IQF Technology Certification | Nitrogen-cooled cryogenic systems digitize quality protocols for food-service distributor mandates. |
| Backward Integration into Farming | Idaho potato processors control varietal selection for fry and flake applications. |
| Sustainable Packaging Transition | USDA BioPreferred procurement preference creates first-mover advantage for compostable bag suppliers. |
Research Approach
A standing panel of freezing facility operations managers, food-service procurement directors, retail category buyers, and cold-chain logistics coordinators provided ongoing calibration across the study period. Primary interview data combined with secondary validation from USDA Agricultural Marketing Service grading records, FDA enforcement documentation, EPA AIM Act regulatory filings, and EIA natural gas price series. Bottom-up volume triangulation against top-down value estimates anchored segmentation outputs.
Scenario-bracketing around natural gas price volatility and refrigerant phase-down timelines bounded high-low projections across the analysis window. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and packaging format with regional production hub overlays. CAGRs derived from trend extrapolation with cross-validation against historical frozen produce volume trajectories. Forecast inputs incorporated Henry Hub futures curves and EPA compliance deadline schedules.
Sensitivities concentrate around EPA enforcement intensity on HFC retrofits and FDA traceability rule implementation pacing. Forecasts reflect documented assumptions regarding meal-kit penetration rates and cold-chain infrastructure investment flows. Cross-checking against USDA National Agricultural Statistics Service production benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
United States Guacamole Market