
 Egypt Fruits and Vegetables Market | 2026-2036
Egypt Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Fruits and Vegetables Market Foresight
Organic and export-grade certification tiers is bifurcating the Egypt Fruits and Vegetables Market into parallel value chains. Sekem Group leverages its biodynamic farming protocols to command premium positioning in European organic channels. Juhayna Food Industries anchors large-scale juice and concentrate operations through backward integration into citrus and tomato supply. Delta Food Group competes on frozen and processed vegetable output, sustaining volume contracts with institutional food service buyers.
Egypt Fruits and Vegetables encompass fresh, dried, and processed horticultural products cultivated across irrigated desert reclamation zones and traditional Nile Valley plots, with shelf life, brix levels, and pesticide residue thresholds determining export eligibility. Fresh fruits and fresh vegetables dominate tonnage throughput, though margin pools concentrate in processed vegetables where pasteurization and IQF freezing extend value capture. Dried fruits represent the fastest-growing product type, driven by raisin and date exports to Gulf and European markets where reduced moisture content slashes freight costs per unit of nutrition.
Egypt's Ministry of Agriculture and Land Reclamation sets phytosanitary standards for export eligibility, while the Food Safety Authority enforces maximum residue limits aligned with EU Regulation 396/2005 to preserve market access. The Agricultural Export Council coordinates compliance training and cold chain certification for smallholder cooperatives seeking European retail contracts. Stakeholders must monitor groundwater allocation permits and salinity thresholds, as Nile water scarcity pressures the irrigation infrastructure that underpins both yield stability and export-grade consistency.
Market Dynamics
Groundwater salinity intrusion and Nile water scarcity are forcing Egyptian growers to abandon flood irrigation for precision systems, while EU phytosanitary enforcement tightens export eligibility thresholds faster than smallholder compliance capacity can adapt.
Growth Catalysts
- EU Regulation 396/2005 alignment:The Food Safety Authority's residue limit enforcement preserves European retail channel access for certified Egyptian exporters.
- Drip irrigation subsidies:Agricultural modernization programs accelerate desert reclamation zone productivity through subsidized precision water infrastructure deployment.
- Food service procurement:Cairo and Alexandria institutional buyers now mandate certified produce traceability, pulling farm-level standards upward.
Market Restraints
- Fertilizer import dependency:Egyptian growers face input cost volatility tied to global urea and phosphate supply disruptions.
- Groundwater salinity thresholds:Nile Delta aquifer degradation threatens yield stability in the corridor that supplies both domestic retail and European export channels.
- Cold chain fragmentation:Post-harvest loss concentrates in smallholder cooperatives lacking continuous refrigeration from farm gate to port.
Strategic Opportunities
- New Valley Governorate expansion:Underpenetrated desert reclamation zones offer untapped acreage for export-grade citrus and table grape cultivation.
- Biodynamic certification convergence:Organic and Demeter standards integration opens premium European channel positioning beyond conventional organic tiers.
- Direct-to-retail digitization:Blockchain-enabled traceability platforms allow producer cooperatives to bypass traditional aggregator markups.
Industry Challenges
- Phytosanitary certification timelines:Smallholder cooperatives struggle with Agricultural Export Council compliance training duration and documentation complexity.
- Cold chain capex intensity:IQF freezing and controlled atmosphere storage require capital deployment beyond most mid-scale operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Fruits and Vegetables Market |
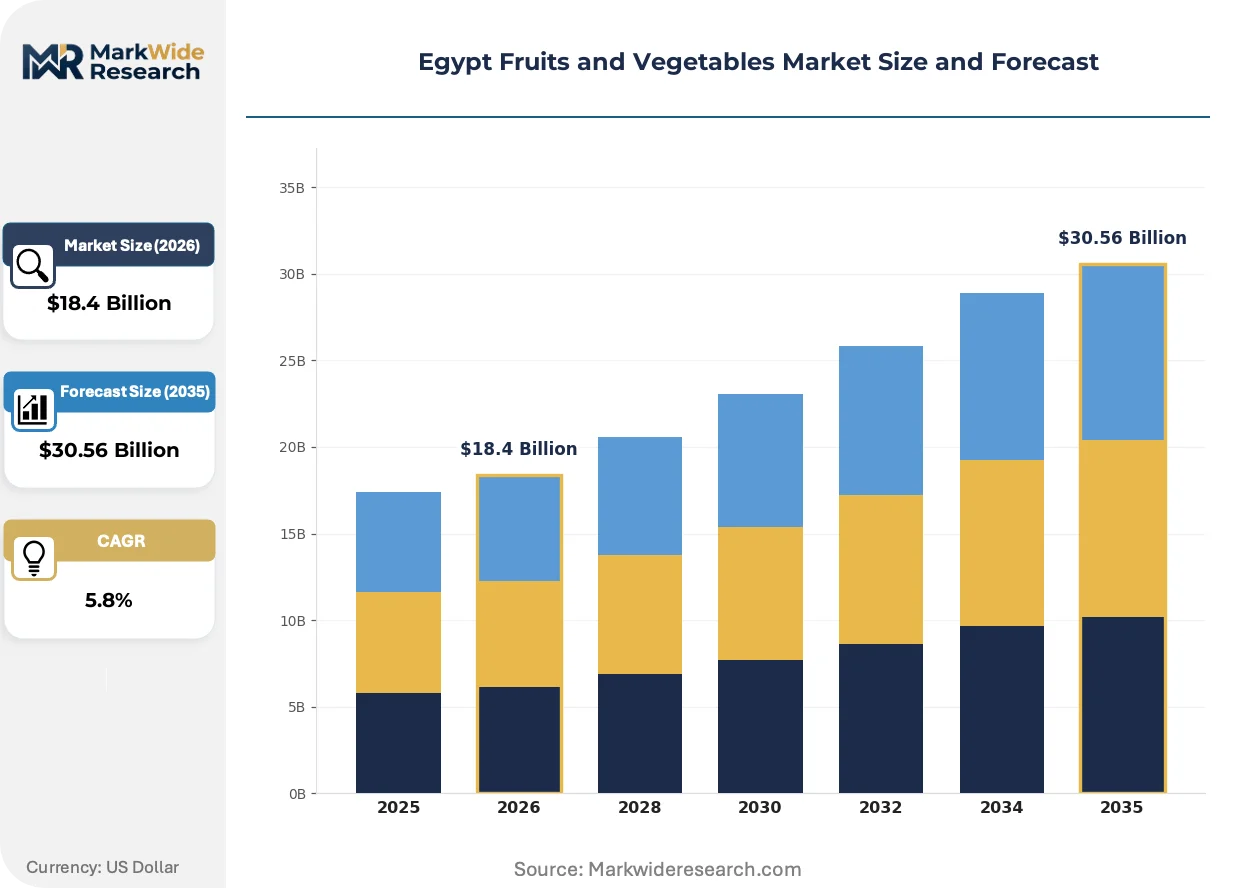
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fruits, Fresh Vegetables, Dried Fruits, Processed Vegetables Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesalers End User: Households, Restaurants, Food Service, Exporters Sales Channel: Direct Sales, E-commerce, Bulk Sales, Traditional Retail |
| Companies Covered | Egyptian General Authority for Exhibitions and Conferences, Delta Food Group, El Eman, Arabian Food Corporation, Juhayna Food Industries, Agricultural Export Council, Farm Frites Egypt, Sekem Group, Egyptian Commercial Service, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Fruits and Vegetables Market Shifts & Advancements
Biodynamic farming protocols and blockchain traceability systems are converging to create dual-tier value chains that separate premium export-grade producers from conventional commodity suppliers.
Solar-powered drip irrigation arrays are displacing diesel-powered pumping stations across the Western Desert reclamation zones. Large-scale tomato and citrus operators in Minya and Beni Suef Governorates are deploying photovoltaic-fed precision water systems at commercial scale. This technology is displacing fuel-dependent irrigation economics while reducing operational cost volatility for export-oriented growers.
The Agricultural Export Council's cold chain certification mandate is reshaping post-harvest infrastructure investment priorities. Compliance training and equipment standards now condition European retail contract eligibility for smallholder cooperatives. Nile Delta processing clusters are responding with consolidated pre-cooling facility construction to serve dispersed farm suppliers.
Hypermarket private label procurement is consolidating buyer power around certified traceability requirements. Carrefour and Spinneys Egypt now specify lot-level digital tracking for fresh produce categories, displacing traditional wholesale market sourcing for premium tiers. This concentration is most visible in Cairo's retail corridor, where food service and retail procurement standards have effectively merged.
Egypt Fruits and Vegetables Market Segmentation
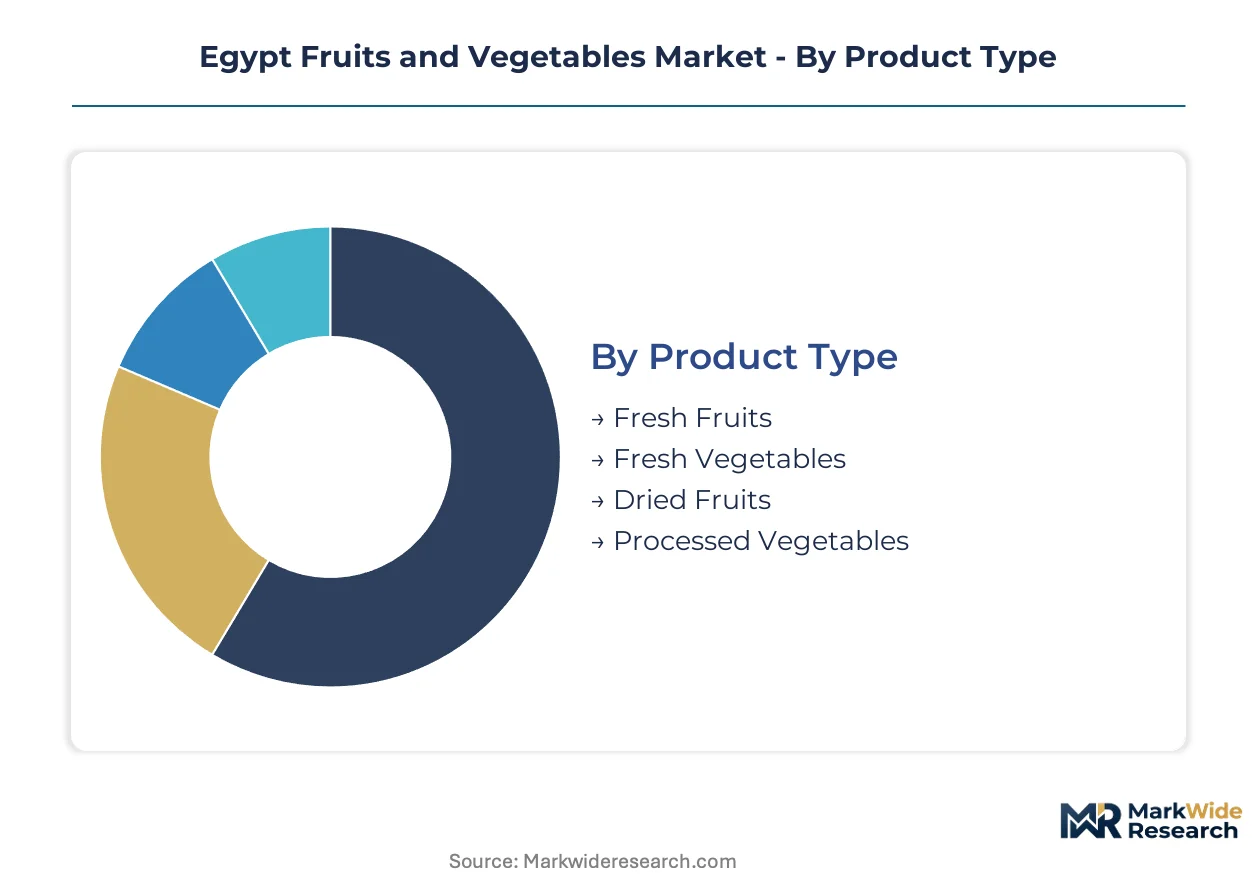
Channel configuration in Egypt's produce market determines pricing power and margin capture. Certification requirements and cold chain access create divergent pathways for each segment, with export-grade and domestic-retail tiers operating on separate commercial logics.
Product Type:
Fresh produce dominates Cairo and Alexandria retail corridors, while processed and dried categories concentrate margin in export-oriented supply chains.
- Fresh Fruits:Citrus, table grapes, and stone fruits move through supermarket and food service channels where EU phytosanitary compliance governs eligibility. Cairo hypermarkets now mandate lot-level traceability for premium citrus varieties.
- Fresh Vegetables:Tomatoes, cucumbers, and leafy greens supply domestic retail and institutional kitchens across the Nile Delta corridor. Cold chain fragmentation elevates post-harvest loss rates in smallholder-dominated supply.
- Dried Fruits:Raisins and dates for Gulf and European markets where moisture reduction cuts freight costs per nutritional unit.
- Processed Vegetables:Pasteurized concentrates and IQF frozen output for institutional buyers and export channels.
By volume, Fresh Vegetables leads. By growth pace, Dried Fruits is ahead.
Distribution Channel:
Certification tiers split procurement pathways, with traceability-mandated channels capturing premium pricing while traditional wholesale handles commodity volume.
- Supermarkets:Carrefour and Spinneys Egypt enforce digital lot-tracking for fresh categories, displacing wholesale sourcing for certified tiers. Private label concentration reshapes supplier power dynamics.
- Local Markets:Traditional wholesale bazaars in Cairo and Alexandria handle uncertified produce where price competition suppresses margins. Smallholder cooperatives lack cold chain continuity to reach alternative channels.
- Online Retail:Digital platforms serving Greater Cairo households with scheduled delivery slots for packaged produce.
- Wholesalers:Aggregator networks supplying restaurants and institutional kitchens across urban corridors.
Supermarkets command the steepest margin expansion trajectory. Local Markets retain dominant volume share.
End User:
Procurement standards are converging between food service and retail segments as traceability mandates spread across buyer categories.
- Households:Urban consumers in Cairo and Alexandria driving certified produce demand through supermarket and online channels.
- Restaurants:Alexandria seafood and Cairo hotel operators mandating documented supply chain provenance for menu positioning.
- Food Service:Institutional caterers and airline suppliers requiring Agricultural Export Council cold chain certification for contract eligibility.
- Exporters:European retail channel access conditioned on Food Safety Authority residue limit compliance aligned with EU Regulation 396/2005.
Exporters capture the highest unit margins. Households represent the largest absolute demand pool.
Sales Channel:
Digital infrastructure and bulk contracting are displacing traditional spot-market transactions for certified produce tiers.
- Direct Sales:Producer cooperatives in New Valley Governorate bypassing aggregator markups through blockchain-enabled traceability platforms.
- E-commerce:Scheduled delivery platforms serving Greater Cairo with pre-packaged fresh and dried categories.
- Bulk Sales:Volume contracts between Delta processing clusters and institutional food service buyers for frozen and pasteurized output.
- Traditional Retail:Independent grocers and corner stores handling uncertified produce in dense urban neighborhoods.
Traditional Retail maintains volume dominance. Direct Sales shows the most rapid channel-share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity concentrates in traditional wholesale bazaars across the Nile Delta, while premium-tier buyers in Cairo's hypermarket corridor absorb traceability premiums without volume elasticity.
Nile Delta Corridor
Smallholder cooperatives supply tomatoes, cucumbers, and leafy greens through fragmented cold chains where post-harvest loss erodes margins. The Food Safety Authority enforces residue limits aligned with EU Regulation 396/2005, conditioning export eligibility. Alexandria processing clusters consolidate pre-cooling infrastructure to serve dispersed farm suppliers.
Greater Cairo
Urban households and institutional food service operators mandate certified produce traceability for contract eligibility. Carrefour and Spinneys Egypt specify lot-level digital tracking, displacing wholesale sourcing for premium tiers. Cairo's retail corridor merges food service and retail procurement standards.
New Valley Governorate
Underpenetrated desert reclamation zones attract export-grade citrus and table grape cultivation. Drip irrigation subsidies from agricultural modernization programs accelerate productivity in photovoltaic-fed precision water systems. Producer cooperatives bypass aggregator markups through blockchain-enabled traceability platforms.
Alexandria
Seafood restaurants and hotel operators drive documented supply chain provenance requirements for menu positioning. The Agricultural Export Council coordinates compliance training and cold chain certification for European retail contract access. Alexandria anchors the export gateway infrastructure serving European channels.
Minya and Beni Suef Governorates
Large-scale tomato and citrus operators deploy solar-powered drip irrigation arrays displacing diesel-powered pumping stations. Groundwater allocation permits and salinity thresholds pressure yield stability. Processing clusters concentrate pasteurized concentrate and IQF frozen output for institutional buyers.
Egypt Fruits and Vegetables Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across certification tiers. The market structures around three strategic groups: biodynamic-certified premium exporters, large-scale integrated processors, and cooperative-based smallholder networks. Consolidation concentrates in processed and frozen categories where capital requirements exclude mid-scale entrants. Dominant competitive moves include backward integration into captive supply and cold chain infrastructure expansion.
Within the premium-certified tier, Sekem Group exemplifies biodynamic positioning for European organic channels, while Juhayna Food Industries anchors large-scale juice and concentrate operations through upstream control over citrus and tomato supply. Delta Food Group occupies the processed vegetable segment with frozen output volume contracts. These three represent distinct archetypes: certification-driven premium positioning, scale-driven backward integration, and institutional volume contracting.
| Leading Market Players |
|---|
| Egyptian General Authority for Exhibitions and Conferences |
| Delta Food Group |
| El Eman |
| Arabian Food Corporation |
| Juhayna Food Industries |
| Agricultural Export Council |
| Farm Frites Egypt |
| Sekem Group |
| Egyptian Commercial Service |
| Others |
Supply & Pricing Matrix
Photovoltaic-fed drip irrigation displacing diesel-powered pumping across Egypt's Western Desert reclamation zones simultaneously redraws farm-gate supply geography and compresses operational cost structures for export-grade citrus and table grape operators.
Pricing Analysis
After-sales service contracts for cold chain maintenance and Agricultural Export Council compliance training now generate lifetime value exceeding initial produce sales for certified tier suppliers. Pricing stratifies across biodynamic premium, EU-certified organic, and conventional commodity tiers, with Food Safety Authority residue limit alignment as the primary differentiation driver. Cost compression in the conventional tier intensifies because groundwater salinity intrusion erodes yields in Nile Delta strongholds. Institutional food service buyers in Cairo exhibit the least price sensitivity, while traditional wholesale bazaar operators absorb volume without traceability premiums.
Supply Chain Analysis
Cold chain fragmentation at the farm-gate-to-port transition chokes margin capture for smallholder cooperatives lacking continuous refrigeration infrastructure. Egypt draws concentrated supply from domestic Nile Delta plots and New Valley Governorate desert reclamation zones, with supplementary date and raisin inputs from Tunisia and Saudi Arabia. Fertilizer imports—urea and phosphate—rest on volatile global commodity markets. Single-source vulnerability concentrates in groundwater allocation permits where salinity thresholds threaten yield stability. Distribution runs through Alexandria's export gateway infrastructure for European channels and Cairo hypermarket corridors for domestic retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain as-a-service offerings and blockchain traceability platform subscriptions expand faster than hardware sales of pre-cooling equipment and IQF freezing infrastructure, reframing this market around recurring-revenue service layers.
For Market Incumbents: Fortify backward integration into captive citrus and tomato supply to defend against Juhayna Food Industries' scale advantages in pasteurized concentrate output. Expand controlled-atmosphere storage capacity in Alexandria processing clusters to lock in smallholder cooperative volumes before competitor consolidation. EU Regulation 396/2005 alignment investments anchor defensive positioning. For New Entrants and Emerging Players: Agricultural Export Council cold chain certification fast-tracks open European retail contract access for New Valley Governorate producer cooperatives bypassing traditional aggregator markups. Target underpenetrated desert reclamation acreage for export-grade table grape cultivation where drip irrigation subsidies compress capital requirements. Deploy direct-to-retail digitization via blockchain-enabled traceability platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale processing operators lacking biodynamic certification tiers for European organic channel premium positioning. Five-to-ten year viability hinges on groundwater allocation permit security and salinity management infrastructure deployment. Acquisition targets should demonstrate existing Agricultural Export Council compliance training completion. The signal to watch is Food Safety Authority enforcement intensity for EU Regulation 396/2005 residue limit alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Investment | Demeter and organic tier convergence unlocks premium European retail channel positioning beyond conventional organic. |
| Backward Integration into Citrus Supply | Captive tomato and citrus orchards secure raw material cost stability for pasteurized concentrate and juice operations. |
| Cold Chain Infrastructure Expansion | Consolidated pre-cooling facilities in Nile Delta processing clusters reduce post-harvest loss for smallholder cooperatives. |
| Blockchain Traceability Platform Deployment | Lot-level digital tracking satisfies Carrefour and Spinneys Egypt procurement mandates for premium fresh categories. |
| Photovoltaic Irrigation Array Installation | Solar-powered drip systems displace diesel pumping economics across Western Desert reclamation zones. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs export records, Agricultural Export Council compliance documentation, and Food Safety Authority regulatory filings. Primary interviews engaged farm operators in New Valley Governorate, cold chain logistics coordinators at Alexandria processing clusters, procurement managers at Cairo hypermarket chains, and Agricultural Export Council training program administrators. Secondary validation drew from EU phytosanitary import databases, Nile Delta groundwater monitoring reports, and desert reclamation zone productivity assessments. Bottom-up acreage and yield estimates triangulate against top-down export value flows.
Segmentation dimensions modeled span product type (fresh fruits, fresh vegetables, dried fruits, processed vegetables), distribution channel (supermarkets, local markets, online retail, wholesalers), and end user (households, restaurants, food service, exporters). Geographic clustering follows Nile Delta corridor, Greater Cairo, New Valley Governorate, Alexandria, and Minya-Beni Suef Governorates. CAGRs derive from trend extrapolation of export certification growth rates and domestic retail modernization trajectories across the projection horizon. Forecast inputs incorporate drip irrigation subsidy program uptake and EU phytosanitary enforcement intensity.
Underlying assumptions cover sustained EU market access under Regulation 396/2005 alignment, continued drip irrigation subsidy program funding, and stable groundwater allocation permit availability, with deviation risk concentrated in Nile water scarcity escalation and fertilizer import cost volatility. Practitioners should keep alternative scenarios live as Food Safety Authority enforcement protocols and European retail traceability mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market