
 Jicama Market | 2026-2036
Jicama Market Size, Share, and Industry Trends Forecast 2026-2036
Jicama Market Outlook
Specialty produce distribution is tilting toward direct-to-retailer contracts as grocers tighten quality specifications and shorten replenishment cycles. Frieda's Inc. leverages decades of exotic produce merchandising to sustain shelf positioning in premium supermarket chains. Albert's Organics anchors organic certification requirements across its procurement network, while Dole Food Company, Inc. competes through scale advantages in tropical and subtropical sourcing corridors.
Jicama is a tuberous root vegetable derived from Pachyrhizus erosus, characterized by crisp white flesh containing approximately 86-90% water content, 4-5% dietary fiber, and minimal fat, serving primarily as a raw or minimally processed ingredient in food service and packaged goods applications. Fresh Jicama dominates volume throughput due to its versatility across snacking and salad applications, though Jicama Noodles represent the fastest-growing product type as grain-free pasta alternatives gain traction in health-conscious retail channels. Margin pools concentrate in Jicama Powder, where dehydration processing creates value-added positioning for supplement and functional food manufacturers.
The USDA's Agricultural Marketing Service enforces grade standards for root vegetables entering interstate commerce, while FDA oversight under the Food Safety Modernization Act mandates preventive controls for fresh-cut processing operations. Mexico's SENASICA phytosanitary certification requirements shape export eligibility for cross-border supply into the United States. Stakeholders must monitor evolving clean-label enforcement thresholds and climate-driven harvest volatility as dual determinants of procurement strategy.
Market Dynamics
Clean-label snacking preferences are compressing replenishment cycles and forcing direct-to-retailer contracting as grocers tighten phytosanitary specifications for root vegetable sourcing corridors.
Growth Catalysts
- Latin American Cuisine Integration:Food service operators in the United States are expanding jicama placement across salad and taco applications, pulling volume through specialty produce distributors.
- FSMA Preventive Controls:FDA-mandated hazard analysis for fresh-cut processing is accelerating consolidation toward certified packers with documented cold-chain protocols.
- Grain-Free Pasta Alternatives:Spiralized jicama noodles are capturing shelf space in refrigerated produce sections as ketogenic and paleo diet adherence spreads.
Market Restraints
- Input Cost Volatility:Diesel and refrigerated transport rates fluctuate with crude oil markets, compressing margins on cross-border shipments from Mexican growing regions.
- Phytosanitary Certification Friction:SENASICA export protocols create inspection bottlenecks at Nogales and McAllen border crossings, delaying just-in-time retail replenishment.
- Perishability Constraints:High water content limits shelf life to 2-4 weeks post-harvest, restricting inventory positioning distant from processing facilities.
Strategic Opportunities
- Dehydration Value Addition:Jicama powder production for supplement and functional food manufacturers commands premium positioning in nutraceutical channels.
- Organic Certification Expansion:USDA National Organic Program compliance opens placement in Albert's Organics and similar procurement networks with strict input documentation.
- Direct-to-Consumer Subscriptions:Meal-kit platforms and specialty produce boxes represent underpenetrated channels for pre-cut jicama formats.
Industry Challenges
- Harvest Labor Availability:Seasonal field crews for tuber extraction remain scarce in Jalisco and Puebla growing regions, constraining peak-season volume throughput.
- Integrated Pest Management Compliance:SENASICA-mandated pest monitoring systems require capital investment in pheromone trapping and field scouting infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jicama Market |
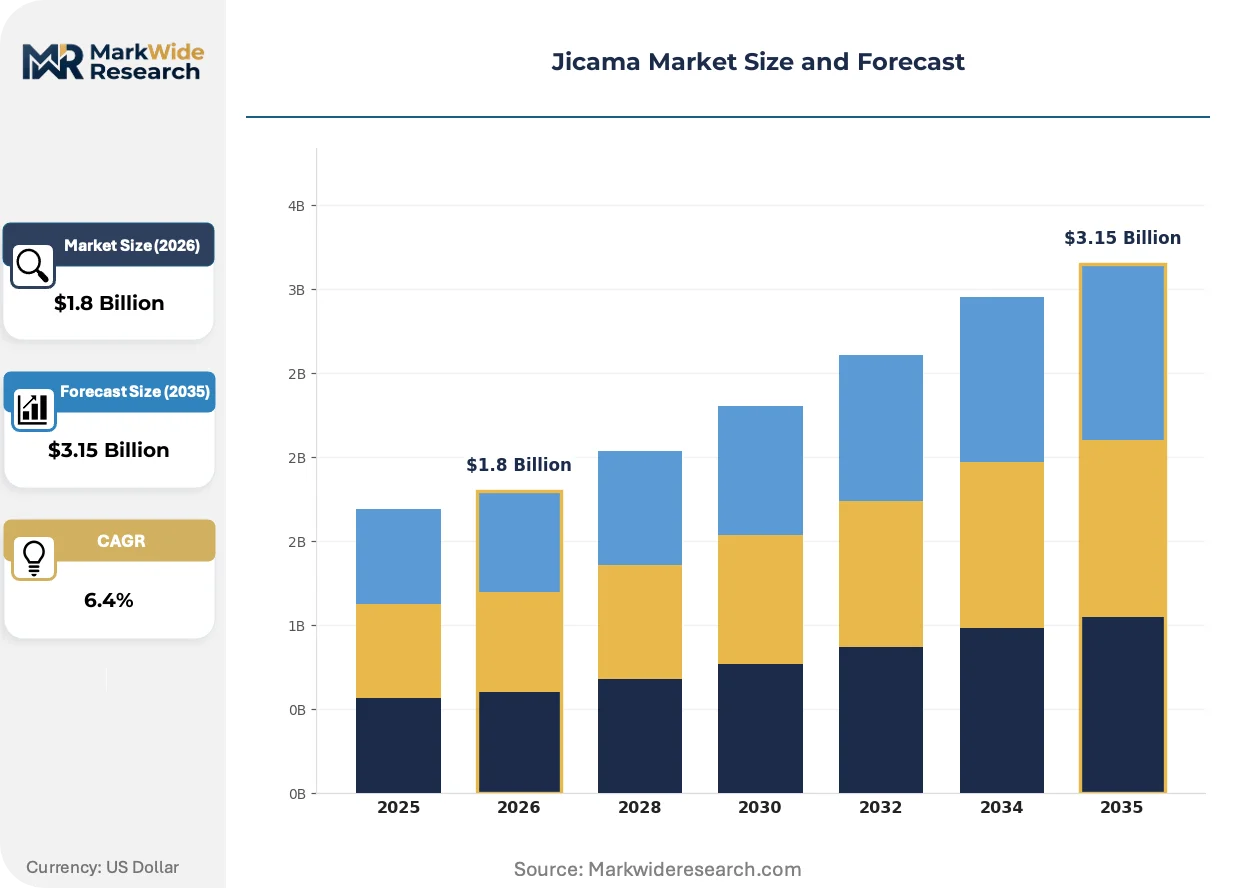
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Jicama, Jicama Chips, Jicama Powder, Jicama Noodles End User: Retail, Food Service, Food Processing, Health Enthusiasts Application: Snacking, Salads, Cooking, Smoothies Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | Albert's Organics, Kitazawa Seed Company, United Produce, Vega Produce, Frieda's Inc., Asian Veggies Inc., Eurofrutta Ltd., Fine Food Specialist Ltd., Dole Food Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jicama Market Strategic Shifts
Processing technology and distribution configuration are restructuring how jicama moves from field to finished product, with dehydration and fresh-cut operations diverging toward distinct equipment and buyer relationships.
Modified atmosphere packaging is migrating from passive film technologies to active oxygen-scavenging systems for fresh-cut jicama strips. Retail deli and grab-and-go salad manufacturers are adopting these systems to extend color stability from 5 to 12 days. The shift is compressing spoilage allowances and enabling longer distribution radii from centralized processing hubs.
USDA grade standards for root vegetables are tightening inspection protocols for external defects and internal discoloration. Interstate shippers now face rejection penalties for consignments falling below U.S. Fancy grade thresholds. Fresh jicama consignments entering Chicago and New York terminal markets bear the highest compliance burden, driving pre-sorting investment at Mexican packing sheds.
Health-conscious buyers are rotating toward single-ingredient snack formats that displace multi-component processed alternatives. Pre-cut jicama sticks in portable portion packs are capturing vending and convenience channel placements previously held by puffed grain products. This pattern concentrates most visibly in California and Texas retail environments with high Hispanic population density and established produce snacking habits.
Jicama Market Segmentation
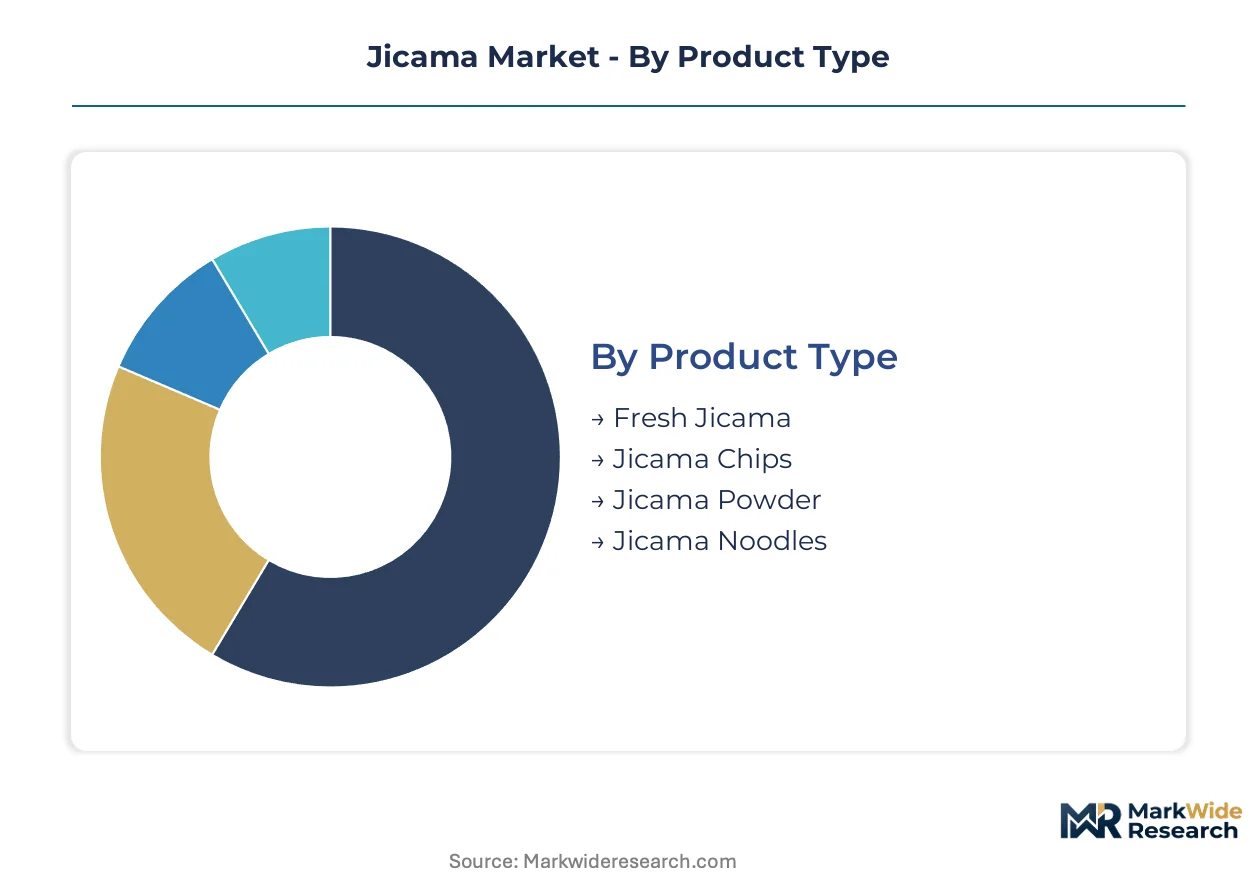
Jicama's commercial trajectory splits across four structural dimensions that determine procurement patterns and margin capture. Product format dictates processing investment and shelf-life economics. End-user concentration shapes packaging specifications and replenishment cadence. Application context drives formulation requirements for food service versus retail channels. Distribution configuration determines cold-chain intensity and certification burden.
Product Type:
Maturity spreads unevenly across formats, with raw commodity forms anchoring volume while processed derivatives capture value-added positioning.
- Fresh Jicama:The unprocessed tuber retains 86-90% water content and delivers 2-4 weeks post-harvest shelf life under refrigerated conditions. Supermarket produce departments in Texas and California pull the highest throughput volumes where Latin American cuisine penetration is deepest.
- Jicama Chips:Thin-sliced dehydration produces shelf-stable snacking formats with extended distribution radii. Albert's Organics and similar premium retailers are expanding placement of clean-label chip alternatives as multi-component processed snacks face displacement.
- Jicama Powder:Complete dehydration creates functional food inputs for supplement manufacturers. Nutraceutical channels command premium positioning through documented fiber content and low glycemic index properties.
- Jicama Noodles:Spiralized fresh-cut formats are expanding most quickly in refrigerated produce sections. Ketogenic and paleo diet adherence in United States coastal markets is accelerating retail placement as grain-free pasta alternatives.
Fresh Jicama retains volume leadership; Jicama Noodles holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity procurement from premium positioning across buyer categories.
- Retail:Grocery chains dominate volume throughput with tightening phytosanitary specifications and shortened replenishment cycles. Direct-to-retailer contracting is displacing traditional wholesale intermediation as quality documentation requirements intensify.
- Food Service:Restaurant and institutional operators demand consistent sizing and peel-ready formats for labor efficiency. Taco and salad applications in United States food service are expanding jicama placement through specialty produce distributors.
- Food Processing:Manufacturers of packaged goods and beverage formulations require standardized brix and fiber specifications. Jicama powder procurement for functional food integration is concentrating among certified organic processors.
- Health Enthusiasts:Direct-to-consumer subscription boxes and meal-kit platforms represent emerging channels for pre-cut formats. This segment exhibits highest price elasticity and certification sensitivity across all buyer categories.
Retail commands absolute volume; Health Enthusiasts are climbing the fastest as clean-label snacking preferences spread.
Application:
Application context determines preparation state and packaging configuration from field to final use.
- Snacking:Pre-cut sticks and chips in portable portion packs are capturing vending and convenience channel placements. California and Texas retail environments with established produce snacking habits show highest penetration.
- Salads:Julienned and spiralized formats for food service and retail deli applications require modified atmosphere packaging. Active oxygen-scavenging systems are extending color stability from 5 to 12 days in grab-and-go manufacturing.
- Cooking:Stir-fry and roasting applications in home kitchens and food service tolerate broader size grading. This application sustains demand for whole tuber formats with minimal processing.
- Smoothies:Frozen and fresh-cut jicama for beverage formulations requires documented microbial compliance. Juice bar chains and home blending trends are pulling volume through frozen produce distributors.
Snacking anchors current volume; Smoothies are gaining share fastest as functional beverage formats proliferate.
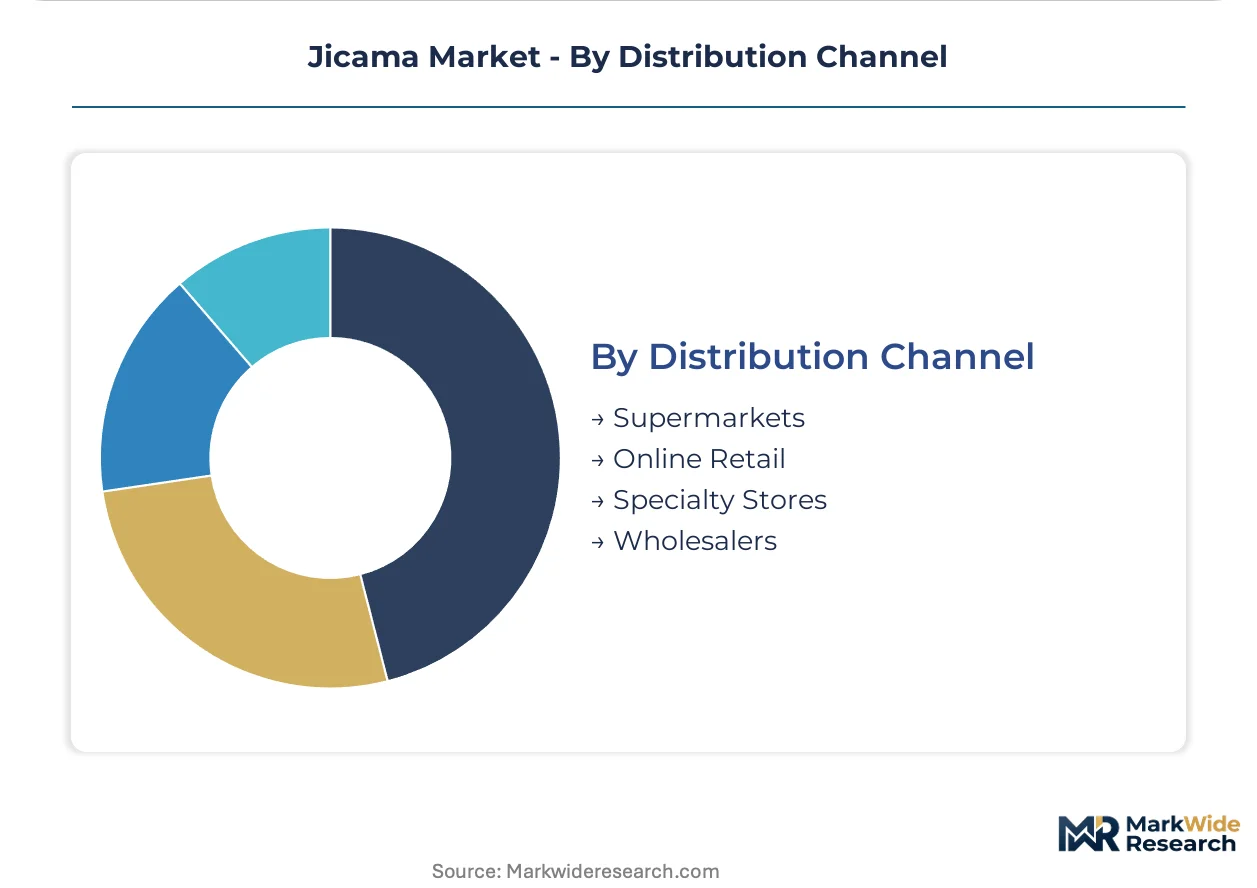
Distribution Channel:
Channel configuration determines cold-chain intensity, certification documentation, and margin structure.
- Supermarkets:Premium produce sections in United States chains are tightening grade standards toward U.S. Fancy thresholds. Pre-sorting investment at Mexican packing sheds is rising to avoid rejection penalties at Chicago and New York terminal markets.
- Online Retail:E-commerce platforms for specialty produce require robust packaging for last-mile delivery. Subscription box operators are piloting pre-cut jicama formats with insulated containment and ice-pack protocols.
- Specialty Stores:Independent grocers and ethnic food retailers sustain placement of whole tuber formats. Hispanic population concentration in Southwestern United States supports dedicated produce sections with established jicama merchandising.
- Wholesalers:Traditional intermediation faces compression as direct contracting expands. Remaining wholesale volume concentrates in food service redistribution and independent retail supply.
Supermarkets retain volume leadership; Online Retail holds the steepest expansion trajectory as direct-to-consumer formats mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA phytosanitary incentives and FDA modernization mandates are reshaping cross-border sourcing corridors for tuberous root vegetables, concentrating investment in certified cold-chain infrastructure near major population centers.
United States
Latin American cuisine penetration and ketogenic diet adherence in Texas and California are accelerating retail placement of fresh-cut formats. The FDA's Food Safety Modernization Act preventive controls mandate documented hazard analysis for interstate fresh-cut shipments. Chicago and New York terminal markets enforce the strictest USDA grade standard compliance, driving pre-sorting investment at Mexican packing sheds serving these corridors.
Mexico
Jalisco and Puebla growing regions supply the bulk of North American fresh jicama volume through seasonal field operations. SENASICA phytosanitary certification requirements create inspection bottlenecks at Nogales and McAllen border crossings, delaying just-in-time replenishment. Mexico City Metro anchors domestic processing capacity for dehydration value-added formats bound for export markets.
Canada
Health Canada oversight under the Safe Food for Canadians Regulations governs import eligibility for fresh produce entering Ontario and Quebec distribution networks. Toronto and Vancouver specialty grocers are expanding placement of organic-certified tuber formats as clean-label snacking preferences spread. Health Canada and PMRA coordinated enforcement is tightening residue monitoring protocols for root vegetable consignments.
Germany
EFSA novel food approval pathways and EU organic certification requirements shape market access for jicama powder in functional food applications. Bavaria and North Rhine-Westphalia host the densest concentrations of nutraceutical formulators seeking low-glycemic index ingredients. ECHA REACH compliance documentation is becoming a procurement prerequisite for dehydrated formats entering German supplement manufacturing channels.
United Kingdom
London's ethnic food retail corridors sustain demand for whole tuber formats serving established Hispanic and Southeast Asian communities. The FSA's import notification system enforces documentary compliance for fresh produce entering UK ports. Greater Manchester and Birmingham distribution hubs are piloting modified atmosphere packaging protocols for pre-cut formats targeting meal-kit platforms.
Jicama Market Competitive Environment
On the supply side, the industry is bifurcated between scale-driven tropical produce conglomerates and specialized exotic vegetable merchandisers with deep retail relationships. Three strategic archetypes dominate: certified organic procurement networks, direct-to-retailer contracting specialists, and dehydration value-added processors. Competitive moves concentrate on backward integration into Mexican growing regions and portfolio diversification into grain-free pasta alternatives.
Among specialty produce merchandisers, Frieda's Inc. and Albert's Organics exemplify the premium-tier positioning archetype, while Dole Food Company, Inc. occupies the scale-driven vector with established tropical sourcing infrastructure. These three entities represent distinct competitive postures without implying specific strategic coordination or market share claims.
| Leading Market Players |
|---|
| Albert's Organics |
| Kitazawa Seed Company |
| United Produce |
| Vega Produce |
| Frieda's Inc. |
| Asian Veggies Inc. |
| Eurofrutta Ltd. |
| Fine Food Specialist Ltd. |
| Dole Food Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Jalisco and Puebla growing regions anchor North American jicama supply, and their seasonal labor constraints directly compress downstream margin pools for cross-border distributors serving United States retail chains.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers in this market. USDA National Organic Program compliance and SENASICA phytosanitary certification separate Albert's Organics procurement networks from conventional wholesale channels. Cost compression in standard-grade fresh tubers is intensifying because diesel and refrigerated transport rates track crude oil volatility. Health enthusiasts exhibit highest price elasticity, while food service operators show lowest sensitivity due to labor-cost substitution value.
Supply Chain Analysis
SENASICA export protocols function as de facto restricted-technology controls, limiting eligible flows through Nogales and McAllen border crossings to certified packers with documented cold-chain infrastructure. Mexico supplies raw tuber volume, the United States anchors fresh-cut processing capacity, and Canada draws from both for organic-certified distribution. Inputs hinge on seasonal field crews for harvest, pheromone trapping systems for pest compliance, and modified atmosphere packaging film for retail shelf-life extension. Single-source vulnerability concentrates in Jalisco growing regions during peak season. Distribution runs through direct-to-retailer contracting with specialty produce distributors serving food service redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
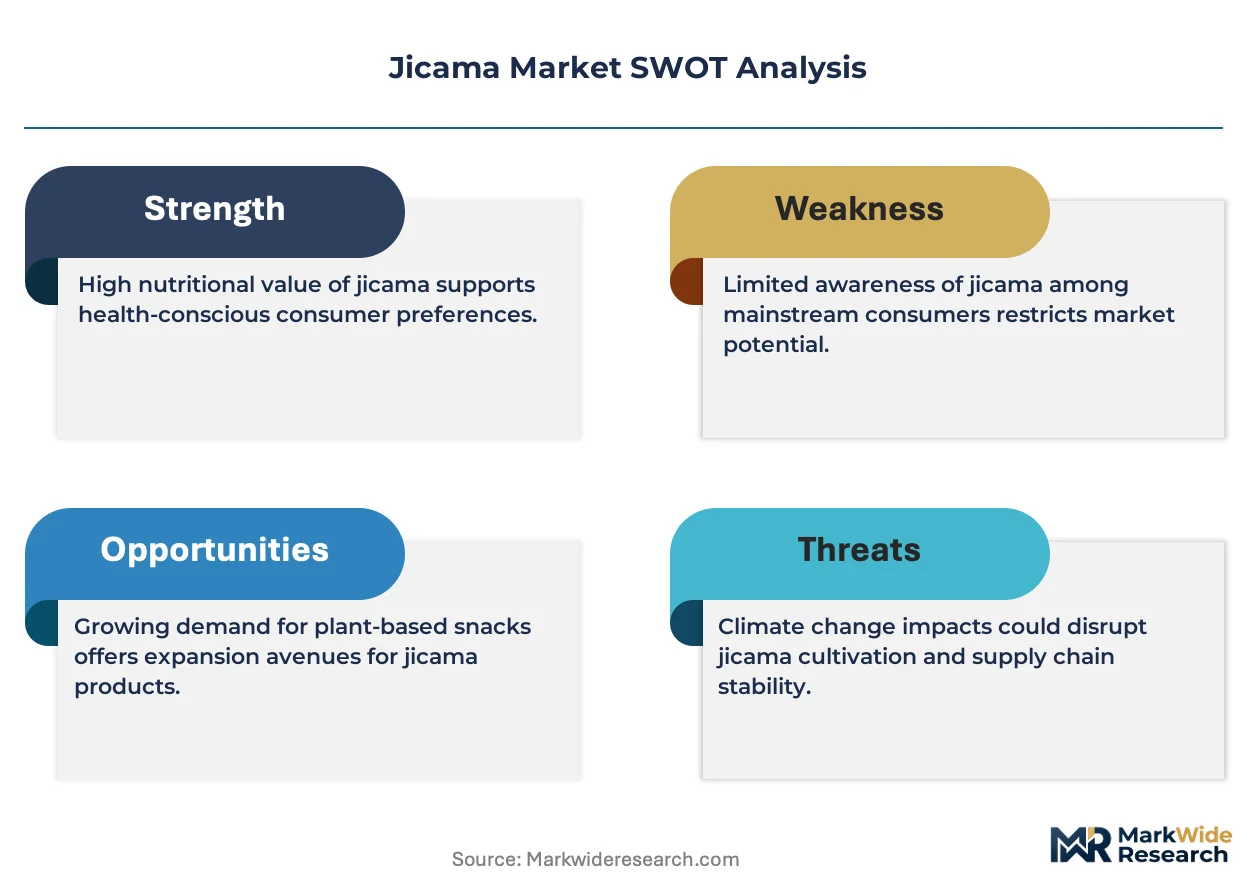
Jicama's commercial fragmentation creates entry niches as clean-label snacking preferences splinter demand across organic, pre-cut, and single-ingredient formats that incumbent scale players underserve.
For Market Incumbents: Build certification moats through backward integration into Mexican growing regions with captive SENASICA-compliant packing infrastructure. Secure direct-to-retailer contracts with documented cold-chain protocols to lock out wholesale intermediaries. Defend against dehydration value-added specialists by expanding jicama powder production capacity in Mexico City Metro processing hubs. For New Entrants and Emerging Players: Canada and Germany represent geographic underpenetration with fastest regulatory pathway expansion for organic-certified and novel food formats. Target Health Canada import eligibility and EFSA novel food approval corridors before incumbent scale advantages solidify. Enter through meal-kit platform partnerships for pre-cut formats with insulated last-mile delivery protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certified organic processors with multi-year retail chain contracts. Long-term viability centers on climate-resilient sourcing diversification and functional food ingredient positioning. Watch SENASICA inspection bottleneck resolution at border crossings as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mexican Growing Regions | Captive SENASICA-compliant supply secures border-crossing priority and quality documentation. |
| Organic Certification Expansion | USDA National Organic Program compliance opens Albert's Organics and premium retail placement. |
| Dehydration Value-Added Capacity | Jicama powder production commands nutraceutical channel premium with documented fiber content. |
| Direct-to-Consumer Subscription Launch | Meal-kit platforms represent underpenetrated channel for pre-cut formats with insulation protocols. |
| Modified Atmosphere Packaging Upgrade | Active oxygen-scavenging systems extend color stability from 5 to 12 days for grab-and-go manufacturing. |
Study Parameters
A spread of perspectives from specialty produce distributors, SENASICA compliance officers, retail category buyers, and food service procurement managers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from USDA Agricultural Marketing Service grade standards, FDA Food Safety Modernization Act guidance documents, SENASICA export protocol filings, and customs trade data for root vegetable cross-border flows. Bottom-up volume estimates from Mexican growing region capacity and top-down demand calibration from United States retail scanner data were triangulated.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation modeled across product format, end-user concentration, application context, and distribution configuration. CAGRs were derived from historical volume trajectories and forward-looking adoption curves for grain-free pasta alternatives and clean-label snacking formats. Climate-driven harvest volatility and phytosanitary enforcement thresholds served as industry-specific forecast inputs.
Practitioners should monitor SENASICA inspection capacity expansion, diesel transport cost movements, and organic certification backlog durations for early signals of forecast deviation. Forecasts reflect assumptions about Latin American cuisine penetration rates and ketogenic diet adherence persistence. Material shifts in FDA preventive controls enforcement intensity or Mexico-United States trade corridor disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Fermented Cucumber Market