
 North America Rice Protein Market | 2026-2036
North America Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rice Protein Market Analytics
Specialty stores and direct-to-consumer channels is reconfiguring how rice protein reaches end users across North America. NOW Foods leverages its established retail presence to sustain shelf visibility in natural product chains. Axiom Foods, Inc. anchors the supply side through its integrated rice protein extraction and ingredient manufacturing operations. Growing Naturals LLC competes by specializing in organic-certified rice protein isolates targeted at allergen-sensitive consumers.
Rice protein comprises the albumin and globulin fractions extracted from brown, white, or whole-grain rice through aqueous or enzymatic processing, typically yielding protein concentrations between 50% and 90% depending on isolation method. The ingredient serves primarily as a hypoallergenic, vegan protein fortifier in human nutrition products where soy and dairy allergens must be avoided. Isolate commands the premium tier within product type segmentation due to its superior amino acid completeness and lower carbohydrate residue. Nutritional supplements represents the fastest-expanding end user segment as endurance athletes and fitness consumers shift toward single-source plant proteins. Powder form dominates current volume flows, though bar applications are gaining traction in convenience-oriented channels.
The FDA governs protein content claims and Good Manufacturing Practice compliance for rice protein sold in the United States, while Health Canada and the PMRA oversee ingredient safety and novel food approvals for the Canadian market. USDA Organic certification and Non-GMO Project verification function as de facto market access requirements for premium positioning in both countries. Stakeholders must monitor evolving amino acid scoring regulations and impending front-of-package labeling rules that could recalibrate competitive advantage between isolate and concentrate grades.
Market Dynamics
Clean-label manufacturing clusters in California and the Pacific Northwest are compressing supply chains and forcing ingredient suppliers to co-locate near formulation centers. FDA protein labeling uncertainty is accelerating reformulation cycles as brands hedge against pending amino acid scoring changes.
Growth Catalysts
- Sports nutrition diversification:Endurance athletes in the United States and Canada are pivoting from whey to single-source plant proteins, creating pull-through demand for rice protein isolates in powdered supplements and ready-to-drink formats.
- USDA Organic certification expansion:Premium positioning now requires dual verification through USDA Organic and Non-GMO Project standards, locking in supply contracts with certified rice processors.
- Allergen-free school nutrition programs:K-12 foodservice directors in California and Texas are adopting rice protein for compliant meal fortification where soy and dairy are restricted.
Market Restraints
- Input cost volatility:Drought cycles in Arkansas and Louisiana rice belts create raw material price swings that concentrate risk for non-integrated ingredient processors.
- Supply concentration:Brown rice protein extraction capacity clusters in southern China and Vietnam, exposing North American brands to trans-Pacific shipping disruptions and tariff exposure.
- Lysine limitation:Rice protein's incomplete amino acid profile requires costly blending with pea or hemp isolates to achieve PDCAAS parity with dairy alternatives.
Strategic Opportunities
- Canadian natural health product expansion:Health Canada's evolving novel food approval pathway for plant proteins creates first-mover advantage for isolate grades targeting NHP license holders.
- Cell-cultured meat hybridization:Precision fermentation startups are exploring rice protein as a scaffolding material and nutritional matrix for cultivated protein products.
- Direct-to-consumer subscription channels:Specialty e-commerce platforms bypass traditional distribution markups, enabling margin capture for branded isolate formulations.
Industry Challenges
- Enzymatic extraction talent scarcity:Food biochemists with rice protein-specific expertise remain concentrated in legacy soy and dairy processing regions, forcing relocation premiums.
- Dual-jurisdiction compliance timelines:Simultaneous FDA GRAS self-determination and Health Canada novel food submissions extend time-to-market by 18-24 months for new isolate grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rice Protein Market |
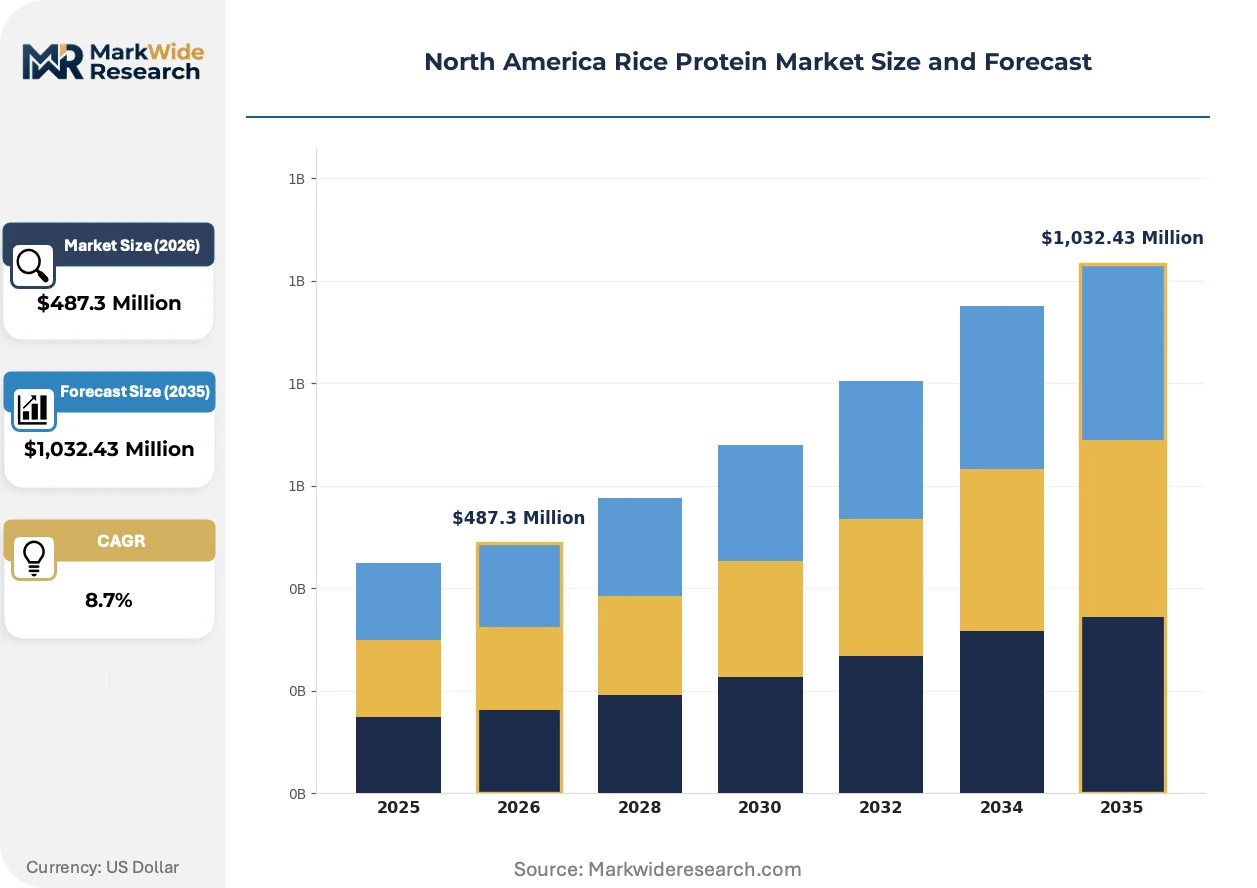
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Blends End User: Food & Beverage, Nutritional Supplements, Pharmaceuticals, Animal Feed Form: Powder, Liquid, Granule, Bars Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | NOW Foods, Ribus, Inc., Axiom Foods, Inc., North Coast Naturals, Golden Grain Group, AIDP Inc., Growing Naturals LLC, Naked Nutrition, RiceBran Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rice Protein Market Evolving Landscape
Computational protein modeling and precision fermentation are converging to reshape how rice protein is extracted, characterized, and positioned against competing plant sources. These shifts are compressing development cycles and redefining quality benchmarks.
Enzymatic hydrolysis with substrate-specific proteases is virtualizing traditional aqueous extraction methods by enabling targeted peptide cleavage that improves digestibility without denaturing functional properties. Sports nutrition formulators in the Pacific Northwest are adopting these isolates for rapid-absorption applications. This technology is virtualizing the conventional concentrate-isolate hierarchy by delivering intermediate protein grades with isolate-like amino acid scores at concentrate price points.
FDA's pending modernization of protein content claims under the Nutrition Facts Label is forcing preemptive reformulation across the supplement sector. The agency's proposed shift toward digestible indispensable amino acid scores threatens to downgrade rice protein's declared protein percentage versus dairy and soy alternatives. Brands are responding by commissioning third-party DIAAS testing and front-loading leucine fortification to protect label claims.
Subscription-based personalized nutrition services are disintermediating traditional retail channels for rice protein distribution. Direct-to-consumer brands in California and Texas are capturing recurring revenue through algorithm-driven flavor and formulation matching. This shift is most visible among millennial fitness consumers who prioritize convenience and traceability over shelf presence in natural product chains.
North America Rice Protein Market Segmentation
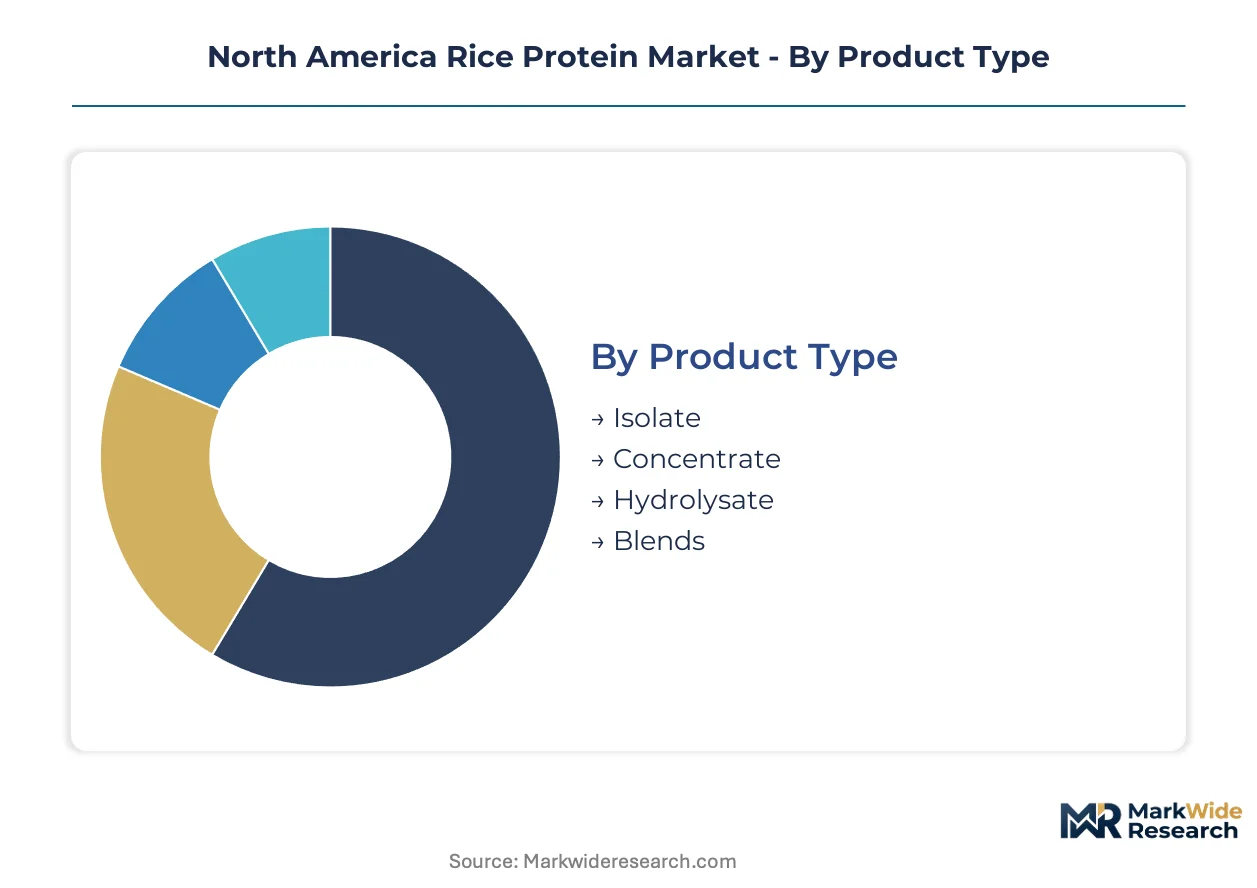
Rice protein segmentation in North America reflects divergent technical specifications and channel economics. Manufacturers calibrate protein concentration, processing method, and physical form to match end-use requirements and pricing thresholds across sports nutrition, foodservice, and pharmaceutical applications.
Product Type:
Mature extraction technologies dominate the high-volume tiers, while enzymatic innovation is reshaping the premium frontier.
- Isolate:Protein concentrations of 80-90% achieved through aqueous or enzymatic extraction yield superior amino acid completeness and minimal carbohydrate residue. Sports nutrition brands in California and the Pacific Northwest specify isolate for single-source plant protein positioning where PDCAAS scoring matters.
- Concentrate:Processing yields 50-80% protein content with retained fiber and starch fractions, commanding lower unit economics suited to food & beverage fortification. K-12 foodservice programs in Texas and California leverage concentrate for cost-compliant meal enhancement where allergen restrictions apply.
- Hydrolysate:Pre-digested peptide fractions accelerate absorption kinetics for clinical nutrition applications.
- Blends:Lysine-fortified combinations with pea or hemp protein address amino acid limitations in premium formulations.
Isolate handles the majority of throughput; hydrolysate is the fastest mover on share.
End User:
Application diversity spans regulated pharmaceutical channels through commodity feed inputs, with margin structures varying fourfold across the spectrum.
- Nutritional Supplements:Powdered isolates and ready-to-drink formats target endurance athletes and fitness consumers shifting from whey to plant proteins. Pacific Northwest formulation clusters drive demand for USDA Organic-certified, Non-GMO Project-verified grades with rapid-absorption hydrolysates.
- Food & Beverage:Clean-label bakery, dairy alternatives, and meat analogs incorporate concentrate and isolate grades for texture and protein fortification. California-based natural product manufacturers specify low-flavor-impact isolates for neutral-taste applications.
- Pharmaceuticals:Hypoallergenic enteral nutrition and clinical protein supplements require GMP-compliant isolate grades with batch-level allergen documentation.
- Animal Feed:Pet food and specialty livestock nutrition utilize lower-concentration grades where amino acid completeness is less critical.
Nutritional supplements commands the steepest expansion trajectory; food & beverage anchors current volume flows.
Form:
Physical format selection hinges on manufacturing integration requirements and consumer convenience positioning across channel types.
- Powder:Dominant volume format enabling flexible dosing, extended shelf stability, and efficient bulk logistics. Direct-to-consumer subscription brands in California and Texas algorithm-match powder formulations to individual consumer profiles.
- Bars:Convenience-oriented sports nutrition and meal replacement applications gain traction in specialty retail and online channels. Pacific Northwest clean-label manufacturers compress supply chains by co-losing bar production near rice protein extraction facilities.
- Liquid:Ready-to-drink applications require stabilized emulsion systems for suspension and taste masking.
- Granule:Intermediate format for industrial food manufacturing with specific dispersibility requirements.
Powder handles the majority of throughput; bars are gaining share fastest.
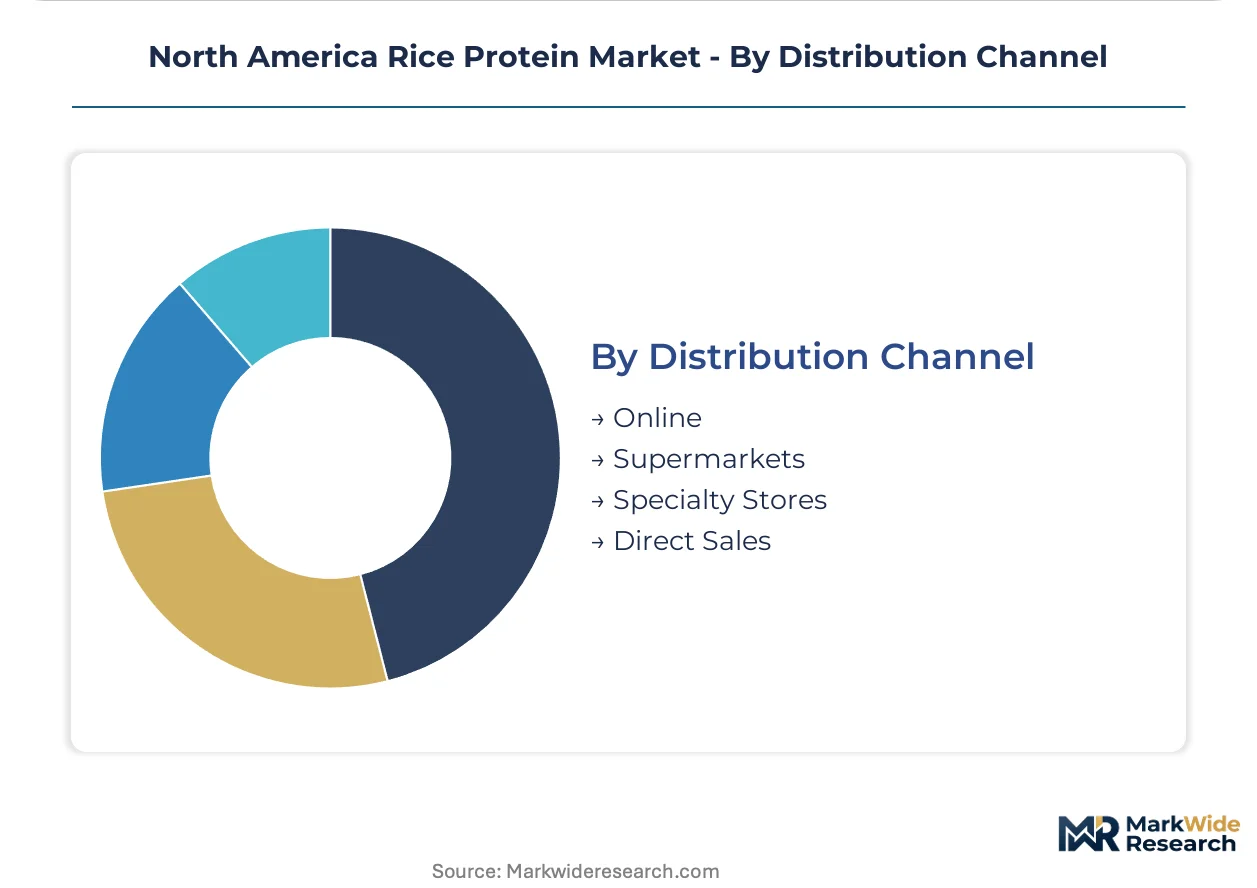
Distribution Channel:
Channel strategy determines margin capture, brand control, and regulatory documentation burdens across the value chain.
- Online:Direct-to-consumer platforms bypass traditional distribution markups while enabling subscription-based recurring revenue. Algorithm-driven personalization services in California match flavor and formulation preferences to individual fitness consumers.
- Specialty Stores:Natural product chains and independent retailers sustain shelf visibility for premium organic-certified grades. NOW Foods leverages established retail presence across United States and Canadian natural product chains.
- Supermarkets:Mass-market penetration requires price-competitive concentrate grades with conventional certification.
- Direct Sales:Bulk pharmaceutical and foodservice contracts bypass retail markup entirely.
Online handles the majority of throughput; specialty stores is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Organic certification expansion and FDA protein labeling modernization are reshaping investment flows across North American rice protein markets. State-level clean-label manufacturing incentives in California and Texas accelerate facility siting decisions. Health Canada's novel food approval pathway creates parallel compliance requirements for cross-border brands.
United States
California's clean-label manufacturing clusters and Pacific Northwest sports nutrition formulation centers drive isolate-grade demand. FDA's pending DIAAS scoring modernization compels preemptive third-party testing investments. Austin and Dallas foodservice distributors adopt rice protein concentrates for K-12 allergen-compliant meal programs.
Canada
Health Canada's evolving novel food approval pathway for plant proteins creates first-mover positioning for isolate suppliers targeting natural health product license holders. British Columbia's functional food manufacturing corridor concentrates organic-certified rice protein formulation. Toronto-area distribution hubs service cross-border supplement brands with dual-jurisdiction compliance documentation.
Mexico
Querétaro and Jalisco states attract contract manufacturing investment from US brands seeking nearshored production capacity. Mexico's national food safety authority COFEPRIS aligns novel ingredient protocols with FDA frameworks. Baja California nutrition ingredient clusters supply cross-border sports nutrition assembly operations.
North America Rice Protein Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated rice processors and specialized ingredient refiners. The vendor base separates into three strategic tiers: agricultural cooperatives with captive milling capacity, dedicated protein extraction specialists, and branded finished goods marketers. Capacity expansion and strategic partnerships dominate competitive moves as firms secure organic-certified brown rice supply contracts.
Within the integrated processing tier, Axiom Foods, Inc. and RiceBran Technologies exemplify supply-chain-anchored positioning through upstream rice milling integration. NOW Foods occupies the branded finished goods vector with established natural product retail distribution. Growing Naturals LLC represents the specialization archetype through organic-certified isolate targeting allergen-sensitive segments.
| Leading Market Players |
|---|
| NOW Foods |
| Ribus, Inc. |
| Axiom Foods, Inc. |
| North Coast Naturals |
| Golden Grain Group |
| AIDP Inc. |
| Growing Naturals LLC |
| Naked Nutrition |
| RiceBran Technologies |
| Others |
Value Network & Pricing Analysis
Tariff exposure on trans-Pacific brown rice protein shipments determines both the premium commanded by domestically extracted isolates and the geographic clustering of formulation facilities near coastal ports. Buyers face tiered cost structures that widen when ocean freight rates spike or when FDA amino acid scoring changes force rapid reformulation.
Pricing Analysis
Certification level creates the primary spread between USDA Organic and Non-GMO Project dual-verified isolates versus conventional concentrate grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein concentration, with 80-90% isolates capturing margin premiums from sports nutrition brands while 50-70% concentrates serve price-sensitive K-12 foodservice programs. Cost compression in the standard tier is intensifying because enzymatic extraction capacity expansion in Vietnam and southern China feeds oversupply into North American spot markets. Direct-to-consumer subscription buyers exhibit lowest price sensitivity, whereas mass-market supermarket procurement teams drive hard volume discounts.
Supply Chain Analysis
Extended payment terms from California clean-label manufacturers to Arkansas and Louisiana rice cooperatives are compressing working capital cycles for non-integrated processors. Raw material sourcing draws from Arkansas long-grain, California medium-grain, and imported Vietnamese brown rice varieties, with enzymatic extraction enzymes supplied by Danish and Japanese specialty chemical houses. Single-source vulnerability concentrates in southern China's extraction facility cluster, where 60-day ocean transits expose brands to container availability shocks. Distribution runs through direct-to-consumer platforms, natural product specialty chains, and bulk pharmaceutical contracts, with co-location of bar manufacturing near Pacific Northwest formulation centers shortening last-mile logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among direct-to-consumer subscription platforms and K-12 foodservice purchasing cooperatives, fragmenting traditional brand loyalty and compressing margin capture for non-integrated suppliers.
For Market Incumbents: Pre-empt FDA DIAAS scoring disruption by commissioning third-party amino acid testing now and front-loading leucine fortification into isolate formulations before labeling rules finalize. Secure backward integration into Arkansas and Louisiana rice milling capacity to hedge against tariff volatility on Asian-sourced protein. Lock multi-year USDA Organic supply contracts before 2025 crop cycles tighten certified acreage availability. For New Entrants and Emerging Players: Pursue Health Canada novel food approval first-mover positioning for isolate grades targeting British Columbia natural health product license holders, where dual-jurisdiction compliance documentation creates incumbent switching costs. Target allergen-free school nutrition programs in Texas and California as the most penetrable volume segment, with concentrate grades priced below pea protein alternatives. Lead with direct-to-consumer subscription acquisition to bypass retail slotting fee barriers and capture recurring revenue algorithms. For Investors and Strategic Acquirers: The market sits at a certification-scarcity phase that favors integrated processors with captive organic rice supply and in-house enzymatic extraction capabilities. Long-term viability hinges on defensible positioning upstream of formulation clusters rather than branded finished goods marketing. Watch FDA DIAAS implementation timing as the inflection signal that separates isolate-grade premium capture from concentrate-grade commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Milling | Captive supply of USDA Organic brown rice insulates margin from Arkansas drought cycles and Asian tariff exposure. |
| Health Canada Novel Food Submission | First-mover approval for isolate grades locks in natural health product license holder supply contracts before competitors file. |
| Direct-to-Consumer Platform Launch | Algorithm-driven subscription matching bypasses NOW Foods' retail shelf dominance and captures millennial fitness consumer lifetime value. |
| Enzymatic Hydrolysis Capacity Expansion | Substrate-specific protease investment delivers rapid-absorption isolates that command premium from Pacific Northwest sports nutrition formulators. |
| Dual-Jurisdiction Compliance Documentation | Simultaneous FDA GRAS and Health Canada novel food dossiers enable cross-border brand supply without 18-24 month regulatory delays. |
Research Methodology
Initial hypotheses were tested against primary input from sports nutrition formulators, K-12 foodservice procurement directors, rice protein extraction plant managers, and natural product retail category buyers, then refined through secondary validation. Bottom-up demand modeling triangulated against top-down supply capacity assessments used FDA GRAS notification filings, USDA Organic certification databases, Health Canada novel food submissions, and Pacific Northwest clean-label manufacturing cluster employment data. Trade flow analysis from customs records and enzymatic extraction equipment import manifests anchored supply-side calibration.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation modeled across product type tiers, end-use applications, physical form factors, and distribution channel economics. CAGRs derived from iterative convergence of historical volume trajectories and forward-looking capacity expansion announcements, incorporating rice acreage planting intentions and drought probability indices as agriculture-specific forecast inputs.
Sensitivities concentrate around FDA DIAAS scoring implementation timing, trans-Pacific shipping rate volatility, and Arkansas-Mississippi River basin drought frequency. Forecasts embed assumptions regarding organic certification expansion rates and enzymatic extraction yield improvements that macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Meat Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Middle East and Africa Plant-Based Meat and Dairy Products Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant-Based Bacon Market