
 Vegan Dips Market | 2026-2036
Vegan Dips Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Dips Market Analytics
Foodservice operators are rotating toward vegan dips as quick-service restaurants and casual dining chains expand plant-based appetizer menus. SABRA DIPPING CO. LLC dominates refrigerated hummus distribution through broad retail penetration. The Kraft Heinz Company leverages its condiment infrastructure to extend shelf-stable vegan formats into mass-market channels. Kite Hill specializes in almond-based cream cheese alternatives that anchor premium positioning in specialty grocers.
Vegan dips are emulsified or pureed plant-based preparations, typically containing 60-85% water plus oil, protein, acid, and stabilizers, manufactured through high-shear blending or cold-processing to achieve spoonable texture for crudité, chip, or bread accompaniment. Hummus leads volume as chickpea-based formulations benefit from established supply chains and neutral flavor adaptability, while nut dips command margin premiums due to cashew raw material costs and artisan positioning. Single-serve pouches represent the fastest-expanding packaging format as convenience retailers prioritize grab-and-go portability over traditional tub formats.
The USDA enforces organic certification standards that constrain ingredient sourcing for vegan dip producers seeking premium labeling, while the FDA governs allergen disclosure requirements for tree nut and soy bases that affect formulation decisions and facility segregation. The EU Green Deal's carbon border adjustments will reshape import economics for avocado-dependent guacamole suppliers sourcing from Latin America. Stakeholders must monitor cold-chain energy regulations and alternative protein labeling battles as these determine which base ingredients retain cost-competitive market access.
Market Dynamics
Foodservice procurement of vegan dips is pivoting toward single-serve formats as convenience retailers and quick-service operators reconfigure cold-chain logistics around grab-and-go portability rather than bulk tub distribution.
Growth Catalysts
- EU Green Deal carbon border adjustments:Cold-chain efficiency mandates are accelerating refrigerated plant-based SKU expansion in German supermarkets, creating shelf-space pull-through for hummus and nut-based formats.
- Quick-service restaurant plant-based menu integration:Casual dining chains are rotating vegan dips into appetizer sections as standard offerings rather than limited-time promotions, normalizing trial behavior.
- Almond protein cold-processing:High-shear blending advances are reducing emulsifier dependency and enabling cleaner-label formulations that qualify for organic certification under USDA standards.
Market Restraints
- Cashew raw material cost volatility:Artisan-positioned nut dips face margin compression when cashew harvests in Vietnam and India fluctuate, forcing reformulation or price adjustments.
- Avocado supply concentration:Guacamole-dependent suppliers sourcing from Mexico and Peru encounter logistics disruption risk from climate-induced yield variability and export licensing friction.
- FDA allergen disclosure requirements:Tree nut and soy base segregation mandates increase facility capital requirements and constrain co-manufacturing flexibility for mid-scale producers.
Strategic Opportunities
- Underpenetrated German convenience retail:Refrigerated plant-based shelf space expansion in discounters and petrol stations offers first-mover positioning ahead of competitor saturation.
- F-Gas Regulation refrigerant transition:EU cold-chain operators retrofitting transport fleets create partnership openings for dip suppliers willing to co-invest in compliant logistics infrastructure.
- High-pressure processing (HPP) and clean-label convergence:Combining HPP pasteurization with minimal stabilizer formulations enables extended refrigerated shelf life without synthetic preservatives.
Industry Challenges
- Organic certification timeline compression:USDA ingredient sourcing audits for premium-label vegan dips extend new product development cycles by six to twelve months.
- Cold-chain energy cost reconfiguration:F-Gas Regulation compliance retrofits and electricity price volatility are forcing distributors to rebalance inventory depth against spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Dips Market |
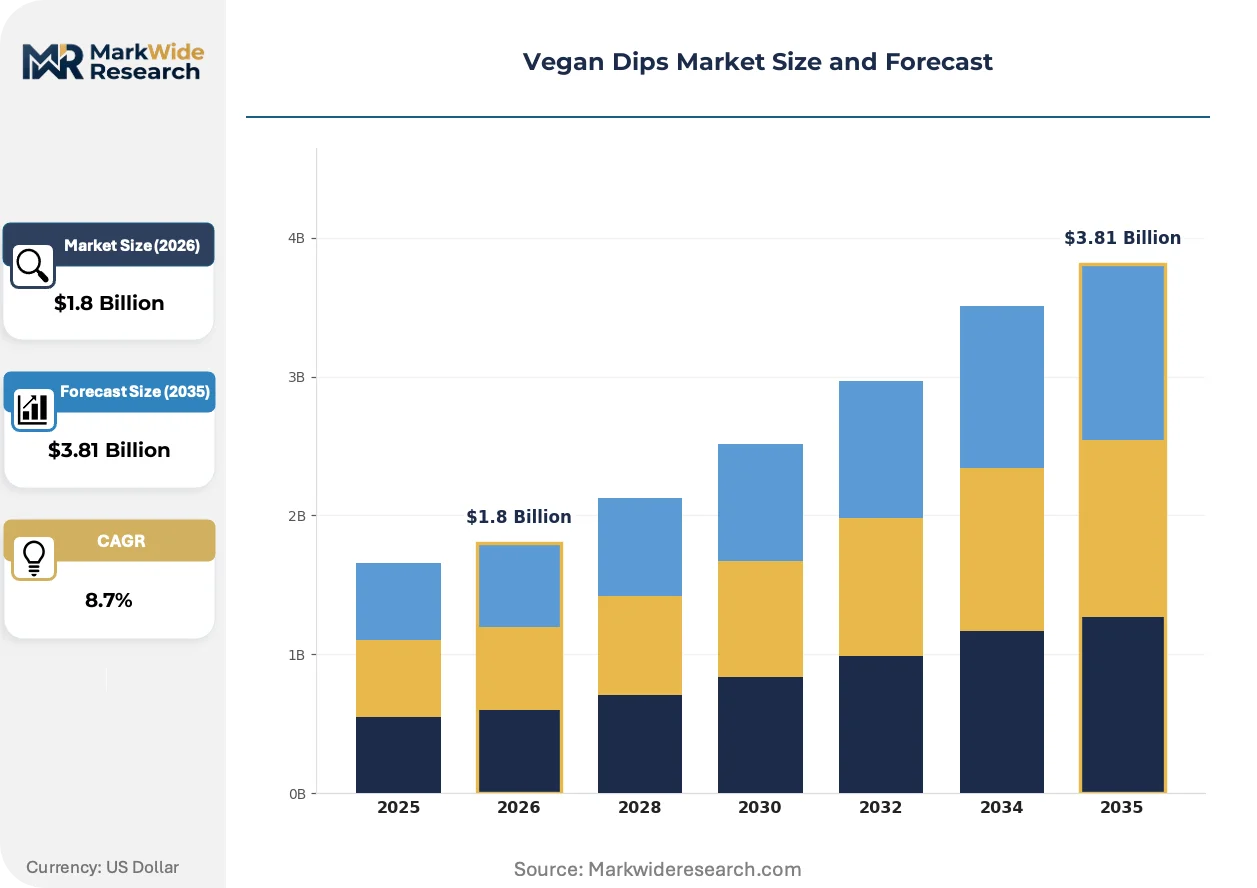
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hummus, Guacamole, Bean Dips, Nut Dips Base Ingredient: Chickpeas, Avocado, Black Beans, Cashews Flavor Profile: Spicy, Savory, Sweet, Herb-infused Packaging Type: Tubs, Pouches, Single Serve, Jars |
| Companies Covered | The Kraft Heinz Company, SABRA DIPPING CO. LLC, Frito-Lay North America Inc., Bolthouse Farms Inc., Kite Hill, Good Foods Group, Galaxy Nutritional Foods Inc., DAIYA FOODS INC., Wingreen World, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Dips Market Evolving Landscape
Processing technology and regulatory frameworks are compressing formulation cycles while procurement patterns shift toward portability-first specifications that reward format innovation over traditional tub economics.
High-pressure processing (HPP) is decomposing the traditional trade-off between shelf stability and clean-label positioning. Refrigerated vegan dip producers are adopting HPP units to eliminate thermal pasteurization and reduce stabilizer loads. This technology is decomposing barrier-to-entry advantages held by shelf-stable specialists with retort infrastructure, enabling refrigerated challengers to capture convenience retail placement.
REACH chemical safety evaluations and F-Gas Regulation phase-down schedules are tightening emulsifier and refrigerant specifications simultaneously. Dip manufacturers must reformulate away from certain stabilizers while logistics partners retrofit cold-chain equipment. German retailers are responding fastest, demanding supplier documentation on both formulation compliance and transport refrigeration credentials.
Single-serve pouch specifications are displacing multi-serve tubs in convenience channel negotiations. Retail buyers are prioritizing grab-and-go rotation rates and reduced spoilage write-offs over per-ounce economy. This pattern concentrates in German petrol station and urban convenience formats where consumption occasions skew toward immediate consumption rather than household stock-up.
Vegan Dips Market Segmentation
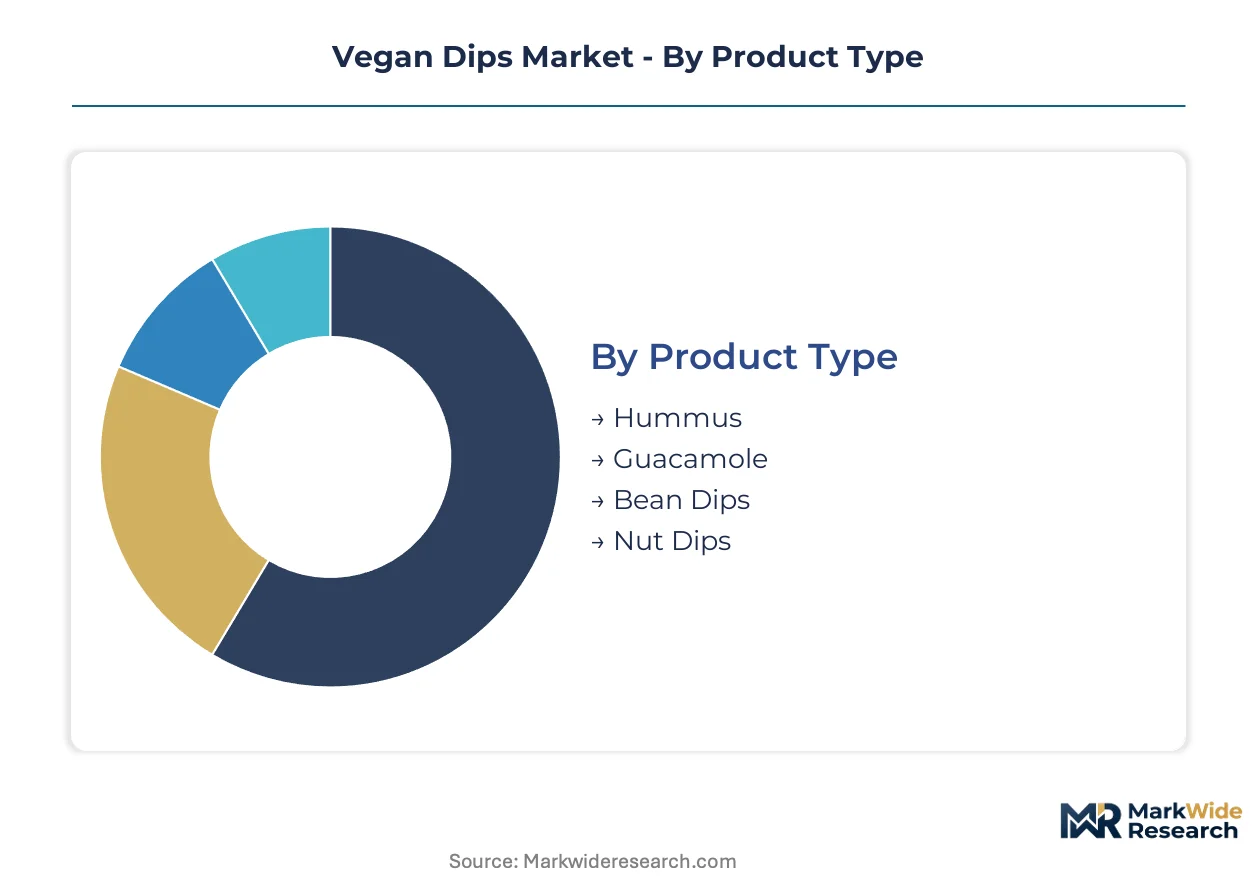
Segmentation in vegan dips reveals how formulation choices, packaging formats, and flavor positioning create distinct competitive arenas. Each category carries different margin profiles, cold-chain requirements, and retail channel access patterns that determine supplier viability.
Product Type:
Hummus dominates domestic production volumes across North American and European facilities, while guacamole and nut-based formats rely more heavily on cross-border ingredient flows and export-oriented processing hubs.
- Hummus:Chickpea-based emulsions with tahini, lemon, and garlic achieve 60-85% water content through high-shear blending. German retailers are expanding refrigerated shelf space for hummus SKUs ahead of other formats, driven by EU Green Deal cold-chain efficiency mandates that favor established supply networks.
- Guacamole:Avocado-based preparations require pressure-sensitive cold chains due to enzymatic browning sensitivity. Mexican and Peruvian sourcing corridors face carbon border adjustment exposure under EU Green Deal implementation, compressing import economics for European market access.
- Bean Dips:Black bean and pinto formulations leverage North American pulse crop infrastructure for cost-competitive positioning in mass-market channels.
- Nut Dips:Cashew and almond bases command premium positioning in specialty retail, with artisan producers clustering in California and Mediterranean processing zones.
Hummus commands the established base. The steepest expansion runs through nut-based alternatives as cashew and almond formulations capture premium positioning.
Base Ingredient:
Ingredient selection determines certification pathways, with chickpea and black bean bases qualifying more readily for USDA organic audits than avocado or cashew alternatives that face extended sourcing verification timelines.
- Chickpeas:Neutral flavor profile and established supply chains in Turkey, India, and North America enable scale production. German foodservice operators are standardizing chickpea-based hummus as default vegan dip options in quick-service restaurant appetizer rotations.
- Avocado:High oil content delivers creamy texture without emulsifier dependency. Mexican harvest variability and export licensing friction create supply concentration risk that reformulation strategies are beginning to address.
- Black Beans:US and Canadian pulse production supports clean-label positioning with minimal processing requirements for organic certification compliance.
- Cashews:Vietnamese and Indian harvest fluctuations drive raw material cost volatility, forcing mid-scale producers toward price adjustments or base substitution.
Chickpea formulations anchor volume production. Cashew bases are climbing the fastest as premium positioning justifies margin premiums in specialty retail channels.
Flavor Profile:
Flavor development cycles vary by regulatory exposure, with spicy and herb-infused variants facing simpler additive disclosure requirements than savory formulations incorporating complex umami compounds.
- Spicy:Chili and pepper-based heat profiles align with quick-service restaurant menu integration trends, particularly in US Southwest and German urban convenience formats seeking grab-and-go differentiation.
- Savory:Miso, nutritional yeast, and fermented base formulations require extended USDA organic certification timelines due to multi-ingredient sourcing audits.
- Sweet:Date and maple-sweetened dessert dips occupy niche positioning in specialty grocers, with limited foodservice penetration.
- Herb-infused:Cilantro, basil, and dill variants leverage clean-label appeal for refrigerated placement in German discounters expanding plant-based assortments.
Savory profiles command the established base. Spicy formulations are gaining share fastest as quick-service operators prioritize menu differentiation through heat-forward appetizers.
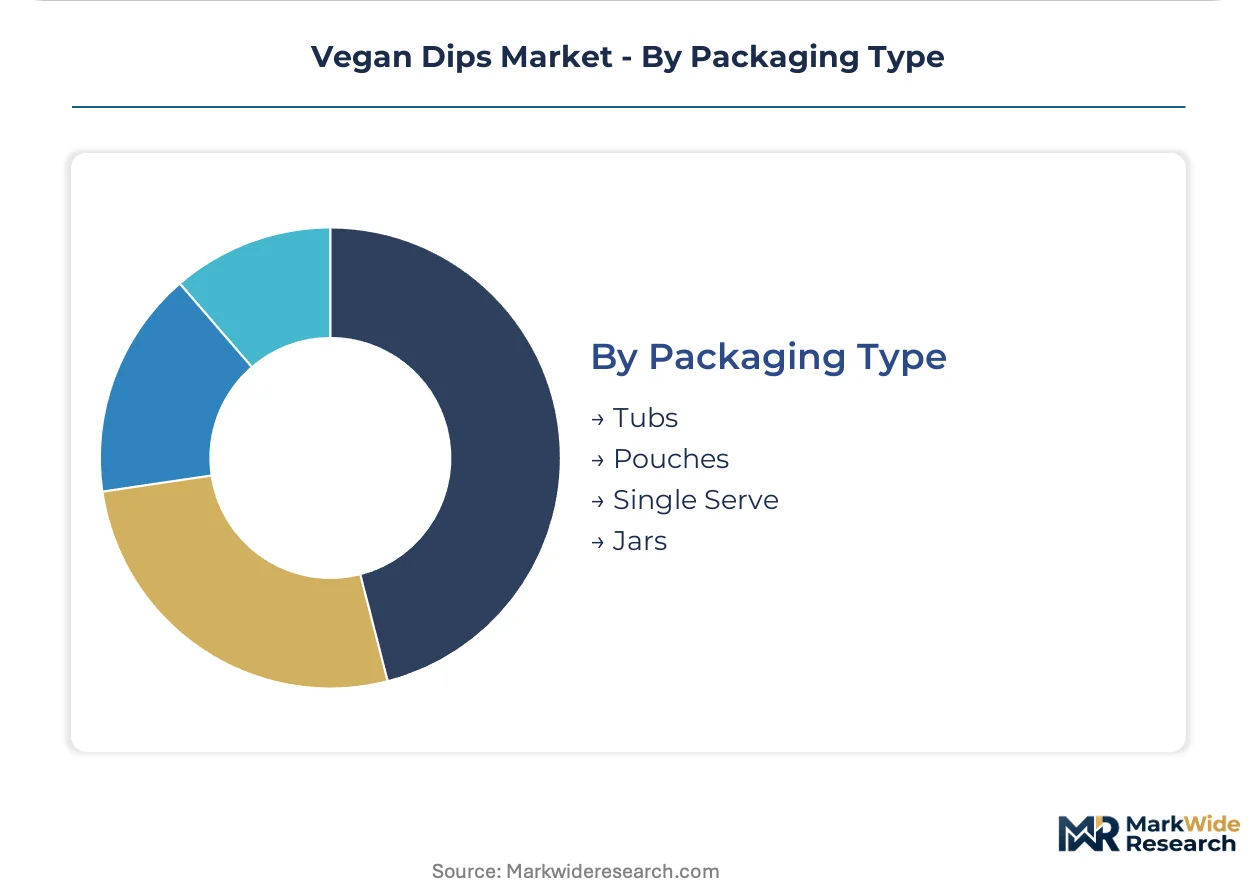
Packaging Type:
Format selection determines channel access, with single-serve specifications requiring HPP pasteurization investment that separates refrigerated challengers from shelf-stable incumbents with retort infrastructure.
- Tubs:Multi-serve containers dominate household stock-up occasions in conventional grocery, though spoilage write-offs pressure retailer margins.
- Pouches:Flexible packaging reduces material costs and shipping cube, attracting private-label programs in European discount channels.
- Single Serve:Portion-controlled formats with HPP pasteurization enable extended refrigerated shelf life without synthetic preservatives. German petrol stations and urban convenience retailers are prioritizing single-serve rotation rates over per-ounce economy.
- Jars:Glass packaging supports premium positioning in specialty retail but carries freight cost penalties and breakage risk in foodservice distribution.
Tub formats command the established base. Single-serve packaging is expanding most quickly as convenience channel buyers reconfigure cold-chain logistics around grab-and-go portability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure anchors European distribution for refrigerated plant-based products, while Union Pacific's refrigerated rail network underwrites North American cross-border movement of temperature-sensitive vegan formats.
Germany
Discounters Aldi and Lidl are widening refrigerated plant-based shelf space in petrol stations and urban convenience formats. The EU Green Deal's F-Gas Regulation is accelerating transport fleet retrofits for compliant cold-chain logistics. Bavarian foodservice distributors in Munich are consolidating procurement around single-serve hummus SKUs for quick-service restaurant integration.
United States
Quick-service chains in Texas and California are standardizing vegan dips as permanent appetizer menu items rather than limited-time offers. FDA allergen disclosure requirements for tree nut and soy bases are constraining co-manufacturing flexibility in Midwest processing facilities. Chicago-area cold-storage operators are reconfiguring inventory depth around HPP-pasteurized single-serve formats to reduce spoilage write-offs.
United Kingdom
Specialty grocers in London and Southeast England are expanding almond-based cream cheese alternative assortments for premium positioning. REACH chemical safety evaluations are tightening emulsifier specifications for clean-label formulations. Manchester-area foodservice distributors are piloting grab-and-go vegan dip programs for urban convenience retailers.
Canada
Health Canada's organic certification alignment with USDA standards is streamlining cross-border ingredient sourcing for pulse-based formulations. Ontario and Quebec retailers are expanding refrigerated plant-based sections in response to foodservice demand for appetizer menu diversification. Toronto-area logistics operators are investing in F-Gas-compliant refrigeration for last-mile cold-chain delivery.
France
ANSM food safety oversight is extending clean-label audit timelines for fermented savory formulations incorporating miso and nutritional yeast. Île-de-France convenience retailers are prioritizing single-serve pouch rotation rates over traditional tub economics. Lyon-based foodservice operators are integrating hummus as default vegan dip options in casual dining appetizer sections.
Vegan Dips Market Competitive Landscape
Listed leaders compete with private specialists across refrigerated distribution infrastructure and clean-label formulation capabilities. The vendor base clusters around three tiers: multinational condiment conglomerates with mass-market shelf-stable reach, refrigerated specialists with HPP pasteurization assets, and artisan nut-based producers occupying premium specialty positioning. Dominant competitive moves include backward integration into almond and cashew processing to secure raw material cost stability, and strategic partnerships with cold-chain logistics operators to secure F-Gas-compliant transport capacity.
Within the mass-market tier, The Kraft Heinz Company and SABRA DIPPING CO. LLC exemplify divergent infrastructure strategies—one leveraging condiment distribution density, the other anchoring refrigerated retail penetration. Kite Hill occupies a position among premium-tier specialists focused on almond-based alternatives. These three represent the competitive archetype spectrum: scale-driven shelf-stable extension, refrigerated category ownership, and artisan premium positioning.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| SABRA DIPPING CO. LLC |
| Frito-Lay North America Inc. |
| Bolthouse Farms Inc. |
| Kite Hill |
| Good Foods Group |
| Galaxy Nutritional Foods Inc. |
| DAIYA FOODS INC. |
| Wingreen World |
| Others |
Value Network & Pricing Analysis
Cashew-to-almond base substitution among premium nut dip producers is simultaneously shifting procurement geography toward California and Mediterranean processing zones while compressing artisan tier pricing premiums as almond supply scales more predictably than Vietnamese and Indian cashew harvests.
Pricing Analysis
Volume-discount tiering structures separate mass-market hummus SKUs from premium nut-based alternatives. Three-tier pricing stratifies across organic-certified premium, conventional refrigerated standard, and private-label economy levels. Cost compression in the cashew-dependent artisan tier is intensifying because Vietnamese harvest variability forces reformulation or price adjustments. Quick-service restaurant procurement teams exhibit highest price sensitivity, while specialty grocer buyers prioritize clean-label certification over per-unit cost.
Supply Chain Analysis
Port congestion at Veracruz and Manzanillo is elevating inbound logistics costs for Mexican avocado-dependent guacamole suppliers serving European markets. Raw material flows draw from Turkish and Indian chickpea corridors, Vietnamese and Indian cashew processing hubs, and Peruvian avocado export zones. Single-source vulnerability concentrates in Mexican avocado licensing and export authorization systems. Distribution runs through refrigerated third-party logistics networks with F-Gas Regulation compliance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
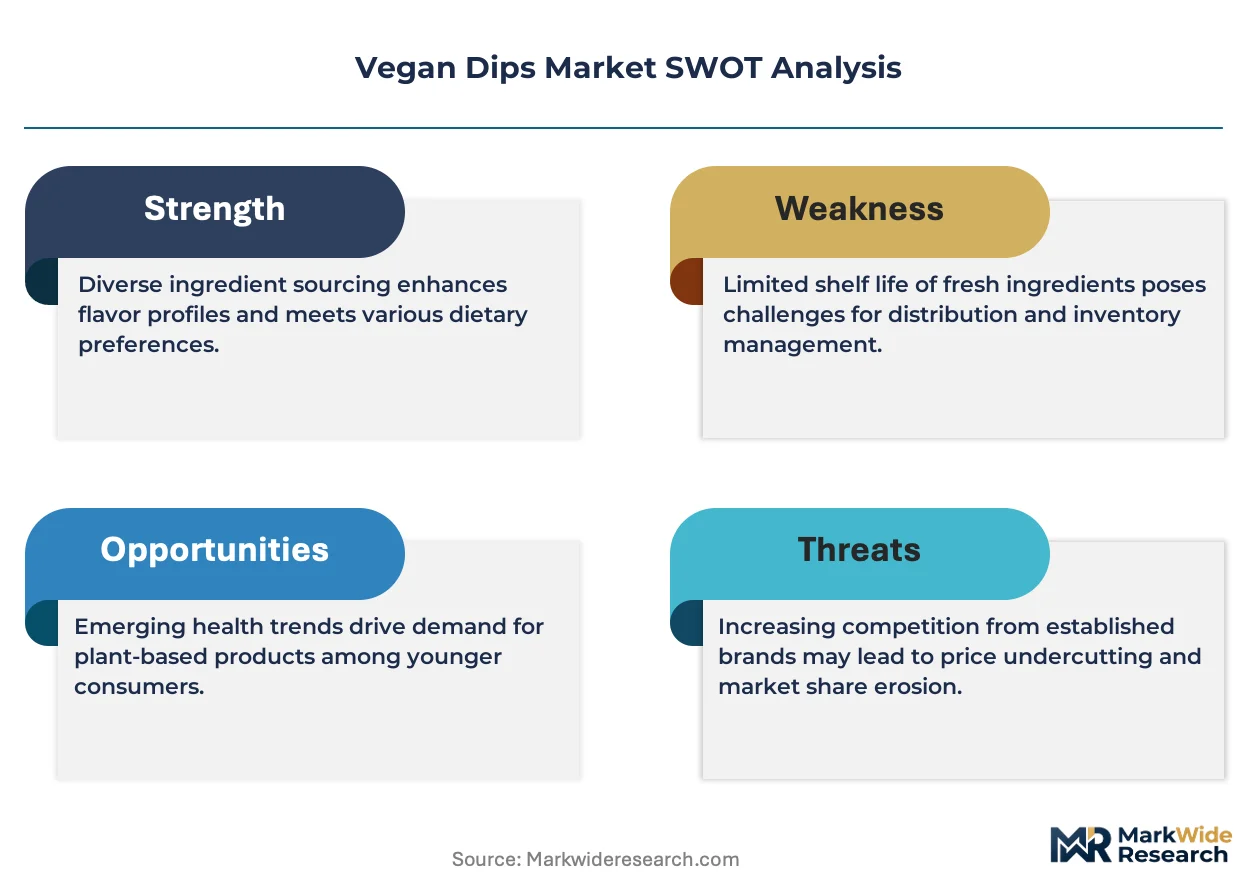
Scarcity of HPP pasteurization capacity combined with F-Gas-compliant cold-chain partnerships is constraining which suppliers can access German convenience retail expansion, creating defendable positions for asset-heavy incumbents.
For Market Incumbents: Compound refrigerated distribution density through exclusive cold-chain logistics partnerships ahead of EU Green Deal enforcement deadlines. Secure backward integration into almond processing in California to stabilize raw material costs against cashew volatility. Defend against private-label encroachment by accelerating single-serve pouch format proliferation in petrol station channels. For New Entrants and Emerging Players: Single-serve format under-service by shelf-stable incumbents creates white-space opportunity in German urban convenience and petrol station formats. Target herb-infused hummus variants in discounter channels where refrigerated plant-based shelf space is expanding fastest. Deploy co-manufacturing partnerships with HPP-equipped facilities to bypass capital-intensive pasteurization infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed refrigerated specialists possessing HPP units and established German retail listings. Five-to-ten-year viability hinges on clean-label formulation capabilities and F-Gas-compliant logistics integration. Monitor EU carbon border adjustment implementation timelines as inflection indicator for avocado-dependent supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Pasteurization Investment | Eliminates thermal processing to enable extended refrigerated shelf life without synthetic preservatives. |
| Backward Integration into Almond Processing | Captures margin from California cultivation through finished goods in premium nut dip tiers. |
| F-Gas-Compliant Cold-Chain Partnership | Secures transport capacity for EU market access under tightening refrigerant phase-down schedules. |
| Single-Serve Pouch Format Launch | Aligns with German convenience retailer prioritization of grab-and-go rotation rates. |
| USDA Organic Certification Investment | Qualifies products for premium labeling that commands shelf placement in specialty grocers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant-based food manufacturing executives, cold-chain logistics operators, and German retail category buyers; and secondary validation through customs trade records, EU regulatory filings, and refrigerated retail audit data. Bottom-up volume modeling triangulated against top-down market sizing across ingredient cost structures.
Across the projection horizon, the analytical framework segmented by product type, base ingredient, flavor profile, packaging format, and regional regulatory cluster. CAGRs derived from trend extrapolation of foodservice procurement patterns and retail shelf-space expansion rates, with inputs from EU Green Deal implementation timelines and F-Gas Regulation compliance schedules.
Material uncertainties — climate-induced avocado yield variability, cashew harvest fluctuations, and EU carbon border adjustment enforcement timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about cold-chain infrastructure investment continuity and clean-label certification pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Europe Rice Protein Market