
 Global Plant Based Milk Market | 2026-2036
Global Plant Based Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Based Milk Market Intelligence
New labeling guidance from the U.S. FDA, alongside established EU regulations on dairy term usage, is rebalancing the cost-of-entry calculus for new market participants. This regulatory environment favors established players with sophisticated compliance and marketing teams. Oatly leverages its strong brand identity and first-mover advantage in the oat milk category. Danone, through its Alpro brand, dominates the European market with a diverse product portfolio, while Califia Farms differentiates through unique bottle designs and a focus on premium ingredients.
Plant-based milk refers to a category of non-dairy beverages derived from processing plant materials like nuts, seeds, or grains into a liquid. The process often involves homogenization and ultra-high temperature (UHT) treatment to achieve a stable emulsion and long shelf life. While almond milk and soy milk remain foundational segments, oat milk represents the fastest-growing category due to its creamy texture and functional performance in coffee. The distribution channel mix is shifting, with online retail and health food stores gaining share from traditional supermarkets.
Product formulation and labeling are governed by agencies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). These bodies set standards for nutritional content, allergen declarations, and permissible health claims, directly influencing R&D priorities. In China, GB standards dictate food safety and quality requirements for market access. Stakeholders must now decide whether to invest in proprietary crop sourcing or rely on a consolidating third-party ingredient supply chain.
Market Dynamics
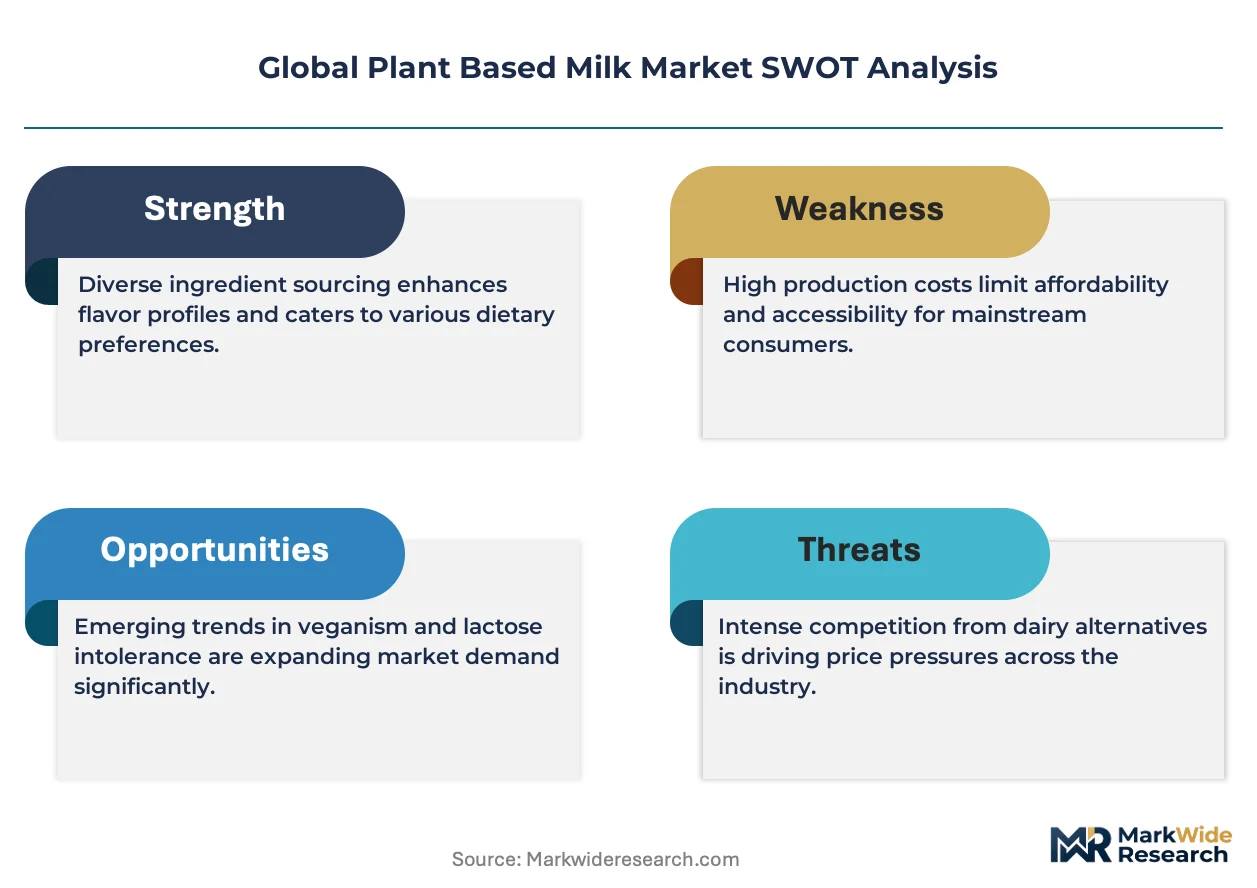
The tension between sourcing specialized, allergen-free ingredients and achieving mass-market scalability defines the competitive landscape. This dynamic forces a choice between proprietary supply chains and reliance on consolidating third-party suppliers.
Growth Catalysts
- High-Pressure Processing (HPP):This non-thermal pasteurization technology extends shelf life while preserving nutritional value, meeting consumer demand for less-processed foods.
- Concentrated Urban Demand:Rapid urbanization in China and India creates dense pockets of demand for premium plant-based options, accelerating market penetration.
- Barista Formulations:Oat milk's superior performance in coffee applications drives significant adoption within the high-volume café and restaurant channel.
Market Restraints
- Input Cost Volatility:Prices for raw materials like almonds and oats are subject to climate and agricultural policy fluctuations, impacting manufacturer margins.
- Regulatory Labeling Friction:EU regulations restricting dairy terms like "milk" on plant-based labels create marketing and branding hurdles for participants.
- Ingredient Supply Consolidation:The supply chain for protein isolates is concentrating among few suppliers, creating dependency risks for beverage formulators.
Strategic Opportunities
- Functional Fortification:Adding ingredients like probiotics and vitamins creates value-added products targeting specific wellness needs beyond basic nutrition.
- Geographic Expansion:Markets in Latin America and Southeast Asia represent significant growth potential as consumer awareness and disposable incomes increase.
- Hybrid Blends:Combining plant bases like oat and pea allows for creating novel products with superior nutritional profiles and sensory characteristics.
Industry Challenges
- Water Usage Scrutiny:The high water footprint associated with certain crops, particularly almonds, is attracting negative consumer and regulatory attention, requiring supply chain adjustments.
- Maintaining Texture and Stability:Achieving a consistently creamy mouthfeel and preventing separation in the final product without using undesirable additives remains a core R&D challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Based Milk Market |
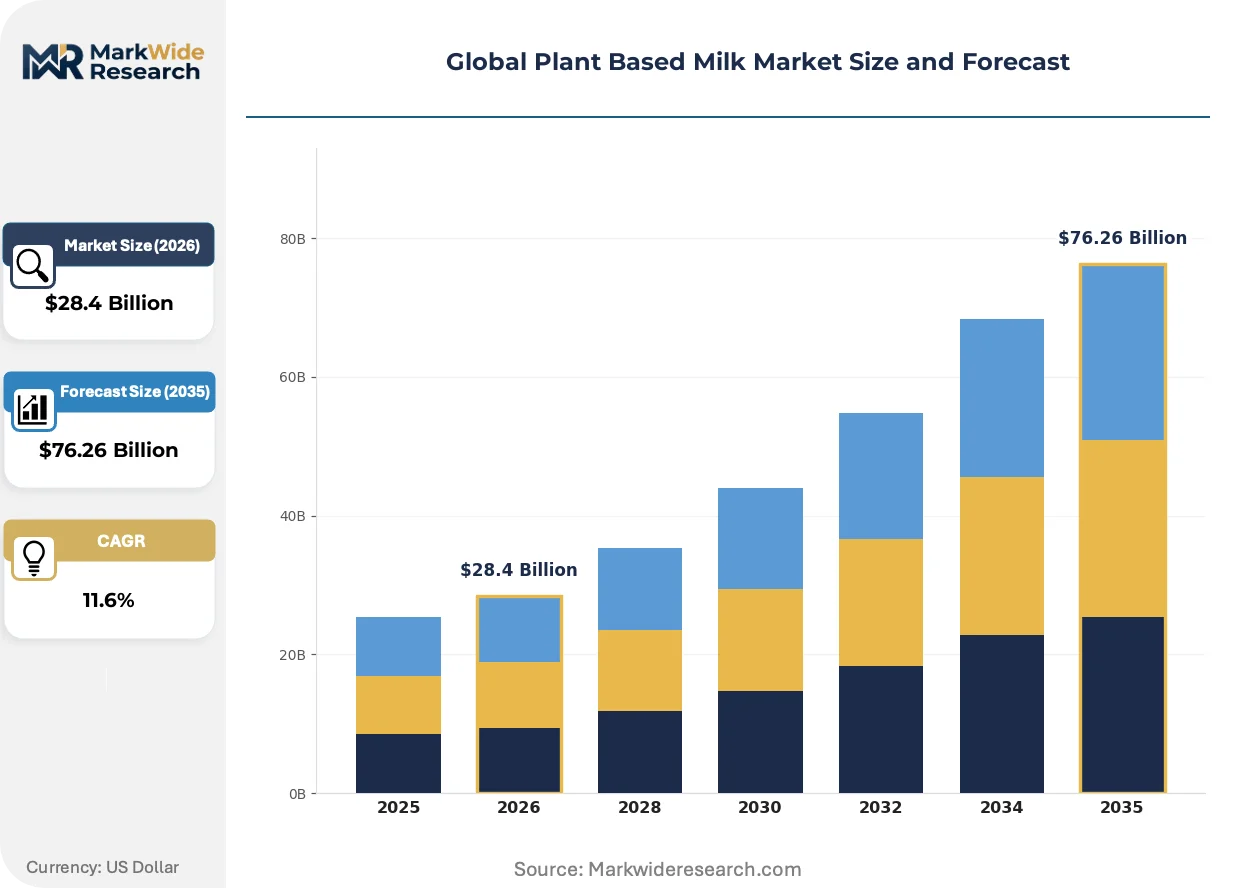
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $76.26 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk End User: Households, Cafes, Restaurants, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Packaging Type: Carton, Bottle, Bag, Tetra Pack |
| Companies Covered | The Hain Celestial Group, Califia Farms, Danone, Alpro, Ripple Foods, Blue Diamond Growers, SunOpta, Vitasoy International Holdings, Oatly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Based Milk Market Strategic Shifts & Innovations
Formulation science is advancing to meet complex consumer expectations for taste, texture, and nutritional transparency. This evolution pushes brands beyond simple dairy analogues toward creating functionally distinct, plant-derived beverages that stand on their own merit.
High-Pressure Processing (HPP) utilizes intense hydrostatic pressure, not heat, for pasteurization, preserving delicate flavors and nutrients. Premium brands are rapidly adopting HPP for their product lines. This technology is decentralizing production from massive UHT facilities, enabling regional players to compete with fresh, extended-shelf-life offerings.
New draft guidance from the U.S. FDA permits using dairy terms like "milk" on plant-based beverages, if they include voluntary nutrient comparisons. This policy clarifies labeling rules, reducing legal uncertainty for manufacturers in the United States. The almond and soy segments, historically targeted by legal challenges, now have a clearer marketing path.
Consumer purchasing is migrating from large supermarket trips toward a hybrid model of online subscriptions and visits to health food stores. This shift disrupts the shelf-space dominance of traditional grocery, favoring brands with strong direct-to-consumer (DTC) logistics. This pattern is most visible in North American and European cities with mature e-commerce infrastructure.
Global Plant Based Milk Market Segmentation
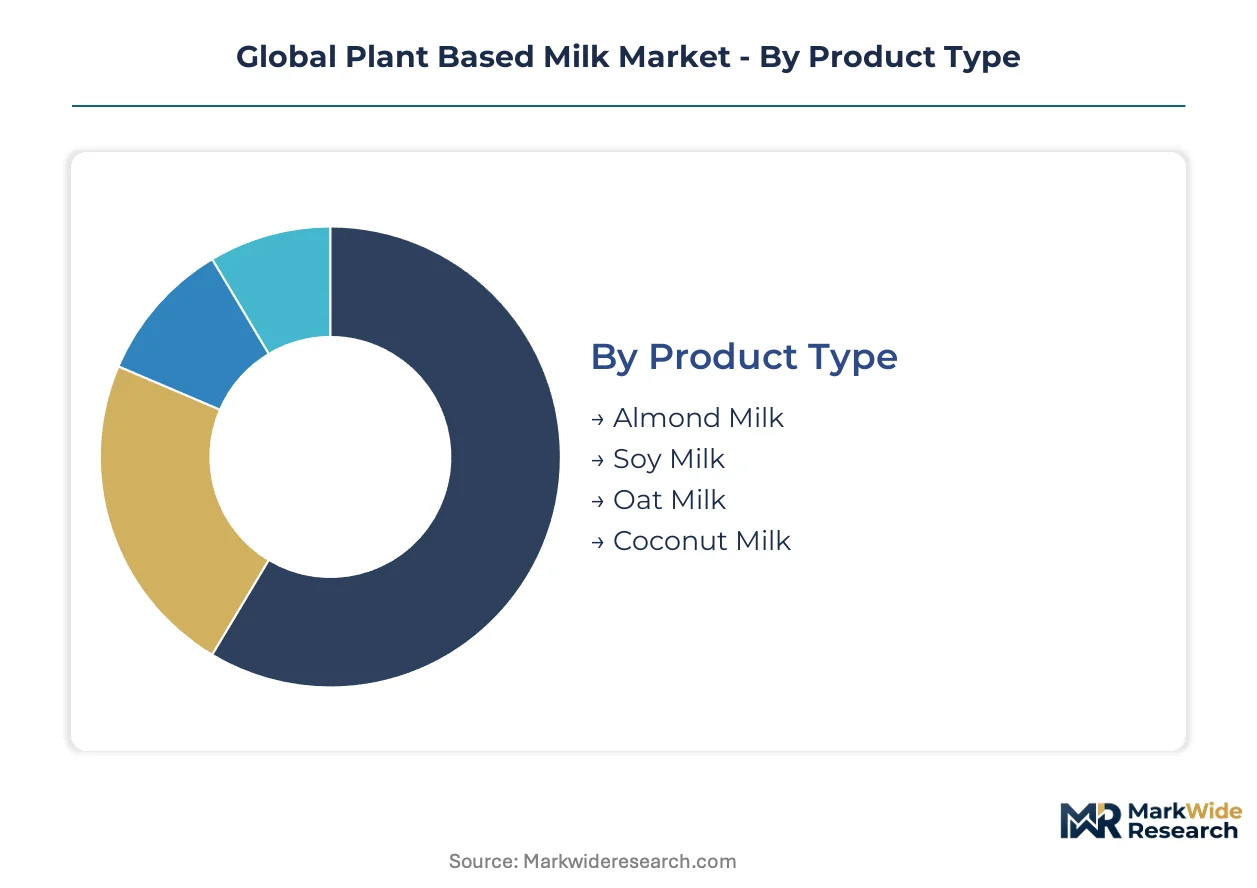
The Global Plant Based Milk Market is analyzed through distinct segmentation categories, providing a granular understanding of product evolution, consumer preferences, and market dynamics. This detailed breakdown illuminates strategic opportunities for market participants seeking to optimize product development and distribution strategies.
Product Type:
The product type segmentation differentiates plant-based milk offerings based on their primary botanical source and distinct flavor profiles.
- Almond Milk:Derived from ground almonds and water, this segment offers a mild flavor and lighter texture, making it a popular dairy alternative. Demand is significant in North America, driven by calorie-conscious consumers and its versatility in various applications.
- Soy Milk:Produced from soybeans, this foundational segment provides a complete protein profile and a richer, creamier consistency. Its established presence in Asian markets, particularly China, continues to drive substantial volume.
- Oat Milk:This category, derived from oats, is expanding most quickly due to its creamy texture and superior performance as a barista-friendly formulation. Cafes and restaurants, especially in European urban centers, are driving its rapid adoption.
- Coconut Milk:Extracted from the flesh of mature coconuts, this segment is valued for its distinct tropical flavor and use in specific culinary applications.
Mature deployment sits with Soy Milk. Newer deployment is concentrated in Oat Milk.
End User:
End user segmentation reflects the diverse applications for plant-based milk across various consumption environments.
- Households:This segment encompasses direct consumer purchases for at-home consumption, representing the largest volume driver for plant-based milk. Convenience and health-conscious choices influence purchasing decisions within this broad base.
- Cafes:High-volume demand from cafes is driven by the need for barista-friendly formulations that froth well and complement coffee flavors. Oat milk formulations are particularly favored in this channel across major urban centers.
- Restaurants:The restaurant sector integrates plant-based milk into various menu items, from beverages to culinary preparations, catering to dietary preferences and allergen considerations. Menu diversification is a key driver.
- Food Manufacturers:This segment utilizes plant-based milk as an ingredient in a wide array of processed foods, including ice cream, yogurt, and baked goods.
Demand patterns vary significantly, with Households driving volume and Cafes influencing formulation innovation.
Distribution Channel:
Distribution channel analysis reveals how plant-based milk products reach consumers, highlighting shifts in retail strategy.
- Online Retail:This channel includes e-commerce platforms and direct-to-consumer subscriptions, gaining significant share due to convenience and wider product selection. This shift is pronounced in North American and European cities with mature e-commerce infrastructure.
- Supermarkets:Traditional supermarkets remain a dominant channel, offering broad accessibility and shelf-space visibility for established plant-based milk brands. Pricing strategies and promotional activities are crucial here.
- Health Food Stores:These specialized retailers cater to consumers seeking organic, non-GMO, and niche plant-based options, often featuring premium brands. Product transparency and ingredient sourcing are key considerations for shoppers.
- Convenience Stores:This channel focuses on single-serve formats and immediate consumption, catering to on-the-go consumers.
While Supermarkets remain a volume anchor, Online Retail is gaining share fastest due to convenience and specialization.
Packaging Type:
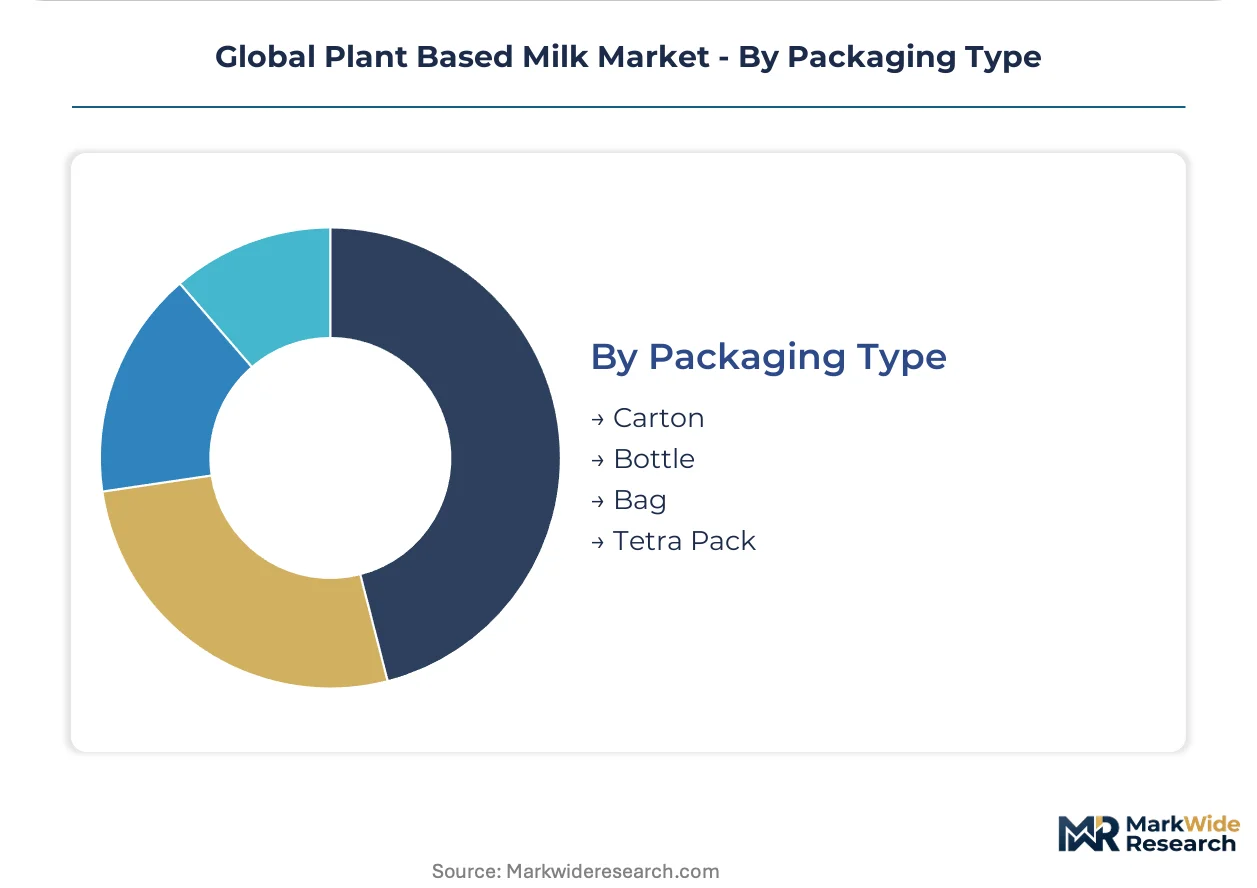
Packaging type segmentation categorizes products by their physical containment, impacting shelf life and consumer convenience.
- Carton:This packaging format, often utilizing aseptic processing, facilitates extended shelf life and is prevalent for bulk and shelf-stable products. It is a cost-effective solution for mass market distribution.
- Bottle:Bottles, typically plastic or glass, are common for premium, refrigerated, or single-serve plant-based milk offerings. Transparency and aesthetic appeal are often emphasized for this format.
- Bag:Bag packaging is less common for ready-to-drink plant-based milk, but can be used for concentrates or institutional sizes.
- Tetra Pack:Tetra Pak solutions provide robust protection and extended shelf life without refrigeration, making them ideal for global distribution and diverse climates.
The preference for Carton reflects shelf-stability requirements, whereas Bottle caters to single-serve or premium offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Economic zones and urban development initiatives across key markets are fostering concentrated demand for plant-based milk products. These areas benefit from favorable investment policies and a rising middle class. Such strategic regions accelerate market penetration and product innovation.
China
Rapid urbanization in China creates dense pockets of demand for premium plant-based options. GB standards dictate food safety and quality requirements for market access, influencing product formulation. Major cities like Shanghai and Beijing are experiencing significant adoption, driven by health-conscious consumers and café culture.
India
Concentrated urban demand in India drives the adoption of plant-based milk, particularly in metropolitan areas. The Food Safety and Standards Authority of India (FSSAI) regulates product labeling and nutritional content. Cities such as Mumbai and Delhi are key consumption hubs, reflecting a growing preference for dairy alternatives.
United States
Consumer preferences for health and wellness drive demand for diverse plant-based milk options in the United States. New labeling guidance from the U.S. FDA clarifies marketing rules for manufacturers. California remains a significant market, with a strong emphasis on innovation and premium product offerings.
Germany
European Union regulations, including those from the European Food Safety Authority (EFSA), shape the competitive landscape for plant-based milk in Germany. Consumers prioritize product transparency and sustainable sourcing, influencing purchasing decisions. Urban centers like Berlin and Hamburg show high per capita consumption, particularly for oat milk.
Brazil
Latin America, including Brazil, represents significant growth potential as consumer awareness and disposable incomes increase. Brazil's national health surveillance agency, ANVISA, sets standards for food and beverage products. São Paulo acts as a major hub for plant-based food innovation and distribution across the region.
Global Plant Based Milk Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping the competitive landscape for plant-based milk products. The market exhibits a tiered structure, with established food and beverage giants coexisting alongside agile niche players. Strategic archetypes include large-scale producers leveraging existing distribution, premium ingredient innovators targeting specific consumer segments, and regional specialists adapting to local tastes. Companies pursue competitive moves such as portfolio diversification and strategic partnerships to expand market reach and secure supply chains.
Within the diversified conglomerate archetype, Danone, a multinational food corporation, occupies a significant position across various dairy alternative categories through its Alpro brand. Califia Farms, known for its distinct branding and focus on premium ingredients, represents an innovator targeting specific consumer segments with unique formulations and bottle designs. Oatly, a pure-play specialist in the oat milk segment, anchors the category-specific growth, leveraging its strong brand identity and first-mover advantage in key markets, particularly within the café channel.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| Califia Farms |
| Danone |
| Alpro |
| Ripple Foods |
| Blue Diamond Growers |
| SunOpta |
| Vitasoy International Holdings |
| Oatly |
| Others |
Cost & Logistics Intelligence
Cafes and restaurants, as concentrated buyer archetypes, drive demand for specialized plant-based milk formulations, influencing pricing for high-performance ingredients. This concentration allows for long-term contract negotiations, but also exposes manufacturers to specific channel demands.
Pricing Analysis
Premium pricing for specialized, barista-friendly formulations reflects the enhanced R&D and quality control required for stable emulsions. The pricing model often involves contract-based long-term offtake agreements for bulk ingredients, with transactional pricing for packaged retail products. Brand premium and geographic delivery costs are significant differentiation drivers. Pricing softness reflects input cost volatility for raw materials like oats and almonds. Households, driven by broad accessibility, exhibit higher price sensitivity compared to cafes prioritizing functional performance.
Supply Chain Analysis
Online retail channels are gaining share, influencing logistics and inventory management for plant-based milk products. The supply chain draws from agricultural regions globally for raw materials, with significant concentration in oat cultivation areas for example. Raw material dependencies include oats, almonds, and specialized protein isolates. Commodity price volatility for these agricultural inputs creates a structural risk for manufacturers. Distribution runs through a hybrid model combining traditional supermarkets with rapidly expanding online and health food store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant-based milk market is in a technology-transition phase, with high-pressure processing (HPP) replacing traditional ultra-high temperature (UHT) treatment for premium offerings.
For Market Incumbents: Deepen proprietary crop sourcing for key ingredients like oats and almonds to mitigate input cost volatility. Invest in advanced formulation science to maintain texture and stability, addressing a core R&D challenge. This defends against emerging private label threats and secures margin position. Expand production capacity in concentrated urban demand centers to serve the rapidly growing café channel.
For New Entrants and Emerging Players: New U.S. FDA labeling guidance, permitting dairy terms with nutrient comparisons, opens a window for innovative marketing. Target underpenetrated geographic markets in Latin America and Southeast Asia, focusing on local flavor preferences. A direct-to-consumer (DTC) logistics model, leveraging e-commerce infrastructure, provides a viable go-to-market angle for niche blends. Focus on hybrid blends combining different plant bases for superior nutritional profiles.
For Investors and Strategic Acquirers: The window for entry favors agile specialists with strong brand identities and proprietary formulation expertise. Long-term viability hinges on companies that can scale specialized ingredient sourcing while navigating evolving regulatory landscapes. The signal to watch is the successful commercialization of novel plant bases beyond oat and almond, indicating diversification potential. Seek companies with established distribution networks in high-growth urban centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Crop Sourcing | Secures raw material supply and mitigates input price volatility for manufacturers. |
| High-Pressure Processing (HPP) Adoption | Extends shelf life and preserves nutritional value, meeting consumer demand for less-processed products. |
| Geographic Expansion into Latin America | Unlocks significant growth potential by accessing new consumer bases and increasing market penetration. |
| Direct-to-Consumer (DTC) Channel Development | Bypasses traditional retail dominance, allowing for stronger brand control and customer relationships. |
| Functional Fortification of Products | Creates value-added offerings that target specific wellness needs beyond basic nutritional content. |
Research Approach
Independent corroboration across industry reports, trade association data, and regulatory filings underwrites the qualitative findings and quantitative projections. The analysis combines primary interviews with R&D leads, procurement managers, brand managers, and café owners. Secondary validation draws from government food safety agencies like the U.S. FDA and EFSA, alongside customs data and company financial reports. Bottom-up and top-down triangulation ensures data consistency across all market segments.
Historical consumption trends anchored the forecast window, providing a robust baseline for future projections across the modeling period. The analytical framework integrated segmentation dimensions including product type, end-user, distribution channel, and packaging type. Compound annual growth rates were derived from a multi-factor analysis considering consumer preferences and economic indicators. Regulatory changes in key markets, like the U.S. and EU, served as critical forecast inputs.
Caveats apply where raw material price volatility or unforeseen climate events could materially shift the outlook. Forecasts reflect assumptions regarding consumer demand stability and ongoing innovation in formulation science. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Plant-Based Nuggets Market