
 Canada Plant Protein Market | 2026-2036
Canada Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Plant Protein Market Outlook
Buyer concentration among Canadian food manufacturers is restructuring procurement patterns for plant protein inputs. Cargill Limited leverages its Prairie grain handling network to secure pea protein supply chains. Maple Leaf Foods Inc. anchors its plant-based portfolio through dedicated protein extraction investments. Burcon NutraScience Corporation differentiates via novel extraction technologies for canola and pea protein isolates.
Canada plant protein encompasses protein isolates, concentrates, and textured fractions derived from legumes, oilseeds, and cereal grains, typically containing 50-90% protein by dry weight depending on processing intensity, and functions as a functional ingredient for emulsification, gelation, and nutritional fortification in formulated foods. Pea protein dominates current volume flows due to favorable allergen profiles and established Prairie processing infrastructure. Soy protein maintains mature positions in nutraceutical applications where cost-performance ratios favor established supply chains. Hemp protein occupies emerging niches in specialty dietary supplements aligned with clean-label positioning.
Health Canada governs novel food ingredient approvals through pre-market notification requirements, while the Canadian Food Inspection Agency enforces labeling standards for protein content claims and allergen declarations. Protein Industries Canada, a federal innovation supercluster, accelerates domestic processing capacity through co-investment mechanisms. Stakeholders must monitor evolving front-of-package labeling regulations and carbon intensity benchmarking for export competitiveness into European and Asian markets.
Market Dynamics
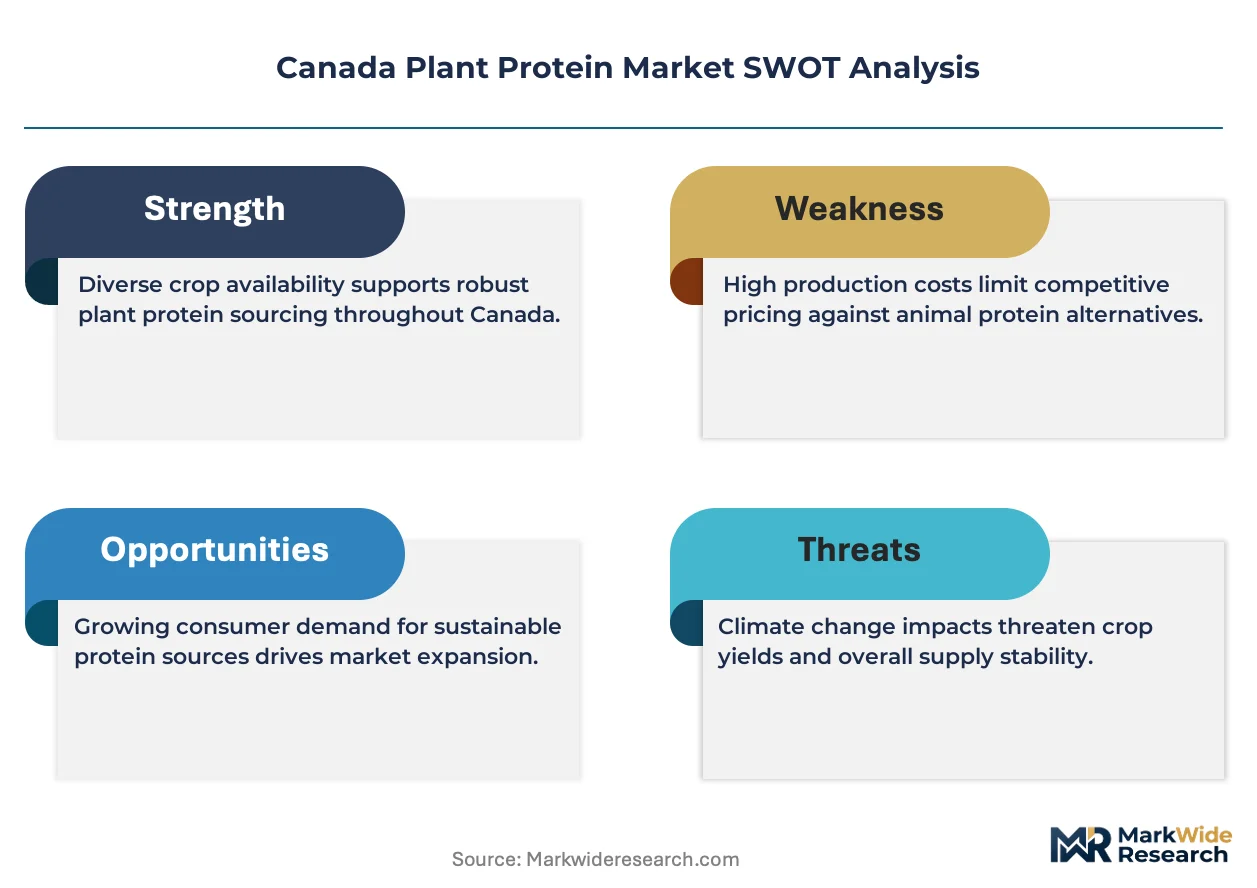
Health Canada's novel food pre-market notification requirements are compressing ingredient approval timelines while Prairie pea protein processing capacity concentrates around Cargill Limited and Roquette Canada Limited facilities, creating procurement bottlenecks for mid-tier food manufacturers.
Growth Catalysts
- Protein Industries Canada supercluster:Federal co-investment mechanisms accelerate domestic extraction facility buildouts, reducing reliance on imported isolates for meat alternative formulations.
- Prairie pulse crop expansion:Saskatchewan and Manitoba farmers are increasing pea and lentil acreage, tightening feedstock proximity to processing infrastructure near Portage la Prairie.
- Clean-label positioning:Canadian food manufacturers are reformulating with single-source protein declarations to meet retailer front-of-package guidelines.
Market Restraints
- Input cost volatility:Yellow pea prices fluctuate with Prairie drought cycles and rail logistics constraints to Vancouver export terminals.
- Supply concentration risk:Over 70% of Canadian pea protein isolate capacity sits within 200 kilometers of Winnipeg, creating geographic vulnerability to weather and labor disruptions.
- Regulatory friction:Health Canada's novel food determinations for emerging oilseed proteins delay product launches by 18-24 months versus U.S. GRAS self-affirmation pathways.
Strategic Opportunities
- Alberta canola protein commercialization:Burcon NutraScience Corporation's Meritage and Puratein extraction patents unlock high-value isolates from existing crush facilities in Lethbridge and Lloydminster.
- Pet food protein fortification:Premium companion animal brands in Ontario are adopting pulse concentrates for allergen-controlled formulations.
- Carbon intensity benchmarking:European Union deforestation-free supply chain regulations favor Canadian Prairie-sourced proteins over South American soy for export positioning.
Industry Challenges
- Food protein technologist scarcity:Specialized expertise in extrusion texturization and isolate functionalization concentrates in Guelph and Saskatoon research corridors, constraining scale-up timelines.
- Capex intensity for fractionation:Wet-milling protein isolate facilities require CAD 150-300 million per installation, limiting entrants to agribusiness conglomerates with balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Plant Protein Market |
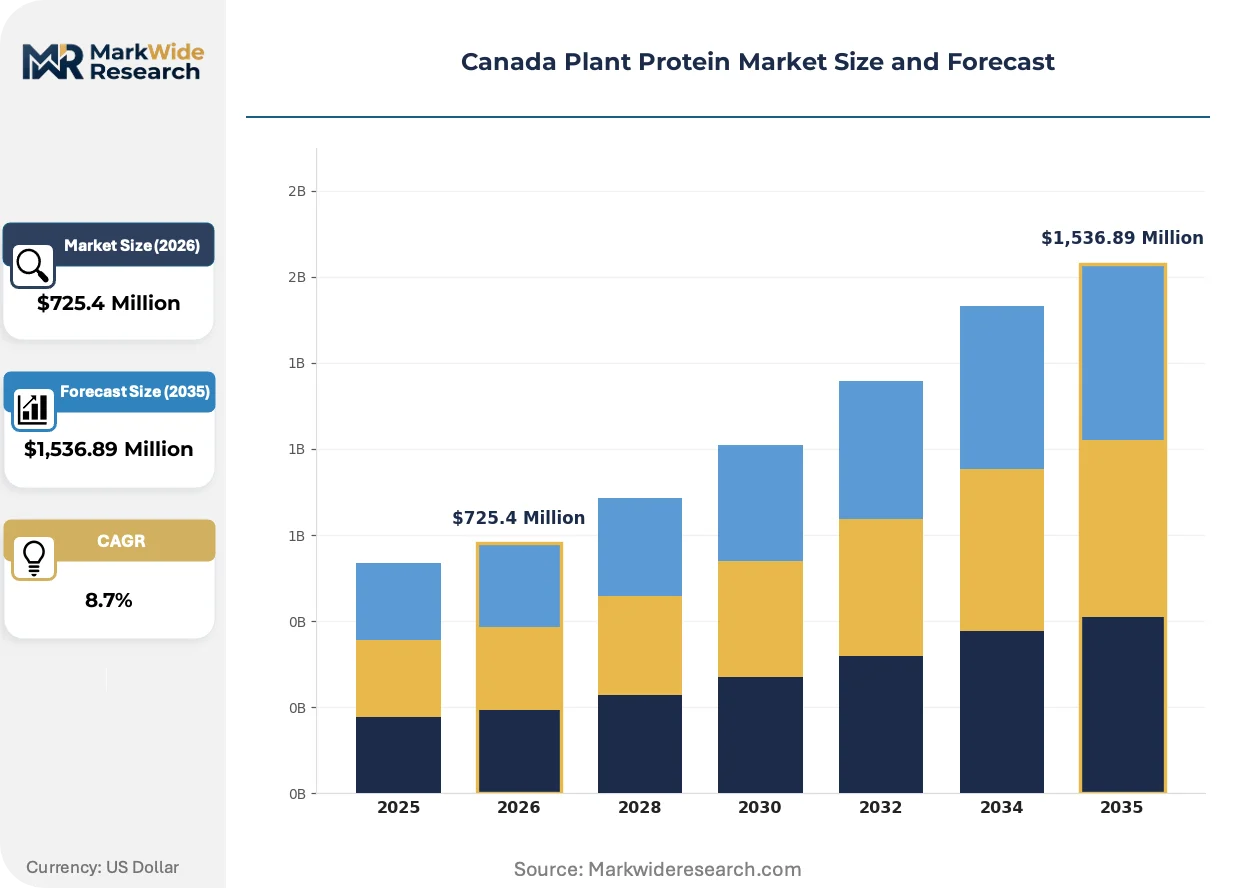
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,536.89 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein End User: Food Manufacturers, Nutraceuticals, Dietary Supplements, Animal Feed Application: Meat Alternatives, Protein Bars, Dairy Alternatives, Snacks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores |
| Companies Covered | Archer Daniels Midland Company, DuPont de Nemours Inc., Roquette Frères, CHS Inc., Burcon NutraScience Corporation, Cargill Limited, Maple Leaf Foods Inc., Roquette Canada Ltd., Protein Industries Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Plant Protein Market Strategic Shifts
Canadian plant protein processing is pivoting from commodity ingredient supply toward customized functional systems for specific food matrices, with extraction technology and regulatory science becoming primary competitive differentiators.
Membrane filtration and aqueous extraction technologies are decentralizing protein isolate production from centralized wet-milling complexes toward smaller-scale regional facilities. Mid-sized food manufacturers in Ontario and Quebec are adopting these modular systems to secure captive supply chains. This diffusion is compressing minimum efficient scale thresholds and enabling vertical integration by brands previously dependent on toll processors.
Health Canada's 2023 updated guidance on plant-based protein nutrient content claims tightens amino acid scoring pattern requirements for products marketed as protein sources. Reformulation costs for existing SKUs are diverting R&D budgets from innovation pipelines. Sports nutrition and adult nutrition segments are responding by commissioning third-party protein quality certifications to preempt enforcement actions.
Long-term supply agreements with fixed volume commitments are displacing spot market purchasing for pea protein concentrates among Toronto-area meat alternative manufacturers. This contractual shift locks in processor capacity and transfers price risk to ingredient suppliers. The pattern is most visible in Ontario's food processing corridor, where Maple Leaf Foods Inc. and smaller co-manufacturers are securing multi-year offtake deals.
Canada Plant Protein Market Segmentation
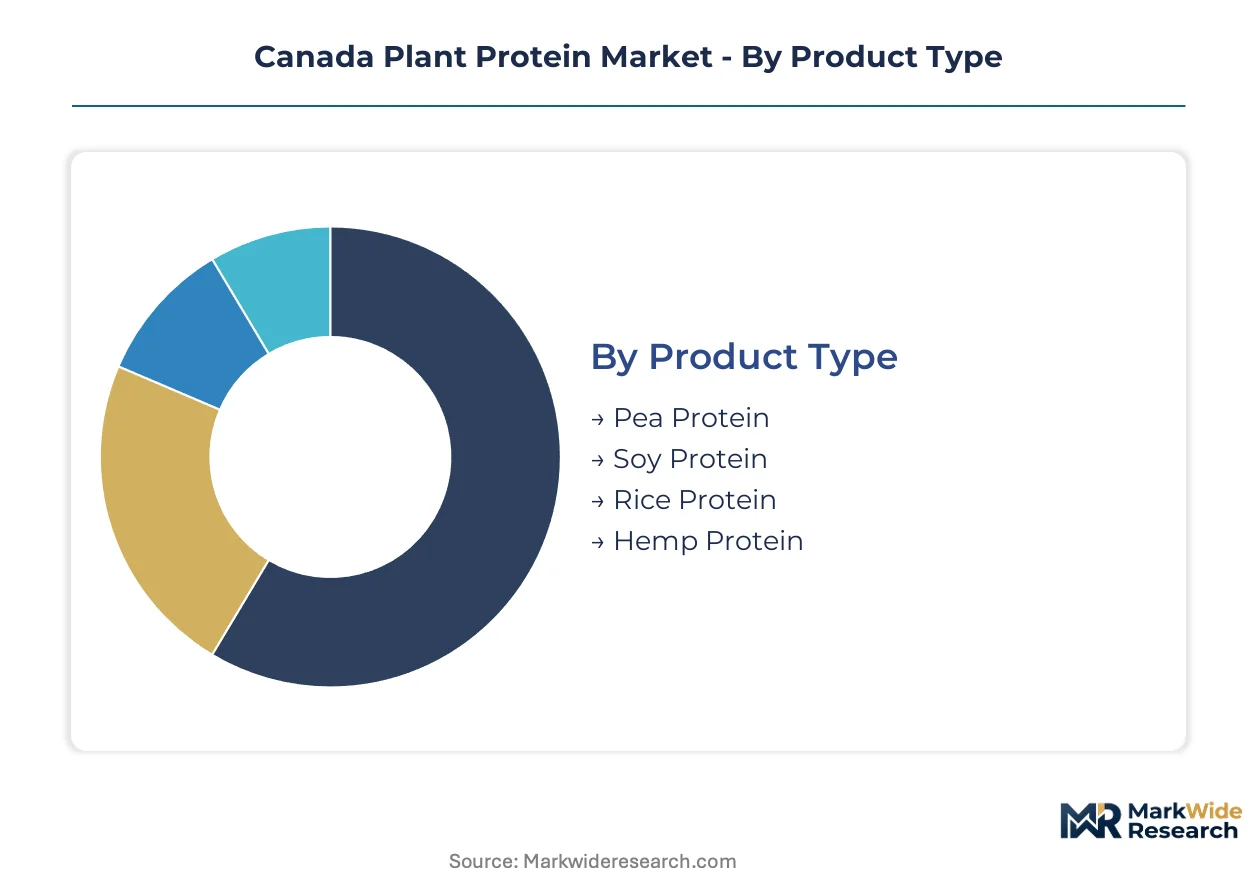
Segmentation in the Canada plant protein market reveals how procurement priorities diverge across buyer types and application requirements. Understanding these divisions exposes where pricing power concentrates and where formulation flexibility creates competitive advantage.
Product Type:
Buyers select protein sources based on allergen profiles, functional performance, and Prairie supply proximity rather than price alone.
- Pea Protein:Isolates and concentrates derived from yellow peas contain 80-90% protein with favorable emulsification properties for meat alternatives. Demand concentrates among Toronto-area food manufacturers seeking Health Canada-compliant clean-label formulations with established supply chains through Portage la Prairie processing clusters.
- Soy Protein:Mature isolate and concentrate formats deliver complete amino acid profiles at lower cost points than pulse alternatives. Nutraceutical buyers in Ontario prioritize soy for protein quality certifications and established GRAS-equivalent regulatory pathways under Health Canada guidelines.
- Rice Protein:Hypoallergenic concentrate fractions appeal to specialty dietary supplement brands targeting elimination diets.
- Hemp Protein:Whole-seed concentrates with omega fatty acid retention serve premium positioning in British Columbia natural products channels.
Pea protein leads on scale; hemp protein leads on momentum.
End User:
Volume commitments and technical specifications vary sharply across buyer sophistication tiers.
- Food Manufacturers:Large-scale meat alternative and dairy alternative producers require functional protein systems with guaranteed amino acid scores and extrusion texturization compatibility. Multi-year offtake agreements with Prairie processors dominate procurement patterns among Maple Leaf Foods Inc. and Ontario co-manufacturers seeking supply security.
- Nutraceuticals:Capsule and tablet formulators demand high-purity isolates with documented bioavailability and low heavy metal specifications. Regulatory documentation burdens from Health Canada's Natural Health Products Directorate shape supplier qualification timelines.
- Dietary Supplements:Powder format brands prioritize solubility and flavor masking over protein concentration percentages.
- Animal Feed:Pet food manufacturers in Ontario adopt pulse concentrates for allergen-controlled premium companion animal formulations.
Food manufacturers command volume; nutraceuticals command margin.
Application:
Formulation complexity and regulatory scrutiny intensity differ markedly across finished product categories.
- Meat Alternatives:Extruded texturized proteins require specific water-holding capacity and fibrous structure development through high-moisture extrusion. Protein Industries Canada supercluster investments target this segment with dedicated fractionation capacity near Winnipeg processing corridors.
- Dairy Alternatives:Barista-grade pea protein isolates must deliver foam stability and neutral flavor profiles for oat and almond milk blending applications.
- Protein Bars:Cold-pressed formats tolerate lower protein solubility but require binding properties and shelf-life stability.
- Snacks:Puffed and baked applications prioritize expansion volume and crunch retention over protein density.
Meat alternatives absorb capex; dairy alternatives expand most quickly.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and inventory velocity needs.
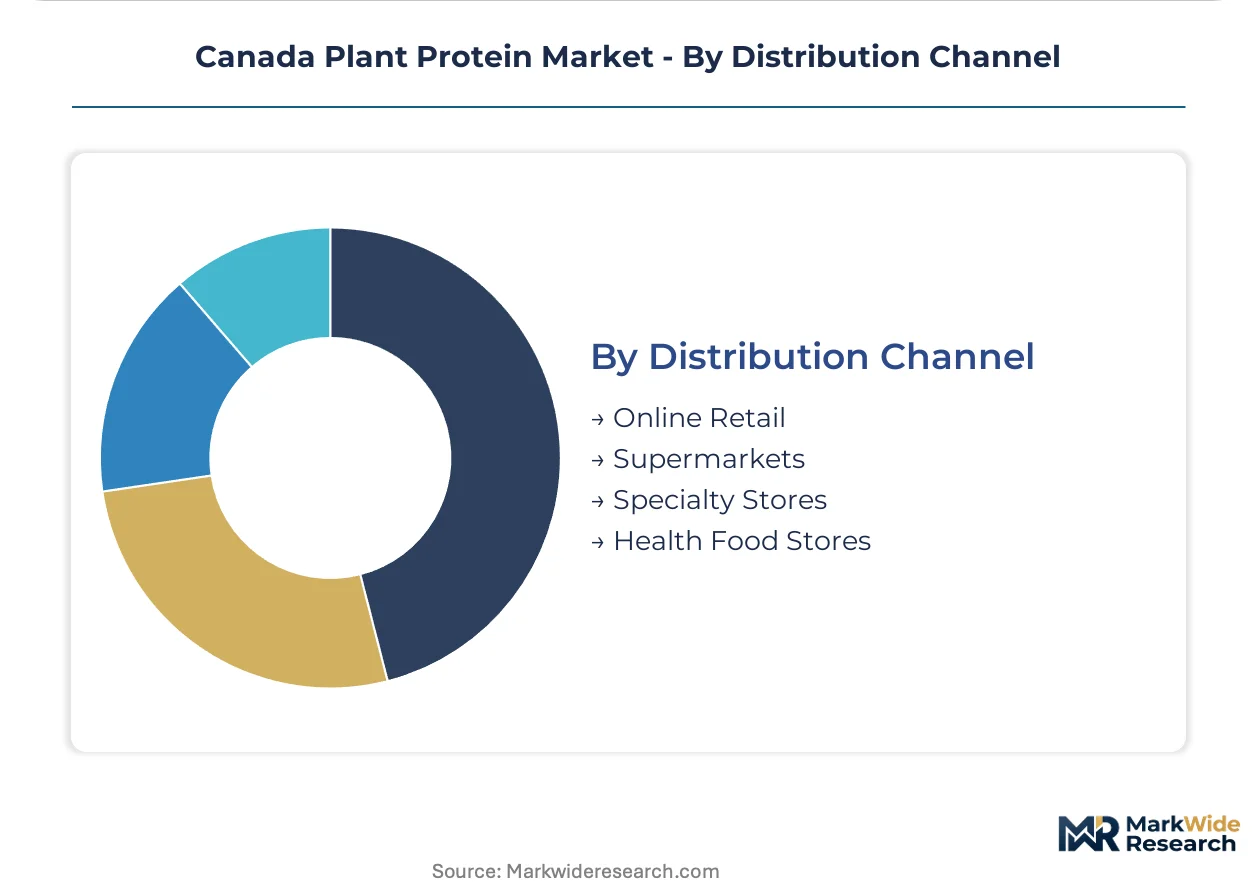
- Supermarkets:Loblaws, Sobeys, and Metro chains dominate volume flows for branded plant-based finished goods, with protein ingredient sourcing decisions made at headquarters level in Toronto and Montreal. Listing fees and promotional compliance requirements favor suppliers with national distribution infrastructure.
- Online Retail:Direct-to-consumer protein powder brands leverage Amazon.ca and Shopify-powered storefronts for niche positioning and subscription revenue models.
- Specialty Stores:Independent natural retailers in Vancouver and Toronto stock premium single-source proteins with transparent supply chain documentation.
- Health Food Stores:Chains like Popeyes Supplements and GNC Canada focus on sports nutrition applications with third-party certification requirements.
Supermarkets consolidate volume; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's plant protein infrastructure outpaces Australia's commercial scale but trails the United States in extraction technology depth. Provincial specialization creates distinct supply chain geographies across the country.
Ontario
Meat alternative manufacturers in the Toronto-Waterloo corridor drive concentrated demand for pea protein isolates with specific extrusion compatibility. Health Canada's front-of-package labeling regulations tighten amino acid scoring requirements for products distributed through Loblaws and Sobeys headquarters in Mississauga. Guelph anchors food protein research clusters where the University of Guelph trains scarce extrusion technologists.
Quebec
Dairy alternative formulators in Montreal prioritize barista-grade foam stability specifications for oat-pea blended beverages. The Canadian Food Inspection Agency enforces bilingual labeling standards that extend packaging compliance timelines for protein ingredient suppliers. Roquette Canada Ltd. operates fractionation capacity near Portage la Prairie with rail connectivity to Montreal processing plants.
Alberta
Canola crush facilities in Lethbridge and Lloydminster pivot toward protein isolate extraction from existing oilseed processing streams. Protein Industries Canada supercluster co-investment mechanisms fund Burcon NutraScience Corporation's Meritage and Puratein patent commercialization. Edmonton research corridors develop aqueous extraction technologies for decentralized regional processing.
Saskatchewan
Pulse crop acreage expansion around Regina and Saskatoon tightens feedstock proximity to Prairie processing infrastructure. Prairie drought cycles and CN Rail logistics constraints to Vancouver terminals create yellow pea price volatility for ingredient buyers. Saskatoon hosts Agriculture and Agri-Food Canada research stations advancing pea breeding for protein content optimization.
British Columbia
Premium natural products channels in Vancouver stock hemp protein concentrates with omega fatty acid retention for clean-label positioning. The province's carbon intensity benchmarking aligns with European Union deforestation-free supply chain regulations favoring Canadian Prairie-sourced proteins. Victoria specialty retailers demand transparent supply chain documentation for single-source protein declarations.
Canada Plant Protein Market Competitive Environment
Prairie-based processors anchor one tier; multinational ingredient specialists hold formulation technology advantages. Market structure concentrates around wet-milling facilities requiring CAD 150-300 million capital deployment, limiting viable entrants to agribusiness conglomerates with balance sheet capacity. Three archetypes dominate: Prairie grain handlers with captive supply chains, extraction technology licensors, and integrated food manufacturers with captive protein demand. Competitive moves center on multi-year offtake agreements locking processor capacity and technology licensing for novel oilseed protein isolates.
Among multinational ingredient suppliers, Archer Daniels Midland Company and DuPont de Nemours Inc. occupy positions as scale-driven archetypes with established regulatory pathways. Within the Canadian specialist tier, Burcon NutraScience Corporation exemplifies technology-centric positioning through patented extraction methods, while Cargill Limited represents integrated supply chain control from Prairie grain handling through isolate production. Maple Leaf Foods Inc. anchors the food manufacturer archetype with dedicated protein extraction investments supporting plant-based portfolio expansion.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| DuPont de Nemours Inc. |
| Roquette Frères |
| CHS Inc. |
| Burcon NutraScience Corporation |
| Cargill Limited |
| Maple Leaf Foods Inc. |
| Roquette Canada Ltd. |
| Protein Industries Canada |
| Others |
Value Chain & Pricing Dynamics
Agribusiness conglomerates with sovereign wealth and pension fund backing anchor Canadian plant protein capacity, tightening supply discipline through multi-year offtake structures that transfer price risk to ingredient buyers while locking Prairie processor output.
Pricing Analysis
Capacity additions in Manitoba and Saskatchewan are reshaping price floors for pea protein isolates as Roquette Canada Ltd. and Cargill Limited expand fractionation facilities near Winnipeg. Contract-based long-term offtake agreements now dominate procurement, with pricing stratifying across premium certified-organic tiers, standard food-grade isolates, and economy-positioned feed-grade concentrates. Cost compression in standard-tier isolates is intensifying because Protein Industries Canada supercluster co-investment mechanisms subsidize competitor buildouts. Mid-tier meat alternative manufacturers in Ontario exhibit highest price sensitivity, while nutraceutical buyers prioritize low-heavy-metal certification over unit cost.
Supply Chain Analysis
Reverse-logistics flows for spent processing water and protein-rich byproducts feed into Ontario pet food manufacturers and Alberta animal feed compounders, closing loop inefficiencies. Geographic supply concentrates in Canada, with secondary dependencies on U.S. organic yellow pea imports and European membrane filtration equipment. Raw material flows draw from Saskatchewan pulse acreage, Manitoba rail terminals, and Portage la Prairie processing clusters. Single-source vulnerability pervades the Winnipeg-centered isolate corridor, where over 70 percent of capacity sits within 200 kilometers. Distribution runs through Prairie rail networks to Toronto-Waterloo food manufacturers and Vancouver natural products channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada plant protein functions as a geographic-arbitrage play against U.S. and European supply, exploiting Health Canada's novel food pathway cost differentials and Prairie feedstock proximity that compresses landed costs for Asian export markets.
For Market Incumbents: Anticipate margin compression from membrane filtration technology diffusion enabling smaller-scale regional competitors to bypass traditional wet-milling scale requirements. Defend position by deepening backward integration into Saskatchewan pulse breeding programs and securing exclusive rail siding access at Portage la Prairie. Certification investment in carbon intensity benchmarking represents the critical lever for European market access under deforestation-free regulations. For New Entrants and Emerging Players: Boutique extrusion service providers in Ontario's food processing corridor offer the most penetrable entry point, co-manufacturing for brands lacking in-house texturization capacity. Target Alberta canola protein commercialization, where Burcon NutraScience Corporation patent licensing creates technology access without captive extraction investment. A go-to-market angle centered on aqueous extraction modular systems for mid-sized Quebec dairy alternative formulators bypasses incumbent scale advantages. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Prairie toll processors without captive brand offtake or proprietary extraction patents. Long-term viability over a 5-10 year window hinges on regulatory arbitrage durability as Health Canada tightens novel food timelines. Acquisition targets should exhibit backward integration into organic pulse acreage or exclusive channel relationships with Toronto-area meat alternative manufacturers. Monitor European Union deforestation-free enforcement actions as the signal for Canadian export premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Breeding | Saskatchewan Agriculture and Agri-Food Canada research partnerships secure proprietary high-protein germplasm for isolate yield optimization. |
| Membrane Filtration Technology Licensing | Edmonton aqueous extraction patents enable decentralized regional processing without CAD 150-300 million wet-milling capital deployment. |
| Carbon Intensity Certification Program | European Union deforestation-free regulations favor Prairie-sourced proteins with documented supply chain traceability and low-carbon production. |
| Long-term Supply Agreement with Food Manufacturers | Maple Leaf Foods Inc. and Ontario co-manufacturers lock processor capacity through multi-year offtake deals transferring price risk to suppliers. |
| Joint Venture with Pet Food Brands | Ontario premium companion animal manufacturers adopt pulse concentrates for allergen-controlled formulations with guaranteed amino acid scores. |
Study Parameters
Bottom-up food manufacturer demand modeling reconciled against top-down Prairie processing capacity tracking forms the analytical core of this study. Primary interviews with protein extraction technologists, procurement leads at Toronto-area meat alternative manufacturers, regulatory affairs specialists at Health Canada, and grain handling operations managers at Cargill Limited facilities informed demand-side assumptions. Secondary validation drew from Canadian Food Inspection Agency labeling guidance, Protein Industries Canada supercluster investment disclosures, Agriculture and Agri-Food Canada crop production statistics, and SEC filings of multinational ingredient suppliers.
Historical trendline analysis of Prairie pulse acreage, processing capacity utilization, and meat alternative SKU launches established baseline growth patterns across the projection horizon. The forecast framework segments by protein source type, end-user sophistication tier, application functional requirements, and provincial regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating Health Canada novel food approval velocity and European carbon border adjustment mechanism implementation timelines. Industry-specific inputs include extrusion texturization equipment installation rates and membrane filtration technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Prairie drought frequency, CN Rail logistics disruptions, and Health Canada front-of-package labeling enforcement intensity. Practitioners should monitor European Union deforestation-free supply chain regulation implementation, Protein Industries Canada supercluster funding renewal decisions, and Toronto-Waterloo food manufacturer capital expenditure announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Plant-Based Bacon Market